
 Italy Alcohol E-Commerce Market | 2026-2036
Italy Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Alcohol E-Commerce Market Insights
Multi-source inventory aggregation is shifting how Italian alcohol e-commerce platforms secure their supply chains. Tannico leverages direct winery partnerships across Piedmont and Tuscany to sustain exclusive access to small-batch labels. Callmewine anchors its competitive position through temperature-controlled warehousing that protects wine integrity during summer fulfillment peaks.
Italy Alcohol E-Commerce denotes the digital retailing of alcoholic beverages through web-based platforms, requiring compliance with cold-chain logistics specifications for wine storage between 12-16°C and real-time age-verification protocols at delivery. The primary commercial purpose centers on connecting producers with consumers while navigating Italy's strict alcohol distribution laws. Wine dominates transaction volume within product type segmentation, though ready-to-drink formats are expanding fastest among younger demographics seeking convenience. Subscription services within the sales channel dimension capture the highest customer lifetime value, while third-party retailers absorb margin compression from platform commission structures.
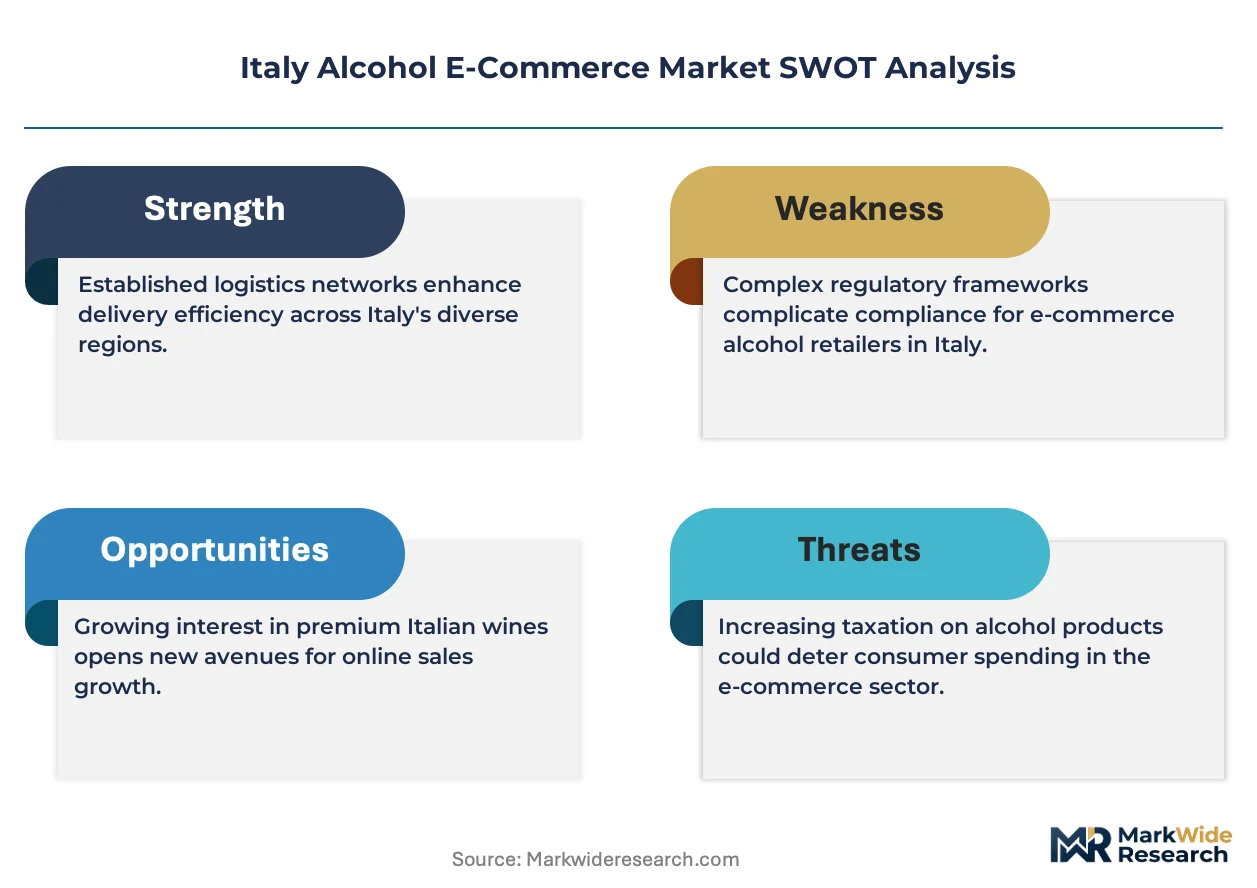
Italy's alcohol e-commerce sector operates under overlapping oversight from the Ministry of Health's age-verification mandates, AGCM consumer protection standards, and EU-wide GDPR requirements for customer data handling in subscription models. These frameworks elevate compliance costs for cross-border shipments but simultaneously protect domestic platforms from unregulated foreign competition. Stakeholders must monitor pending revisions to Italy's alcohol advertising codes that could restrict retargeting algorithms and reshape customer acquisition economics.
Market Dynamics
EU Green Deal packaging waste directives are forcing Italian alcohol e-commerce platforms to redesign cold-chain logistics infrastructure, compressing margins while accelerating consolidation among temperature-controlled fulfillment providers.
Growth Catalysts
- Mobile-first purchasing habits:Young urban professionals in Milan and Rome now complete over half of wine transactions via smartphone apps, driving platform investment in one-tap reordering interfaces.
- AGCM consumer protection standards:Strict enforcement of transparent pricing and delivery guarantees has elevated trust metrics, reducing cart abandonment rates for premium subscription services.
- Small-batch Piedmont labels:Direct winery partnerships bypass traditional distribution tiers, granting platforms exclusive access to limited-production Barolo and Barbaresco allocations.
Market Restraints
- GDPR compliance costs:Subscription models handling biometric age-verification data face elevated legal and technical expenditures that foreign competitors often circumvent.
- Summer cold-chain volatility:Temperature excursions during July-August fulfillment peaks degrade wine integrity, forcing platforms to maintain redundant refrigerated warehousing.
- Input cost concentration:Specialized insulated packaging suppliers cluster in northern Italy, creating bottleneck risk during demand surges.
Strategic Opportunities
- Sicily and Puglia penetration:Same-day delivery infrastructure remains underdeveloped in southern regions, offering first-mover advantages for platforms establishing localized hubs.
- EU AI Act alignment:Automated age-verification systems that meet emerging algorithmic transparency standards will qualify for streamlined cross-border operating licenses.
- Ready-to-drink formats:Convenience-seeking demographics in Turin and Bologna demonstrate unmet demand for pre-mixed aperitif cocktails in single-serve packaging.
Industry Challenges
- Cold-chain engineering talent scarcity:Platforms struggle to recruit specialists capable of optimizing 12-16°C warehouse zones during heat waves.
- Legacy POS integration friction:Independent enotecas migrating online face technical barriers connecting inventory systems to marketplace APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Alcohol E-Commerce Market |
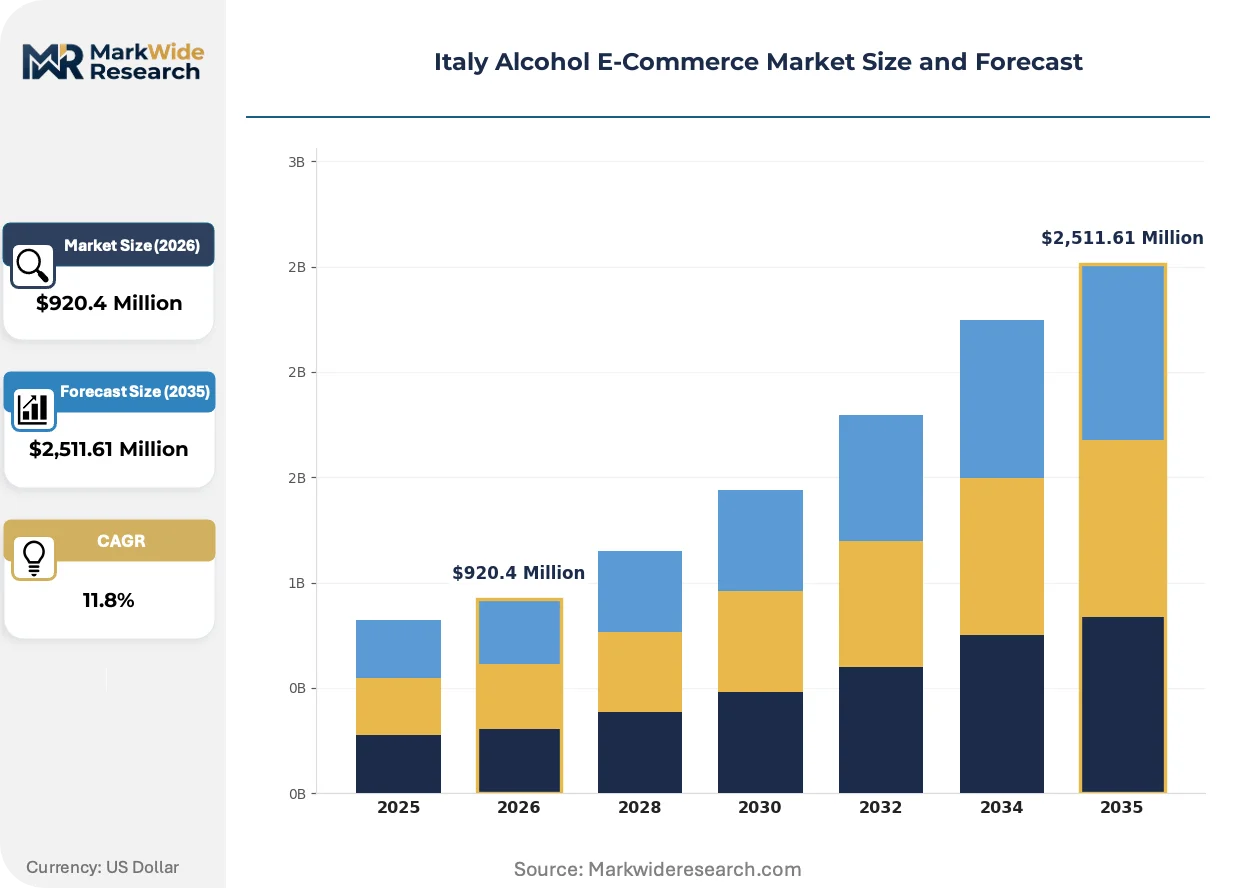
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $2,511.61 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine, Beer, Spirits, Ready-to-Drink Customer Type: Sole Buyers, Households, Event Planners, Bars Sales Channel: Online Platforms, Direct-to-Consumer, Third-Party Retailers, Subscription Services Payment Method: Credit Card, Digital Wallet, Bank Transfer, Cash on Delivery |
| Companies Covered | Tannico, Vinitaly WineClub, Callmewine, Enoteca Online, Italian Wine Central, Bibendum, Winelivery, Glasgow Wine, Evaluna, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Alcohol E-Commerce Market Trends and Innovations
Italian alcohol e-commerce is experiencing fundamental restructuring as regulatory pressure, logistics technology, and generational purchasing habits converge to reshape platform economics and customer relationships.
Blockchain-enabled provenance tracking is modularizing how high-value wine authentication operates. Collectors and investment buyers in Florence and Verona now demand immutable vineyard-to-cellar records. This compression of trust verification into distributed ledger systems is displacing traditional paper-based certification and reducing dispute resolution costs.
EU Green Deal packaging waste directives are mandating reusable insulated container programs across member states. Italian platforms must redesign reverse logistics networks to recover and sanitize thermal packaging. Wine subscription services absorb the heaviest compliance burden, passing container deposit fees to subscribers while lobbying for harmonized standards.
Subscription bundling now dominates customer acquisition strategy among Lombardy households. Single-bottle purchasers convert to curated monthly deliveries at accelerating rates, displacing impulse-driven cart behavior. Rome and Milan exhibit the highest concentration of multi-vinestry membership stacking, where consumers maintain parallel subscriptions to access exclusive allocations.
Italy Alcohol E-Commerce Market Segmentation
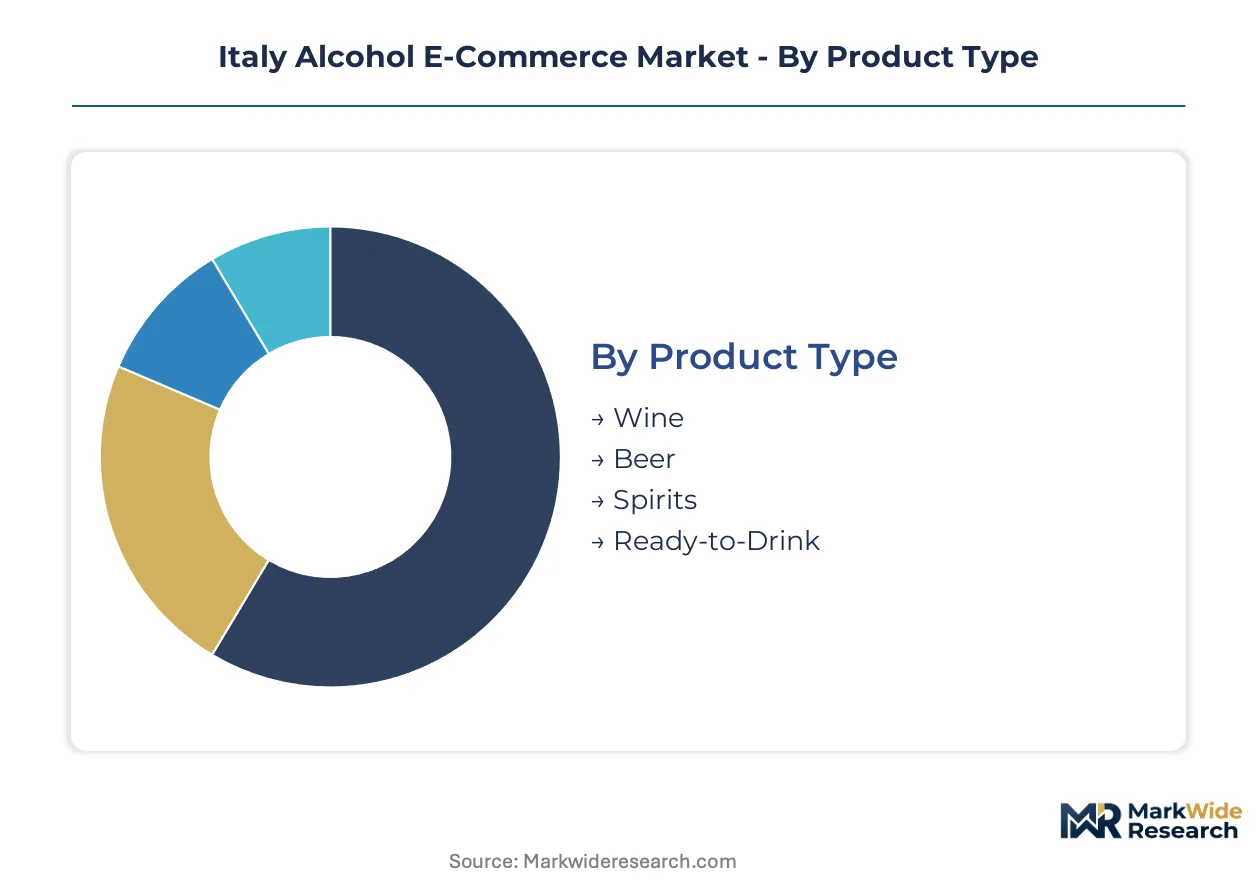
Segmentation in Italy's alcohol e-commerce market reveals how distinct buyer behaviors and fulfillment requirements fragment platform economics. Each dimension carries unique regulatory burdens and margin profiles that reshape competitive strategy.
Product Type:
Wine operates as the standalone anchor category with embedded cold-chain dependencies, while beer and spirits function as more flexible embedded purchases within broader basket builds.
- Wine:Temperature-sensitive inventory requiring 12-16°C storage protocols dominates transaction volume. Demand clusters in Lombardy and Tuscany where premium Barolo and Brunello allocations drive subscription loyalty. AGCM delivery guarantee enforcement elevates trust premiums for temperature-verified shipments.
- Ready-to-Drink:Pre-mixed cocktails and single-serve aperitifs target convenience-seeking urban professionals in Milan and Rome. Mobile-first purchasing patterns and summer heat-wave fulfillment windows create distinct logistics requirements separate from traditional wine cold-chain infrastructure.
- Beer:Standard ambient storage requirements enable broader distribution reach with lower per-unit fulfillment costs.
- Spirits:Higher ABV content triggers stricter age-verification protocols and AGCM disclosure requirements for limited-edition releases.
Volume placements concentrate in Wine; the faster expansion belongs to Ready-to-Drink.
Customer Type:
Cost tier differentiation separates high-frequency low-margin household replenishment from episodic high-value event procurement.
- Households:Recurring subscription purchasers in Rome and Milan generate the highest customer lifetime value through multi-vinestry membership stacking. GDPR-compliant biometric age-verification data management elevates retention infrastructure costs.
- Event Planners:Bulk procurement of allocated vintages for weddings and corporate functions concentrates in Florence and Verona. Blockchain-enabled provenance documentation commands price premiums for authentication-sensitive buyers.
- Sole Buyers:Individual collectors seeking single-bottle investment-grade acquisitions.
- Bars:Licensed hospitality operators sourcing replenishment inventory through B2B platform interfaces.
Margin concentration sits with Event Planners; the steepest volume climb tracks Households.
Sales Channel:
Channel selection determines margin compression exposure versus customer data ownership trade-offs.
- Subscription Services:Curated monthly deliveries capture recurring revenue with prepaid cash flow advantages. EU Green Deal packaging return obligations impose reverse logistics costs that platforms pass through as container deposits.
- Direct-to-Consumer:Winery-owned platforms bypass third-party commission structures while absorbing full GDPR compliance and cold-chain capital expenditure burdens.
- Online Platforms:Aggregator marketplaces connecting fragmented enoteca inventory to national demand.
- Third-Party Retailers:Traditional wine shops extending reach through marketplace APIs with legacy POS integration friction.
Revenue stability favors Subscription Services; the channel gaining share fastest is Direct-to-Consumer.
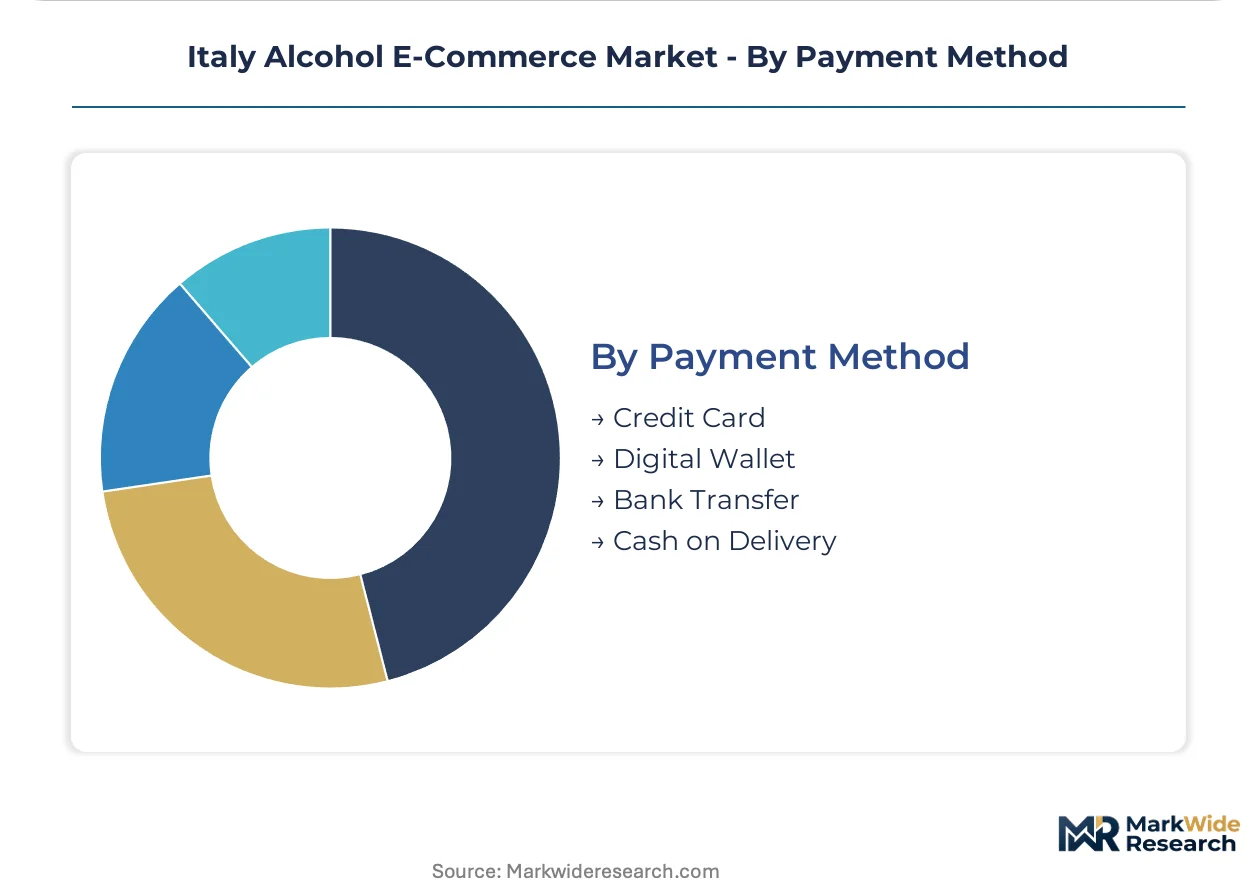
Payment Method:
Payment infrastructure maturity separates trusted digital natives from cash-preference holdouts in southern regions.
- Digital Wallet:Apple Pay and Google Pay integration enables one-tap reordering for mobile-first Milan professionals. AGCM transparent pricing mandates require real-time fee disclosure before transaction confirmation.
- Credit Card:Chargeback protection and installment financing options dominate high-value wine acquisitions.
- Bank Transfer:Preferred for B2B bar procurement and large-format event orders.
- Cash on Delivery:Persistent demand in Sicily and Puglia where digital banking penetration lags and age-verification handoff occurs at physical delivery.
Transaction velocity peaks with Digital Wallet; Cash on Delivery retains importance in underpenetrated southern hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piedmont's vineyard density and Tuscany's winery concentration anchor Italy's alcohol e-commerce supply base, with northern logistics corridors feeding southern demand expansion.
Lombardy
Milan's mobile-first professional cohort drives subscription service adoption, with same-day delivery infrastructure achieving deepest penetration here. AGCM consumer protection standards enforce transparent pricing disclosures that reduce cart abandonment. The city anchors Italy's highest concentration of multi-vinestry membership stacking.
Piedmont
Direct winery partnerships for Barolo and Barbaresco allocations concentrate procurement leverage among platforms operating here. EU Green Deal packaging waste directives force redesign of cold-chain logistics serving this temperature-sensitive inventory. The Langhe wine district supplies exclusive small-batch labels to national subscription services.
Lazio
Rome households generate the highest customer lifetime value through recurring curated deliveries. GDPR-compliant biometric age-verification infrastructure elevates platform retention costs. The capital's event planning sector concentrates demand for blockchain-enabled provenance documentation.
Tuscany
Brunello di Montalcino and Chianti Classico allocations drive premium subscription loyalty in this region. Summer cold-chain volatility during July-August fulfillment peaks forces redundant refrigerated warehousing investments. Florence and Siena anchor collector demand for investment-grade authentication systems.
Sicily
Underdeveloped same-day delivery infrastructure creates first-mover opportunities for platforms establishing localized hubs. Cash on delivery persists as a dominant payment method where digital banking penetration lags. Palermo and Catania represent untapped demand pools for mobile-first purchasing conversion.
Italy Alcohol E-Commerce Market Competitive Landscape
Direct winery partnership formation dominates the current landscape, with platforms racing to secure exclusive allocation agreements before competitors consolidate access. The vendor base clusters around three strategic archetypes: pure-play digital natives with proprietary logistics, established enotecas extending through marketplace APIs, and winery-owned direct-to-consumer channels. Tiered competitive positioning separates temperature-controlled infrastructure holders from ambient-storage generalists. M&A activity targets cold-chain engineering capabilities, while portfolio diversification into ready-to-drink formats captures convenience-seeking demographics.
Within the digital native tier, Tannico and Callmewine exemplify platform archetypes built around specialized fulfillment infrastructure, with the former leveraging Piedmont partnerships and the latter anchoring competitive position through temperature-controlled warehousing. Vinitaly WineClub occupies a position bridging trade show heritage with subscription service conversion. Enoteca Online and Winelivery represent marketplace-aggregator models connecting fragmented traditional retail inventory to national demand, sitting within the legacy-extension archetype facing POS integration friction.
| Leading Market Players |
|---|
| Tannico |
| Vinitaly WineClub |
| Callmewine |
| Enoteca Online |
| Italian Wine Central |
| Bibendum |
| Winelivery |
| Glasgow Wine |
| Evaluna |
| Others |
Pricing and Supply Chain Analysis
Captive warehousing networks in northern Italy anchor both supply security and pricing power for temperature-sensitive wine inventory. Platforms operating proprietary 12-16°C facilities bypass third-party logistics markups while commanding subscription premiums for delivery guarantee enforcement under AGCM standards.
Pricing Analysis
Temperature-verified delivery warranties separate bundled premium subscriptions from unbundled per-transaction purchases. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain certification grade and geographic delivery cost to Lombardy versus southern regions. Pricing pressure stems from EU Green Deal packaging return obligations forcing container deposit fees onto subscribers. Households in Milan exhibit lowest price sensitivity; cash-on-demand buyers in Sicily show highest.
Supply Chain Analysis
Specialized cold-chain engineering talent scarcity in Piedmont and Tuscany constrains warehouse expansion velocity. Inventory draws from concentrated Barolo and Brunello allocations in these northern regions, with ready-to-drink formats sourcing from broader European manufacturing. Single-source vulnerability sits with insulated packaging suppliers clustering around Milan. Distribution runs through subscription fulfillment hubs feeding same-day delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's alcohol e-commerce sector is transitioning from marketplace aggregation toward proprietary logistics technology, with blockchain-enabled provenance systems displacing paper-based authentication and reshaping customer trust economics.
For Market Incumbents: Lock in exclusive winery partnerships across Piedmont and Tuscany before competitor consolidation accelerates. Invest in redundant refrigerated warehousing to mitigate summer temperature excursion risks threatening AGCM delivery guarantee compliance. Prioritize GDPR-compliant biometric age-verification infrastructure as foreign platform entry barrier.
For New Entrants and Emerging Players: Southern regional distributors represent the most penetrable channel partner type for establishing Sicily and Puglia fulfillment hubs ahead of same-day delivery infrastructure buildout. Target cash-on-delivery demand pools in Palermo and Catania with mobile-first purchasing conversion. Pursue ready-to-drink format specialization to capture convenience-seeking demographics in Turin and Bologna.
For Investors and Strategic Acquirers: Exit pathways concentrate in cold-chain engineering capability acquisitions by larger platform aggregators seeking temperature-controlled infrastructure. Long-term viability favors vertically integrated models with direct winery relationships over marketplace-dependent enoteca extensions. Watch EU AI Act algorithmic transparency standard adoption as inflection indicator for automated age-verification system valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Winery Partnership Formation | Secures exclusive Barolo and Barbaresco allocations ahead of competitor consolidation in Piedmont. |
| Temperature-Controlled Warehousing Expansion | Enables AGCM-compliant delivery guarantees during July-August fulfillment peaks in Lombardy. |
| Blockchain Provenance System Deployment | Reduces authentication dispute costs for investment-grade collectors in Florence and Verona. |
| Reusable Packaging Program Implementation | Aligns reverse logistics with EU Green Deal directives while passing container deposits to subscribers. |
| Mobile-First Interface Investment | Captures young urban professional purchasing habits driving Milan and Rome transaction volume. |
Research Methodology
Independent corroboration across platform operations executives, cold-chain logistics directors, and winery partnership managers underwrites the qualitative findings. Primary interviews with AGCM compliance officers and subscription service heads combined with secondary validation from EU regulatory filings, Italian trade association reports, and customs shipment records. Bottom-up segmentation modeling triangulated against top-down market sizing from digital payment processor disclosures.
Comparable-period anchoring to historical subscription growth trajectories and mobile transaction penetration rates established the forecast window baseline. The analytical framework projects across product type, customer archetype, sales channel, and payment method dimensions throughout the forecast period. CAGRs derive from logistics capacity buildout curves and generational purchasing habit migration patterns, with cold-chain infrastructure investment cycles and EU packaging directive compliance timelines as key inputs.
Several conditions sit outside the modeled scope, including pending revisions to Italy's alcohol advertising codes and cross-border tariff harmonization outcomes. Forecasts reflect documented assumptions regarding biometric age-verification technology adoption rates and insulated packaging supplier capacity expansion. Material deviation in EU AI Act implementation timelines or summer heat wave severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Beer Line Cleaning Kit Market
Alcoholic Beverages
Oak Barrel Alternatives Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Alcohol Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Global Shortenings Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
Premium Wine Cooler Market