
 South America Fermented Drinks Market | 2026-2036
South America Fermented Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fermented Drinks Market Analytics
Brazilian dairy cooperatives and Andean grain distillers is hardening the supply base for traditional fermented beverages across the continent. Ambev leverages its bottling infrastructure to distribute chicha-derived products through retail chains in the Andean zone. Groupe Danone SA sustains its kefir portfolio through cold-chain partnerships with Brazilian supermarket networks. Heineken NV competes in the premium fermented segment by positioning craft-style ales in urban bars from Bogotá to Buenos Aires.
South America fermented drinks encompass beverages produced through controlled microbial fermentation of substrates including dairy, tea, maize, and agave, yielding ethanol, lactic acid, or carbonation as functional byproducts with shelf lives typically spanning 14 to 90 days under refrigeration. These products serve commercial purposes ranging from probiotic health positioning to ceremonial consumption and alcohol delivery. Kefir and kombucha occupy expanding margin pools in health stores and online retail channels where consumers pay premiums for live-culture claims. Chicha and pulque sustain deep-rooted demand in wholesale and direct-to-consumer channels tied to cultural consumption patterns across Peru and Mexico's southern reach.
ANVISA governs microbiological safety standards for fermented beverages in Brazil, while Peru's national health authority enforces traditional preparation protocols for chicha in commercial settings. Both frameworks elevate compliance costs for imported cultures and packaging materials, reshaping procurement toward local suppliers. Stakeholders must monitor evolving strain registration requirements and cold-chain enforcement intensity as regulatory divergence between Mercosur and Andean Community members complicates cross-border formulation strategies.
Market Dynamics
ANVISA's updated food labeling regulations for fermented products are tightening compliance requirements across Brazil, forcing producers to reconfigure supply chains toward local culture suppliers and certified packaging vendors.
Growth Catalysts
- Live-culture certification protocols:ANVISA's strain registration requirements for probiotic claims are elevating product credibility in Brazilian health stores. Retailers now demand documented colony-forming unit counts.
- Cold-chain partnerships:Brazilian supermarket networks are expanding refrigerated shelf space for kefir and kombucha. This infrastructure investment unlocks distribution for small-batch producers.
- Ceremonial consumption patterns:Chicha maintains wholesale demand across Peru's Andean communities. Direct-to-consumer channels tied to cultural festivals sustain volume outside commercial retail.
Market Restraints
- Import dependency for starter cultures:Brazilian producers rely on European and North American suppliers for specific probiotic strains. Currency volatility elevates working capital requirements.
- Refrigeration infrastructure gaps:Last-mile cold-chain coverage remains inconsistent in Brazil's northeastern states. Shelf-life compression limits geographic expansion for unpasteurized products.
- Traditional preparation protocols:Peru's national health authority mandates specific chicha production methods. Compliance costs exclude industrial-scale entrants from artisanal market segments.
Strategic Opportunities
- Argentina's underpenetrated probiotic segment:Health stores in Buenos Aires and Córdoba are expanding shelf space faster than supplier capacity. First-mover brands capture premium positioning.
- Agave fermentation convergence:Pulque production techniques transfer to commercial-scale operations in southern Mexico's reach. Equipment suppliers adapt traditional methods for controlled environments.
- Online retail channel innovation:Subscription models for live-culture beverages bypass refrigeration constraints through direct-to-consumer logistics. Temperature-controlled packaging investments unlock recurring revenue.
Industry Challenges
- Microbiologist talent scarcity:Strain isolation and culture maintenance require specialized laboratory skills. Brazilian universities produce fewer qualified technicians than expanding production capacity demands.
- Dual registration complexity:Mercosur and Andean Community regulatory divergence forces reformulation for cross-border sales. Compliance timelines extend product development cycles.
- Legacy dairy cooperative integration:Traditional kefir producers lack digital traceability systems. Upgrading to ANVISA-mandated batch-tracking requires capital investment many cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fermented Drinks Market |
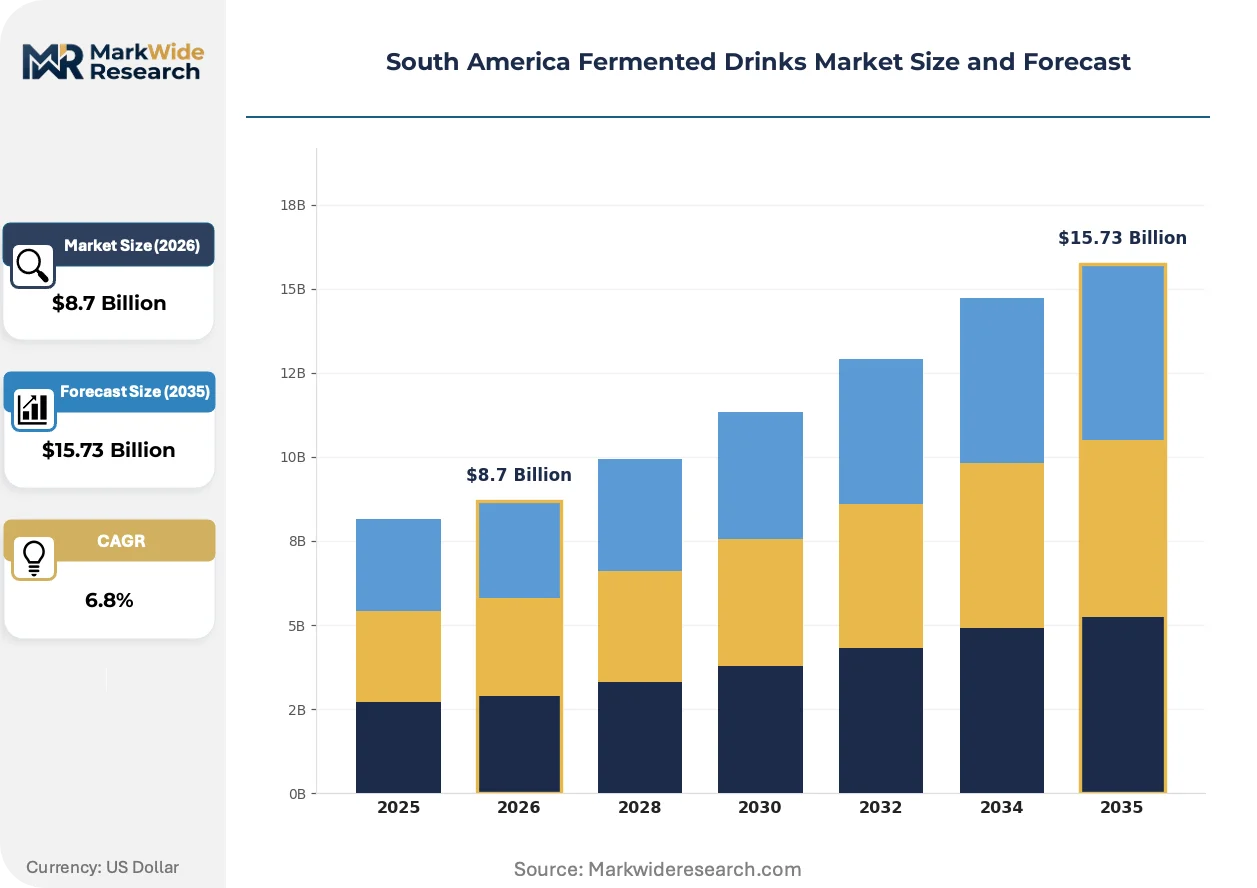
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Chicha, Pulque End User: Restaurants, Supermarkets, Health Stores, Online Retail Packaging Type: Bottles, Cans, Pouches, Kegs Distribution Channel: Wholesale, Direct-to-Consumer, Retail Chains, E-commerce |
| Companies Covered | Nestle SA, Yakult Honsha Co Ltd, Bacardi Limited, Groupe Danone SA, Ambev, Heineken NV, Anheuser-Busch, Amyris, Britvic PLC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fermented Drinks Market Evolving Landscape
Fermentation technology is absorbing digital monitoring capabilities while regulatory frameworks harden safety standards. Consumer behavior shifts toward subscription-based procurement of live-culture products.
Controlled-environment fermentation systems are absorbing IoT sensor networks for real-time pH and temperature monitoring. Brazilian dairy cooperatives deploy these systems to reduce batch failure rates. The technology is absorbing quality-control labor costs while compressing time-to-market for new formulations.
ANVISA's microbiological safety standards for fermented beverages now require documented hazard analysis at each production stage. This elevates compliance costs for imported cultures and packaging materials. Brazilian producers respond by consolidating procurement toward ANVISA-prequalified local suppliers.
Subscription-based procurement of kefir and kombucha is displacing conventional supermarket purchasing among health-conscious consumers in São Paulo and Rio de Janeiro. Direct-to-consumer channels capture higher margins while building consumption habit data. This pattern concentrates in Brazil's southeastern urban corridor where cold-chain logistics mature fastest.
South America Fermented Drinks Market Segmentation
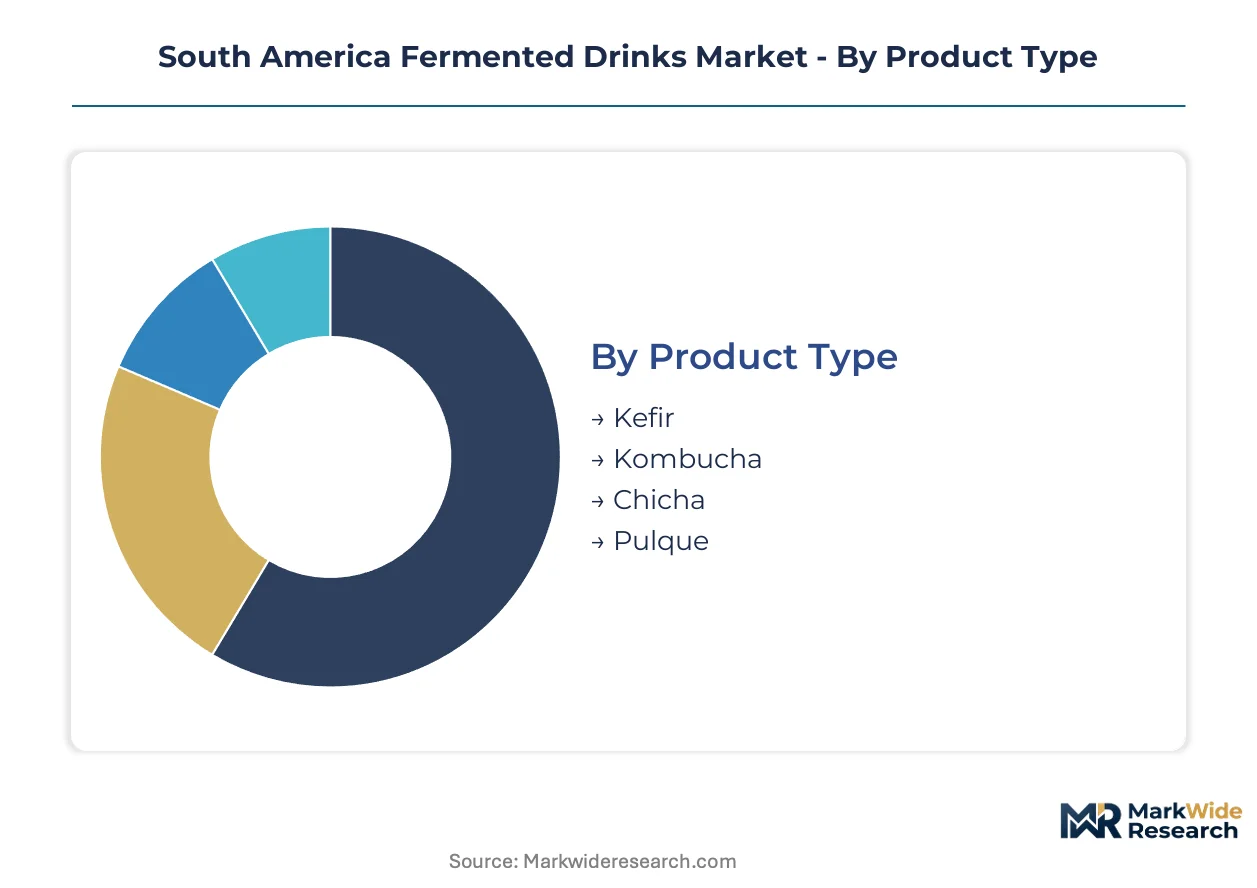
Fermented drinks in South America fragment across distinct demand profiles shaped by refrigeration infrastructure, cultural consumption patterns, and regulatory compliance intensity. Understanding these segment boundaries clarifies where margin pools concentrate and where supply-side investments unlock geographic expansion.
Product Type:
Standardization dominates dairy-based fermentation while artisanal protocols persist in grain and agave categories, creating divergent compliance burdens and shelf-life profiles across the customization spectrum.
- Kefir:Fermented milk beverage containing kefir grains with 10-12% milk fat content and documented colony-forming units. Demand concentrates in São Paulo and Rio de Janeiro health stores where ANVISA's live-culture certification protocols elevate product credibility and justify premium positioning.
- Kombucha:Tea-based fermentation yielding acetic acid and carbonation through SCOBY culture maintenance. Brazilian supermarket networks in the southeastern urban corridor are expanding refrigerated shelf space for unpasteurized variants, though cold-chain gaps in northeastern states constrain distribution reach.
- Chicha:Maize-fermented beverage tied to Andean ceremonial consumption with mandated traditional preparation protocols in Peru.
- Pulque:Agave sap fermentation sustaining deep-rooted demand in Mexico's southern reach with techniques now adapting to controlled commercial environments.
Most installed capacity flows through Kefir. Expansion is steepest in Kombucha.
End User:
Channel selection determines margin capture versus volume scale, with health stores and online retail commanding premium pricing while restaurants and supermarkets optimize throughput.
- Restaurants:On-premise consumption of craft-style fermented ales and ceremonial beverages. Buenos Aires and Bogotá urban bars represent concentrated demand for Heineken NV's premium positioning.
- Supermarkets:Mass-market distribution requiring ANVISA-compliant cold-chain partnerships. Brazilian networks are absorbing IoT-enabled refrigeration investments to reduce spoilage rates for live-culture products.
- Health Stores:Curated probiotic assortments with documented strain registration. Retailers now demand colony-forming unit counts as a condition of shelf access.
- Online Retail:Subscription-based procurement bypassing refrigeration constraints through temperature-controlled packaging investments.
Volume concentrates in Supermarkets. Margin expansion is climbing fastest in Online Retail.
Packaging Type:
Material selection tracks shelf-life requirements and distribution channel economics, with glass and aluminum dominating premium positioning while flexible formats reduce last-mile logistics costs.
- Bottles:Glass containers preserving live-culture viability for kefir and kombucha. Health stores across Brazil and Argentina prioritize bottle formats for premium perception.
- Cans:Aluminum barriers enabling ambient distribution for pasteurized variants. Ambev leverages existing bottling infrastructure to distribute chicha-derived products through Andean retail chains.
- Pouches:Flexible packaging reducing shipping weight for direct-to-consumer channels.
- Kegs:Stainless steel vessels for on-premise draft service in restaurants and ceremonial settings.
Most fermentation output ships in Bottles. Format innovation is accelerating most quickly in Pouches.
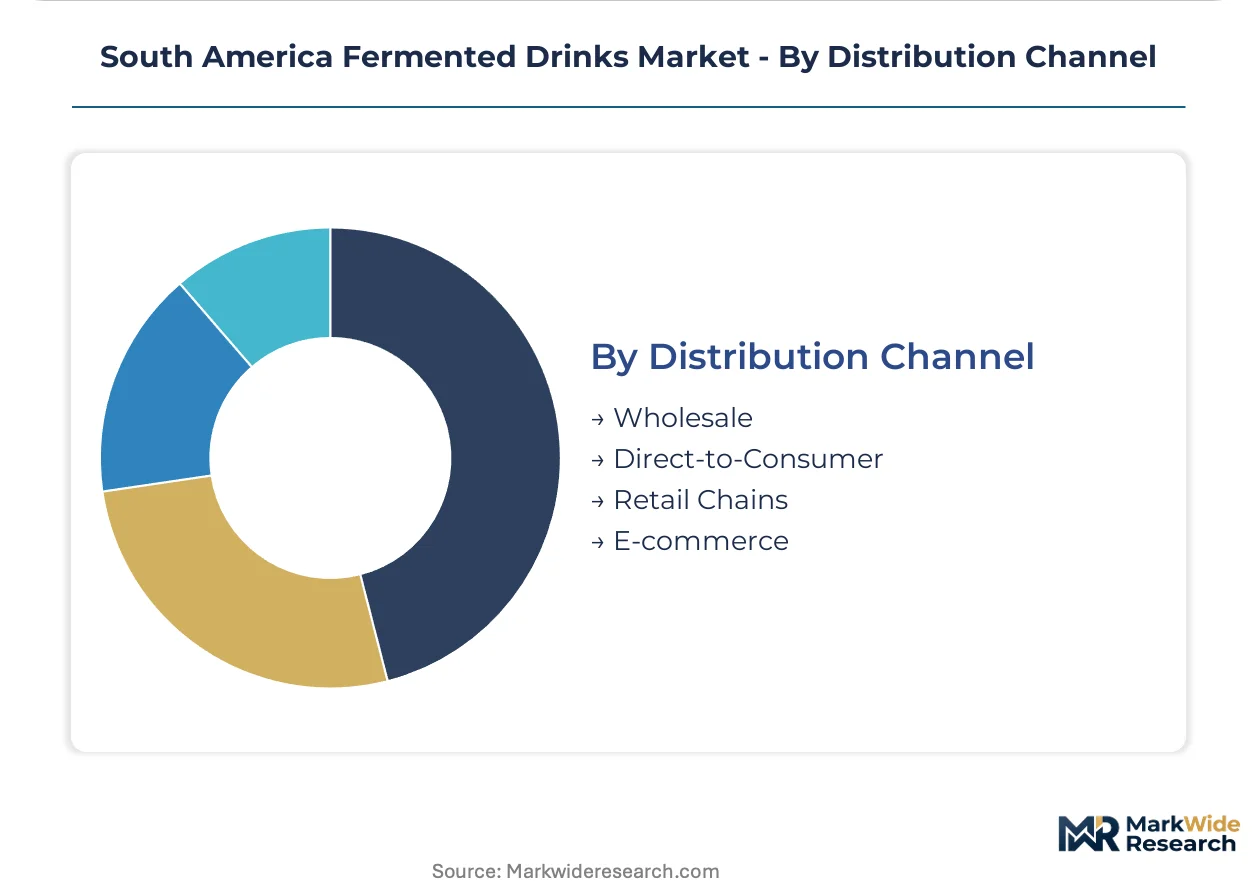
Distribution Channel:
Channel structure determines regulatory touchpoint density, with wholesale and retail chains absorbing compliance verification burdens while direct-to-consumer models internalize traceability requirements.
- Wholesale:Bulk distribution to retailers and foodservice operators. Chicha maintains wholesale demand across Peru's Andean communities tied to cultural festival consumption.
- Direct-to-Consumer:Subscription logistics with temperature-controlled packaging. São Paulo and Rio de Janeiro consumers demonstrate highest adoption of recurring kefir and kombucha procurement.
- Retail Chains:Branded shelf placement requiring ANVISA-mandated batch-tracking systems. Legacy dairy cooperatives face capital barriers to upgrading digital traceability.
- E-commerce:Platform-mediated sales with third-party logistics integration.
Volume flows predominantly through Retail Chains. Channel development is expanding most steeply in Direct-to-Consumer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production investment toward jurisdictions with streamlined strain-registration pathways. Brazilian producers absorb elevated compliance costs while Argentine entrants exploit labeling harmonization gaps. Cross-border formulation strategies now prioritize Mercosur alignment over Andean Community integration.
Brazil
Live-culture certification protocols and cold-chain infrastructure expansion drive demand concentration in São Paulo and Rio de Janeiro. ANVISA's microbiological safety standards mandate documented hazard analysis at each production stage, elevating procurement toward prequalified local suppliers. Southeastern urban corridors absorb the majority of kefir and kombucha distribution capacity.
Argentina
Health store expansion in Buenos Aires and Córdoba outpaces supplier capacity, creating first-mover positioning opportunities for probiotic brands. The country's national food safety authority enforces labeling requirements less stringent than Brazilian counterparts, reducing compliance timelines for new entrants. Metropolitan retail networks prioritize documented colony-forming unit counts as shelf-access conditions.
Peru
Ceremonial consumption patterns sustain wholesale chicha demand across Andean communities. The national health authority mandates traditional preparation protocols for commercial production, excluding industrial-scale entrants from artisanal segments. Cusco and Puno regions concentrate direct-to-consumer channels tied to cultural festival calendars.
Colombia
Craft-style fermented ales capture urban bar demand in Bogotá's premium on-premise segment. Local regulatory frameworks for fermented beverages remain less codified than Brazilian standards, attracting formulation testing from regional producers. Antioquia and Valle del Cauca departments host emerging distribution partnerships for cross-border brands.
Chile
Wine fermentation expertise transfers to non-alcoholic probiotic categories through equipment supplier adaptation. The country's food safety regulator maintains alignment with Mercosur standards, facilitating import substitution for Brazilian-sourced cultures. Santiago Metropolitan Region concentrates cold-chain logistics investments for temperature-sensitive products.
South America Fermented Drinks Market Competitive Landscape
Brazilian producers anchor the mass-market tier; Andean specialists hold ceremonial and craft positioning. The market structure fragments across three operational scales: multinational beverage conglomerates with bottling infrastructure, dairy cooperatives with fermentation legacy, and artisanal distillers with cultural distribution channels. Strategic archetypes include cold-chain integrators, culture propagation specialists, and ceremonial-channel custodians. Capacity expansion and regulatory compliance partnerships dominate competitive moves as producers consolidate procurement toward ANVISA-prequalified vendors.
Within the multinational tier, Groupe Danone SA and Heineken NV exemplify divergent positioning strategies. Ambev occupies a central role in Andean distribution infrastructure through retail chain partnerships. These three entities represent the spectrum from dairy-based probiotic portfolios to premium alcoholic fermentation, with each anchoring distinct margin pools across Brazilian and Andean market segments.
| Leading Market Players |
|---|
| Nestle SA |
| Yakult Honsha Co Ltd |
| Bacardi Limited |
| Groupe Danone SA |
| Ambev |
| Heineken NV |
| Anheuser-Busch |
| Amyris |
| Britvic PLC |
| Others |
Value Network & Pricing Analysis
ANVISA's live-culture certification protocols are forcing Brazilian health store chains to consolidate procurement toward prequalified local suppliers, compressing margins for imported strain distributors while elevating pricing power for domestic culture propagators with verified colony-forming unit documentation.
Pricing Analysis
Direct-to-consumer subscription margins capture the widest spread in São Paulo and Rio de Janeiro, where temperature-controlled packaging investments justify recurring revenue premiums over supermarket shelf pricing. Three-tier pricing structure across premium live-culture kefir, standard pasteurized variants, and economy-positioned grain ferments reflects certification intensity and cold-chain compliance costs. Pricing pressure stems from currency volatility elevating working capital requirements for European and North American starter culture imports. Health-conscious urban consumers in Brazil's southeastern corridor demonstrate lowest price sensitivity, while northeastern retail chains face acute margin compression due to refrigeration infrastructure gaps.
Supply Chain Analysis
Microbiologist talent scarcity in Brazilian universities constrains laboratory capacity for strain isolation and culture maintenance, forcing producers to compete for qualified technicians across São Paulo's fermentation clusters and Rio de Janeiro's dairy cooperative networks. Supply concentrates in Brazil's southeastern urban corridor and Peru's Andean grain distilling regions, with Argentine probiotic production emerging as secondary capacity. Raw material dependencies include dairy substrates from Minas Gerais cooperatives, maize bases from Cusco-Puno agricultural zones, and imported SCOBY cultures from North American propagation facilities. Single-source vulnerability for specific probiotic strains exposes Brazilian producers to import disruption. Distribution runs through Ambev's Andean retail chain partnerships and Danone's cold-chain supermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with ANVISA's strain registration requirements creating durable competitive moats for compliant producers while excluding informal competitors from health store shelf access.
For Market Incumbents: Anchor cold-chain infrastructure investments in Brazil's northeastern states before regional competitors replicate southeastern distribution density. Consolidate backward integration into local culture propagation to neutralize import dependency risks from currency volatility. Lock exclusive partnerships with ANVISA-prequalified packaging vendors to raise compliance barriers for artisanal challengers lacking capital for batch-tracking system upgrades. For New Entrants and Emerging Players: Capture Argentina's underpenetrated probiotic segment in Buenos Aires and Córdoba health stores where supplier capacity lags shelf space expansion. Exploit labeling harmonization gaps relative to Brazilian standards to accelerate product launch timelines. Deploy subscription-based direct-to-consumer models with temperature-controlled packaging to bypass incumbent-controlled retail chain gatekeeping. For Investors and Strategic Acquirers: Asymmetric upside sits with culture propagation specialists possessing documented strain libraries and ANVISA registration pathways, positioned for acquisition by multinational beverage conglomerates seeking compliant supply chain integration. Long-term viability hinges on regulatory arbitrage durability across Mercosur alignment versus Andean Community divergence. Monitor ANVISA enforcement intensity in Brazil's northeastern states as inflection indicator for geographic expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Strain Registration Investment | Documented colony-forming unit protocols unlock health store shelf access in São Paulo and Rio de Janeiro. |
| Cold-Chain Partnership Expansion | IoT-enabled refrigeration investments reduce spoilage rates for live-culture kefir and kombucha distribution. |
| Local Culture Propagation Capacity | In-house starter culture production neutralizes currency volatility exposure from European and North American imports. |
| Subscription Channel Development | Direct-to-consumer logistics with temperature-controlled packaging bypass incumbent retail chain dominance. |
| Andean Distribution Infrastructure | Ambev-style retail chain partnerships unlock ceremonial and craft beverage access across Peru and Colombia. |
Research Methodology
Bottom-up health store and supermarket channel modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with brand managers at Brazilian dairy cooperatives, category buyers at Argentine health store chains, regulatory affairs specialists navigating ANVISA compliance, and culture propagation laboratory directors supplied demand-side and operational perspectives. Secondary validation drew from ANVISA regulatory filings, Mercosur trade statistics, customs records for starter culture imports, and cold-chain infrastructure investment disclosures from Brazilian supermarket networks. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped fermentation substrate flows through production stages to end-use channels across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and geographic regulatory cluster. CAGRs derived from fitted growth curves incorporating live-culture certification adoption rates, cold-chain penetration trajectories, and ceremonial consumption pattern stability. Industry-specific forecast inputs comprised ANVISA enforcement intensity indices and microbiologist graduate pipeline data from Brazilian universities.
Currency volatility, regulatory enforcement divergence between Mercosur and Andean Community members, and cold-chain infrastructure buildout delays are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding sustained ANVISA compliance cost structures and stable ceremonial demand patterns in Peru's Andean communities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Irish Whiskey Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Wine Box Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Europe Alcoholic Beverage Market
Alcoholic Beverages
Global Premium Alcoholic Beverage Market
Alcoholic Beverages
Wine Cork Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Guerbet Alcohols Market