
 France Tequila Market | 2026-2036
France Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
France Tequila Market Insights
The EU Green Deal is realigning packaging and sourcing expectations for spirits imported into France. Diageo plc leverages its distribution network to secure shelf space across French hypermarkets. Pernod Ricard SA anchors its portfolio through dedicated tequila brands with established bar relationships. Jose Cuervo S.A. de C.V. competes on heritage storytelling and agave provenance credentials.
Tequila is a distilled spirit manufactured from fermented blue agave juice, requiring minimum 51% agave content for mixto classification and 100% agave for premium grades, with distillation typically occurring at 35-55% ABV. Blanco expressions lead volume due to lower price points and cocktail versatility, while extra añejo commands concentrated margin pools among collectors. The on-trade channel through bars and restaurants captures the highest value per liter as mixologists promote aged expressions to affluent clientele.
ANSM monitors alcohol labeling and health warnings under French public health codes, while EU Spirits Regulation governs geographical indication protections and production definitions. France's national public health agency enforces strict marketing restrictions that limit broadcast advertising and sponsor visibility. Stakeholders must monitor evolving EU-wide sustainability disclosure requirements and anticipate stricter glass recycling mandates affecting import logistics.
Market Dynamics
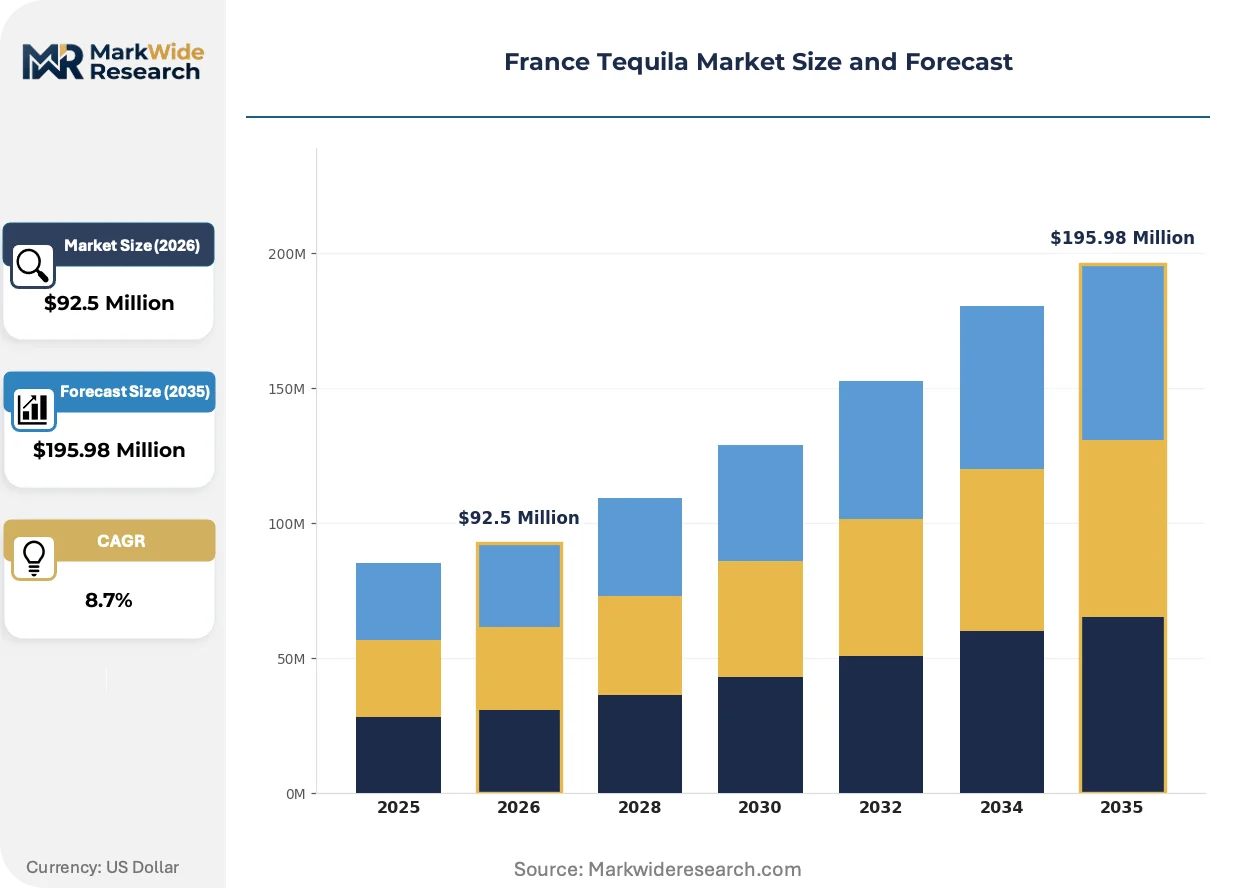
The France tequila market pivots on EU Green Deal packaging mandates that are forcing importers to reconfigure glass sourcing and carbon disclosure protocols ahead of 2030 sustainability deadlines.
Growth Catalysts
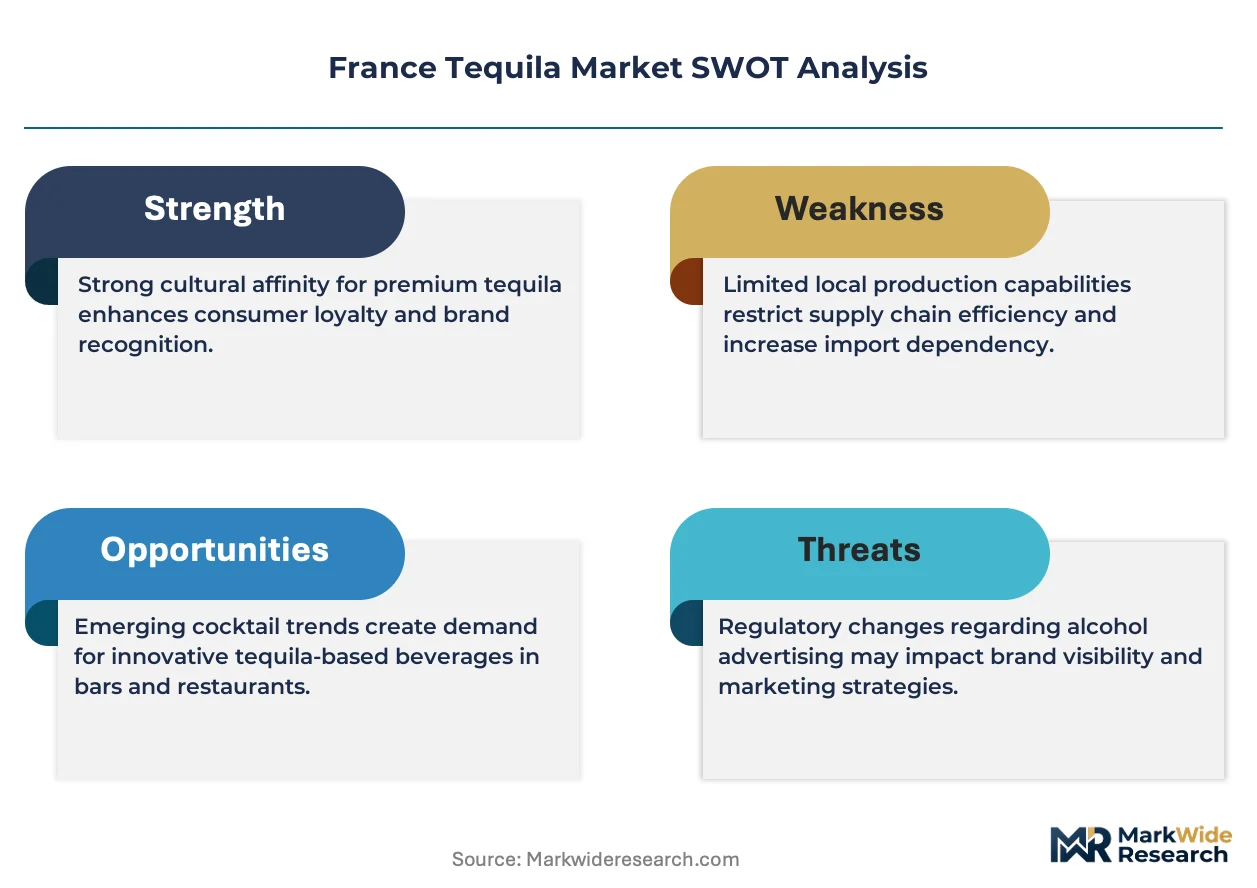
- EU Spirits Regulation harmonization:Standardized geographical indication protections enable French distributors to source authenticated 100% agave products with verified provenance documentation, reducing counterparty risk.
- Paris cocktail bar density:Premium on-trade venues in the capital cluster generate concentrated demand for aged expressions, creating pull-through for super-premium imports.
- Millennial urban consumption:Consumers aged 25-40 in Lyon and Marseille demonstrate measurable preference for terroir-transparent spirits, rewarding brands with estate-specific storytelling.
Market Restraints
- Agave supply concentration:Blue weber agave cultivation concentrates in Jalisco highlands, exposing French importers to Mexican harvest volatility and price spikes.
- ANSM marketing restrictions:France's national public health agency enforces broadcast advertising bans and sponsorship limitations that constrain brand-building reach versus adjacent spirits categories.
- Glass recycling mandates:Stricter EU-wide packaging recovery targets increase logistics costs for imported bottled spirits, compressing landed margins.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur expansion:Underpenetrated coastal hospitality markets outside Marseille offer white space for premium tequila placement in seasonal high-end venues.
- CSRD-aligned sustainability disclosure:Early adoption of EU corporate sustainability reporting standards creates differentiation among environmentally credentialled brands.
- Direct-to-bar distribution:Bypassing traditional wholesale layers through specialized spirits importers enables margin capture and relationship control with mixologist gatekeepers.
Industry Challenges
- Agave spirits certification complexity:Navigating EU Spirits Regulation classification requirements demands specialized regulatory affairs capacity that smaller distributors lack.
- On-trade relationship intensity:Securing consistent placement in Paris cocktail bars requires sustained brand ambassador investment and staff education programming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Tequila Market |
| Market Size in 2026 | $92.5 Million |
| Market Size in 2035 | $195.98 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Distribution Channel: Retail Stores, Online, Bars, Restaurants Customer Type: Millennials, Gen X, Baby Boomers, Tourists Price Segment: Premium, Mid-Range, Economy, Super Premium |
| Companies Covered | Bacardi Limited, Heaven Hill Distilleries, Diageo plc, Casamigos (Diageo), El Grado Tequila LLC, Pernod Ricard SA, Jose Cuervo S.A. de C.V., Patrón Spirits International, Suntory Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Tequila Market Trends and Innovations
Three forces are actively restructuring how tequila enters and competes within France: sustainable packaging innovation, regulatory disclosure expansion, and channel-specific positioning strategies.
Alternative agave fiber packaging is overtaking conventional glass for sample formats and gift sets, with several importers testing biodegradable materials for on-trade promotional kits. Premium bars in Paris tenth arrondissement are adopting these formats for event programming. This shift is compressing per-unit packaging costs while satisfying venue sustainability procurement criteria.
The EU Green Deal's packaging and waste directive is mandating extended producer responsibility schemes that require French importers to document end-of-life recovery pathways for all glass containers. Large hypermarket chains are now demanding carbon footprint labelling as a listing prerequisite. Añejo and extra añejo categories face the steepest compliance burden due to higher bottle weights and premium positioning expectations.
Mixologist-driven curation is displacing portfolio-based wholesale selling in the on-trade channel, with bar programs increasingly selecting single-estate expressions over volume brands. Independent importers specializing in artisanal Mexican producers are capturing shelf space from traditional distributors. This pattern concentrates in Paris and Lyon, where bartender guilds actively influence spirits procurement decisions through tasting panels and collaborative menu development.
France Tequila Market Segmentation
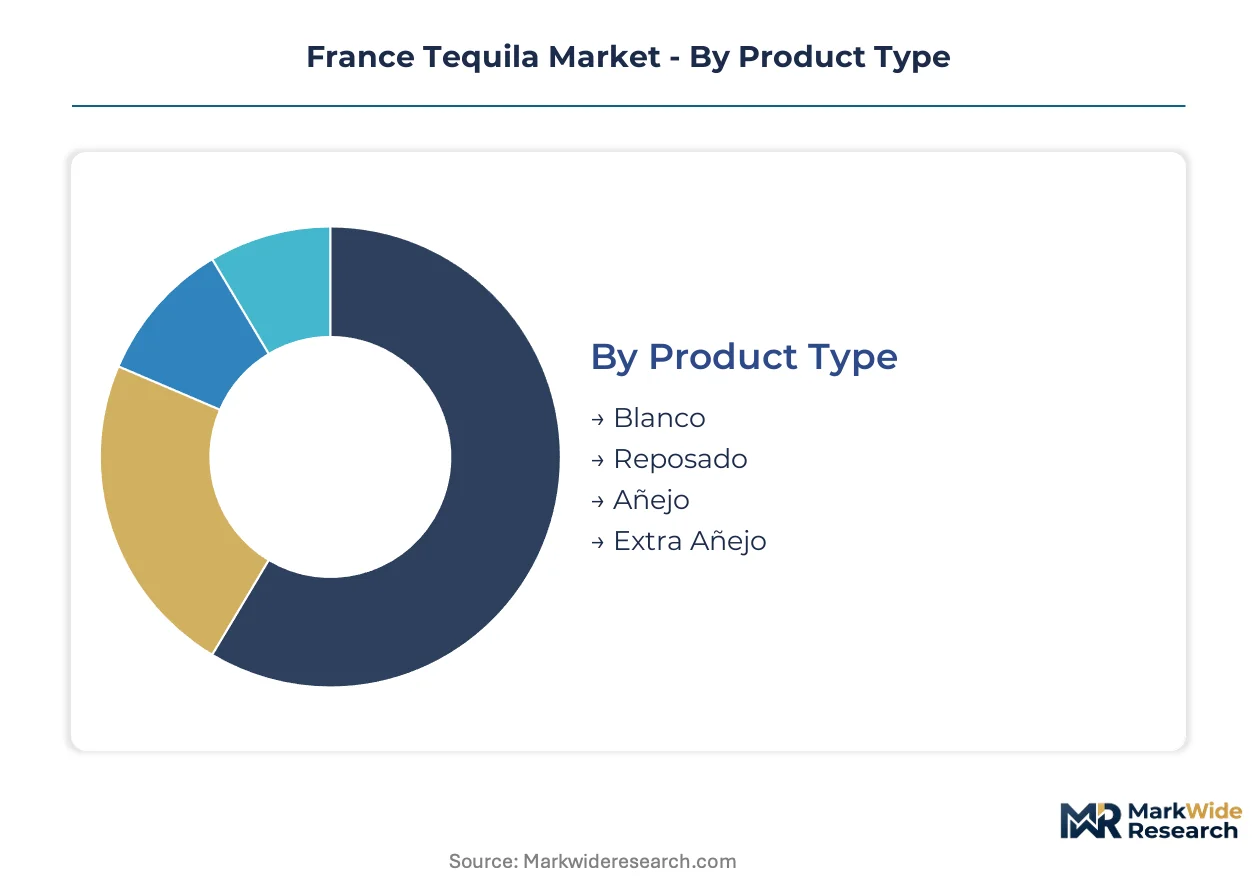
Tequila segmentation in France tracks how consumer sophistication, channel access, and price thresholds fragment demand across distinct buyer profiles. Understanding these splits enables importers to align portfolio depth with where margin pools actually concentrate.
Product Type:
Consumer choice pivots on aging duration and the flavor complexity that barrel contact delivers.
- Blanco:Unaged or briefly rested expressions preserve raw agave character with crisp vegetal and citrus notes. Paris cocktail bars drive volume here, as mixologists prize the clean base for margaritas and palomas where agave identity must cut through modifiers.
- Reposado:Two to twelve months of oak contact softens the spirit with vanilla and light caramel while retaining brightness. Lyon on-trade venues favor reposado for stirred agave cocktails that bridge accessibility and sophistication.
- Añejo:One to three years of aging develops deeper wood spice and dried fruit concentration. Añejo serves neat consumption in Marseille's premium restaurant scene where diners seek sipping alternatives to cognac.
- Extra Añejo:Extended barrel maturation beyond three years creates concentrated, cognac-like profiles with substantial tannin structure. Collectors and connoisseurs in Provence-Alpes-Côte d'Azur seasonal venues sustain this ultra-premium tier.
Blanco leads on scale; extra añejo leads on momentum.
Distribution Channel:
Channel selection determines price realization and brand control intensity for French importers.
- Retail Stores:Hypermarkets and specialized wine merchants capture volume through visible shelf placement and promotional pricing. Carrefour and Casino networks dominate mass-market blanco sales with standardized margin structures.
- Online:Direct-to-consumer platforms and specialized spirits e-tailers serve educated buyers seeking rare expressions. E-commerce climbs fastest as millennials research provenance and compare estate credentials before purchase.
- Bars:Premium cocktail establishments in Paris tenth arrondissement and Lyon Presqu'île generate the highest value per liter through mixologist advocacy and menu integration.
- Restaurants:Fine dining venues in Marseille and coastal Provence position aged tequilas as digestifs, capturing margin through by-the-glass programs and sommelier-guided pairings.
Bars command the steepest pricing power; online expands most quickly.
Customer Type:
Generational cohorts diverge sharply in how they discover, evaluate, and purchase agave spirits.
- Millennials:Urban consumers aged 25-40 demonstrate the strongest preference for terroir transparency and craft production narratives. This cohort dominates discovery at Paris cocktail bars and drives social sharing that amplifies brand awareness.
- Gen X:Established professionals aged 41-56 balance exploration with consistency, favoring recognized premium brands for home entertaining. Gen X sustains retail premiumization as they trade up from entry-level mixtos.
- Baby Boomers:Consumers over 57 approach tequila with lingering quality skepticism from early mass-market experiences. Conversion requires education focused on 100% agave certification and production integrity.
- Tourists:International visitors in French Riviera seasonal markets purchase gift formats and airport retail exclusives. Tourist demand concentrates in summer months with limited year-round baseline.
Millennials anchor volume growth; Gen X anchors value stability.
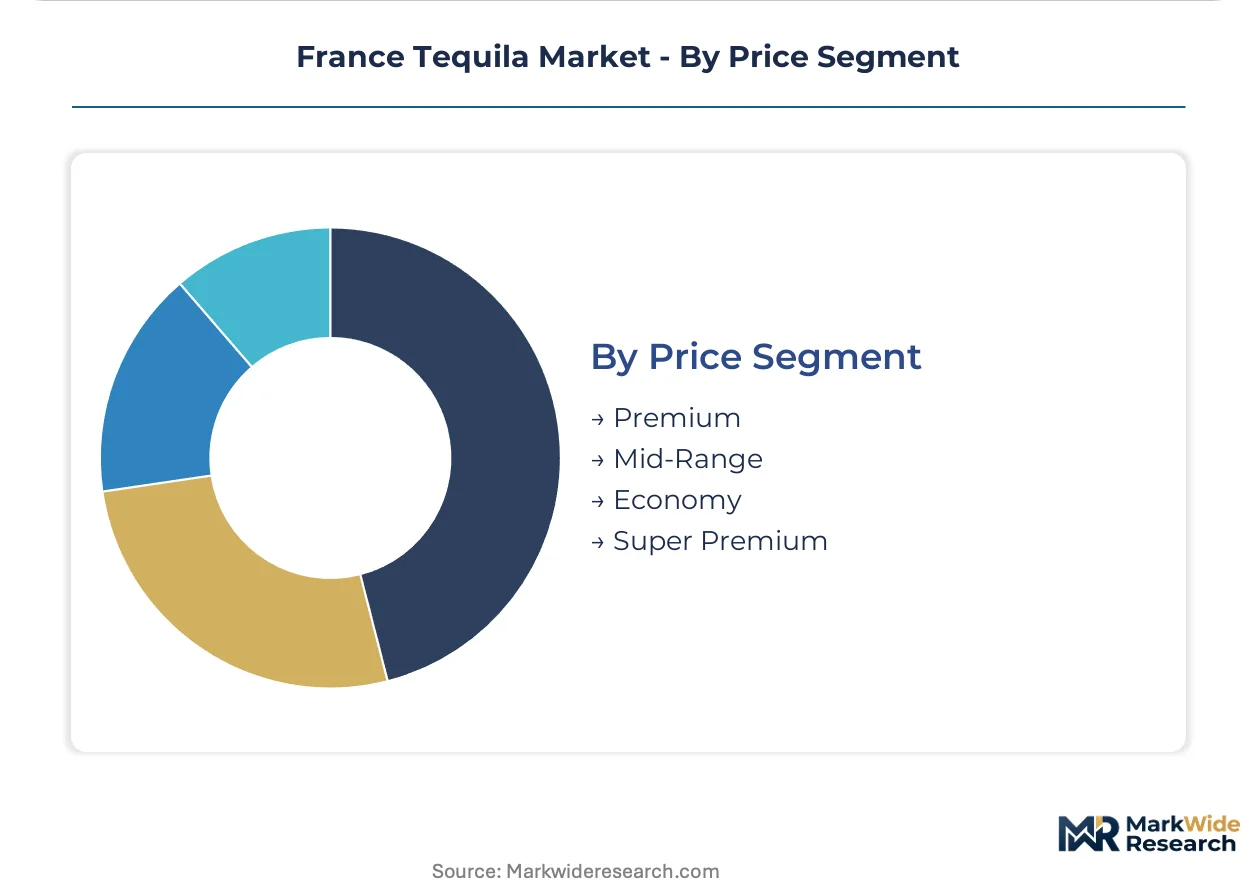
Price Segment:
Pricing tiers separate occasional purchasers from committed enthusiasts and collectors.
- Economy:Mixto expressions at entry price points serve price-sensitive consumers and high-volume cocktail production. This tier faces margin compression from glass recycling compliance costs and agave price volatility.
- Mid-Range:Standard 100% agave blanco and reposado expressions dominate household penetration. Mid-range captures the broadest demographic spread across French urban centers.
- Premium:Añejo and certified additive-free expressions reward brands with estate-specific storytelling. Premium placement requires sustained investment in bartender education and tasting programming.
- Super Premium:Extra añejo, single-estate, and limited releases command collector attention and gift purchase occasions. Super premium concentrates in Paris and Lyon where affluent buyers seek differentiation.
Mid-range leads on absolute volume; super premium leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris-based mixologists and hospitality entrepreneurs anchor France's tequila expertise concentration, with specialized knowledge clustering in urban cocktail bar networks across Île-de-France and major metropolitan centers.
Île-de-France
Paris cocktail bars in the tenth and eleventh arrondissements drive premium aged expression demand through mixologist advocacy and menu integration. ANSM enforces strict broadcast advertising bans that constrain mass-market brand building. The capital's density of specialized agave spirits importers creates concentrated distribution expertise unavailable elsewhere in France.
Auvergne-Rhône-Alpes
Lyon's Presqu'île district hospitality venues generate sustained pull-through for reposado and añejo categories through sommelier-guided programs. EU Spirits Regulation harmonization enables verified 100% agave sourcing with reduced counterparty risk. The city's bartender guilds actively influence procurement decisions through collaborative tasting panels and estate-specific curation.
Provence-Alpes-Côte d'Azur
Seasonal high-end venues in Marseille and the French Riviera sustain super-premium extra añejo demand among affluent collectors and gift purchasers. EU Green Deal packaging mandates force reconfiguration of glass sourcing and carbon disclosure protocols for imported spirits. Coastal hospitality markets outside Marseille remain underpenetrated, offering white space for premium placement.
Hauts-de-France
Lille's emerging craft cocktail scene demonstrates measurable preference for terroir-transparent spirits among millennial consumers. France's national public health agency extends marketing restrictions to digital sponsorships, limiting influencer-driven discovery. The region's proximity to Belgian and Dutch distribution hubs creates cross-border logistics advantages for specialized importers.
Nouvelle-Aquitaine
Bordeaux wine merchant networks are expanding into agave spirits curation, leveraging established relationships with educated buyers. Stricter EU-wide glass recycling mandates increase logistics costs for imported bottled spirits, compressing landed margins. The region's tourism infrastructure supports summer gift format demand through airport retail and hospitality venue placement.
France Tequila Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across France's tequila market structure, where multinational spirits conglomerates hold consolidated positions against specialized artisanal importers. The vendor base separates into three strategic archetypes: global portfolio owners with dedicated tequila divisions, independent estate-focused distributors, and hybrid luxury goods conglomerates with spirits exposure. M&A activity concentrates on acquiring authentic Mexican production credentials, while portfolio diversification into additive-free and single-estate expressions dominates competitive maneuvering.
Among global portfolio owners, Diageo plc and Pernod Ricard SA occupy positions representing scale-driven distribution leverage across French hypermarkets and on-trade networks. Jose Cuervo S.A. de C.V. anchors the heritage-authenticity archetype, with its family-owned structure exemplifying estate-specific storytelling that resonates with millennial urban consumers. These three entities collectively represent the competitive tension between volume efficiency and provenance credibility that defines France's tequila market positioning.
| Leading Market Players |
|---|
| Bacardi Limited |
| Heaven Hill Distilleries |
| Diageo plc |
| Casamigos (Diageo) |
| El Grado Tequila LLC |
| Pernod Ricard SA |
| Jose Cuervo S.A. de C.V. |
| Patrón Spirits International |
| Suntory Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
Blue weber agave futures pricing in Jalisco cascades through French import channels, compressing mid-range tier margins while super-premium estate brands absorb volatility through collector pricing power anchored in terroir storytelling.
Pricing Analysis
Bundled on-trade programming with staff education and menu integration commands 40-60% premiums over unbundled wholesale case rates. Three-tier pricing structure across super-premium, premium, and economy levels separates additive-free estate credentials from standard 100% agave and entry mixto classifications. Cost compression in economy tiers is intensifying because EU Green Deal glass recycling mandates layer logistics charges onto already thin landed margins. Price-sensitive hypermarket buyers in Carrefour and Casino networks drive volume at entry price points, while collector segments in Paris tenth arrondissement demonstrate minimal elasticity for extra añejo releases.
Supply Chain Analysis
Agave piña supply rests on Jalisco highland cultivation zones with secondary sourcing from Nayarit and Michoacán fallback regions. Raw material dependencies center on mature blue weber plants requiring 7-10 year growth cycles, French glass bottle manufacturing for premium presentation formats, and oak barrel cooperage from Limousin forests for añejo maturation. Single-source vulnerability concentrates in Jalisco highland estate producers lacking geographic diversification against climate-induced harvest failures. Distribution runs through specialized spirits importers with Paris-based warehousing before final-mile delivery to on-trade venues and retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's tequila market operates as a geographic-arbitrage play where EU regulatory compliance costs and sustainability disclosure requirements create entry barriers that protect incumbent margin structures against low-cost Mexican direct exporters lacking ANSM-aligned labeling capacity.
For Market Incumbents: Cement bar relationships through dedicated brand ambassador programs targeting Lyon and Marseille mixologist guilds before emerging estate-focused distributors capture shelf space. Lock in long-term agave supply contracts with Jalisco highland producers to neutralize harvest volatility that threatens mid-range pricing stability. Channel control through direct-to-bar distribution layers defends against hypermarket margin compression.
For New Entrants and Emerging Players: Additive-free certification technology serves as a credible wedge against portfolio conglomerates with legacy mixto exposure. White space concentrates in Provence-Alpes-Côte d'Azur coastal venues outside Marseille where seasonal high-end hospitality lacks dedicated tequila programming. Target millennial discovery through Paris cocktail bar tasting panels before retail expansion.
For Investors and Strategic Acquirers: Asymmetric upside sits with independent estate-focused distributors holding verified 100% agave sourcing relationships and established ANSM compliance infrastructure. Long-term viability over the next decade hinges on sustainability credential alignment with EU Green Deal packaging mandates. Watch agave harvest yield reports from Jalisco as the inflection indicator for input cost pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Estate-Specific Sourcing Agreements | Direct contracts with Jalisco highland producers secure provenance documentation required under EU Spirits Regulation harmonization. |
| Sustainability Certification Program | CSRD-aligned carbon disclosure creates differentiation among hypermarket chains demanding environmental labelling. |
| Direct-to-Bar Distribution Buildout | Bypassing wholesale layers captures margin and relationship control with Paris and Lyon mixologist gatekeepers. |
| Additive-Free Production Investment | Certified clean production credentials command super-premium pricing among terroir-transparent millennial buyers. |
| Alternative Packaging Development | Agave fiber and biodegradable formats satisfy EU Green Deal mandates while reducing per-unit logistics costs. |
Research Methodology
Direct dialogue with tequila brand managers, specialized spirits importers, Paris cocktail bar owners, Lyon sommelier guild representatives, and ANSM regulatory affairs consultants grounded qualitative findings. Secondary validation drew from EU Spirits Regulation documentation, ANSM public health code filings, French customs import records, and EU Green Deal packaging directive texts. Bottom-up volume estimates from on-trade venue counts and retail channel audits triangulated against top-down market sizing from spirits industry association data.
Bottom-up modeling aggregated venue-level consumption patterns across Paris, Lyon, and Marseille metropolitan zones while top-down analysis tracked import volumes and price realization by tier. Segmentation dimensions included product type aging classification, distribution channel structure, generational buyer archetype, and price segment positioning. CAGRs were derived from trend extrapolation of import growth rates adjusted for channel mix shifts and regulatory compliance cost absorption. Forecast inputs incorporated agave harvest cycle timing and EU packaging mandate implementation schedules.
The model holds under stable EU-Mexico trade relations and consistent ANSM enforcement patterns; deviation in agave supply shocks or accelerated sustainability disclosure timelines would shift volume and value projections. Forecasts embed assumptions regarding millennial cohort expansion and on-trade channel premiumization that warrant sensitivity testing against macroeconomic consumption pressures. A small set of named triggers—agave price spikes, EU packaging mandate acceleration, and ANSM marketing restriction expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Alcohol Market
Alcoholic Beverages
Light-Flavor Liquor Market