
 Cocktail Mixers Market | 2026-2036
Cocktail Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Cocktail Mixers Market Intelligence
The bundling of complementary mixers into curated cocktail kits is consolidating consumer purchasing decisions toward convenient, all-in-one solutions. Fever-Tree sustains its premium market position through a sharp focus on natural ingredients and specialized flavor profiles for discerning consumers. Separately, Monin leverages its extensive portfolio of syrups and purees to serve both professional bartenders and the expanding at-home mixology segment.
Cocktail mixers are non-alcoholic preparations, including syrups and juices, designed to be combined with spirits to create mixed drinks. They are technically formulated for specific brix levels and pH balances, ensuring consistent flavor and texture in the final beverage. Fruit juices and soda water constitute the market's high-volume base, while artisanal syrups and bitters command significantly higher price points. Glass bottles remain the standard for premium packaging, though aluminum cans are gaining traction for single-serve and ready-to-mix products.
Food safety authorities like the US FDA and Europe's EFSA enforce stringent rules on ingredient sourcing, allergen declarations, and nutritional labeling. In parallel, national standards from bodies such as India's FSSAI govern the use of artificial sweeteners and preservatives in these products. Success for producers hinges on balancing the consumer shift toward natural, low-sugar options against the effective management of agricultural commodity price fluctuations.
Market Dynamics
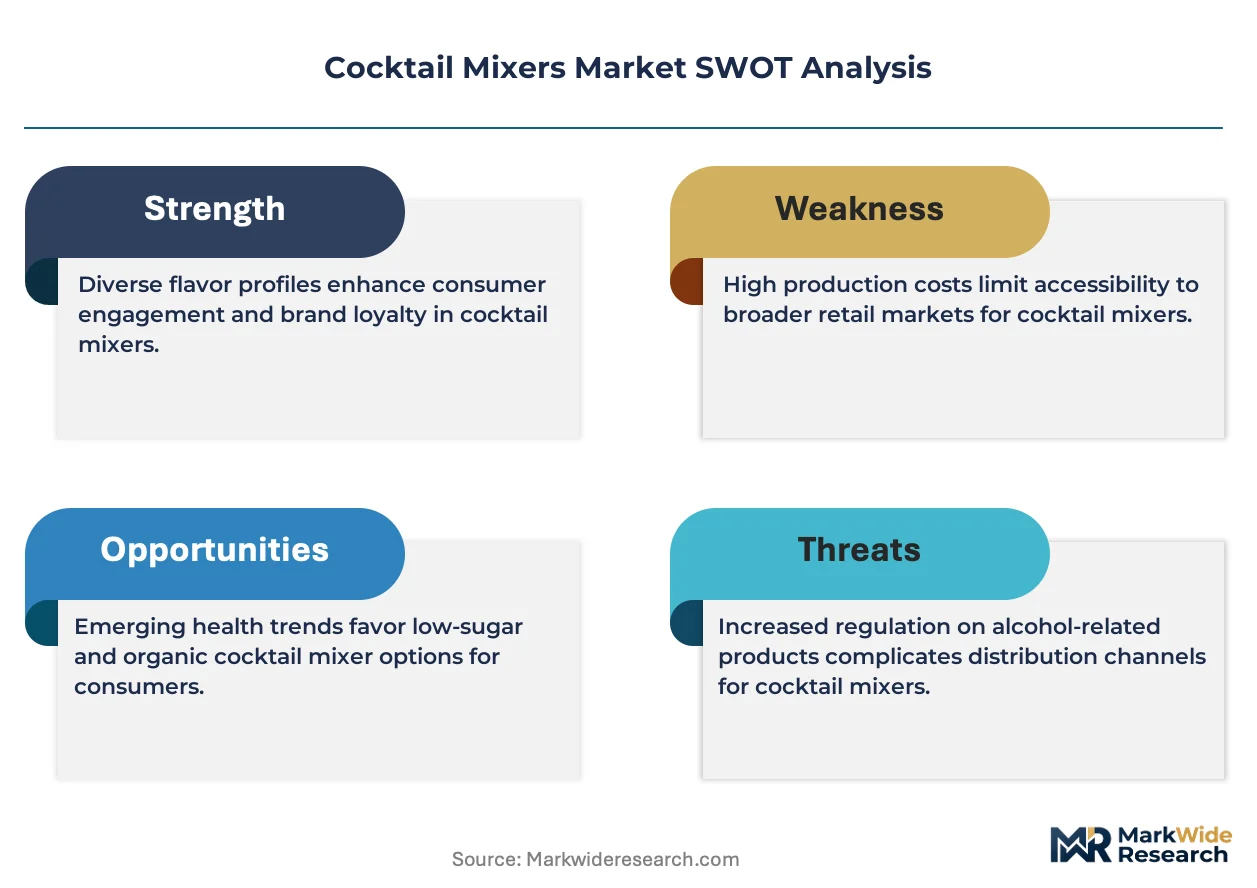
The central dynamic in the cocktail mixers market is the push for product premiumization colliding with non-negotiable consumer demand for clean-label, low-sugar formulations. This tension dictates research and development priorities and brand positioning across all price tiers, from mass-market to artisanal.
Growth Catalysts
- At-Home Mixology:The growth of sophisticated home bartending, particularly in US and European urban centers, boosts demand for high-quality, convenient mixers.
- On-Trade Channel Demand:Bars and restaurants increasingly use unique mixers as a key differentiator, creating a significant B2B growth avenue for premium brands.
- Clean-Label Formulations:Health consciousness pushes development toward mixers with natural ingredients and lower sugar content, expanding the addressable market.
Market Restraints
- Input Cost Volatility:Fluctuating prices for agricultural commodities like fruit purees and cane sugar create margin pressure and sourcing instability.
- Regulatory Compliance Burden:Stringent food safety rules from the FDA and EFSA impose significant testing and labeling costs, particularly for smaller producers.
- Threat of Substitution:Basic sodas and juices represent a low-cost alternative for consumers, capping pricing power for entry-level mixer products.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in Asia-Pacific, such as Australia and South Korea, offer white-space growth as local cocktail culture expands.
- Non-Alcoholic Segment:Developing mixers formulated specifically for non-alcoholic spirits addresses the growing "sober curious" consumer base.
- DTC Subscription Models:Curated, direct-to-consumer kits provide a recurring revenue channel and build brand loyalty among at-home mixologists.
Industry Challenges
- Ingredient Sourcing Consistency:Maintaining a stable, year-round supply of high-quality natural and exotic ingredients presents a major logistical hurdle for producers.
- Fragmented Labeling Standards:Navigating disparate international regulations for nutritional information and allergen declarations from bodies like FSSAI and EFSA complicates global distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocktail Mixers Market |
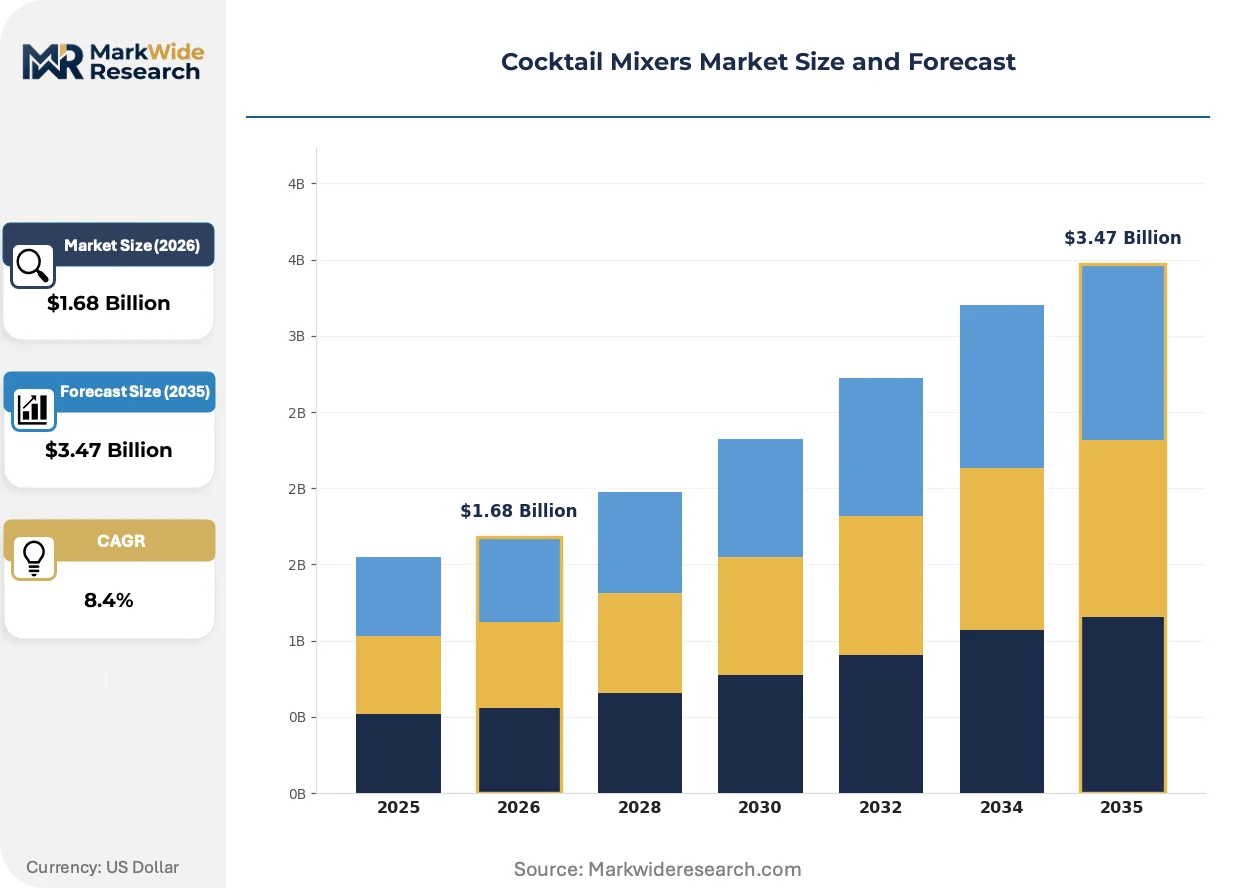
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syrups, Bitters, Fruit Juices, Soda Flavor Profile: Citrus, Herbal, Spicy, Sweet Packaging Type: Glass Bottles, Plastic Containers, Cans, Pouches Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Restaurants |
| Companies Covered | PepsiCo, Britvic, Fever-Tree, Q Mixers, A.G. Barr, Keurig Dr Pepper, Monin, Dabur, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocktail Mixers Market Strategic Shifts & Innovations
Product innovation is defined by a dual pursuit of convenience and authenticity. Formulations are evolving to deliver sophisticated, bar-quality experiences in ready-to-use formats while simultaneously meeting demands for healthier, more transparent ingredient lists.
Precision formulation software allows producers to digitally model and balance key attributes like brix levels, pH, and flavor interactions. Both large-scale manufacturers and artisanal brands are adopting this to shorten R&D cycles. This technology is automating the complex task of ensuring shelf stability while using natural ingredients, accelerating new product launches.
New nutritional labeling mandates from regulators like the US FDA require clearer declaration of added sugars on product panels. This policy compels manufacturers to increase transparency around sweetener content, directly influencing reformulation strategies. The low-sugar mixer category is most affected, responding with greater use of natural alternatives like monk fruit to comply.
A pronounced behavioral shift involves consumers opting for curated cocktail kits over purchasing individual mixer components. This trend disrupts the traditional à la carte retail model by favoring convenient, all-in-one solutions. This purchasing pattern is most evident in the direct-to-consumer channel across North America and Western Europe.
Cocktail Mixers Market Segmentation
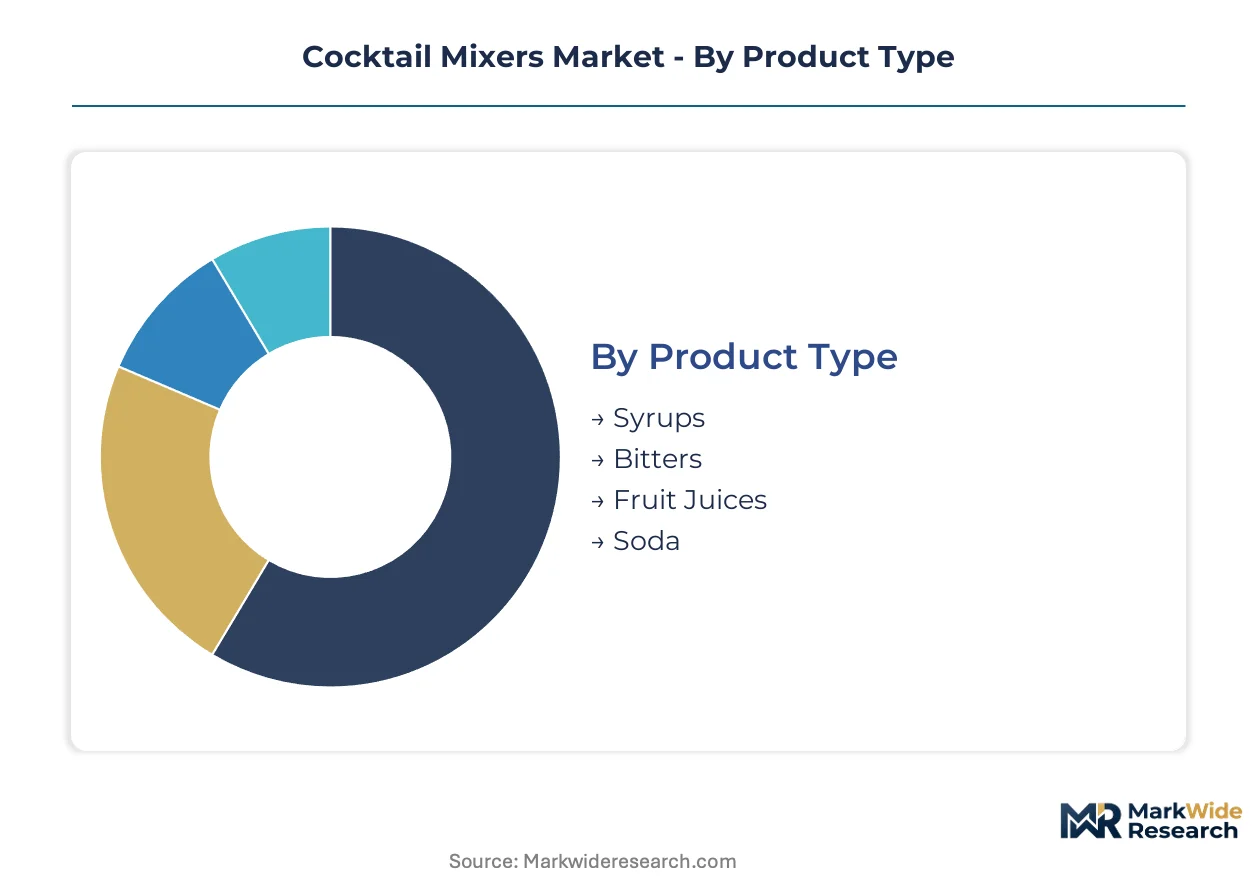
The cocktail mixers market segments based on product type, flavor profile, packaging, and distribution channel, reflecting the diverse preferences of both professional bartenders and at-home consumers. Understanding these segments helps producers tailor offerings to specific demand pockets and optimize market penetration strategies.
Product Type:
Consumer choice for cocktail mixers frequently hinges on the core ingredient's functional role in a drink.
- Syrups:These concentrated liquid sweeteners, often infused with botanicals or fruit extracts, provide both sweetness and complex flavor notes. Demand for artisanal and low-sugar syrups is high among at-home mixologists in urban centers seeking unique concoctions.
- Bitters:Highly concentrated alcoholic extracts of botanicals, herbs, and spices, bitters are used in small dashes to add aromatic complexity and balance to cocktails. Professional bars and discerning home enthusiasts increasingly use diverse bitter varieties to differentiate their drinks.
- Fruit Juices:Natural or concentrated fruit extracts form the high-volume base for many classic cocktails, providing acidity, sweetness, and freshness. These are widely consumed in both on-trade and off-trade channels due to their versatility and broad appeal.
- Soda:Carbonated water and flavored sodas serve as essential diluents and add effervescence to mixed drinks, with demand driven by their accessibility and widespread use in simple highball preparations.
Volume sits with Fruit Juices; growth tilts toward Syrups.
Flavor Profile:
The desired taste experience for a mixed drink directly influences the selection of a cocktail mixer's flavor profile.
- Citrus:Characterized by tart and refreshing notes from lemons, limes, oranges, and grapefruits, citrus flavors are fundamental to a vast array of classic and contemporary cocktails. This profile maintains consistent demand across all consumption settings.
- Sweet:Mixers in this category deliver pronounced sugary notes, often derived from fruits, caramel, or vanilla, appealing to consumers who prefer less alcoholic or dessert-like beverages. The at-home mixology segment shows strong demand for diverse sweet options.
- Herbal:This profile includes mixers infused with botanicals like mint, basil, rosemary, or lavender, offering sophisticated and aromatic dimensions to cocktails. Premium bars increasingly feature herbal mixers for unique drink creations.
- Spicy:Mixers with spicy notes from ingredients such as chili, ginger, or black pepper add a piquant kick, catering to adventurous palates seeking bold and innovative flavor experiences.
Citrus flavors account for significant market volume, while spicy profiles are expanding most quickly.
Packaging Type:
Convenience and perceived premium quality significantly influence consumer and trade preferences for cocktail mixer packaging.
- Glass Bottles:These containers are favored for premium and artisanal mixers, preserving product integrity and communicating a high-end aesthetic. Glass bottles dominate the on-trade channel and specialty retail.
- Cans:Aluminum cans are gaining traction for single-serve and ready-to-mix cocktail products due to their portability, recyclability, and protection from light. This format appeals to consumers seeking convenience and outdoor consumption.
- Plastic Containers:Offering durability and lighter weight, plastic containers are common for high-volume, cost-effective mixer products, particularly in the retail segment.
- Pouches:Flexible pouches provide an economical and space-saving packaging solution, often used for concentrated mixes or bulk quantities.
Glass bottles maintain their premium position, with cans seeing a rapid rise in adoption for convenience formats.
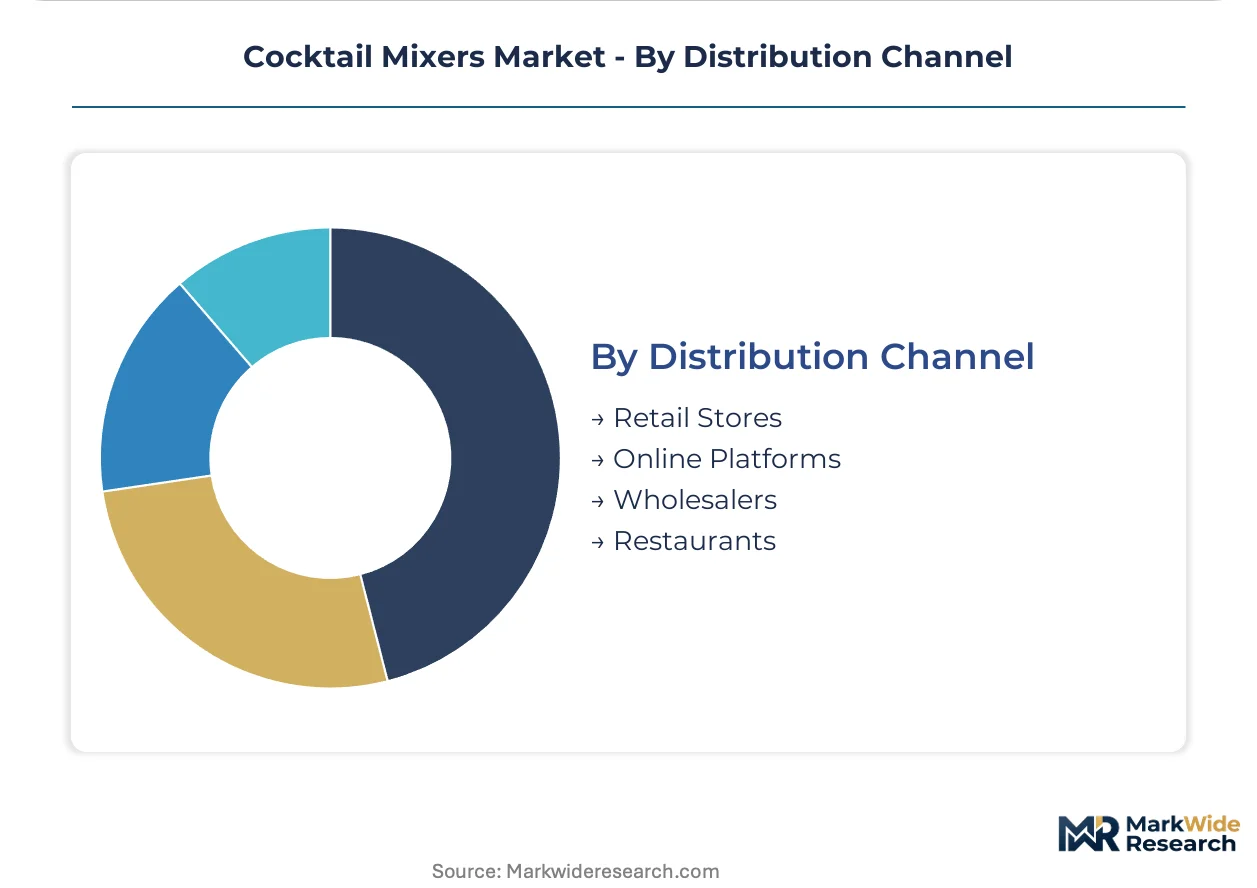
Distribution Channel:
The accessibility and purchasing habits of consumers define the effectiveness of various distribution channels for cocktail mixers.
- Retail Stores:Supermarkets, hypermarkets, and specialty food stores represent the primary sales channel for at-home consumers, offering a wide selection of mixer brands. These stores drive substantial volume for mass-market products.
- Online Platforms:E-commerce websites and direct-to-consumer models provide extensive product ranges and convenient delivery, catering to the expanding at-home mixology segment, particularly in North American and Western European urban centers.
- Wholesalers:These intermediaries supply bulk quantities of cocktail mixers to bars, restaurants, and other hospitality venues, ensuring consistent product availability for the on-trade sector.
- Restaurants:On-premise consumption at restaurants, bars, and hotels creates direct demand for mixers, where quality and consistency are paramount for drink preparation.
Retail stores remain the primary volume channel, while online platforms are experiencing significant expansion due to shifting consumer behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cocktail mixers market exhibits a dynamic geographic landscape, with consumption heavily concentrated in developed urban centers while ingredient sourcing often originates from diverse agricultural regions. This creates a complex interplay between demand pockets and supply chain logistics. Flavor preferences and regulatory frameworks vary significantly across key global markets.
United States
Demand for premium mixers is high among at-home mixologists in urban centers across the United States. The US FDA mandates clear nutritional labeling, including added sugars, directly influencing product reformulation strategies. Major metropolitan areas like New York and Los Angeles drive innovation in artisanal syrup and bitters consumption.
Germany
European consumers prioritize clean-label and low-sugar options for cocktail mixers, particularly in Germany. EFSA regulations dictate strict food safety and allergen declaration standards for all beverage products. Berlin's vibrant bar scene fosters demand for unique herbal and spicy mixer profiles.
India
The FSSAI governs the use of artificial sweeteners and preservatives in mixer products, significantly impacting local formulations in India. Growing disposable incomes in cities like Mumbai and Bangalore fuel demand for sophisticated, non-alcoholic drink options. This expansion aligns with evolving urban lifestyle trends.
Australia
The "sober curious" movement boosts demand for non-alcoholic spirits and complementary mixers across Australia. TGA regulations ensure product quality and safety for all food and beverage items sold in the country. Sydney and Melbourne lead in adopting curated cocktail kits and direct-to-consumer subscription models.
South Korea
Local cocktail culture is expanding in South Korea, increasing the need for diverse flavor profiles and premium ingredients. MFDS enforces stringent food additive and ingredient sourcing rules for imported and domestic products. Seoul's burgeoning mixology scene drives experimentation with unique botanical and fruit-based mixers.
Cocktail Mixers Market Key Industry Players
The competitive structure tilts toward a tiered market, where established beverage giants coexist with nimble artisanal producers. This market exhibits a clear differentiation between mass-market, high-volume offerings and premium, specialized formulations designed for sophisticated palates. Strategic archetypes include large-scale manufacturers leveraging extensive distribution networks and niche players focusing on unique ingredient sourcing and craft production. Dominant competitive moves involve portfolio diversification into adjacent beverage categories and strategic partnerships to expand geographic reach and tap into new consumer segments.
On the premium-tier vector, Fever-Tree exemplifies a brand built on natural ingredients and specialized flavor profiles, catering to discerning consumers seeking high-quality mixers. Monin occupies a position as a versatile provider of an extensive portfolio of syrups and purees, serving both professional bartenders and the expanding at-home mixology segment with its diverse offerings. PepsiCo, as a large-scale manufacturer, represents an archetype focused on broad market penetration through extensive retail presence and leveraging its diverse product lines to capture significant market share.
| Leading Market Players |
|---|
| PepsiCo |
| Britvic |
| Fever-Tree |
| Q Mixers |
| A.G. Barr |
| Keurig Dr Pepper |
| Monin |
| Dabur |
| The Coca-Cola Company |
| Others |
Cost & Logistics Intelligence
The significant differentiation between mass-market and artisanal cocktail mixers dictates divergent pricing strategies and complex, bifurcated supply chain configurations for ingredients.
Pricing Analysis
Margin tightening in mass-market cocktail mixers reflects intense competition and high input cost volatility. Transactional per-unit pricing dominates, with a premium-mid-economy pricing differentiation. Brand premium and natural ingredient sourcing drive higher price points for artisanal products. Agricultural commodity price fluctuations create margin pressure for volume producers. On-trade channels demonstrate lower price sensitivity for unique offerings, while retail consumers remain highly sensitive to entry-level product costs.
Supply Chain Analysis
FSSAI regulations in India, governing artificial sweeteners, reshape local sourcing for specific ingredients. Ingredient sourcing concentrates in agricultural regions like Brazil for fruit purees and Southeast Asia for botanicals. The market relies on stable supplies of cane sugar, fruit concentrates, and specialized botanical extracts. Logistics chokepoints and geopolitical instability introduce significant supply chain risk. Distribution runs through wholesalers for the on-trade channel and retail networks for at-home consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cocktail mixers market is entering a technology-transition phase, with precision formulation software replacing traditional trial-and-error methods for product development.
For Market Incumbents:To counter the threat of artisanal brands capturing premium market share, large manufacturers should diversify their portfolios with niche flavor profiles and expand their clean-label offerings. This involves strategic acquisitions of smaller, innovative brands or in-house development of specialized product lines. Investing in advanced precision formulation software represents a crucial R&D area to shorten product development cycles and ensure consistent product quality.
For New Entrants and Emerging Players:Capture white-space growth in underpenetrated Asia-Pacific markets like Australia and South Korea by introducing non-alcoholic mixer lines tailored to local tastes. The "sober curious" consumer base represents a highly penetrable segment for innovative, low-sugar formulations with natural ingredients. Direct-to-consumer subscription models offer a compelling go-to-market angle to build brand loyalty and recurring revenue among at-home mixologists.
For Investors and Strategic Acquirers:Re-rating potential sits with mid-cap specialists given the accelerating consumer shift towards clean-label and premium offerings across global urban centers. Long-term viability hinges on brands that can consistently deliver authentic taste experiences with transparent ingredient lists and sustainable sourcing. Acquisition targets should prioritize companies with strong intellectual property in natural sweeteners or unique botanical sourcing capabilities. The sustained growth of at-home mixology in urban centers serves as a key inflection indicator for investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Non-Alcoholic Mixers | Addresses the growing "sober curious" consumer base and expands the addressable market for beverage companies. |
| Investment in Precision Formulation Software | Accelerates R&D cycles and ensures consistent flavor profiles for complex natural ingredient blends. |
| Geographic Expansion into Asia-Pacific | Taps into nascent cocktail cultures in markets like South Korea, leveraging evolving urban lifestyle trends. |
| Direct-to-Consumer Subscription Model Launch | Builds recurring revenue streams and fosters brand loyalty among engaged at-home mixologists in North America. |
| Strategic Acquisition of Craft Mixer Brands | Secures unique flavor profiles and natural ingredient supply chains, enhancing premium market positioning. |
Research Approach
Document review covered trade publications, regulatory filings from the US FDA and EFSA, and company annual reports, complemented by interviews with industry stakeholders. Conversations included brand managers, R&D directors, procurement specialists, and hospitality venue owners. Secondary validation drew from market intelligence platforms, customs data for ingredient flows, and academic research on consumer trends. This approach ensured robust bottom-up and top-down triangulation of market data points.
The quantitative model produced granular volume and value projections across the analysis window. Segmentation dimensions modeled included product type, flavor profile, packaging, distribution channel, and regional consumption patterns. Compound annual growth rates were derived from historical data trends and projected shifts in consumer preferences and regulatory landscapes. Key industry-specific inputs included raw material price forecasts and new product launch pipelines.
The model holds under current consumer health consciousness and stable agricultural commodity prices; deviation in global supply chain stability or regulatory enforcement would shift market trajectories. Forecasts reflect documented assumptions regarding market dynamics and competitive responses. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Champagne Market