
 Cider Market | 2026-2036
Cider Market Size, Share, and Industry Trends Forecast 2026-2036
Cider Market Intelligence
The shift toward organic and artisanal ciders is redrawing the competitive landscape. Heineken N.V. leverages its extensive distribution network to introduce premium cider brands to new markets. In contrast, The Boston Beer Company Inc. differentiates through its focus on innovative flavored ciders and seasonal offerings. C and C Group Plc sustains its strong position in core European markets like Ireland and the United Kingdom through established brand loyalty.
Cider is an alcoholic beverage produced from the fermented juice of apples, with some variations using pears. Its production involves crushing fruit for juice, which is then fermented with yeast, resulting in alcohol content typically ranging from 1.2% to 8.5% ABV. Among product types, flavored ciders are expanding rapidly, particularly with younger consumers. The on-trade distribution channel is crucial for brand building, while off-trade channels account for the majority of sales volume.
Alcoholic beverage regulations, enforced by agencies like the US Alcohol and Tobacco Tax and Trade Bureau (TTB) and through EU directives, govern labeling, advertising, and taxation. These rules directly influence production costs and market access for cider manufacturers in key regions like the United States and Germany. Producers must continually balance investments in traditional apple varieties against the development of novel fruit and flavor combinations to capture shifting consumer tastes.
Market Dynamics
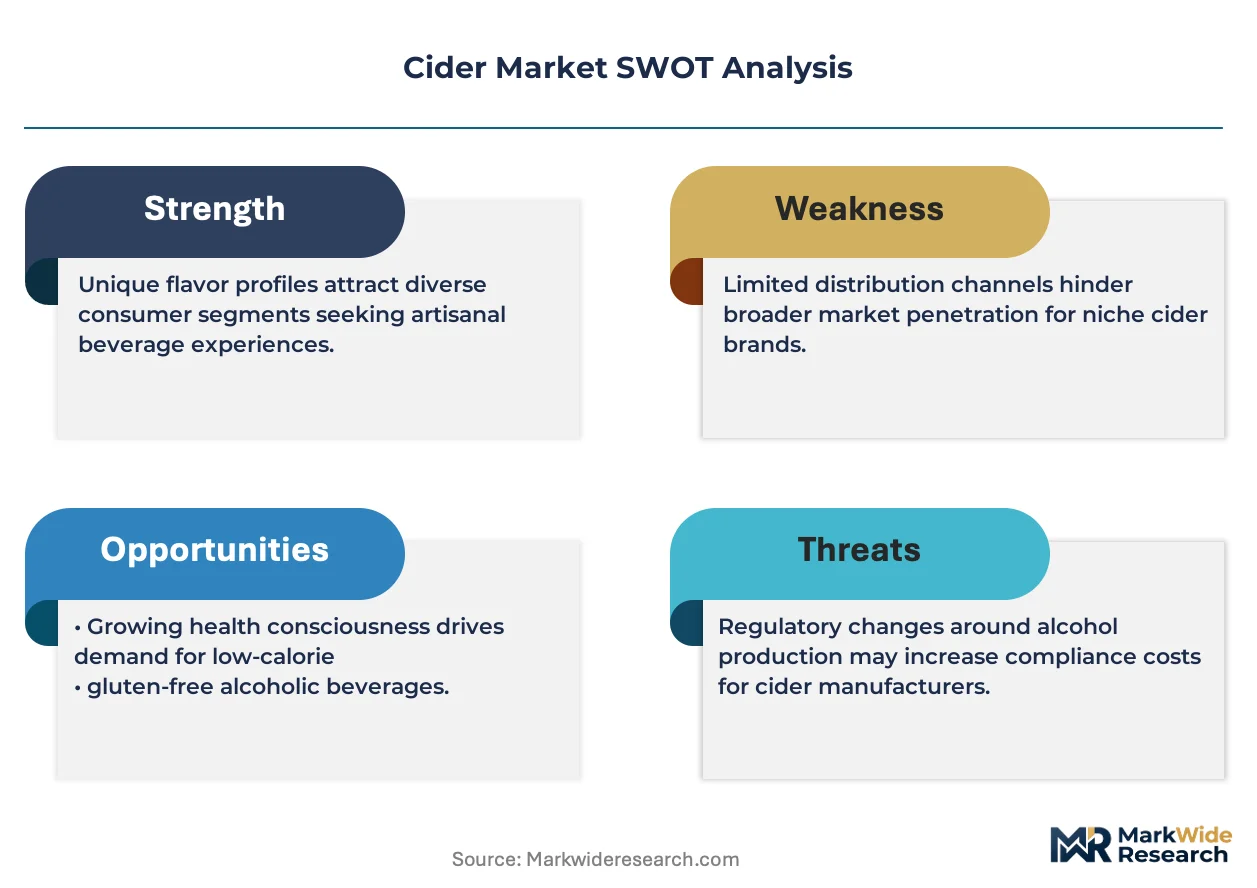
The cider market's evolution is defined by the consumer pivot towards low-alcohol options. This shift creates tension with traditional production, forcing innovation within a tightening regulatory framework for beverage labeling.
Growth Catalysts
- Regulatory Clarity:EU labeling rules for low-alcohol drinks establish a formal market category, spurring product development for health-conscious consumers.
- Artisanal Demand:The US craft beverage movement expands consumer preference for locally sourced, artisanal ciders, creating a premium niche.
- Process Innovation:Advanced fermentation allows production of flavorful low-ABV ciders, addressing the consumer wellness trend.
Market Restraints
- Input Volatility:Production costs are tied to the agricultural volatility of specific apple varieties, susceptible to climate events.
- Regulatory Complexity:Disparate tax and labeling laws from agencies like the US TTB and in the EU increase compliance costs for producers.
- Substitution Pressure:Hard seltzers and canned cocktails directly compete for the same consumer demographic and retail shelf space.
Strategic Opportunities
- Geographic Expansion:Asia-Pacific markets like Japan offer growth potential due to rising interest in Western alcoholic beverages and low current cider penetration.
- Channel Innovation:Direct-to-consumer subscription models enable craft cideries to bypass traditional distribution and build direct customer relationships.
- Product Diversification:Developing adjacent products like artisanal cider vinegars or culinary glazes leverages brand equity and raw material supply.
Industry Challenges
- Supply Chain Consistency:Securing a consistent supply of heritage apple varieties, not widely cultivated at industrial scale, remains a primary operational hurdle.
- Market Saturation:Differentiating a brand is difficult in markets like the UK and US, crowded with large producers and numerous craft cideries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cider Market |
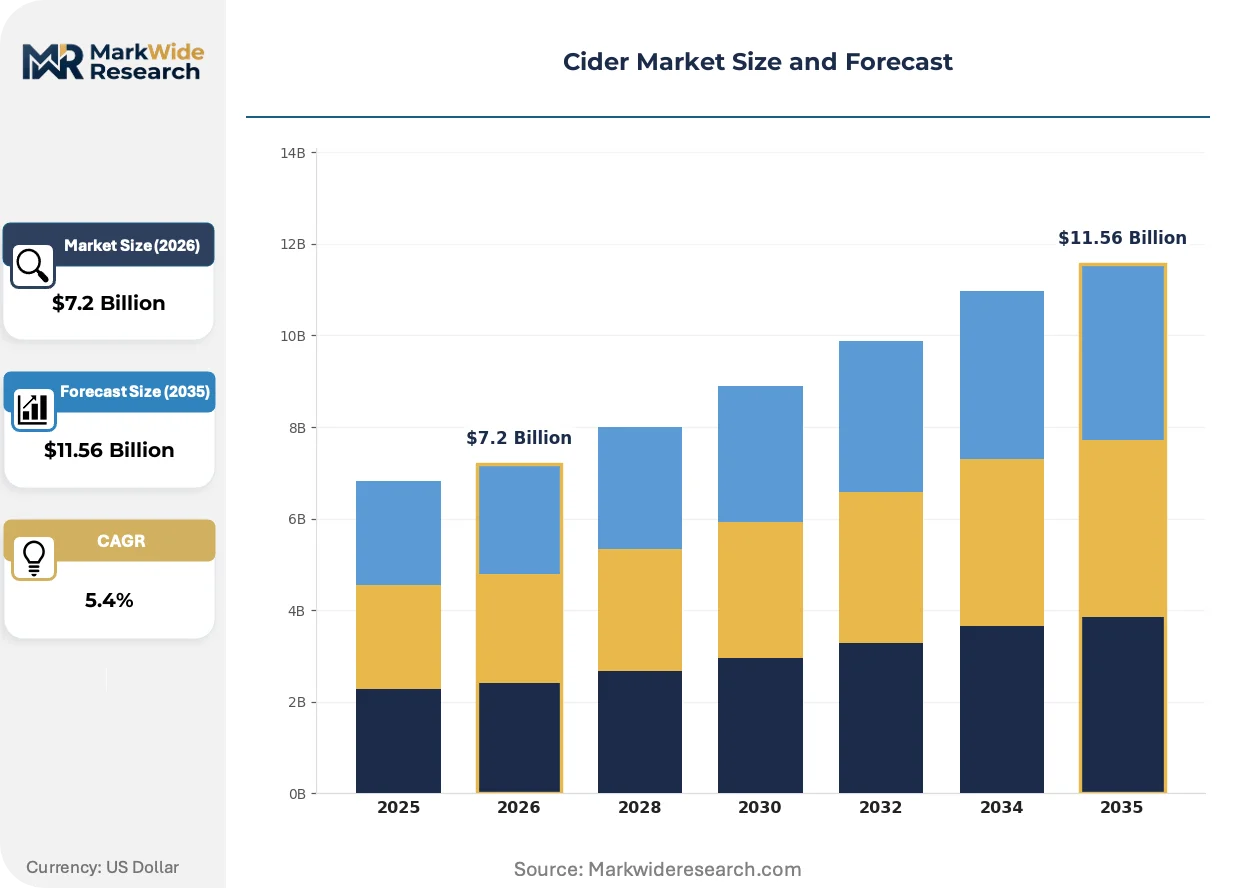
| Market Size in 2026 | $7.2 Billion |
| Market Size in 2035 | $11.56 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Cider, Sweet Cider, Flavored Cider, Ice Cider, Organic Cider Packaging Type: Bottle, Can, Keg, Carton, Plastic Bottle Distribution Channel: On-Trade, Off-Trade, E-Commerce, Direct Sales, Wholesale Consumer Age Group: 18-24, 25-34, 35-44, 45-54, 55 Plus |
| Companies Covered | SABMiller Plc, Molson Coors Beverage Co., Heineken N.V., The Boston Beer Company Inc., Diageo plc, Anheuser-Busch InBev, C and C Group Plc, Halewood Wines & Spirits, Carlsberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cider Market Strategic Shifts & Innovations
Product innovation is moving the cider category beyond traditional apple profiles. This evolution centers on creating distinct consumer experiences through novel flavors and production transparency to capture a wider demographic.
Precision fermentation technology allows for exact control over sugar conversion and alcohol levels. Craft producers and large beverage companies alike are adopting these methods to develop complex, consistent flavor profiles in flavored and low-alcohol ciders. This technological adoption is bifurcating the market into traditional, orchard-focused ciders and highly engineered, flavor-forward beverage creations.
European Union regulations for Protected Designation of Origin (PDO) status in regions like Normandy, France, create a legally defined premium tier. This framework links product identity to geography, providing a marketing tool and justification for premium pricing. Producers in these zones gain an advantage, while others must develop alternative signals of quality.
Consumer preference is shifting toward experiential venues like on-site taprooms and dedicated cider houses. This trend disrupts the on-trade channel by prioritizing direct engagement, diminishing the role of third-party distributors for craft brands. The movement is most visible in North American and UK urban centers where craft culture supports destination-based business models.
Cider Market Segmentation
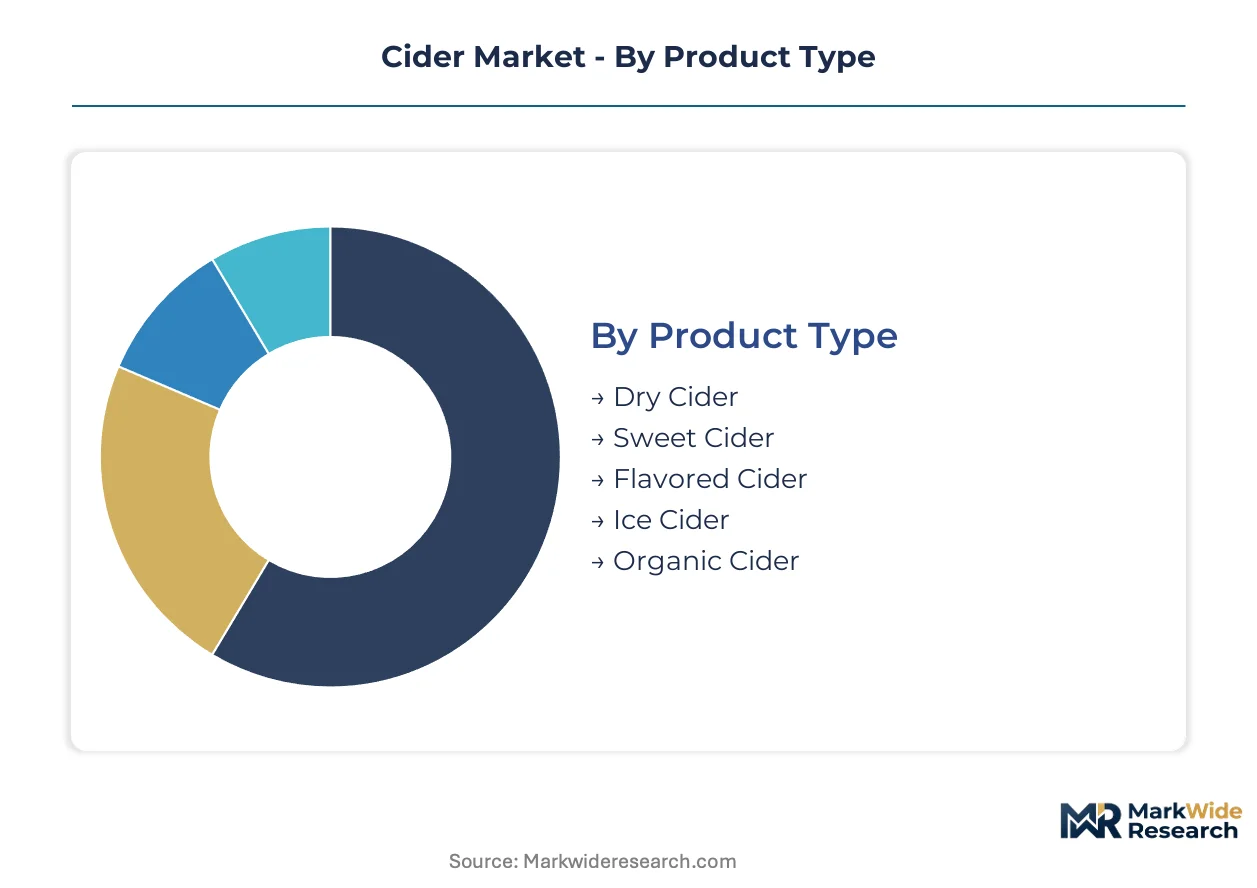
Understanding the cider market's segmentation reveals the diverse consumer preferences and strategic pathways for producers. This granular view helps manufacturers tailor product development and distribution strategies to specific demographic and behavioral groups. Segmentation also highlights areas susceptible to competitive pressure from substitute beverages.
Product Type:
The product type segmentation highlights intense substitution pressure from hard seltzers and other ready-to-drink alcoholic beverages, particularly for novel flavor profiles.
- Flavored Cider:Flavored ciders incorporate fruit essences, spices, or other natural extracts beyond apple, creating diverse taste profiles. Demand concentrates among younger consumers in the United States, driven by a preference for experimental and less traditional alcoholic options.
- Organic Cider:Organic ciders are produced from apples grown without synthetic pesticides or fertilizers, adhering to certified organic farming standards. Consumer demand for organic options is concentrated in European markets like Germany, driven by health consciousness and environmental sustainability concerns.
- Dry Cider:Dry cider features minimal residual sugar, offering a crisp, tart profile favored by traditional cider drinkers.
- Sweet Cider:Sweet cider retains higher levels of residual sugar, providing a richer, fruit-forward taste appealing to a broader palate.
- Ice Cider:Ice cider is made from apples naturally or artificially frozen to concentrate sugars, resulting in a dessert-style beverage.
Dry Cider anchors the volume base while Flavored Cider gains share at the steepest rate.
Packaging Type:
Packaging type segmentation primarily reflects consumer convenience and specific channel requirements for cider distribution.
- Can:Aluminum cans provide a lightweight, portable, and recyclable packaging solution, protecting cider from light degradation. Demand for canned cider concentrates in outdoor consumption settings and for grab-and-go retail, particularly across North American markets.
- Keg:Kegs are large, pressurized containers designed for bulk storage and dispensing, primarily in on-premise establishments. On-trade venues in the United Kingdom drive demand for kegged cider, offering draught options and reducing individual packaging waste.
- Bottle:Glass bottles remain a traditional packaging choice, often associated with premium and artisanal cider varieties.
- Carton:Cartons offer a lightweight, cost-effective packaging option, particularly for multi-packs or value-oriented cider products.
- Plastic Bottle:Plastic bottles provide a shatterproof and lighter alternative, finding use in certain event venues or budget segments.
The preference for Can packaging is expanding most quickly due to its portability, while Bottle packaging sustains its traditional market presence.
Distribution Channel:
Distribution channel segmentation reveals distinct margin profiles and strategic brand-building opportunities for cider producers.
- Off-Trade:Off-trade channels encompass retail outlets such as supermarkets, liquor stores, and convenience stores, where cider is purchased for consumption elsewhere. This channel accounts for the majority of sales volume across European and North American markets, driven by consumer convenience and price sensitivity.
- On-Trade:On-trade channels include bars, restaurants, and pubs, where cider is consumed on-premise, often as part of a social experience. Brand building and premium product introductions occur significantly through on-trade establishments in the United Kingdom, influencing consumer perception.
- E-Commerce:E-Commerce platforms facilitate online sales and home delivery, providing convenience and wider product selection for consumers.
- Direct Sales:Direct sales channels involve cideries selling directly to consumers, often through taprooms or farm stands, fostering brand loyalty.
- Wholesale:Wholesale distribution involves selling large quantities to intermediaries who then supply various retail and on-trade establishments.
Off-Trade channels continue to capture the largest sales volume, while E-Commerce is climbing the fastest with digital-native consumers.
Consumer Age Group:
Consumer age group segmentation highlights varying preferences for cider styles, flavor profiles, and alcoholic content across demographics.
- 25-34:This demographic segment comprises young adults establishing consumption habits, often open to new experiences and product innovations. Demand concentrates for flavored and low-ABV ciders among this group in urban centers of the United States, seeking diverse beverage options.
- 55 Plus:The 55 Plus age group typically exhibits established preferences, often favoring traditional or familiar cider styles. Traditional dry ciders and heritage apple varieties see steady demand from this segment in rural European regions, valuing authenticity and quality.
- 18-24:The 18-24 age group shows interest in experimental flavors and social consumption, often influenced by peer trends.
- 35-44:Consumers aged 35-44 balance traditional preferences with an openness to premium and craft cider offerings.
- 45-54:The 45-54 age group often seeks consistent quality and established brands, sometimes preferring ciders with moderate alcohol content.
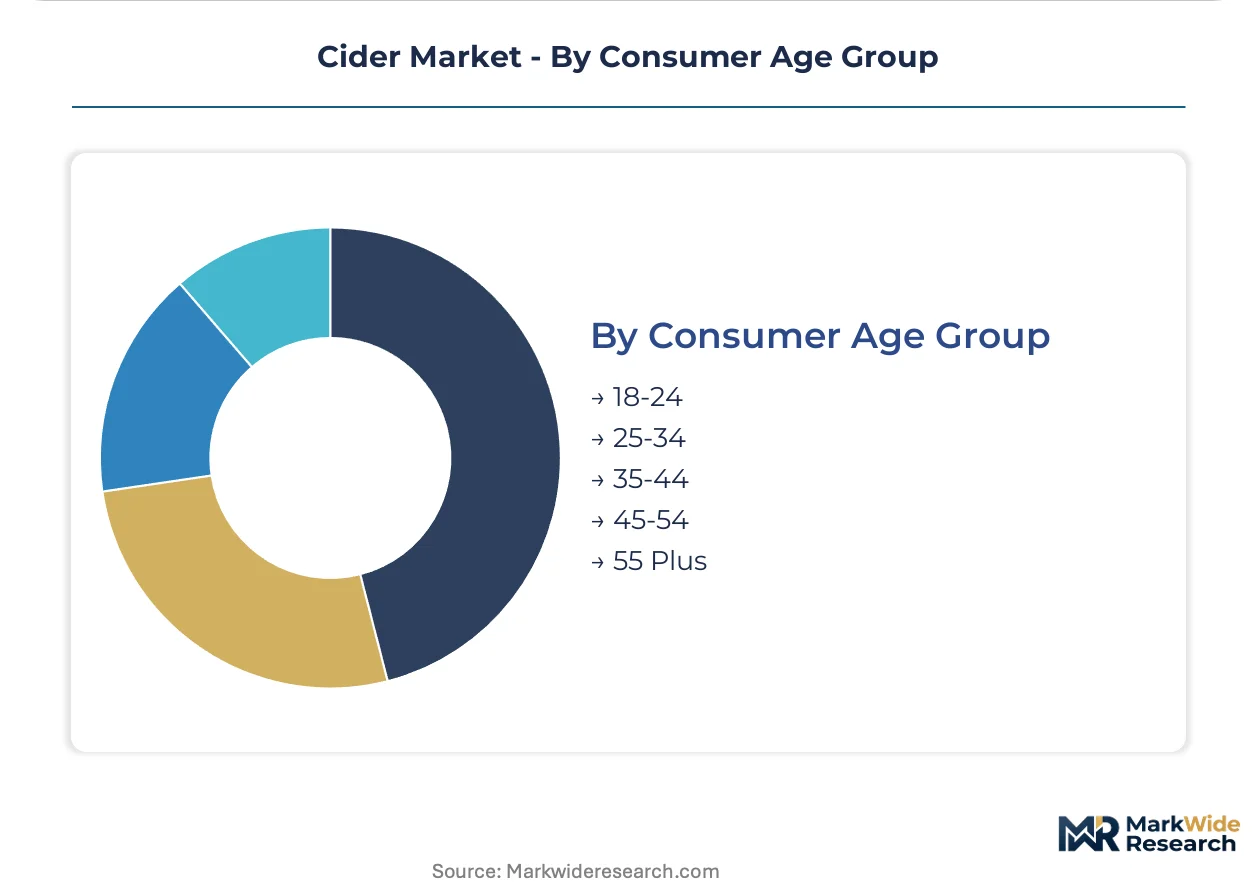
The 25-34 age group is driving the steepest expansion trajectory for novel cider products, while the 45-54 group maintains stable demand for established brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cider market sees diverse regional trade flows, with established producers often exporting to emerging consumer bases. While some countries maintain strong domestic production, others rely on imports to meet growing demand for specific cider styles. This dynamic shapes investment in local apple varieties and distribution networks.
United States
Demand for craft and flavored ciders drives market expansion, particularly among younger consumers. The US Alcohol and Tobacco Tax and Trade Bureau (TTB) regulates labeling and taxation for all cider producers. Craft cideries in the Pacific Northwest and New England are innovating with local apple varieties and unique flavor profiles.
United Kingdom
Established brand loyalty and on-trade consumption sustain the market for traditional ciders. EU directives, even post-Brexit, influence product standards and import regulations for ciders entering the UK. Traditional apple-growing regions like Herefordshire and Somerset remain centers of production and heritage cider.
Germany
Health-conscious consumers propel demand for organic and low-alcohol options, aligning with broader wellness trends. German food and beverage regulations, including those for organic certification, guide product development and market claims. Frankfurt and its surrounding Hessian region are known for traditional Apfelwein production and consumption.
Japan
Rising interest in Western alcoholic beverages expands the consumer base for imported premium ciders. Japan's national food safety standards and import regulations govern market entry for international brands. Tokyo's urban centers show increasing demand for premium and imported cider varieties, often consumed in on-trade settings.
France
Protected Designation of Origin (PDO) status elevates premium cider recognition and ensures quality. French agricultural policies support local apple cultivation and traditional cider-making methods. Normandy, a historic cider-producing region, benefits from its strong geographical indication and tourism, driving specialized production.
Cider Market Key Industry Players
Listed leaders compete with private specialists across distribution reach and product innovation. The market exhibits a tiered structure, from global beverage conglomerates to regional craft producers. Large players leverage extensive distribution networks for broad market penetration and brand visibility. Smaller, agile companies often focus on niche segments, emphasizing artisanal quality or unique flavor profiles. Portfolio diversification and strategic partnerships are dominant competitive moves shaping the competitive dynamics.
Global beverage conglomerates like Heineken N.V. anchor the market's premium segment through extensive distribution capabilities. North American-based innovators such as The Boston Beer Company Inc. exemplify a focus on innovative flavored ciders and seasonal offerings. C and C Group Plc occupies a strong position in core European markets, demonstrating sustained brand loyalty in regions like Ireland and the United Kingdom. These players represent distinct strategies for market capture and consumer engagement.
| Leading Market Players |
|---|
| SABMiller Plc |
| Molson Coors Beverage Co. |
| Heineken N.V. |
| The Boston Beer Company Inc. |
| Diageo plc |
| Anheuser-Busch InBev |
| C and C Group Plc |
| Halewood Wines & Spirits |
| Carlsberg Group |
| Others |
Cost & Logistics Intelligence
Protected Designation of Origin (PDO) status in regions like Normandy gates both supply qualification for premium ciders and enables price differentiation for certified products. This framework influences market access and consumer perception across European markets.
Pricing Analysis
Industrial OEM buyers anchor the pricing structure for bulk juice, but consumer-facing pricing stratifies across premium, standard, and economy tiers for finished cider. Quality grade, particularly for heritage apple varieties, and brand premium are key differentiation drivers. Pricing softness in the standard segment stems from substitution pressure from hard seltzers. Younger consumers (25-34) for novel flavored ciders exhibit lower price sensitivity compared to off-trade general consumers.
Supply Chain Analysis
Inventory management for specific apple varieties requires careful planning due to agricultural seasonality and climate event exposure. Supply concentrates in traditional apple-growing regions such as Herefordshire in the UK and Normandy in France. Raw material dependencies include specific heritage apple varieties and specialized yeast strains. Agricultural volatility of specific apple varieties due to climate events represents a primary supply chain risk. Distribution runs through a hybrid model, with off-trade channels dominating volume and on-trade for brand building.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cider market is an early-cycle expansion story, with growth justified by a consumer pivot towards low-alcohol beverage options. This trend creates opportunities for both established players and new entrants to capture market share.
For Market Incumbents:Consolidate extensive distribution networks to counter substitution pressure from hard seltzers. Invest in precision fermentation technology to develop consistent, complex flavor profiles for low-ABV ciders. Leverage existing brand equity to introduce new product categories, mitigating margin pressure from intense competition. Expand into emerging Asia-Pacific markets, utilizing established supply chain infrastructure.
For New Entrants and Emerging Players:Certification fast-tracks for organic or locally sourced ingredients provide a credible entry point into health-conscious European markets. Target younger consumers (18-34) in urban centers of the United States with innovative flavored and low-ABV ciders. A direct-to-consumer subscription model offers a cost-effective go-to-market angle, bypassing traditional distribution hurdles. Focus on unique flavor combinations and transparent production stories to differentiate from larger producers.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting in an upward direction across the craft cidery sub-segment, driven by taproom investments. The market demonstrates sustained growth over the next decade, making craft cideries with strong regional brand loyalty attractive acquisition targets. These targets often possess unique heritage apple sourcing programs or innovative flavor portfolios. The expansion of on-site taprooms and dedicated cider houses is a key signal to watch, indicating strong direct consumer engagement and brand building.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Diversification | Developing adjacent products like artisanal cider vinegars leverages brand equity and raw material supply. |
| Geographic Expansion | Entering Asia-Pacific markets like Japan taps into rising interest in Western alcoholic beverages. |
| Channel Innovation | Implementing direct-to-consumer subscription models builds direct customer relationships for craft brands. |
| Precision Fermentation Investment | Adopting advanced fermentation technology enables consistent, complex flavor profiles in low-ABV ciders. |
| Heritage Apple Sourcing Programs | Securing consistent supply of traditional apple varieties differentiates premium and organic cider offerings. |
Research Approach
Desk research of industry association reports, government agricultural statistics, and trade publications preceded structured interviews with cider producers, distribution channel managers, retail buyers, and regulatory experts. This approach combines primary insights with secondary validation, employing both bottom-up and top-down triangulation techniques for robust data analysis.
Variance decomposition analysis informed the analytical framework for market projections over the projection horizon. The framework segmented the market by product type, packaging type, distribution channel, consumer age group, and regional market. Compound annual growth rates were derived from historical trend analysis and future market drivers. Key industry-specific forecast inputs included apple harvest yields and evolving regulatory changes like EU labeling rules.
Underlying assumptions cover stable economic conditions and consistent consumer trends, with deviation risk concentrated in agricultural volatility and unforeseen regulatory shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
North America Tequila Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Japan Alcohol E-Commerce Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Germany Wine Coolers Market