
 Mini Brew Fermenter Market | 2026-2036
Mini Brew Fermenter Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Brew Fermenter Market Foresight
North American stainless steel fabrication capacity is rewriting supply dynamics for precision brewing equipment. Ss Brewtech leverages vertical integration into temperature-control component manufacturing to protect margin pools on conical units. Spike Brewing anchors its position through geographic concentration in Wisconsin's metalworking corridor, while Blichmann Engineering differentiates via R&D intensity in modular valve and sampling port configurations.
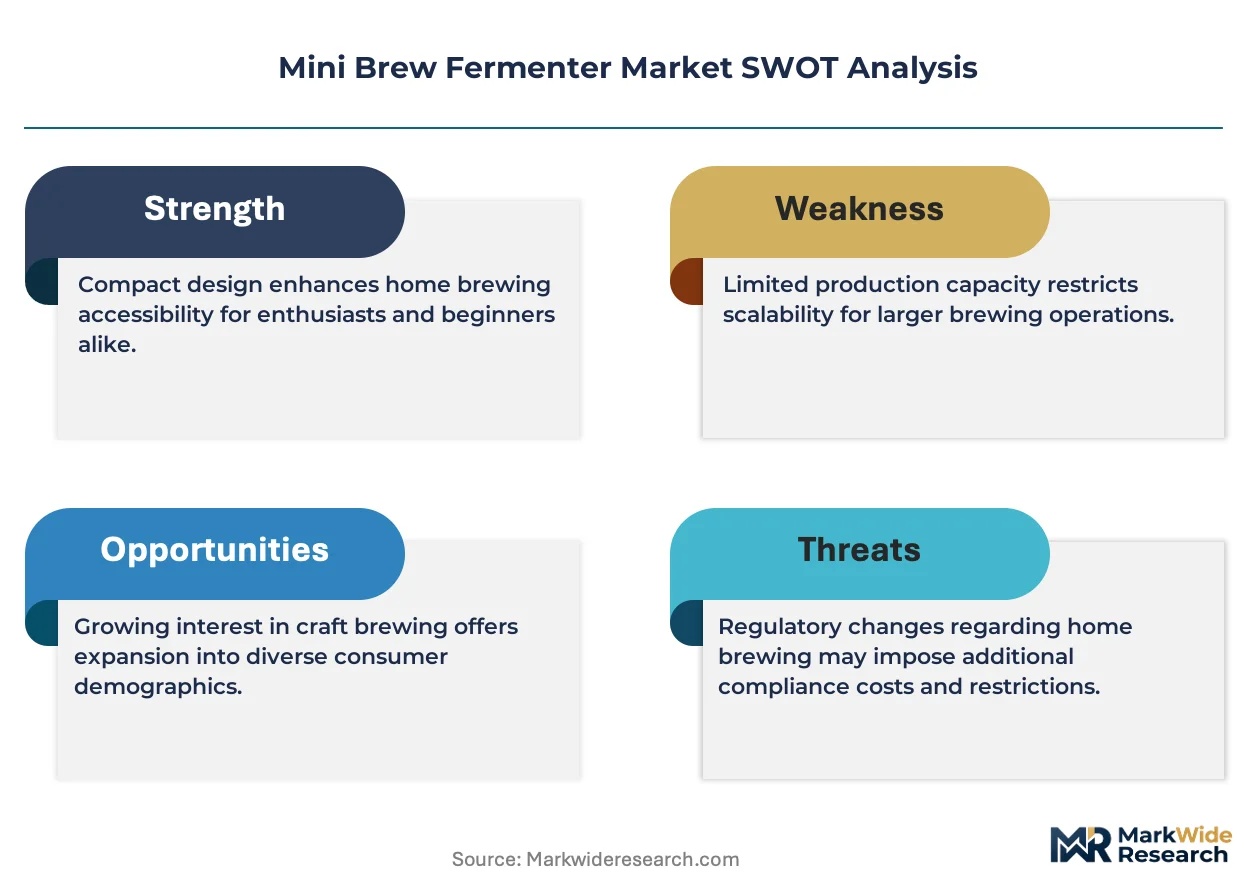
A mini brew fermenter is a scaled fermentation vessel, typically constructed from 304-grade stainless steel, borosilicate glass, or food-safe polyethylene, designed to maintain controlled temperature, pressure, and yeast activity for batches under fifteen gallons. Stainless steel conical fermenters now command the premium tier due to oxygen exclusion durability and clean-in-place compatibility, while glass variants retain share among home brewers prioritizing visual monitoring. Five-gallon capacity units represent the volume anchor across North American retail channels, though ten-gallon configurations are gaining traction in commercial prototyping applications where recipe iteration frequency justifies larger pilot batches.
FDA food-contact surface standards and NSF International certification requirements shape material selection and welding protocol compliance across domestic manufacturers. The EPA's Clean Water Act discharge stipulations influence cleaning chemistry choices and effluent handling accessories bundled with commercial-grade systems. Stakeholders must monitor evolving state-level brewery wastewater regulations and decide whether to engineer compliant drainage integrations directly into fermenter base designs or partner with third-party filtration equipment suppliers.
Market Dynamics
Stainless steel fabrication capacity concentration in Wisconsin and Colorado is compressing lead times for conical units while forcing smaller fabricators toward specialty glass and polyethylene niches. FDA food-contact surface standards are now the primary filter for supplier qualification, not just product certification.
Growth Catalysts
- REACH compliance migration:European craft breweries are replacing legacy equipment to meet evolving EU chemical safety standards for food-contact surfaces, creating replacement demand for certified stainless systems.
- Homebrewing-to-commercial pipeline:Five-gallon home units are serving as trial platforms that accelerate commercial pilot-batch adoption in metropolitan brewing clusters across the United States.
- Clean-in-place automation:Automated CIP compatibility is reducing labor costs for microbreweries running high-frequency recipe iteration cycles.
Market Restraints
- 304-grade stainless volatility:Nickel price swings are compressing margins for mid-tier fabricators without captive raw material agreements.
- Welding certification scarcity:AWS D18.1-qualified orbital welders concentrate in Wisconsin and Pennsylvania, creating geographic supply bottlenecks.
- Polyethylene substitution ceiling:Oxygen permeability limits in plastic fermenters block adoption beyond homebrew segments despite lower unit costs.
Strategic Opportunities
- Indian craft beer emergence:FSSAI food-grade equipment standards are stabilizing, opening import channels for NSF-certified conical systems in Bangalore and Mumbai microbrewery clusters.
- Modular sampling port convergence:Integration of pressure-rated sampling valves with temperature telemetry is enabling real-time gravity monitoring without vessel breach.
- Direct-to-brewery e-commerce:Manufacturer-owned digital channels are bypassing traditional industrial equipment distributors in North American metropolitan markets.
Industry Challenges
- NSF/ANSI 2 certification timelines:Third-party validation cycles are extending product launch windows by four to six months for new vessel configurations.
- Legacy glycol chiller incompatibility:Temperature control integration with existing brewery infrastructure requires custom jacket plumbing that fragments installation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Brew Fermenter Market |
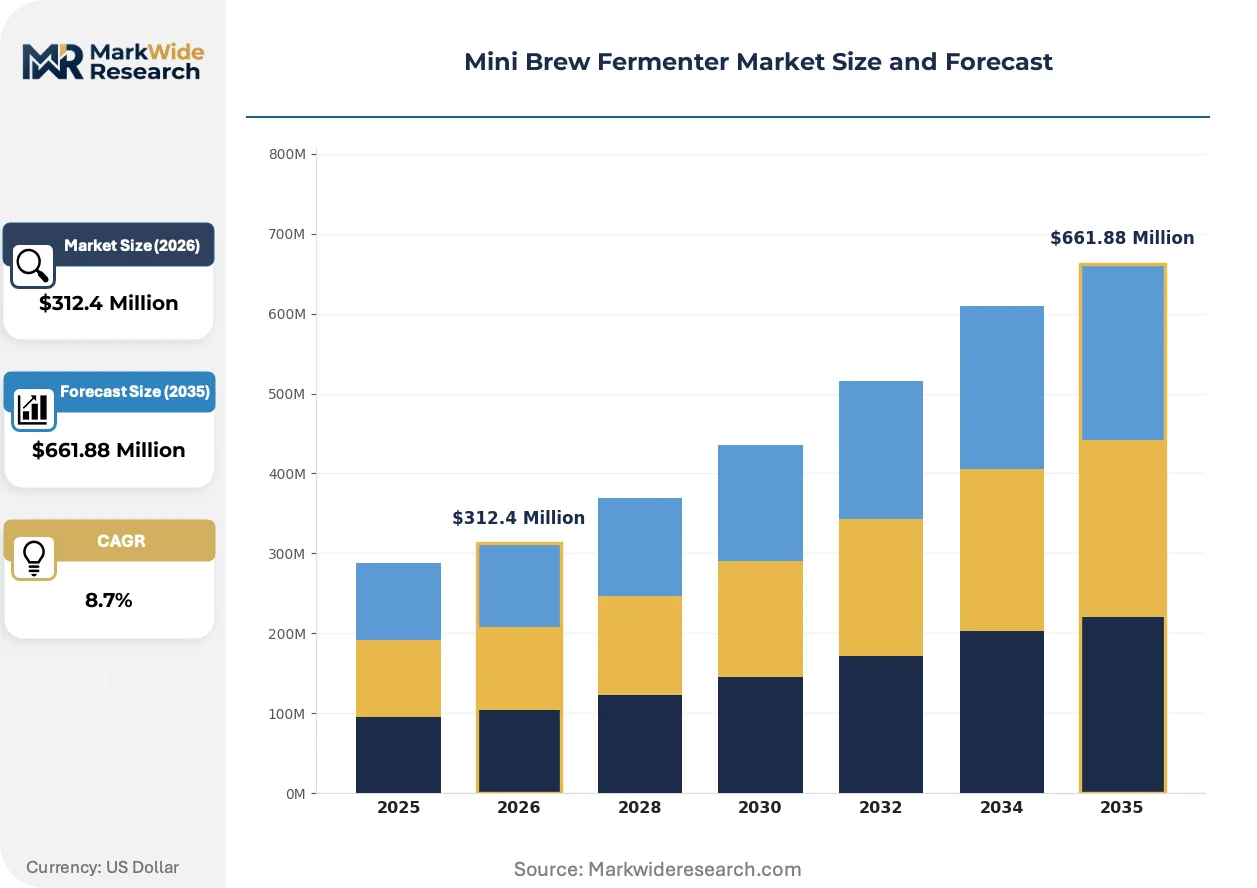
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel Fermenters, Glass Fermenters, Plastic Fermenters, Conical Fermenters Capacity: 1 Gallon, 5 Gallon, 10 Gallon, 15 Gallon Application: Home Brewing, Commercial Brewing, Experimental Brewing, Prototyping Material: Stainless Steel, Polyethylene, Glass, Silicone |
| Companies Covered | Grainfather, Catalyst Fermentation System, Ss Brewtech, Midwest Supplies, Northern Brewer, Blichmann Engineering, Anvil Brewing, MoreBeer!, Spike Brewing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Brew Fermenter Market Shifts & Advancements
Active temperature control systems are converging with pressure-rated vessel designs to enable closed-loop fermentation management. Fabricators are racing to integrate these capabilities without sacrificing clean-in-place accessibility.
Precision glycol-jacketed fermenters are hybridizing with IoT-enabled temperature logging to enable remote monitoring of pilot batches. Craft breweries in Denver and Portland are adopting these systems at twice the rate of traditional thermowell configurations. This convergence is compressing the acceptable response window for temperature excursions from hours to minutes, raising the technical bar for entry-level suppliers.
The EPA's Clean Water Act discharge stipulations are tightening effluent handling requirements for commercial brewing operations. Brewery wastewater now requires pre-treatment before municipal discharge in most US jurisdictions. Stainless fabricators are responding by engineering compliant drainage integrations directly into fermenter base designs rather than relying on third-party filtration add-ons.
Buying patterns among microbreweries are rotating toward specification-driven direct procurement rather than distributor-mediated equipment selection. Brewers in Chicago and Milwaukee are now sourcing conical units through manufacturer digital platforms that expose welding certifications and material traceability documentation. This channel shift is disintermediating traditional industrial supply houses that previously controlled specification influence.
Mini Brew Fermenter Market Segmentation
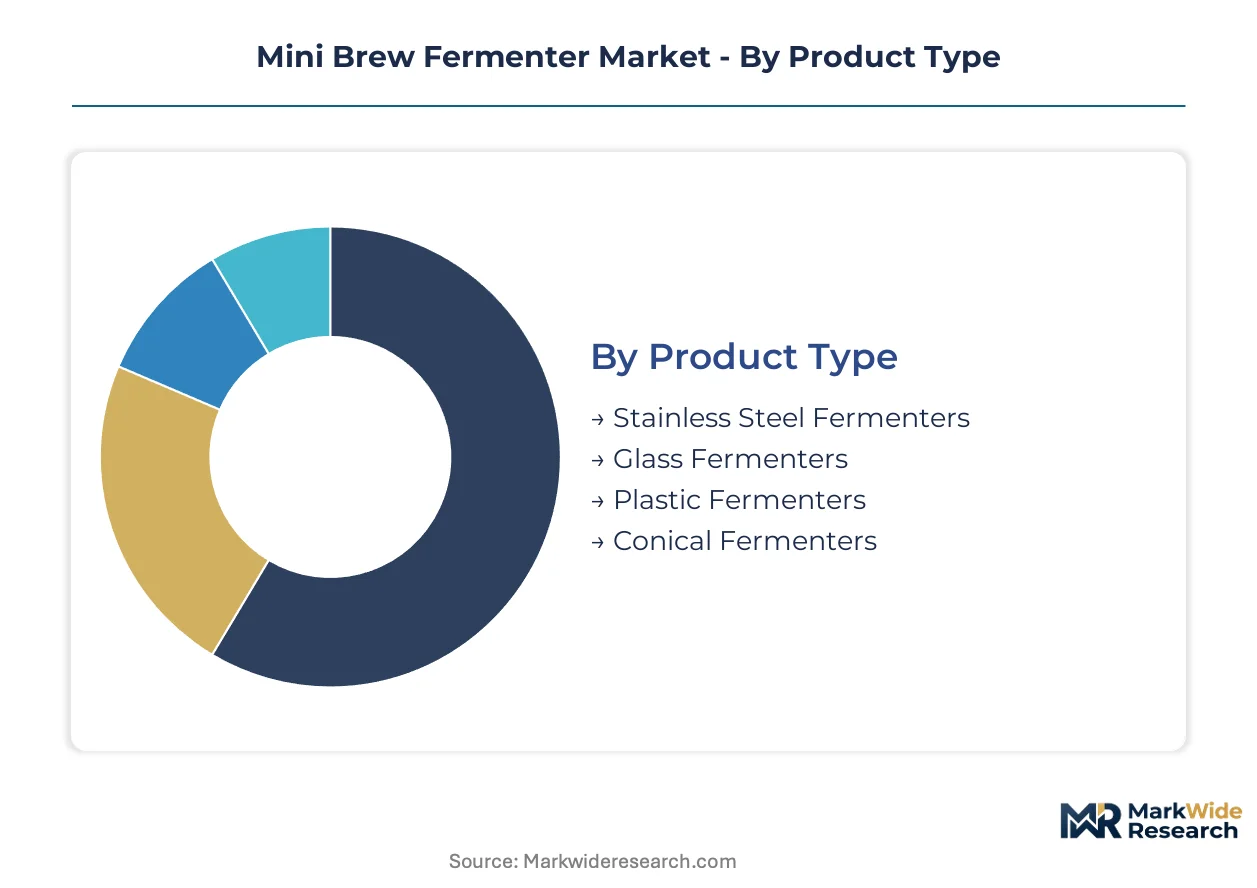
Mini brew fermenter procurement patterns diverge sharply across use cases, with after-sales service intensity varying from minimal home-user support to intensive commercial maintenance contracts. Equipment specification complexity escalates with batch volume and regulatory exposure, forcing manufacturers to architect distinct service architectures for each segment tier.
Product Type:
After-sales service intensity peaks with stainless steel conical units requiring weld inspection and seal replacement protocols, while glass and plastic variants demand minimal field support.
- Stainless Steel Fermenters:304-grade construction with orbital-welded seams dominates professional installations. FDA food-contact surface compliance drives replacement cycles in Germany and United States craft brewery clusters where pilot-batch programs require precision temperature control.
- Glass Fermenters:Borosilicate construction enables visual monitoring of yeast activity and krausen formation. Home brewers in Portland and Denver metropolitan areas favor these units for recipe development despite thermal shock fragility constraints.
- Plastic Fermenters:Food-safe polyethylene offers lightweight portability for entry-level home brewing segments. Oxygen permeability limitations restrict commercial adoption regardless of cost advantage.
- Conical Fermenters:Geometric design enables yeast harvesting and trub separation without vessel breach. Clean-in-place compatibility commands premium positioning in microbrewery prototyping workflows.
By volume, plastic fermenters lead. By growth pace, stainless steel conical configurations are climbing the fastest.
Capacity:
Cost tier stratification separates hobbyist one-gallon units from commercial fifteen-gallon systems requiring glycol chiller integration and pressure-rated jacket plumbing.
- 1 Gallon:Entry-tier vessels serve experimental recipe validation with minimal capital commitment. Urban apartment dwellers in Chicago and Milwaukee drive replacement demand through rapid iteration cycles.
- 5 Gallon:Retail anchor capacity bridges home brewing and commercial pilot applications. NSF certification requirements differentiate professional-grade units from consumer variants in this segment.
- 10 Gallon:Microbrewery prototyping standard enables recipe scale-up testing without full production commitment. Denver craft breweries adopt these units at twice the rate of smaller metropolitan markets.
- 15 Gallon:Maximum mini-class capacity supports commercial pilot batches with full temperature control infrastructure. Lead times extend for custom jacket configurations matching existing glycol systems.
Five-gallon units dominate unit shipments. Ten-gallon configurations show steepest expansion trajectory among commercial adopters.
Application:
Customer type determines specification rigor, with home brewers prioritizing visual access and commercial operators demanding automated clean-in-place compatibility.
- Home Brewing:Enthusiast segment values ease of cleaning and storage footprint over precision control. Glass visibility and plastic affordability split demand in North American retail channels.
- Commercial Brewing:Microbrewery operations require material traceability documentation and welding certification disclosure. Direct procurement through manufacturer digital platforms is displacing distributor relationships in this segment.
- Experimental Brewing:Recipe innovation workflows demand rapid vessel turnaround and cross-contamination prevention. Modular sampling port configurations command premium positioning here.
- Prototyping:Pilot-batch programs in Portland and Chicago metropolitan clusters drive specification-driven procurement with emphasis on temperature telemetry integration.
Home brewing anchors volume. Commercial prototyping applications are gaining share fastest as craft brewery expansion accelerates.
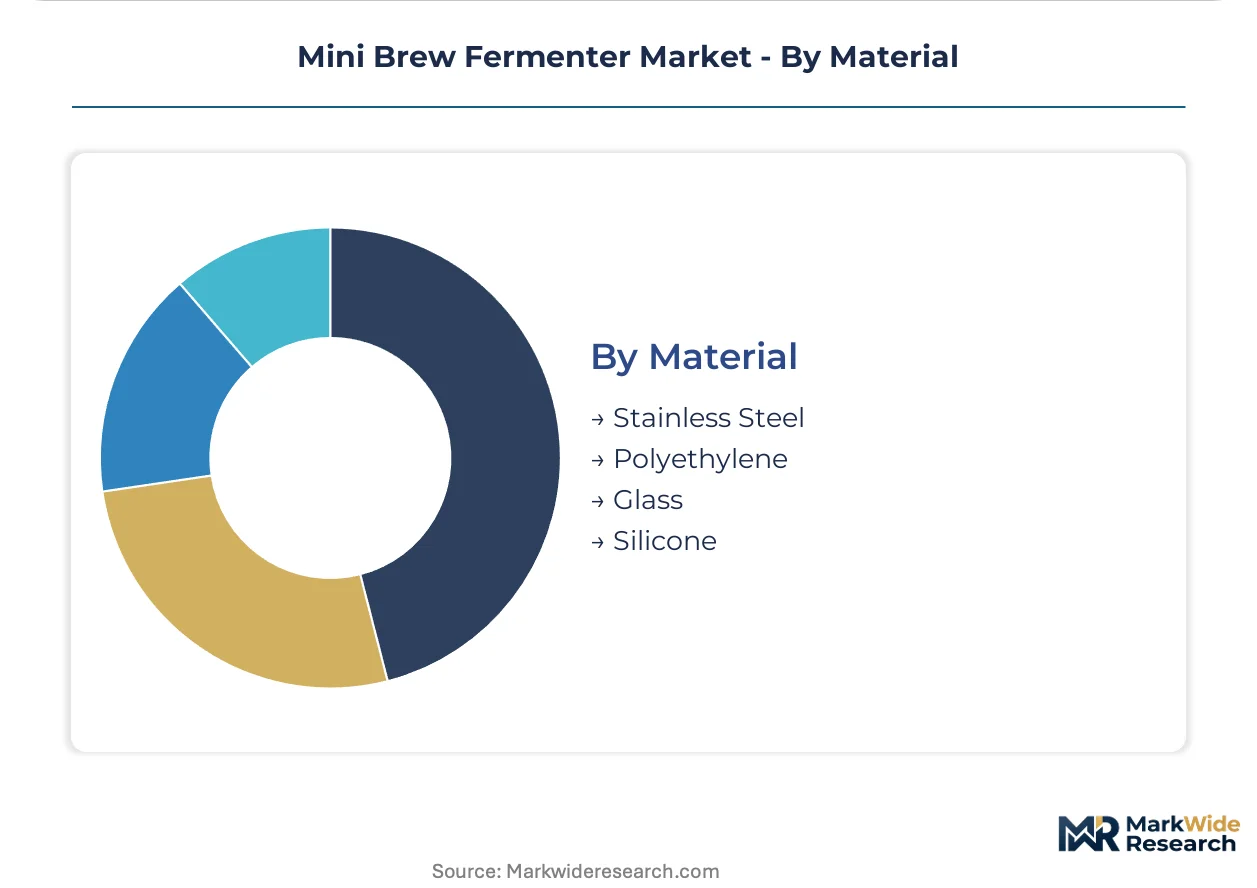
Material:
Supply concentration in Wisconsin and Colorado metalworking corridors advantages domestic stainless fabricators over imported alternatives.
- Stainless Steel:304-grade dominance reflects FDA food-contact surface regulation compliance and clean-in-place durability. Nickel price volatility compresses margins for fabricators without captive raw material agreements.
- Polyethylene:Rotomolded construction serves cost-sensitive home brewing segments with oxygen permeability trade-offs. Replacement cycles accelerate due to scratching and bacterial harboring risks.
- Glass:Borosilicate thermal shock resistance enables temperature swing tolerance for experimental brewing. Breakage rates elevate total cost of ownership despite lower initial acquisition cost.
- Silicone:Gasket and seal applications require platinum-cured formulations for food-contact compliance. Component sourcing concentrates with specialized medical-grade suppliers.
Stainless steel commands value share. Silicone component demand is expanding most quickly with pressure-rated vessel proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters in Wisconsin and Colorado metalworking corridors are compressing lead times for North American buyers while REACH compliance migration in Europe creates replacement demand cycles. Metropolitan brewing clusters in Portland, Denver, and Chicago anchor equipment refresh rates through pilot-batch program expansion.
United States
Metropolitan brewing clusters in Portland, Denver, and Chicago drive specification-driven procurement for stainless steel conical units with clean-in-place compatibility. FDA food-contact surface standards and NSF International certification requirements shape domestic welding protocols and material traceability documentation. Wisconsin's metalworking corridor concentrates AWS D18.1-qualified orbital welders, creating geographic supply advantages for regional fabricators.
Germany
REACH compliance migration is accelerating replacement cycles for legacy equipment across Bavaria and North Rhine-Westphalia craft brewery clusters. ECHA chemical safety standards for food-contact surfaces now filter supplier qualification beyond product certification alone. Munich-based pilot-batch programs are scaling precision-controlled fermentation vessel procurement to meet evolving EU regulatory frameworks.
India
FSSAI food-grade equipment standards are stabilizing, opening import channels for NSF-certified conical systems in Bangalore and Mumbai microbrewery clusters. The country's national food safety regulator is harmonizing certification requirements with international benchmarks. Maharashtra and Karnataka state brewing associations are driving equipment specification education among emerging craft operators.
Australia
Home brewing enthusiast segments in Melbourne and Sydney metropolitan areas sustain demand for glass and polyethylene entry-tier units. The country's national food standards code governs commercial brewing equipment compliance through state-level enforcement. Victoria's craft brewery expansion is creating secondary demand for ten-gallon prototyping configurations with temperature telemetry integration.
Canada
Health Canada food-contact surface guidelines align with FDA standards, enabling cross-border certification efficiency for US fabricators. Ontario and Quebec microbrewery clusters are adopting direct-to-brewery procurement channels that bypass traditional industrial distributors. Toronto's pilot-batch innovation cycles are driving specification complexity toward modular sampling port configurations.
Mini Brew Fermenter Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in temperature control and valve assemblies. The vendor base organizes around three strategic archetypes: vertically integrated stainless fabricators with captive metalworking capacity, modular system assemblers sourcing certified subcomponents, and direct-to-consumer equipment retailers with private-label sourcing relationships. Competitive moves concentrate on backward integration into glycol chiller compatibility engineering and geographic expansion into Indian and Australian emerging craft markets.
Among North American fabricators, Ss Brewtech exemplifies the vertically integrated archetype through upstream control over temperature-control component manufacturing. Spike Brewing anchors the Wisconsin metalworking corridor concentration, while Blichmann Engineering occupies a position within the R&D-intensive modular configuration tier. These three entities represent distinct competitive vectors: captive supply chain control, geographic fabrication clustering, and sampling port innovation specialization.
| Leading Market Players |
|---|
| Grainfather |
| Catalyst Fermentation System |
| Ss Brewtech |
| Midwest Supplies |
| Northern Brewer |
| Blichmann Engineering |
| Anvil Brewing |
| MoreBeer! |
| Spike Brewing |
| Others |
Supply & Pricing Matrix
The Great Lakes freight corridor's steel transport cost dynamics compress margin pools for Wisconsin fabricators while amplifying price differentiation between domestic orbital-welded units and imported alternatives. Supply concentration in this metalworking belt enables captive sourcing advantages that downstream buyers in Chicago and Milwaukee exploit through specification-driven direct procurement.
Pricing Analysis
FDA food-contact surface standards dictate the pricing tier structure across stainless steel conical units, separating NSF-certified professional-grade systems from uncertified consumer variants. Three-tier pricing structure across premium, standard, and economy levels reflects welding certification grade, material traceability documentation depth, and clean-in-place automation integration. Cost compression in mid-tier polyethylene alternatives is intensifying because oxygen permeability limitations block commercial adoption despite lower acquisition costs. Home brewing enthusiasts exhibit highest price sensitivity, while commercial microbreweries prioritize certification compliance over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates with specialized stainless fabricators in Wisconsin, Colorado, and Pennsylvania metalworking corridors holding AWS D18.1-qualified orbital welding capacity. Raw material flows draw from 304-grade stainless suppliers, nickel alloy processors, and platinum-cured silicone gasket specialists. Single-source vulnerability concentrates in orbital welding certification scarcity, where qualified technicians cluster geographically and command premium labor rates. Distribution runs through manufacturer-owned digital channels disintermediating traditional industrial equipment distributors in North American metropolitan brewing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among specification-driven microbreweries running high-frequency pilot-batch programs, fragmenting traditional distributor influence and forcing manufacturers toward direct engagement models.
For Market Incumbents: Build certification moats through accelerated NSF/ANSI 2 validation pipelines that extend competitor launch windows by four to six months. Anchor capacity in Wisconsin's metalworking corridor to capture geographic welding certification scarcity. Defend against polyethylene substitution threats by engineering pressure-rated sampling port configurations that plastic alternatives cannot replicate. Prioritize backward integration into temperature-control component manufacturing to protect margin pools on glycol-jacketed systems. For New Entrants and Emerging Players: Indian craft brewery clusters in Bangalore and Mumbai represent the most penetrable entry point as FSSAI standards harmonize with international benchmarks. Ten-gallon prototyping configurations with modular sampling ports offer white-space positioning between home brewing and full commercial scale. Direct-to-brewery e-commerce platforms bypass entrenched distributor relationships in North American metropolitan markets. Target experimental brewing workflows where rapid vessel turnaround demands exceed incumbent service bandwidth. For Investors and Strategic Acquirers: R&D-intensive modular configuration specialists with proprietary sampling valve and telemetry integration capabilities offer prime acquisition positioning. Long-term viability hinges on clean-in-place automation penetration rates across craft brewery expansion cycles. Monitor Indian import channel development and state-level brewery wastewater regulation tightening as inflection indicators for equipment specification complexity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Temperature Control Components | Ss Brewtech's captive glycol chiller engineering protects margin pools on conical units. |
| Geographic Concentration in Metalworking Corridors | Spike Brewing's Wisconsin anchoring compresses lead times through AWS D18.1 welder proximity. |
| Modular Sampling Port Convergence | Blichmann Engineering's pressure-rated valve integration enables real-time gravity monitoring without vessel breach. |
| Direct-to-Brewery E-Commerce Channel | Manufacturer-owned platforms disintermediate industrial distributors in Portland and Denver clusters. |
| NSF Certification Acceleration Program | Compressed validation cycles extend competitor product launch windows by four to six months. |
Research Methodology
The analysis maps stainless steel conical, glass, and polyethylene fermenter sub-sectors, each validated through craft brewery operations managers, equipment procurement leads, AWS-certified orbital welders, and aftermarket service technicians. Primary interviews with these stakeholders combined with secondary validation from FDA food-contact surface guidance documents, NSF International certification registries, EPA Clean Water Act discharge stipulations, and customs import data for brewing equipment. Bottom-up vessel shipment tracking and top-down craft brewery capital expenditure analysis provided triangulation anchors.
Fixed assumptions across the analysis window include sustained FDA food-contact surface compliance stringency and continued REACH migration in European craft brewery clusters. Segmentation dimensions modeled encompass material grade tier, capacity configuration, application type across home and commercial brewing, and regional regulatory framework. CAGRs derived from weighted average of historical replacement cycle analysis and projected pilot-batch program expansion rates. Nickel price volatility coefficients and welding certification labor supply constraints fed industry-specific forecast sensitivity testing.
Practitioners should monitor nickel alloy price swings, AWS D18.1 certification pipeline throughput, and Indian FSSAI import standard harmonization progress for early signals of forecast revision necessity. Quarterly review of state-level brewery wastewater regulation adoption rates and metropolitan brewing cluster equipment refresh cycles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
West Africa Alcoholic Beverages Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Portable Keg System Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Australia and New Zealand Tequila Market