
 Uganda Spirits Market | 2026-2036
Uganda Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Uganda Spirits Market Intelligence
The gap between premium imported labels and locally manufactured commodity spirits is broadening in Uganda. Distell leverages its Southern African supply network to sustain a premium positioning in urban bars and hotels. Uganda Breweries Limited anchors the mass-market segment through extensive distribution across semi-urban outlets and wholesale markets.
Uganda spirits comprise distilled alcoholic beverages typically manufactured through fermentation and column or pot still distillation, with ethanol concentrations ranging from 35% to 50% ABV, serving recreational consumption and social ceremonial purposes. Whiskey and gin categories dominate volume traded through formal channels, while vodka gains traction among younger consumers in Kampala's nightclub circuit. The distribution channel structure reveals urban retailers and wholesale markets capturing the bulk of value, with online platforms emerging as a nascent but fast-growing route for premium-tier purchases.
The Uganda National Bureau of Standards mandates compulsory product certification under UNBS standards, while the Uganda Revenue Authority enforces excise duty stamps that shape pricing architecture and combat illicit trade. The East African Community customs union protocol additionally governs cross-border spirit movements, affecting import competitiveness for Kenyan and Tanzanian products. Stakeholders must monitor evolving excise policy and compliance cost trajectories to calibrate portfolio mix between local production and regional sourcing.
Market Dynamics
UNBS compulsory certification requirements are compressing margins for smaller distillers while concentrating production capacity among Uganda Breweries Limited and a handful of compliant regional operators.
Growth Catalysts
- Central Region consumption clusters:The Kampala-Entebbe-Jinja corridor generates disproportionate volume through urban nightlife venues and hospitality infrastructure.
- EAC customs union protocol:Cross-border tariff harmonization reduces landed costs for Kenyan and Tanzanian inputs, expanding raw material sourcing options.
- Column still efficiency gains:Modern distillation equipment lowers unit production costs for ethanol recovery above 95% purity.
Market Restraints
- Molasses supply volatility:Sugar factory output fluctuations in Jinja and Lugazi create feedstock price instability for domestic distillers.
- Excise stamp compliance costs:Uganda Revenue Authority digital tracking requirements impose per-unit overhead that disadvantages sub-scale producers.
- Illicit spirits substitution:Unregulated waragi from informal stills in rural districts undercuts formal channel pricing by 40-60%.
Strategic Opportunities
- Northern Region underpenetration:Gulu and Lira districts show rising disposable income with minimal premium spirits distribution presence.
- E-commerce direct-to-consumer channels:Jumia and specialized alcohol platforms bypass wholesale markups for urban professional segments.
- Organic certification alignment:EU export standards create premium positioning for cassava-based ethanol with traceable supply chains.
Industry Challenges
- Quality control laboratory capacity:UNBS testing backlog delays product launches by 8-12 weeks for new market entrants.
- Refrigerated logistics gaps:Cold chain deficiencies between Kampala warehousing and upcountry retail limit ready-to-drink product expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uganda Spirits Market |
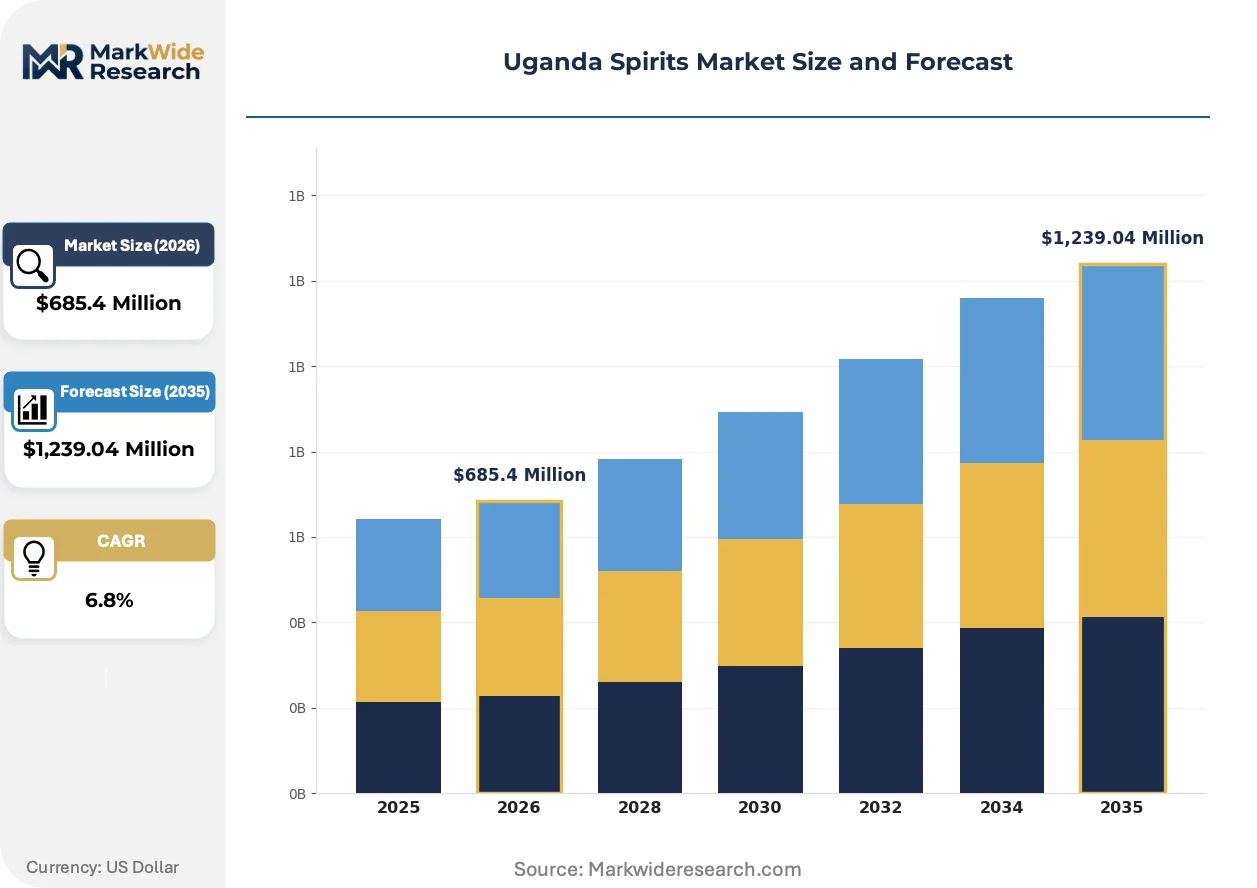
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Gin, Vodka, Rum Distribution Channel: Semi-Urban Outlets, Urban Retailers, Online Platforms, Wholesale Markets Consumer Age Group: 18-24 Years, 25-34 Years, 35-44 Years, 45+ Years Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | Distell, Premier Distilleries Limited, Uganda Breweries Limited, International Distillers Uganda, Kakira Distillery, Leading Distillers (U) Ltd, Africa Spirits Limited, West Nile Distilling, Pernod Ricard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uganda Spirits Market Strategic Shifts & Innovations
Automation and traceability technologies are penetrating Uganda's spirits sector, while regulatory digitization and generational consumption shifts reshape competitive requirements.
Near-infrared spectroscopy is automating real-time ethanol content verification during bottling operations. Uganda Breweries Limited installed inline monitoring systems at its Port Bell facility in 2023. This technology is automating quality assurance throughput while reducing laboratory staffing dependencies.
Uganda Revenue Authority's digital excise stamp system mandates blockchain-linked verification for every 750ml unit. Distillers must integrate track-and-trace hardware into packaging lines or face distribution suspension. Premium importers bear the highest compliance retrofit costs, accelerating informal market leakage for price-sensitive segments.
Kampala's nightclub circuit exhibits rapid flavor-profile rotation, with gin-based cocktails displacing straight whiskey consumption among 25-34 year-olds. On-premise venues in Kololo and Bugolobi now rotate limited-edition botanical infusions quarterly. This pattern concentrates demand volatility in urban hospitality channels while supermarket off-premise sales retain stability.
Uganda Spirits Market Segmentation
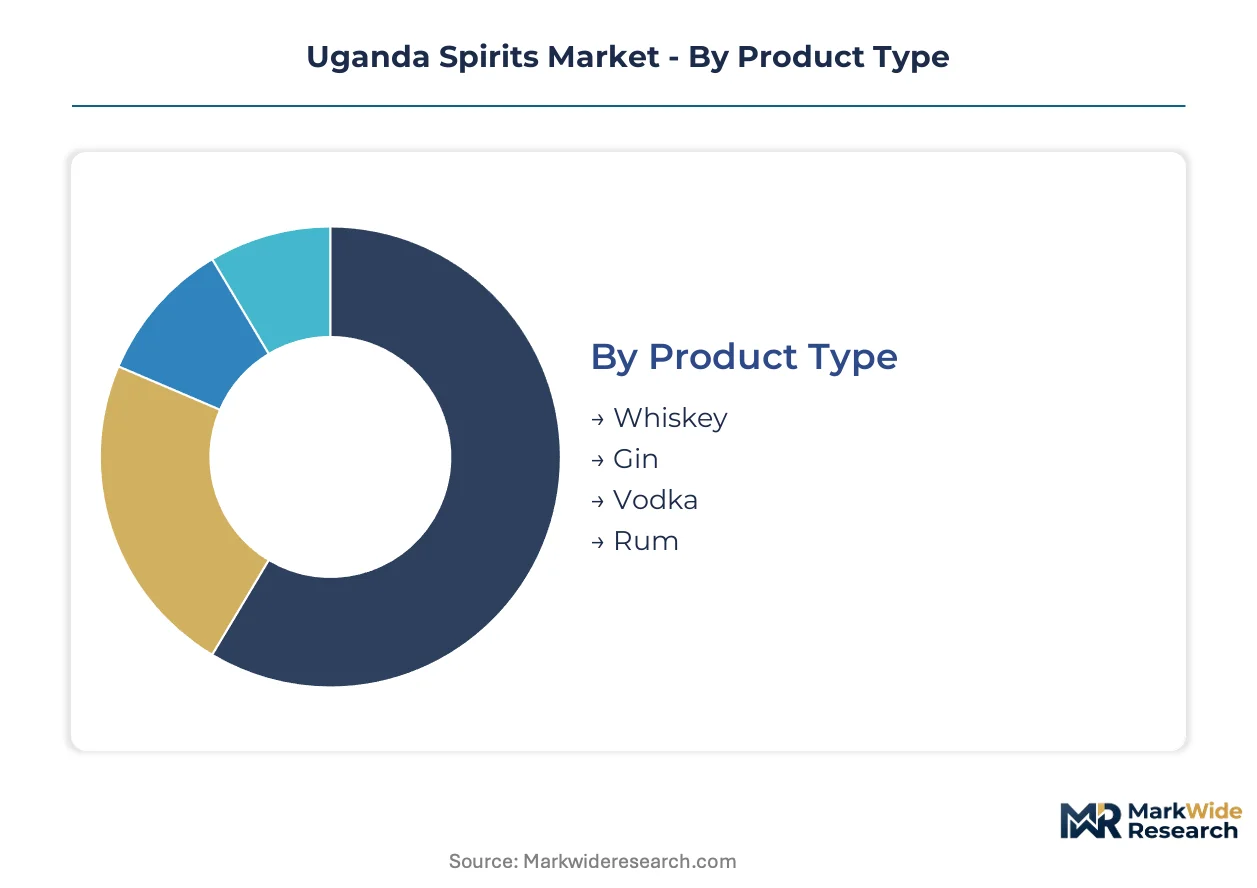
Segmentation in Uganda's spirits sector reveals how consumption patterns fragment across urban-rural divides, generational preferences, and regulatory price tiers. Understanding these divides enables targeted portfolio allocation between mass-market volume plays and premium positioning strategies.
Product Type:
Standardization dominates commodity categories while premium tiers allow botanical and aging customization.
- Whiskey:Oak-barrel aged spirits with 40-50% ABV, produced through malt or grain fermentation followed by pot or column still distillation. Demand concentrates in Kampala's hotel bars and corporate entertainment venues, driven by established brand loyalty among 35-44 year-old professionals. UNBS certification requirements favor established producers with laboratory testing capacity.
- Gin:Juniper-forward neutral spirits with botanical infusions ranging from traditional to experimental profiles. Kololo and Bugolobi nightclubs rotate limited-edition botanical releases quarterly, responding to flavor-profile experimentation among 25-34 year-old urban consumers. Column still efficiency gains lower production costs for neutral spirit bases.
- Vodka:Highly rectified neutral spirits emphasizing purity and mixability.
- Rum:Molasses-based distilled spirits with caramel and tropical flavor associations.
Leading the category by volume: Whiskey. Expanding most quickly: Gin.
Distribution Channel:
Channel selection determines margin capture versus volume throughput across Uganda's fragmented retail landscape.
- Semi-Urban Outlets:Small-format retailers in district towns and trading centers serving rural-urban transition zones. Gulu and Lira districts show rising disposable income with minimal premium spirits distribution infrastructure, creating first-mover opportunities for organized distributors.
- Urban Retailers:Supermarkets, liquor stores, and convenience outlets in Kampala, Entebbe, and Jinja. The Central Region corridor generates disproportionate value through proximity to high-income residential clusters and formal employment centers. Excise stamp compliance costs disadvantage sub-scale operators in this channel.
- Online Platforms:E-commerce direct-to-consumer channels including Jumia and specialized alcohol platforms.
- Wholesale Markets:Bulk distribution hubs serving upcountry retailers and hospitality procurement.
Highest margin capture: Urban Retailers. Steepest expansion trajectory: Online Platforms.
Consumer Age Group:
Generational cohorts diverge sharply in occasion-based consumption and brand discovery patterns.
- 25-34 Years:Urban professionals driving premiumization in on-premise channels. Kampala's nightclub circuit exhibits rapid flavor-profile rotation, with gin-based cocktails displacing straight whiskey consumption. E-commerce adoption bypasses traditional wholesale markups for this segment.
- 35-44 Years:Established earners with brand loyalty and corporate entertainment demand. Hotel bars and hospitality clusters in the Central Region anchor whiskey and premium gin volume for this cohort. Quality certification visibility influences purchase decisions.
- 18-24 Years:Entry-level consumers with price sensitivity and experimental preferences.
- 45+ Years:Traditional consumption patterns with established brand relationships.
Core revenue base: 35-44 Years. Gaining share fastest: 25-34 Years.
Price Tier:
Price stratification aligns with certification compliance costs and raw material sourcing transparency.
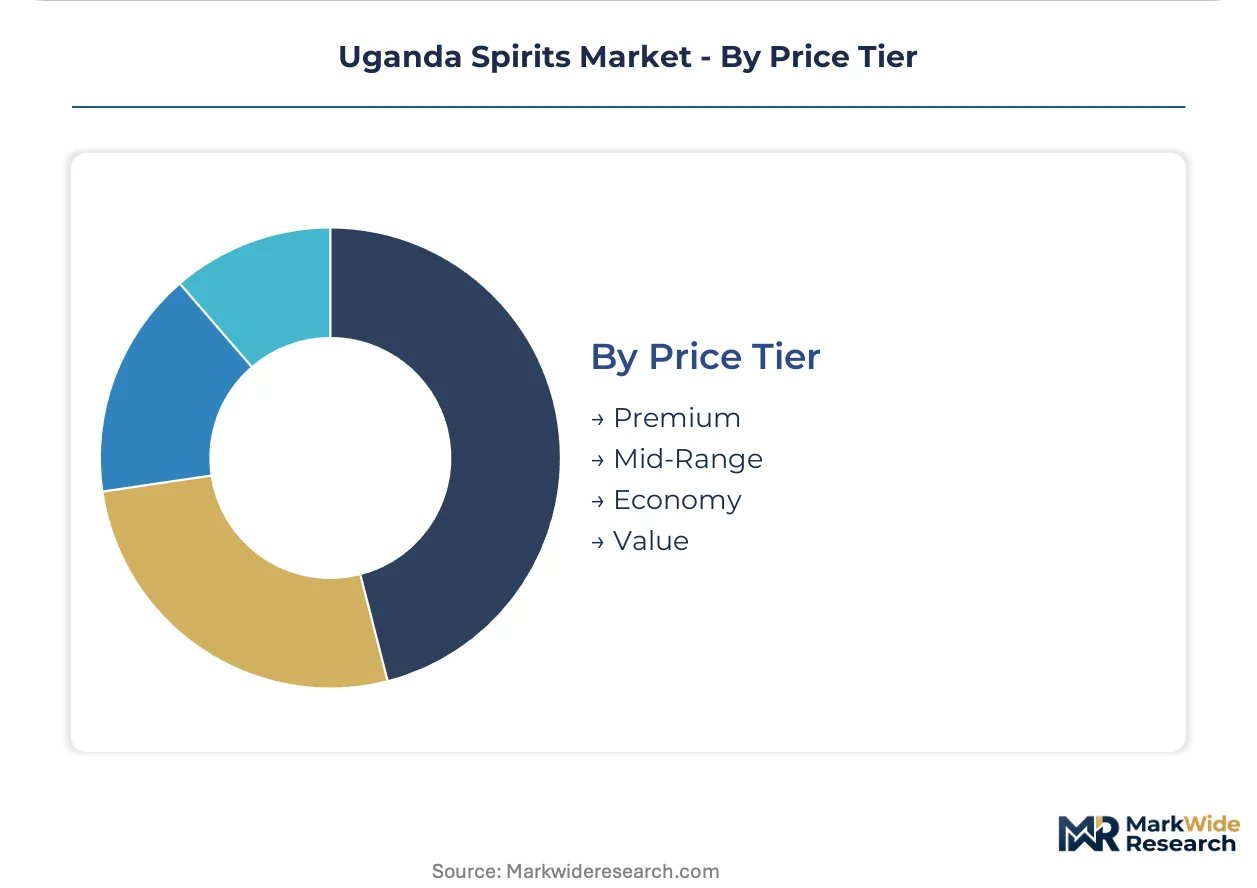
- Premium:Imported and domestically produced spirits with verified provenance, aging claims, and UNBS quality certification. Uganda Revenue Authority digital excise stamp compliance costs accelerate informal market leakage for price-sensitive segments, reinforcing premium tier integrity. Distell leverages Southern African supply networks to sustain positioning in urban bars and hotels.
- Mid-Range:Certified domestic production with moderate aging or botanical differentiation. Uganda Breweries Limited anchors this segment through extensive distribution across semi-urban outlets, balancing compliance scale with accessible pricing.
- Economy:Basic certified spirits prioritizing volume throughput over differentiation.
- Value:Lowest-price formal channel products competing with illicit waragi substitution.
Dominant volume tier: Mid-Range. Climbing the fastest: Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kampala anchors Uganda's spirits consumption through the Central Region corridor linking Entebbe and Jinja, where urban nightlife venues and hospitality infrastructure generate disproportionate volume. The analysis covers sub-regional dynamics across Uganda's five key consumption clusters.
Central Region
Kampala's hotel bars and corporate entertainment venues drive premium whiskey and gin demand among established professionals. Uganda National Bureau of Standards certification requirements favor producers with laboratory testing capacity in this corridor. The Kampala-Entebbe-Jinja triangle concentrates formal channel distribution through organized wholesale networks.
Northern Region
Gulu and Lira districts exhibit rising disposable income with minimal premium spirits distribution infrastructure. Uganda Revenue Authority excise stamp compliance costs disadvantage smaller distributors attempting regional expansion. First-mover opportunities exist for organized distributors targeting this underpenetrated corridor.
Eastern Region
Jinja's sugar factory output fluctuations create molasses feedstock price instability for domestic distillers operating nearby. The country's national standards body enforces compulsory quality certification that compresses margins for smaller operators. Industrial ethanol production clusters around Lugazi and Jinja anchor supply-side capacity.
Western Region
Cassava-based ethanol production offers organic certification alignment for EU export standards with traceable supply chains. Regional sourcing networks face cross-border tariff harmonization under East African Community customs union protocols. Rural districts experience significant illicit waragi substitution pressuring formal channel pricing.
Southwestern Region
Kabale and Mbarara trading centers serve rural-urban transition zones with economy-tier consumption patterns. Cold chain deficiencies between Kampala warehousing and upcountry retail limit ready-to-drink product expansion. Semi-urban outlets capture volume through accessible pricing and established wholesale relationships.
Uganda Spirits Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification compliance and distribution scale dimensions. Uganda Breweries Limited anchors mass-market positioning through extensive semi-urban coverage, while Distell leverages Southern African supply networks for urban premium placement. The competitive structure rewards three archetypes: integrated distillers with UNBS laboratory capacity, regional importers with tariff-optimized sourcing, and niche operators targeting underpenetrated corridors. Capacity consolidation and compliance technology deployment represent the dominant competitive vectors reshaping participant mix.
Among Southern African-linked operators, Distell occupies a position exemplifying premium-tier import positioning through supply network advantages. Uganda Breweries Limited represents the integrated domestic archetype with certification scale and distribution depth. Premier Distilleries Limited sits within the mid-tier certified production segment balancing compliance access with regional reach.
| Leading Market Players |
|---|
| Distell |
| Premier Distilleries Limited |
| Uganda Breweries Limited |
| International Distillers Uganda |
| Kakira Distillery |
| Leading Distillers (U) Ltd |
| Africa Spirits Limited |
| West Nile Distilling |
| Pernod Ricard |
| Others |
Cost & Logistics Intelligence
UNBS organic certification mandates for cassava-based ethanol exports gate qualified supply access and premium-tier pricing power for distillers targeting EU markets. Compliance investment separates certified producers from commodity players, concentrating margin capture among operators with traceable supply chains and laboratory testing capacity.
Pricing Analysis
Yield-based pricing anchors premium whiskey positioning, with aged-stock scarcity commanding disproportionate margin over neutral spirits. Three-tier pricing structure across premium, mid-range, and economy levels stratifies by UNBS certification grade and molasses versus grain feedstock provenance. Cost compression in the economy tier intensifies because illicit waragi substitution erodes formal channel pricing floors. Rural semi-urban outlets exhibit highest price sensitivity, while Kampala hotel bars demonstrate inelastic demand for certified premium labels.
Supply Chain Analysis
Domestic-content rules under the East African Community customs union protocol reshape sourcing toward regional molasses and cassava suppliers. Feedstock concentration centers on Jinja and Lugazi sugar factory corridors for molasses, with Western Region cassava networks expanding for organic ethanol. Single-source vulnerability runs through Kenya and Tanzania cross-border inputs subject to tariff harmonization shifts. Distribution runs through Kampala-anchored wholesale hubs serving upcountry retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy automation is displacing legacy laboratory-based quality verification, compressing launch timelines and reshaping compliance economics for distillers.
For Market Incumbents: Cement certification scale advantages by upgrading Port Bell facility inline monitoring capacity before UNBS testing backlog widens. Prioritize backward integration into Jinja molasses supply contracts to lock feedstock pricing amid sugar factory output volatility. Channel control through exclusive wholesale relationships in the Central Region corridor defends against Kenyan and Tanzanian import encroachment under EAC tariff harmonization.
For New Entrants and Emerging Players: Begin with underpenetrated Northern Region corridors where Gulu and Lira disposable income growth outpaces premium spirits distribution infrastructure. Target e-commerce direct-to-consumer channels for urban professional segments bypassing traditional wholesale markups. A first-mover organic certification play for cassava-based ethanol unlocks EU export pricing premiums unavailable to commodity distillers.
For Investors and Strategic Acquirers: Uganda Revenue Authority digital excise stamp compliance cost spikes are the leading indicator that sub-scale producer distress will accelerate consolidation. Long-term viability favors integrated distillers with captive laboratory capacity and regional distribution depth over pure-play importers facing retrofit overhead. Acquisition targets should demonstrate UNBS certification track record and traceable feedstock sourcing; watch for excise stamp hardware integration delays as margin compression signals.
| Strategic Initiative | Industry Significance |
|---|---|
| UNBS Certification Investment | Compulsory quality certification under Uganda National Bureau of Standards gates formal channel access and premium pricing tiers. |
| Inline Spectroscopy Deployment | Real-time ethanol verification at Port Bell and comparable facilities reduces laboratory staffing dependencies and accelerates batch release. |
| Northern Region Distribution Buildout | First-mover wholesale networks in Gulu and Lira capture rising disposable income ahead of incumbent expansion. |
| Organic Cassava Supply Chain Development | Traceable Western Region sourcing aligns with EU export standards for premium ethanol positioning. |
| Digital Excise Stamp Integration | Uganda Revenue Authority blockchain-linked compliance hardware prevents distribution suspension and informal market leakage. |
Research Approach
Independent corroboration across distillery operations managers, Uganda National Bureau of Standards certification officers, and Kampala hospitality procurement heads underwrites the qualitative findings. Secondary validation draws from Uganda Revenue Authority excise policy documentation, East African Community customs union protocols, and UNBS laboratory capacity disclosures. Bottom-up volume modeling triangulates with top-down macro consumption benchmarks across the Central Region corridor.
Rate-of-change decomposition separates volume growth from pricing dynamics across product type, distribution channel, consumer age cohort, and price tier segmentation. CAGRs derive from trend extrapolation moderated by regulatory inflection points and feedstock cost trajectories. Forecast inputs incorporate molasses supply volatility patterns and digital excise stamp compliance cost curves specific to spirits manufacturing.
Underlying measurement precision varies by segment; premium whiskey and gin categories carry tighter precision than economy-tier commodity spirits due to formal channel data availability. Forecasts reflect assumptions around EAC tariff stability and UNBS certification enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
White Spirits Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Ethanol Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
Home Brew Boiler Market