
 Blackcurrant Seed Oil Market | 2026-2036
Blackcurrant Seed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Blackcurrant Seed Oil Market Analysis
Ingredient-grade oil contracting is reshaping margin distribution across the blackcurrant seed oil value chain. NOW Foods leverages direct agricultural partnerships in Eastern Europe to secure cold-pressed supply chains. Bioriginal Food & Science Corp anchors its position through backward integration into seed crushing and fatty acid profiling laboratories. ConnOils LLC differentiates via specialized organic certification and pharmaceutical-grade filtration capabilities.
Blackcurrant seed oil is a fixed vegetable oil extracted from Ribes nigrum seeds, containing approximately 15-20% gamma-linolenic acid and 12-14% alpha-linolenic acid by weight, valued in cosmetic and nutraceutical applications for its anti-inflammatory and skin-barrier properties. Cold-pressed oil commands premium positioning in cosmetics and dietary supplements due to retained bioactive compounds and minimal thermal degradation. Refined oil occupies volume-driven segments in food industry applications where color stability and neutral flavor predominate. Organic oil certification creates pricing stratification across European and North American distribution channels.
EFSA novel food evaluations and REACH substance registration requirements govern ingredient approval and chemical safety documentation for European market access. FDA GRAS self-affirmation and USDA organic certification shape compliance pathways for US-bound products. Health Canada natural health product licensing adds a third regulatory layer for North American entrants. Stakeholders must monitor evolving organic integrity rules and fatty acid content standardization as procurement criteria tighten across pharmaceutical and cosmetic buyer specifications.
Market Dynamics
REACH substance registration deadlines and EFSA novel food evaluations are compressing ingredient approval timelines, forcing formulators to lock in compliant supply chains eighteen to twenty-four months ahead of production cycles.
Growth Catalysts
- Cosmetic formulator procurement:Premium skincare lines in Germany and France are expanding cold-pressed oil contracting to secure gamma-linolenic acid potency guarantees.
- REACH compliance:European chemical safety documentation requirements are filtering out non-compliant traders, consolidating volume with registered processors.
- Seed crushing technology:Low-temperature screw press advances are improving oil yield without thermal degradation of bioactive compounds.
Market Restraints
- Input cost volatility:Blackcurrant pomace supply fluctuates with juice concentrate harvests in Poland and Ukraine, creating raw material availability mismatches.
- Substitution threat:Evening primrose oil and borage oil compete on gamma-linolenic acid content at lower price points in mass-market nutraceuticals.
- Regulatory friction:Health Canada natural health product licensing timelines extend market entry by fourteen to eighteen months for North American entrants.
Strategic Opportunities
- Pharmaceutical-grade filtration:Supercritical CO2 extraction investment opens prescription dermatology channels requiring endotoxin-free certification.
- USDA organic integrity rules:Updated traceability mandates create first-mover advantage for vertically integrated crushers with in-house organic handling.
- Direct-to-clinic distribution:Functional medicine practitioners in California and New York are bypassing retail for liter-volume therapeutic-grade purchases.
Industry Challenges
- Analytical chemistry capacity:Fatty acid profiling by gas chromatography requires specialized technicians scarce in Eastern European processing zones.
- Certification timeline compression:Simultaneous organic, kosher, and pharmaceutical-grade audits strain quality assurance staffing at mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blackcurrant Seed Oil Market |
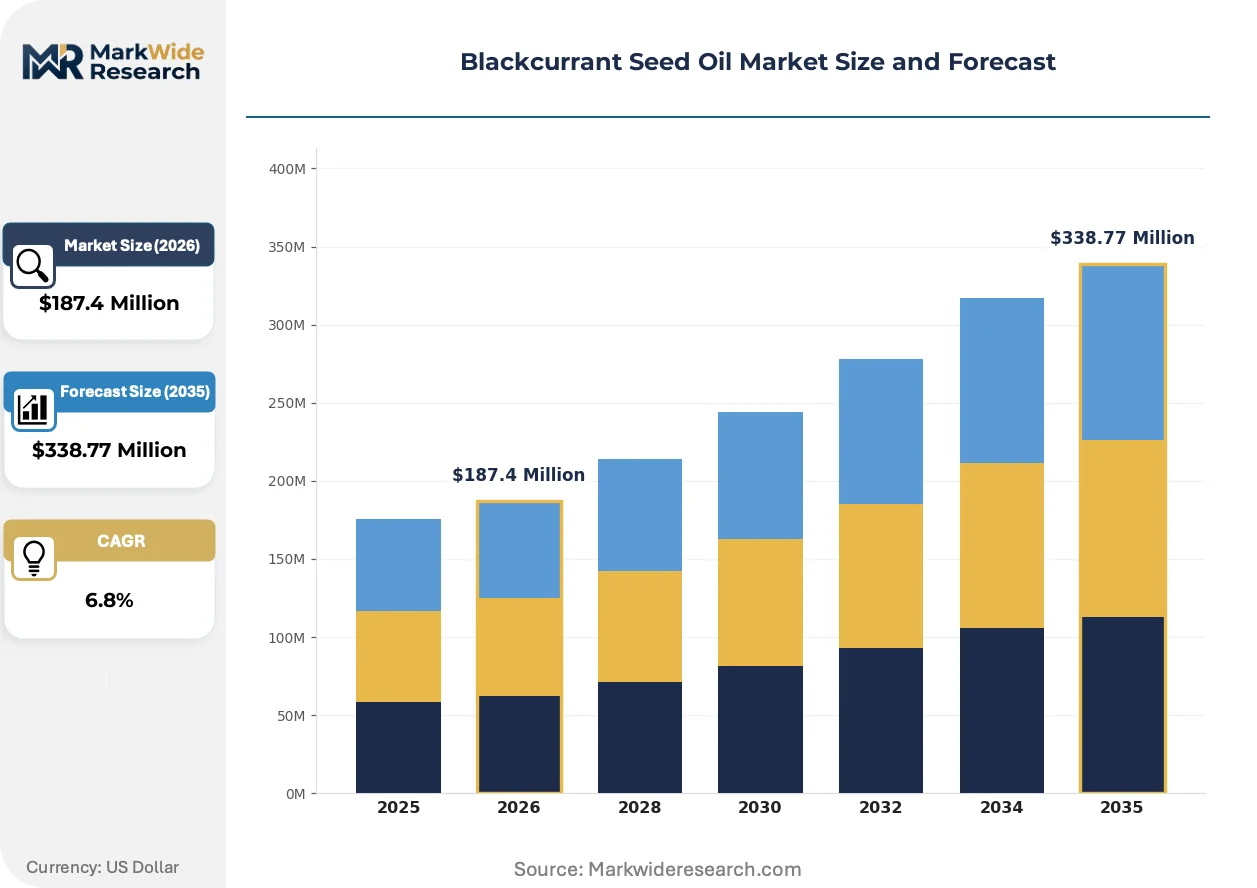
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed Oil, Refined Oil, Organic Oil, Conventional Oil Application: Cosmetics, Dietary Supplements, Food Industry, Pharmaceuticals End User: Individual Consumers, Retailers, Health Organizations, Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | ConnOils LLC, Nutraceutical Corporation, NOW Foods, Botanical Beauty Co., Vando Naturals, Dève Herbes, NUSAPURE, NutriONN, Bioriginal Food & Science Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blackcurrant Seed Oil Market Emerging Trajectories
Supercritical fluid extraction and in-line fatty acid monitoring are redrawing technical specifications across cosmetic and pharmaceutical procurement channels, compressing the viable technology gap between artisanal and industrial processors.
Supercritical CO2 extraction systems with integrated terpene recovery are rendering obsolete traditional solvent-based methods that degrade heat-sensitive phytosterols. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these systems within twelve-month equipment refresh cycles. The technology is compressing minimum viable scale thresholds, enabling regional crushers to enter pharmaceutical-grade segments previously reserved for multi-ton processors.
EFSA novel food evaluations for refined blackcurrant seed oil applications are tightening toxicological data requirements ahead of 2026 compliance windows. Food ingredient manufacturers must submit ninety-day feeding studies and stability documentation that cold-pressed variants already possess. Bakery and functional food developers in the Netherlands and Belgium are reformulating around existing approvals rather than pursuing new dossiers.
Certification-driven preference shifts are fragmenting buyer segments into organic-mandatory, organic-indifferent, and pharmaceutical-grade-only pools. Natural cosmetics brands in France are rejecting non-organic supply regardless of fatty acid parity, while mass-market supplement brands in the United States prioritize cost over certification tier. Poland's expanding processing capacity is capturing organic-indifferent volume, while German and Austrian facilities dominate premium certified channels.
Blackcurrant Seed Oil Market Segmentation
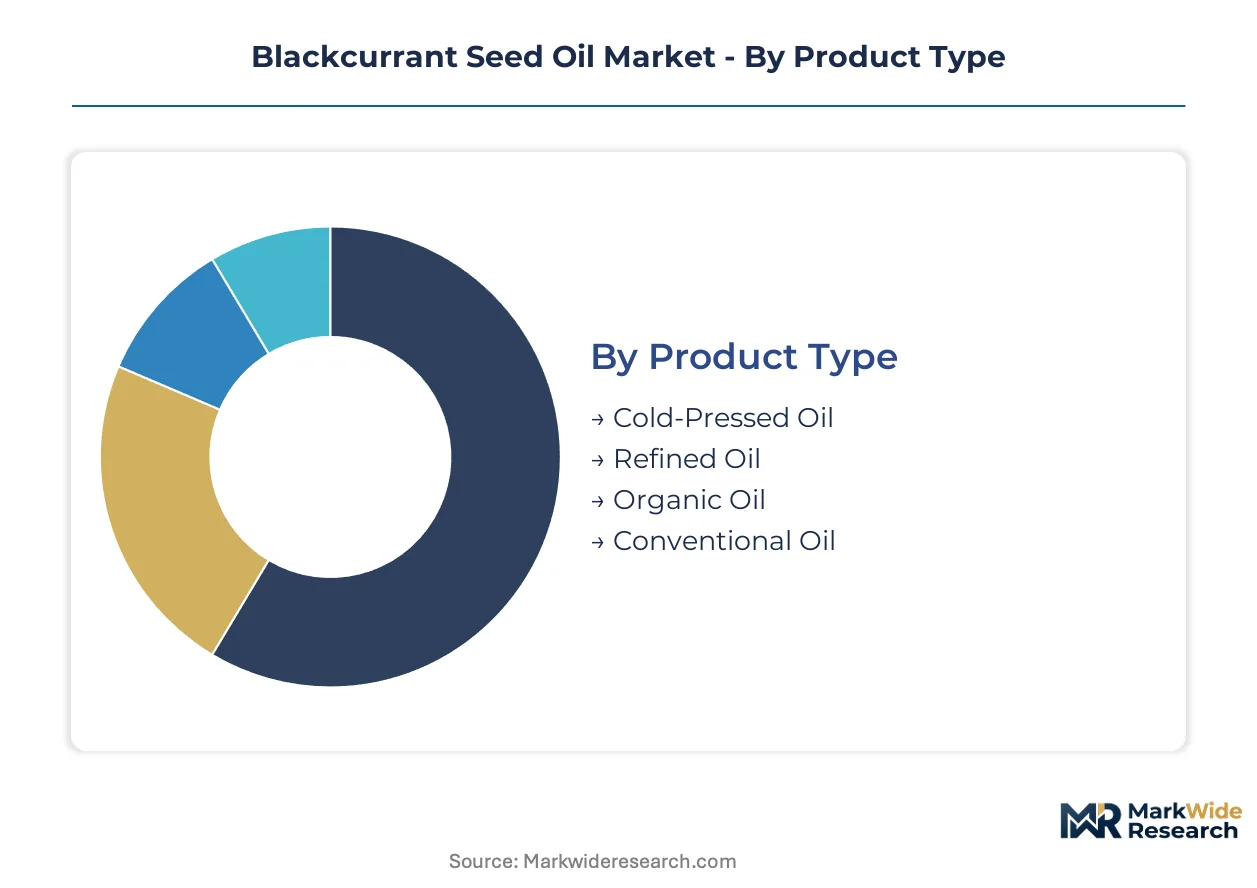
Blackcurrant seed oil procurement patterns diverge sharply across extraction methods and purity grades, with cosmetic formulators and pharmaceutical buyers operating on incompatible specification timelines. Segmentation reveals where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Cold-pressed oil turns inventory fastest in German and French cosmetic supply chains, while refined oil moves slower through food industry tender processes that stretch twelve to eighteen months.
- Cold-Pressed Oil:Retains 15-20% gamma-linolenic acid and heat-sensitive phytosterols through mechanical extraction below 40°C. Premium skincare lines in Germany and France contract eighteen to twenty-four months ahead to secure potency guarantees from registered processors.
- Refined Oil:Bleached and deodorized for color stability and neutral flavor profile. Food industry applications in the Netherlands and Belgium favor this grade where thermal processing tolerance outweighs bioactive retention requirements.
- Organic Oil:Certified under EU 2018/848 or USDA NOP standards with full seed-to-oil traceability. Natural cosmetics brands in France reject non-organic supply regardless of fatty acid parity.
- Conventional Oil:Non-certified volume grade competing on cost against evening primrose and borage alternatives. Poland's expanding processing capacity captures this segment where certification adds no price premium.
Cold-pressed oil dominates installed base value. Organic oil is where expansion concentrates.
Application:
Cosmetic procurement runs on twelve-week replenishment cycles with Swiss and German contract manufacturers, while pharmaceutical qualification timelines extend thirty-six months for endotoxin-free certification.
- Cosmetics:Facial serums and barrier-repair formulations leverage GLA content for anti-inflammatory positioning. Premium lines in France and Germany specify supercritical CO2 extraction to preserve terpene profiles.
- Dietary Supplements:Softgel and liquid formulations competing with evening primrose oil on price-per-milligram GLA. Mass-market brands in the United States prioritize cost over extraction method disclosure.
- Food Industry:Functional bakery and dairy applications requiring EFSA novel food approvals. Developers in Belgium reformulate around existing dossiers rather than pursue new ninety-day feeding studies.
- Pharmaceuticals:Prescription dermatology channels requiring endotoxin-free certification and batch-level fatty acid profiling. Swissmedic-registered facilities in Switzerland and Germany control this tier.
Cosmetics commands the largest revenue pool. Pharmaceuticals represents the fastest-growing trajectory.
End User:
Manufacturers lock in annual contracts with fixed fatty acid specifications, while individual consumers purchase sporadically through channels with minimal technical verification.
- Individual Consumers:Direct purchasers through online retail and specialty stores, price-sensitive to organic certification premiums. California and New York functional medicine practitioners bypass retail for liter-volume therapeutic-grade purchases.
- Retailers:Health food chains and natural cosmetics boutiques demanding kosher, organic, and non-GMO documentation bundles. Quality assurance staffing constraints strain mid-scale processors during audit season.
- Health Organizations:Clinics and wellness centers sourcing therapeutic grades with certificate of analysis per lot. Direct-to-clinic distribution models are displacing traditional wholesale in North American metropolitan markets.
- Manufacturers:Cosmetic formulators and supplement brands with in-house analytical chemistry capabilities. NOW Foods and Bioriginal Food & Science Corp anchor supply through direct agricultural partnerships and backward integration.
Manufacturers dominate procurement volume. Health organizations are where margin expansion concentrates.
Distribution Channel:
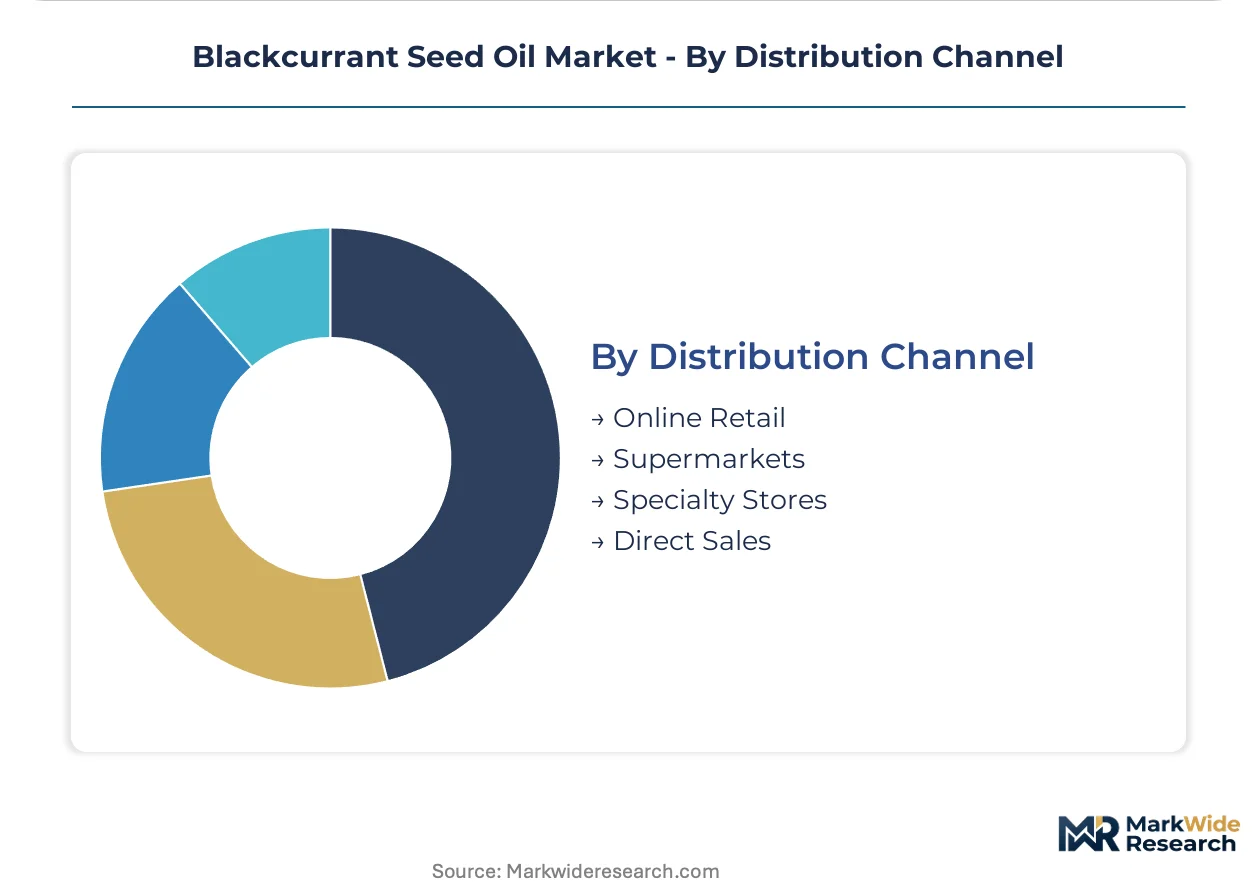
Direct sales to pharmaceutical contract manufacturers operate on eighteen-month qualification timelines, while online retail turns inventory in four to six weeks with minimal specification barriers.
- Online Retail:Amazon and direct-to-consumer platforms with minimal fatty acid verification. Polish and Ukrainian processors use this channel to bypass REACH-registered trader markups.
- Supermarkets:Mass-market supplement placement competing on shelf price against borage oil alternatives. United States retailers demand USDA organic integrity documentation under updated traceability mandates.
- Specialty Stores:Health food and natural cosmetics boutiques with educated staff explaining GLA content differentiation. French and German organic certification requirements filter supplier lists aggressively.
- Direct Sales:Pharmaceutical contract manufacturers and cosmetic formulators with technical qualification protocols. ConnOils LLC differentiates through specialized organic certification and pharmaceutical-grade filtration capabilities in this channel.
Direct sales dominates value capture. Online retail is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Poland and Ukraine exhibit acute price sensitivity, driving volume through conventional oil grades, while Swiss and German cosmetic formulators absorb substantial premiums for certified organic and pharmaceutical-grade supply.
Germany
Premium skincare manufacturers in Hamburg and Berlin contract cold-pressed oil eighteen to twenty-four months ahead to secure gamma-linolenic acid potency guarantees. REACH substance registration requirements filter non-compliant traders, consolidating volume with registered processors. The Baden-Württemberg cluster hosts supercritical CO2 extraction facilities serving pharmaceutical contract manufacturers.
France
Natural cosmetics brands in Paris and Lyon reject non-organic supply regardless of fatty acid parity, creating mandatory certification tiers. ANSM oversight of cosmetic ingredient safety documentation shapes import specifications. The Provence-Alpes-Côte d'Azur region anchors organic oil processing capacity with integrated seed-to-oil traceability systems.
Poland
Expanding crushing capacity in Poznań and Wrocław captures organic-indifferent volume where certification adds no price premium. Blackcurrant pomace supply fluctuates with juice concentrate harvests, creating raw material availability mismatches. The country's processing zones compete on cost against Ukrainian processors in online retail channels.
Switzerland
Swissmedic-registered facilities in Basel and Zurich control prescription dermatology channels requiring endotoxin-free certification and batch-level fatty acid profiling. Pharmaceutical-grade filtration capabilities command three-year qualification timelines with contract manufacturers. The Swiss cluster integrates supercritical CO2 extraction with integrated terpene recovery systems.
United States
Functional medicine practitioners in California and New York bypass retail for liter-volume therapeutic-grade purchases, displacing traditional wholesale models. FDA GRAS self-affirmation and USDA organic certification shape compliance pathways, with updated organic integrity rules creating first-mover advantage for vertically integrated crushers. NOW Foods leverages direct agricultural partnerships to secure cold-pressed supply chains.
Blackcurrant Seed Oil Market Vendor Landscape
Backward-integrated processors and specialized certification specialists split the market between volume efficiency and premium positioning. The structure concentrates around mid-scale facilities with in-house analytical chemistry capabilities, filtering out artisanal crushers unable to meet simultaneous organic, kosher, and pharmaceutical-grade audit demands. Two archetypes dominate: agricultural partnership networks securing raw material access, and filtration technology specialists opening prescription channels. Competitive moves center on supercritical CO2 extraction investment and direct-to-clinic distribution bypassing traditional wholesale markups.
Within the agricultural partnership tier, NOW Foods exemplifies upstream control over Eastern European seed supply, while Bioriginal Food & Science Corp anchors its position through captive supply of seed crushing and fatty acid profiling infrastructure. Among certification-focused specialists, ConnOils LLC occupies a position defined by pharmaceutical-grade filtration capabilities and specialized organic certification documentation. These three entities represent the dominant strategic configurations: direct farm contracting, backward-integrated processing, and multi-certification technical compliance.
| Leading Market Players |
|---|
| ConnOils LLC |
| Nutraceutical Corporation |
| NOW Foods |
| Botanical Beauty Co. |
| Vando Naturals |
| Dève Herbes |
| NUSAPURE |
| NutriONN |
| Bioriginal Food & Science Corp |
| Others |
Supply Flow & Price Mechanics
Blackcurrant pomace supply volatility from Polish and Ukrainian juice concentrate harvests compresses margin buffers across all pricing tiers while simultaneously fragmenting supply chain configurations between certified and conventional processors. This raw material chokepoint forces formulators to choose between long-term agricultural partnerships that lock in cost predictability or spot-market procurement that sacrifices fatty acid potency guarantees.
Pricing Analysis
After-sales certification documentation and batch-level analytical services generate recurring revenue streams that exceed initial oil sale margins for premium processors. Three-tier pricing structure across pharmaceutical-grade, certified organic, and conventional levels stratifies buyer segments, with Swissmedic-registered facilities commanding substantial premiums over Polish volume crushers. Cost compression in conventional grades intensifies as evening primrose and borage oils compete on gamma-linolenic acid content. Mass-market supplement brands in the United States exhibit acute price sensitivity, while French natural cosmetics manufacturers absorb organic certification premiums without volume reduction.
Supply Chain Analysis
Blackcurrant pomace availability in Poland, Ukraine, and Eastern Germany determines upstream feedstock access for European crushing capacity. Seed crushing infrastructure draws from agricultural waste streams of juice concentrate processors, creating dependency on seasonal harvest cycles and weather patterns. Single-source vulnerability concentrates in Polish pomace aggregators who control 60-70% of regional raw material flows. Distribution runs through REACH-registered processors for cosmetic formulators, while online retail channels bypass compliance markups through direct Polish and Ukrainian processor listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is reshaping competitive positioning by collapsing minimum viable scale thresholds and opening prescription dermatology channels previously reserved for multi-ton processors. EFSA novel food evaluation deadlines and REACH registration windows compress qualification timelines, favoring processors with in-house analytical chemistry capabilities.
For Market Incumbents: Insulate margin position through captive seed crushing infrastructure and backward integration into Eastern European agricultural partnerships. Secure eighteen to twenty-four month contracting pipelines with German and French cosmetic formulators before REACH substance registration deadlines filter non-compliant traders. Invest in simultaneous organic, kosher, and pharmaceutical-grade certification capacity to defend against mid-scale facilities with quality assurance staffing constraints. For New Entrants and Emerging Players: Pursue direct-to-clinic distribution models in California and New York functional medicine markets, bypassing traditional wholesale markups that compress margins for retail-channel entrants. Target organic-indifferent volume segments where Polish processing capacity expansion creates procurement gaps. Anchor market entry through supercritical CO2 extraction partnerships with Swiss or German pharmaceutical contract manufacturers seeking endotoxin-free certification alternatives. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors processors with integrated fatty acid profiling laboratories and multi-certification compliance infrastructure. Five-to-ten year viability hinges on regulatory moats rather than commodity scale, positioning mid-cap specialists with analytical chemistry capabilities as preferred acquisition targets. Watch for Health Canada natural health product licensing timeline compression as an inflection signal for North American market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Investment | Opens Swissmedic-registered prescription dermatology channels requiring endotoxin-free certification. |
| Direct Agricultural Partnerships | Secures Polish and Ukrainian pomace supply chains against juice concentrate harvest volatility. |
| Multi-Certification Quality Infrastructure | Enables simultaneous organic, kosher, and pharmaceutical-grade audits for French cosmetic buyers. |
| Direct-to-Clinic Distribution Model | Bypasses retail wholesale markups in California and New York functional medicine markets. |
| In-House Fatty Acid Profiling Capability | Supports REACH compliance documentation and eighteen-month formulator contracting timelines. |
Methodological Framework
Operator-level perspectives from seed crushing plant managers, cosmetic formulator procurement leads, pharmaceutical contract manufacturer quality directors, and REACH compliance consultants anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through EFSA novel food evaluation databases, REACH substance registration filings, USDA organic integrity rule documentation, and customs trade data for blackcurrant seed oil flows. Bottom-up volume estimates from processing facility capacity and top-down demand triangulation from end-use application consumption established analytical convergence.
Scenario-bracketing around regulatory timeline compression and technology adoption curves shaped the projection framework across the analysis window. Segmentation dimensions modeled include extraction method, certification grade, end-use application, and regional regulatory cluster. CAGRs derived from weighted average growth contributions across product tiers, with specific inputs from supercritical CO2 extraction capacity expansion rates and Health Canada licensing pipeline data.
Sensitivities concentrate around EFSA evaluation deadline shifts, REACH substance registration enforcement intensity, and blackcurrant harvest yield variation. Forecasts reflect assumptions on regulatory timeline adherence and technology cost curves without incorporating extreme weather or trade policy discontinuities. Material shifts in organic integrity rule implementation or pharmaceutical-grade filtration technology economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Walnut Market
Nuts and Seeds
Butyrospermum Parkii Market
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
Walnut-Based Spreads Market
Nuts and Seeds
Asia-Pacific Grape Seed Extract Market