
 Beer Mug Market | 2026-2036
Beer Mug Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Mug Market Analysis
ISO 6486-1 certification for ceramic and glass articles in contact with food is reorganizing supplier eligibility across the beer mug value chain. Stoelzle Oberglas GmbH leverages Austrian manufacturing scale to supply premium crystal tankards for European brewers. Borosil Ltd. anchors Indian production capacity with thermal-shock-resistant borosilicate glass formulations. Libbey Inc. dominates North American foodservice channels through extensive distributor partnerships.
A beer mug is a handled drinking vessel, typically fabricated from soda-lime glass, borosilicate, or stoneware ceramic, with wall thickness of 3-5 millimeters and capacity standardized at 0.5 or 1.0 liters for commercial draft service. Glass material commands the largest volume share due to optical clarity and recyclability, though stainless steel variants are gaining traction in outdoor and festival applications where breakage risk constrains glass deployment. Tankard and stein types carry premium positioning through heritage-linked design codes, while craft-type mugs compete on customization throughput for brewery-branded merchandise programs.
FDA food-contact substance regulations in the United States and EU REACH compliance obligations in Europe together elevate testing costs for imported glassware, effectively filtering smaller exporters from these markets. BIS certification requirements in India create parallel compliance tracks for manufacturers serving domestic hospitality procurement. Stakeholders must monitor evolving extended producer responsibility frameworks for packaging and tableware, as these programs will increasingly govern end-of-life collection obligations and material recovery targets.
Market Dynamics
Microbrewery proliferation and festival-scale glassware procurement are compressing order cycles while EU REACH chemical safety mandates are filtering supplier eligibility across European distribution channels.
Growth Catalysts
- Craft Beer Taproom Expansion:Independent breweries in Germany, Belgium, and the Czech Republic are commissioning branded tankards and steins for on-premise consumption and retail merchandise programs.
- REACH Compliance Migration:Lead-free crystal formulations are becoming mandatory for EU market access, accelerating R&D investment among glassware manufacturers serving food-contact applications.
- Thermal-Shock Borosilicate Adoption:Outdoor festival operators are substituting soda-lime glass with borosilicate variants to reduce breakage liability in high-volume service environments.
Market Restraints
- Raw Material Energy Intensity:Soda-lime glass production requires sustained natural gas or electric furnace operation, exposing margins to European energy price volatility.
- Supply Concentration in Austria:Premium crystal tankard capacity clusters around Stoelzle Oberglas manufacturing sites, creating single-source vulnerability for brewers requiring ISO 6486-1 certified vessels.
- Stainless Steel Substitution:Double-walled metal mugs are capturing outdoor and camping segments where weight tolerance and impact resistance outweigh optical clarity preferences.
Strategic Opportunities
- Indian Hospitality Procurement:BIS certification requirements are creating compliant supply gaps that domestic borosilicate producers can capture through certified production lines.
- Extended Producer Responsibility Frameworks:EU packaging and tableware recovery mandates will reward manufacturers with established closed-loop collection infrastructure and material recovery capabilities.
- Laser Etching Customization:Brewery-branded merchandise programs are integrating on-demand personalization technology to reduce minimum order quantities and inventory risk for craft producers.
Industry Challenges
- Multi-Jurisdiction Certification Overlap:FDA food-contact substance testing in the United States, EU REACH compliance, and BIS marking in India create parallel documentation burdens for exporters serving multiple markets.
- Skilled Glassblower Shortage:Heritage tankard and stein production relies on manual pressing and finishing techniques where trained artisan labor is retiring faster than apprenticeship programs replace capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Mug Market |
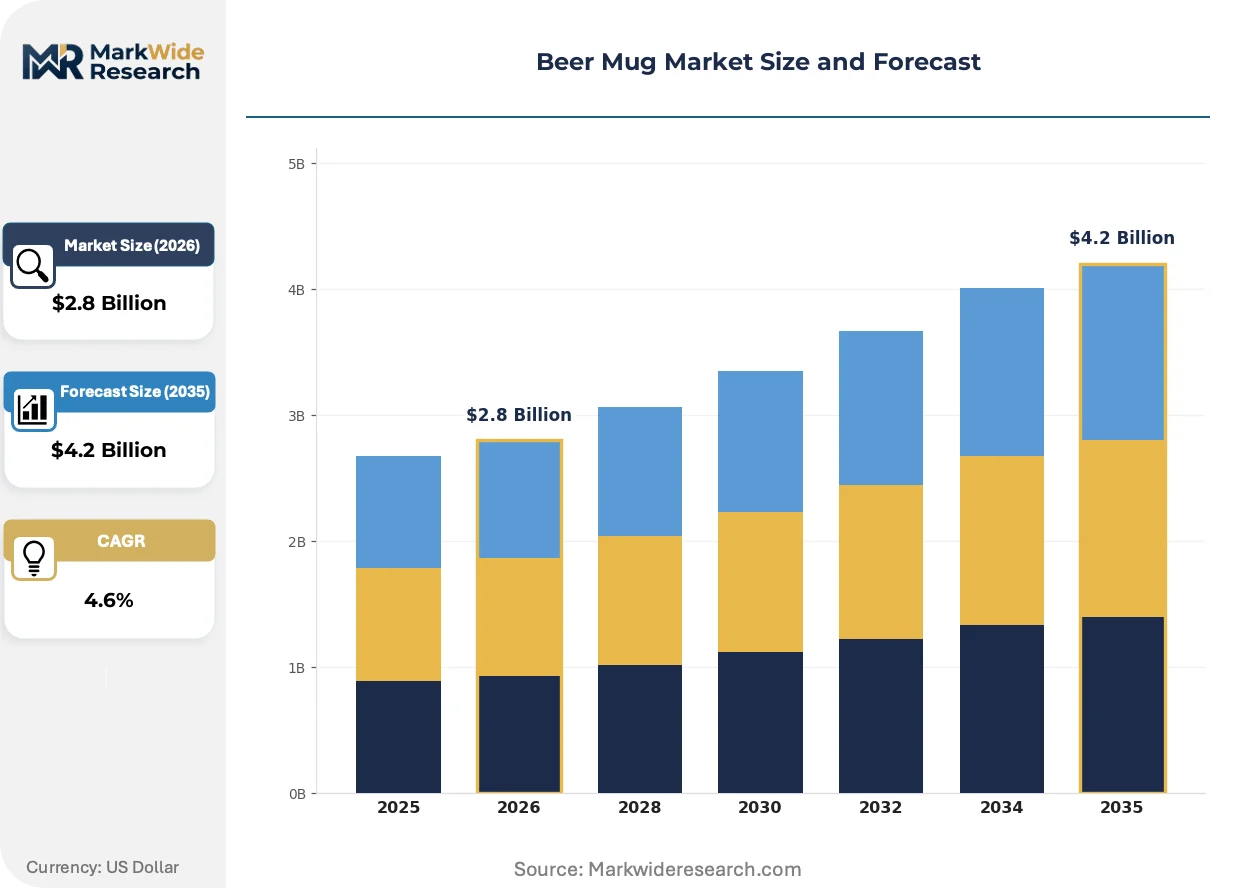
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Ceramic, Stainless Steel Type: Craft, Pint, Steins, Tankards Design: Engraved, Printed, Solid Color, Decorative Usage Occasion: Casual, Formal, Parties, Festivals |
| Companies Covered | Stoelzle Oberglas GmbH, Borosil Ltd., Arc Holdings, Guangdong Garbo Industrial Co. Ltd., Cello World Pvt. Ltd., Bormioli Rocco Spa, bayerische glaswerke gmbh, Ocean Glass Public Co. Ltd., Libbey Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Mug Market Emerging Trajectories
Digital printing and laser surface treatment are collapsing customization lead times for brewery-branded programs while regulatory chemical safety testing is elevating technical barriers to market entry.
Digital ceramic printing is fragmenting the traditional screen-printing monopoly on brewery logo application. Craft producers in Bavaria and Bohemia are adopting direct-to-glass UV curing systems that enable 48-hour turnaround on 500-unit minimum orders. This capability is compressing the competitive advantage of high-volume offset decorators while enabling micro-lot experimentation with seasonal designs.
EU REACH Annex XVII restrictions on lead and cadmium in crystal glassware are forcing reformulation of traditional tankard compositions. Manufacturers serving Oktoberfest-scale accounts must recertify existing product lines under ISO 6486-1 migration testing protocols. German brewers with heritage stein programs are responding by specifying barium oxide substitutions that maintain refractive index without triggering substance restrictions.
Festival operators are unbundling glassware procurement from draft equipment leases to negotiate direct vessel supply agreements. This disintermediation is bypassing traditional beverage distributor bundled-service models in North American and Australian outdoor event markets. Independent rental houses in Melbourne and Austin are building captive tankard inventories to capture margin previously allocated to integrated draft system providers.
Beer Mug Market Segmentation
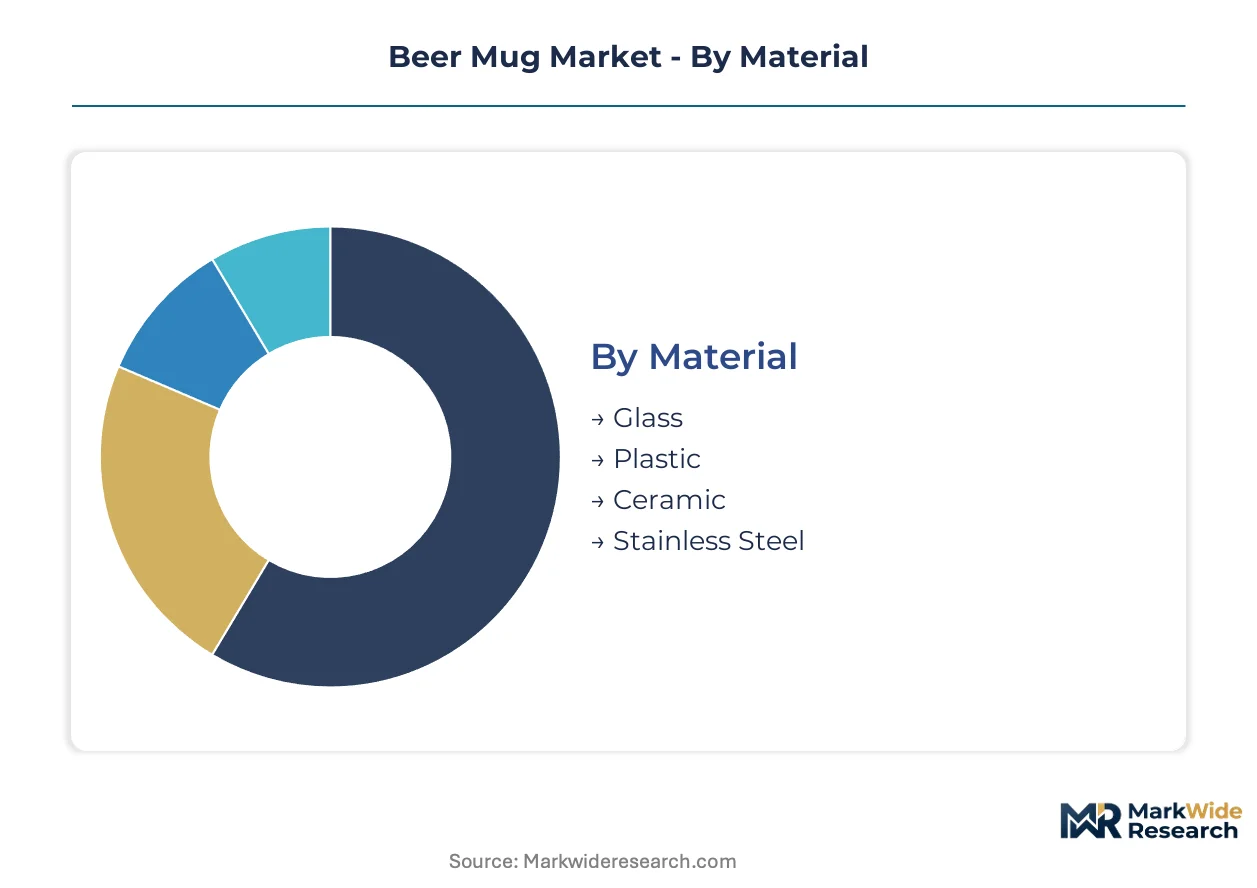
Beer mug procurement channels diverge sharply by material durability and branding requirements. Festival operators, craft taprooms, and hospitality distributors each favor distinct segment combinations based on breakage liability, customization throughput, and regulatory compliance burdens.
Material:
Glass commands foodservice distributor dominance, while stainless steel and plastic variants flow through outdoor equipment rental channels and direct festival procurement.
- Glass:Soda-lime and borosilicate formulations serve commercial draft service where optical clarity and recyclability matter. German Oktoberfest-scale accounts in Bavaria sustain high-volume orders for 0.5 and 1.0 liter standardized capacities, though EU REACH lead-free mandates are elevating testing costs for imported vessels.
- Stainless Steel:Double-walled vacuum insulation delivers impact resistance for camping and outdoor festival applications where glass breakage liability is prohibitive. North American rental houses in Austin and Melbourne are building captive inventories to bypass traditional beverage distributor bundled-service models.
- Ceramic:Stoneware compositions with 3-5 millimeter wall thickness anchor heritage stein reproductions for brewery merchandise programs. BIS certification requirements in India create compliant supply gaps that domestic producers can capture through certified production lines.
- Plastic:Polycarbonate and Tritan copolyester variants serve mass outdoor events and stadium concessions where weight tolerance and disposability outweigh durability preferences. FDA food-contact substance testing elevates technical barriers for Asian exporters serving US procurement channels.
By volume, glass leads. By growth pace, stainless steel is expanding most quickly.
Type:
Cost tier stratification separates premium heritage positioning from high-throughput craft customization.
- Craft:Brewery-branded merchandise programs drive demand for 48-hour turnaround digital printing capabilities. Direct-to-glass UV curing systems in Bohemia enable micro-lot experimentation with seasonal designs, compressing competitive advantage of high-volume offset decorators.
- Pint:Standardized 568 milliliter capacity dominates UK and Irish pub procurement through distributor partnerships. Thermal-shock borosilicate adoption is climbing among festival operators substituting soda-lime alternatives to reduce breakage liability.
- Steins:Traditional lidded vessels with heritage-linked design codes command premium positioning in German-speaking markets. Barium oxide substitutions are replacing lead crystal formulations to maintain refractive index under EU REACH Annex XVII restrictions.
- Tankards:Heavy-walled cylindrical bodies with handles serve Belgian abbey-style and Czech pilsner presentation rituals. ISO 6486-1 certification is reorganizing supplier eligibility across European distribution channels.
Steins capture the highest margin per unit. Craft types are gaining share fastest through microbrewery proliferation.
Design:
Application context determines whether personalization technology or standardized decoration dominates procurement decisions.
- Engraved:Laser surface treatment enables on-demand personalization with reduced minimum order quantities. Skilled glassblower shortages for manual pressing techniques are accelerating automation investment among heritage tankard producers.
- Printed:Digital ceramic printing fragments traditional screen-printing monopoly on brewery logo application. Bavarian craft producers are adopting 500-unit minimum direct-to-glass systems that compress lead times from weeks to days.
- Solid Color:Uniform tinting through bulk glass composition serves stadium and casino procurement where brand neutrality is required. Extended producer responsibility frameworks for packaging and tableware will increasingly govern end-of-life collection obligations.
- Decorative:Applied relief, medallions, and cobalt painting anchor gift and commemorative channels. Supply concentration in Austrian crystal manufacturing creates single-source vulnerability for premium positioning accounts.
Printed designs dominate volume throughput. Engraved variants show the steepest expansion trajectory in premium taproom merchandise.
Usage Occasion:
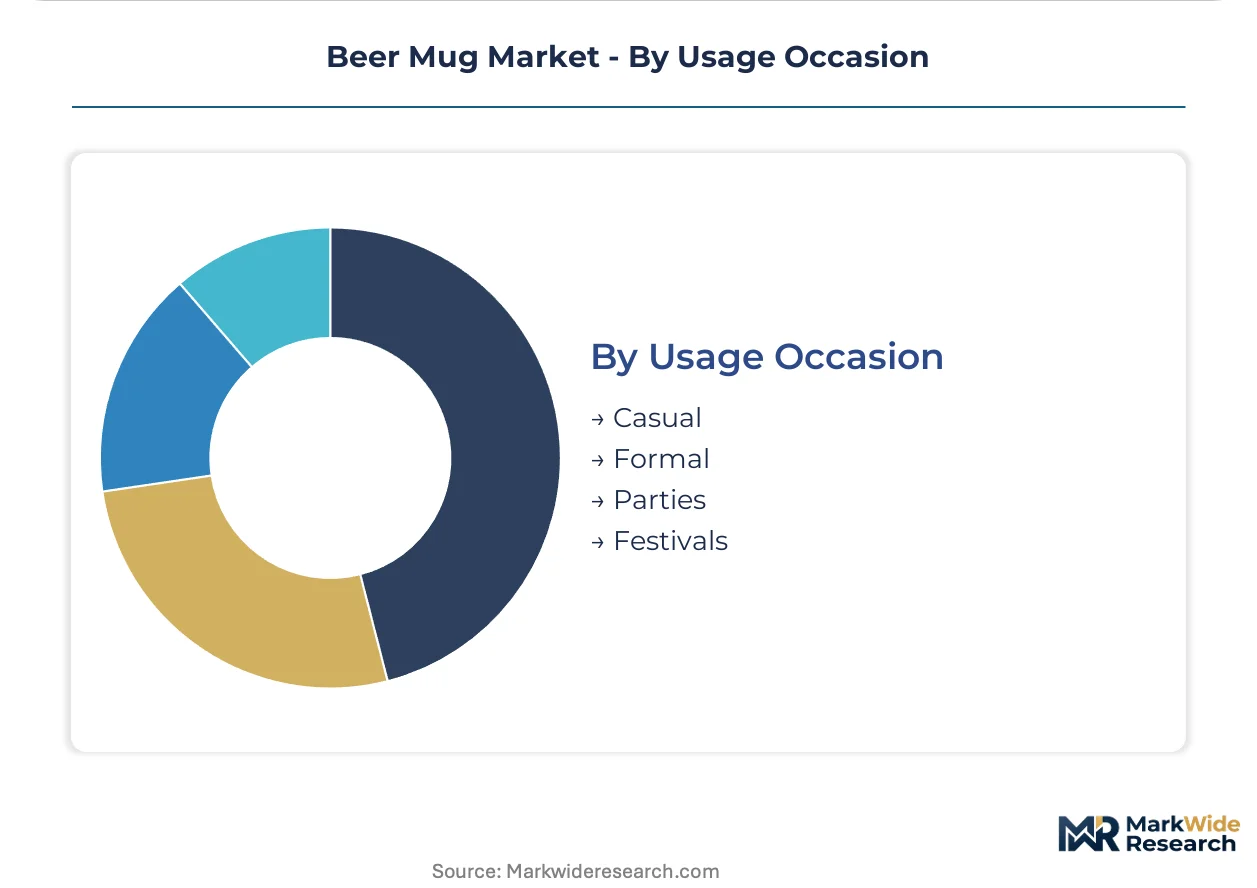
Customer type and service format dictate whether durability, aesthetics, or disposability drives specification.
- Casual:Home and neighborhood pub consumption favors dishwasher-safe soda-lime glass and ceramic stoneware. Indian hospitality procurement is shifting toward BIS-certified borosilicate as domestic production capacity expands.
- Formal:Restaurant and hotel banquet service specifies ISO 6486-1 certified vessels with consistent wall thickness and handle attachment strength. Multi-jurisdiction certification overlap creates parallel documentation burdens for exporters serving US, EU, and Indian markets simultaneously.
- Parties:Disposable and rental-channel procurement favors plastic and lightweight metal variants where loss tolerance is high. Festival operators are unbundling glassware procurement from draft equipment leases to negotiate direct vessel supply agreements.
- Festivals:High-volume outdoor service environments are driving borosilicate substitution and stainless steel adoption where impact resistance outweighs optical clarity. Australian independent rental houses in Melbourne are building captive tankard inventories to capture margin from integrated draft system providers.
Casual usage generates the largest absolute volume. Festival applications are climbing the fastest as outdoor event markets professionalize procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Festival operators and craft taprooms cluster procurement in Germany, the United States, India, China, and Australia. Each geography imposes distinct certification burdens and favors specific material formulations based on service environment and regulatory exposure.
Germany
Oktoberfest-scale accounts in Bavaria sustain high-volume orders for 0.5 and 1.0 liter standardized tankards. EU REACH Annex XVII restrictions on lead and cadmium in crystal glassware are forcing barium oxide substitutions to maintain refractive index. Stoelzle Oberglas leverages Austrian manufacturing scale to supply premium crystal vessels for European brewers requiring ISO 6486-1 certification.
United States
Craft brewery taprooms in Austin and Portland are commissioning branded merchandise programs with compressed customization cycles. FDA food-contact substance regulations elevate testing costs for imported glassware, filtering smaller exporters from foodservice channels. Libbey Inc. dominates North American distributor partnerships through extensive foodservice channel coverage.
India
Domestic hospitality procurement is shifting toward BIS-certified borosilicate as production capacity expands. Borosil Ltd. anchors Indian manufacturing with thermal-shock-resistant formulations suited to high-volume commercial service. Maharashtra and Gujarat clusters are developing certified production lines to capture compliant supply gaps in the domestic market.
China
Guangdong-based fabricators serve export demand for soda-lime glassware while navigating multi-jurisdiction certification overlap. GB standards for food-contact materials create parallel compliance tracks alongside FDA and REACH requirements. Pearl River Delta manufacturing clusters are investing in digital printing capabilities to serve craft brewery customization programs.
Australia
Independent rental houses in Melbourne are building captive tankard inventories to bypass traditional beverage distributor bundled-service models. Festival operators are unbundling glassware procurement from draft equipment leases to negotiate direct vessel supply agreements. Outdoor event markets are driving borosilicate substitution where impact resistance outweighs optical clarity preferences.
Beer Mug Market Vendor Landscape
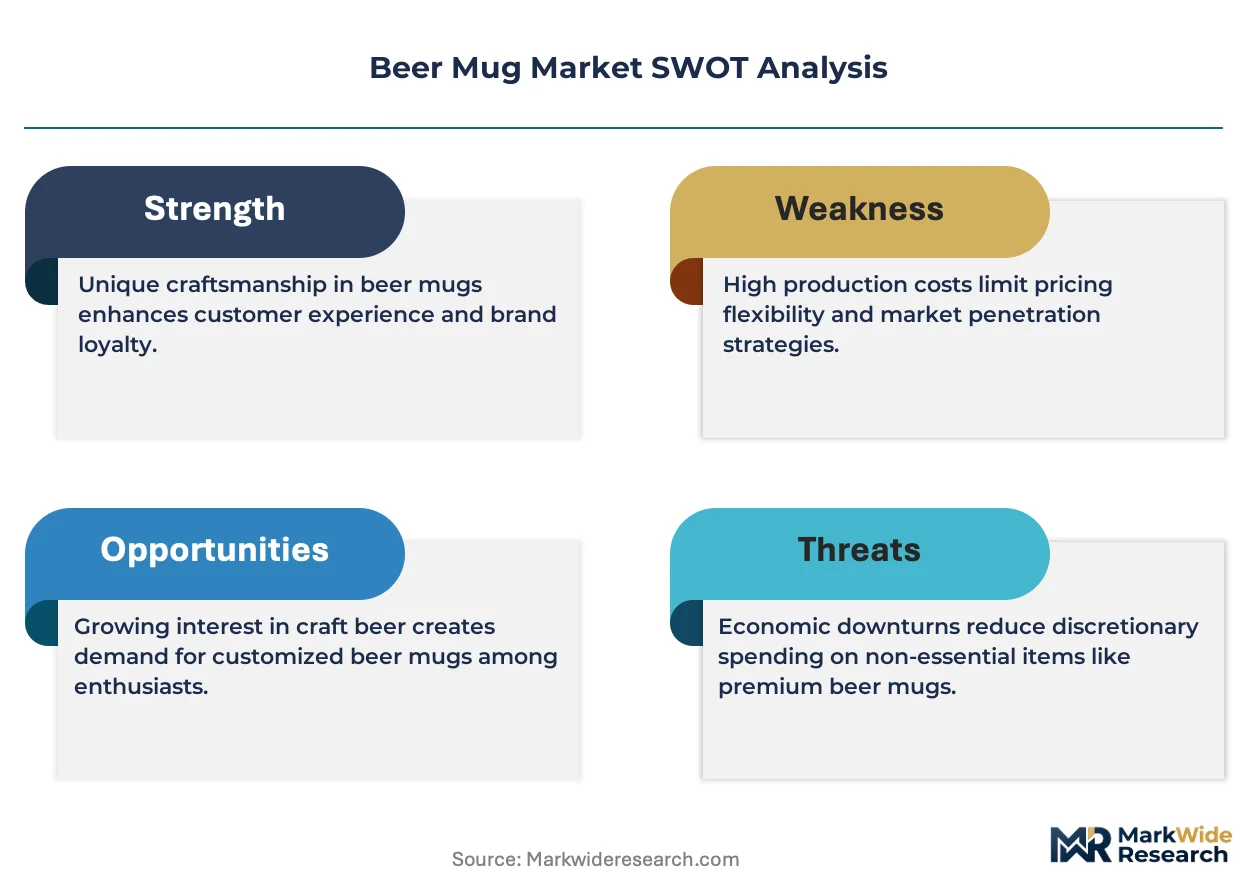
Player mix skews toward European crystal specialists and Asian volume fabricators with divergent certification capabilities. The market structures around heritage-positioned tankard producers, scale-driven soda-lime suppliers, and emerging borosilicate specialists. Strategic moves concentrate on geographic expansion through certified production lines and backward integration into raw material formulation to control lead-free crystal composition.
Among European crystal specialists, Stoelzle Oberglas GmbH and Bormioli Rocco Spa exemplify the heritage-tier archetype with established ISO 6486-1 certification infrastructure. Borosil Ltd. represents the thermal-shock-resistant specialist segment, occupying a position between premium crystal and commodity soda-lime supply. Libbey Inc. anchors North American foodservice distribution through extensive channel partnerships. These three players illustrate the market's tripartite segmentation: certification-heavy European heritage, functional-performance Asian specialists, and distributor-integrated North American volume supply.
| Leading Market Players |
|---|
| Stoelzle Oberglas GmbH |
| Borosil Ltd. |
| Arc Holdings |
| Guangdong Garbo Industrial Co. Ltd. |
| Cello World Pvt. Ltd. |
| Bormioli Rocco Spa |
| bayerische glaswerke gmbh |
| Ocean Glass Public Co. Ltd. |
| Libbey Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Bavarian festival operators and Austrian crystal manufacturers lock in supply access for Oktoberfest-scale procurement while anchoring price visibility against natural gas indexation. These contracts insulate brewers from spot-market volatility in soda-lime glass while exposing margins to energy cost pass-through clauses.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate premium crystal tankard procurement, with price differentiation resting on ISO 6486-1 certification grade and customization throughput. Three-tier pricing structure across heritage stein, craft-branded, and economy soda-lime levels separates barium oxide formulations from standard glass. Cost compression in thermal-shock borosilicate is intensifying because Indian domestic capacity expansion erodes import premiums. Festival rental houses exhibit highest price sensitivity, while German abbey-style brewers tolerate premium positioning for heritage-linked design codes.
Supply Chain Analysis
Austria and Germany anchor premium crystal tankard fabrication, while India and China feed volume soda-lime and borosilicate production. Silica sand, soda ash, and barium oxide draw from concentrated mining districts in Bavaria and Gujarat. Single-source vulnerability clusters around Stoelzle Oberglas manufacturing sites for EU REACH-compliant vessels. Distribution runs through beverage distributor partnerships in North America and direct festival procurement in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Festival operator consolidation is shifting procurement leverage toward buyers, as Melbourne and Austin rental houses bypass bundled-service models to negotiate direct vessel supply agreements.
For Market Incumbents: Fortify ISO 6486-1 certification infrastructure against REACH Annex XVII migration testing requirements while building captive barium oxide formulation capability to control lead-free crystal composition. Stainless steel substitution in outdoor segments demands defensive investment in thermal-shock borosilicate R&D to retain festival accounts. For New Entrants and Emerging Players: Laser etching service-layer gaps in craft brewery merchandise programs offer white-space entry, with Bohemian micro-lot customization showing lowest incumbent saturation. Target Indian BIS-certified borosilicate supply gaps through Maharashtra production clusters. Digital printing equipment leasing models reduce capital barriers versus integrated decorator acquisitions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among festival rental houses with captive tankard inventories and multi-year event contracts. Five-to-ten year viability favors backward-integrated specialists controlling raw material formulation. Watch EU extended producer responsibility framework implementation as inflection signal for collection infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Formulation | Barium oxide substitution capability secures REACH compliance without refractive index degradation. |
| Digital Printing Technology Deployment | UV curing systems in Bohemia compress craft brewery customization lead times from weeks to 48 hours. |
| BIS Certification Investment | Maharashtra production lines capture compliant supply gaps in Indian hospitality procurement. |
| Festival Rental House Acquisition | Melbourne and Austin captive inventories bypass traditional beverage distributor bundled-service models. |
| Extended Producer Responsibility Infrastructure | Closed-loop collection capabilities align with EU packaging and tableware recovery mandates. |
Methodological Framework
Initial hypotheses were tested against primary input from glassware procurement managers at German brewers, festival rental house operators in Melbourne and Austin, and regulatory affairs leads at EU REACH compliance consultancies, then refined through secondary validation against customs trade data, BIS certification registries, and SEC filings from listed glassware manufacturers. Bottom-up volume estimates from individual production facilities were triangulated against top-down category spend analysis.
Variance decomposition across material type, design technology, and usage occasion segmentation dimensions drove analytical framework construction over the projection horizon. CAGRs were derived from modeled unit economics and price trajectory assumptions. Forecast inputs incorporated natural gas cost curves for furnace operations and REACH testing protocol adoption rates.
Underlying assumptions cover sustained craft brewery taproom expansion and EU chemical safety enforcement continuity, with deviation risk concentrated in energy price volatility and skilled glassblower labor availability. Recalibration cycles align with material shifts in extended producer responsibility framework implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Luxury Wines and Spirits Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Distillers Malt Market