
 Copper in Electric Vehicle Market | 2026-2036
Copper in Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Copper in Electric Vehicle Market Intelligence
Direct sourcing channels from miners to automotive original equipment manufacturers is narrowing the role of traditional metal traders. Mining giants like Codelco are forming direct partnerships with vehicle manufacturers to secure long-term offtake agreements. Glencore leverages its recycling operations to supply low-carbon copper, a key differentiator for ESG-focused automotive buyers. Freeport-McMoRan sustains its position through large-scale, low-cost production from its assets in the Americas.
Copper in electric vehicles refers to the high-purity, high-conductivity metal used for efficient electrical power and signal transmission. Its thermal conductivity and ductility make it vital for components managing significant electrical loads and dissipating operational heat. While wiring harnesses and busbars are high-volume segments tied to vehicle output, they face intense price competition. In contrast, the electric motors application requires specialized copper windings, representing a high-value and technically demanding market segment.
Regulations such as the EU's REACH and China's GB standards dictate the purity and composition of copper alloys used in automotive components. Concurrently, the US Inflation Reduction Act's domestic content requirements are reshaping supply chain strategies for North American EV production. Securing ethically sourced and low-carbon copper supply is becoming a critical determinant of competitive advantage for automakers and their Tier 1 suppliers.
Market Dynamics
The central force shaping the market is the collision between exponential demand from electric vehicle production and the inelastic, long-cycle nature of copper supply. This dynamic is amplified by regulatory pressures for supply chain transparency, forcing a strategic re-evaluation of sourcing beyond pure price metrics.
Growth Catalysts
- IRA Domestic Content Rules:The US Inflation Reduction Act incentivizes North American sourcing for EV components, stimulating investment in domestic copper processing and component manufacturing to serve the automotive sector.
- Battery Anode Demand:The shift towards higher energy density batteries requires ultra-thin, high-purity copper foils for current collectors, a technically demanding application that commands premium pricing.
- China's Ecosystem Dominance:China's integrated EV and battery manufacturing hubs, supported by its dual carbon goals, create a concentrated and massive demand center for all forms of automotive-grade copper.
Market Restraints
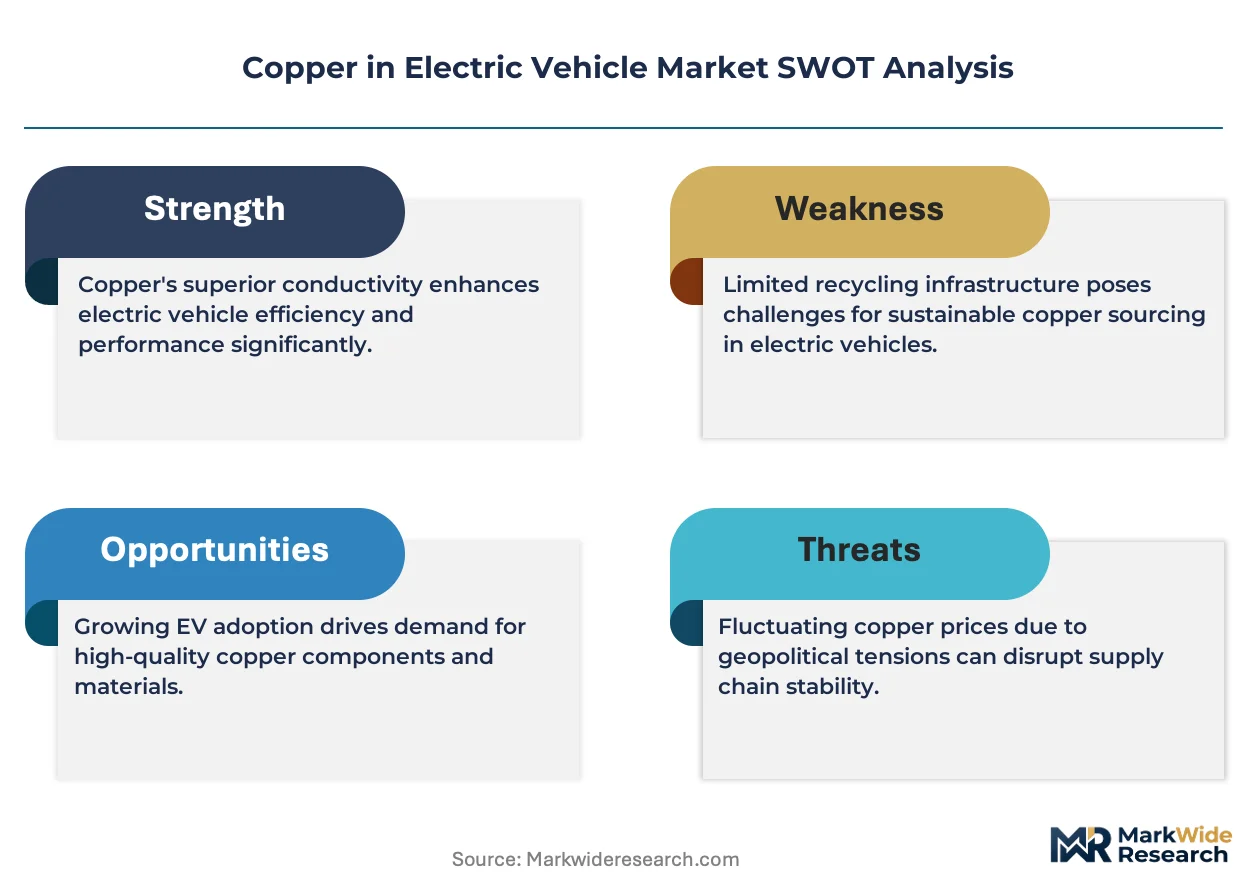
- Input Cost Volatility:The market remains exposed to price fluctuations on the London Metal Exchange for high-grade copper, creating margin pressure for component manufacturers on fixed-price contracts with OEMs.
- Geopolitical Supply Risk:Heavy reliance on mining output from a few countries, particularly in South America, exposes the entire EV supply chain to potential disruptions from political instability or resource nationalism.
- Substitution Threat in Low-Value Segments:While not a direct replacement in motors or batteries, aluminum continues to be evaluated as a lower-cost alternative for certain wiring harness and busbar applications, capping price ceilings.
Strategic Opportunities
- Thermal Management for Fast Charging:The development of ultra-fast charging infrastructure creates an opportunity for advanced copper-based cooling systems and high-capacity cables to manage extreme thermal loads.
- Certified Low-Carbon Copper:Regulations like the EU's CSRD create a distinct market for suppliers who can provide certified, low-carbon copper from recycled or hydro-powered sources, attracting ESG-focused OEMs.
- Indian EV Market Entry:India's growing focus on electric mobility, supported by its PLI scheme, presents an underpenetrated market for specialized copper foil and winding wire suppliers.
Industry Challenges
- Supply Chain Traceability:Implementing robust traceability systems to verify the origin and carbon footprint of copper from mine to vehicle is a complex operational challenge, yet increasingly a non-negotiable customer requirement.
- Capital Investment Cycles:The immense capital expenditure and long lead times required to bring new copper mines online or build advanced recycling facilities create a persistent lag behind rapidly scaling EV production targets.
- Anode Foil Standardization:A lack of global standards for the thickness, tensile strength, and surface roughness of copper foils for next-generation batteries creates engineering friction and complicates supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper in Electric Vehicle Market |
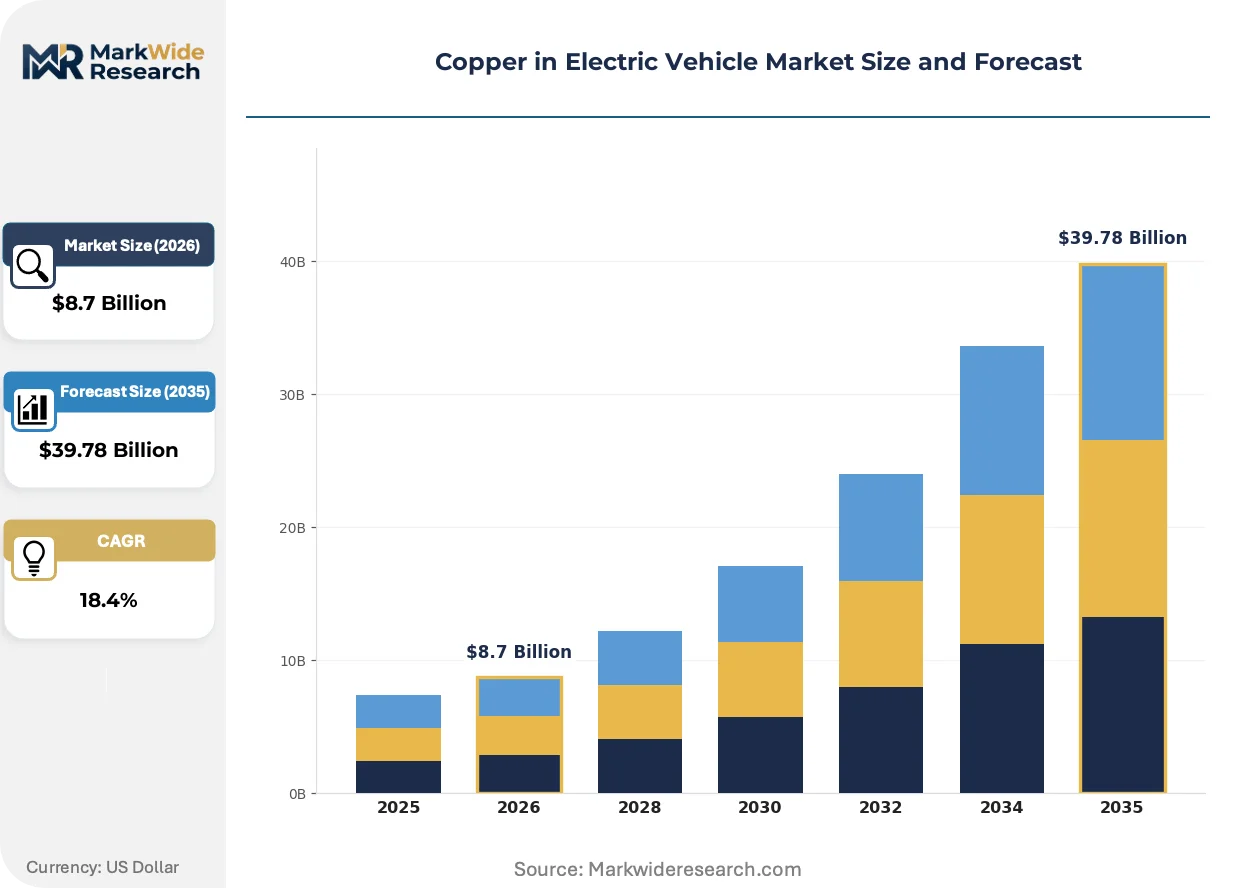
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cables, Connectors, Busbars, Wiring Harnesses Application: Power Distribution, Charging Infrastructure, Battery Manufacturing, Electric Motors End User: OEMs, Aftermarket Providers, Fleet Operators, Charging Station Manufacturers Technology: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle, Hybrid Electric Vehicle |
| Companies Covered | Glencore, Antofagasta PLC, Freeport-McMoRan, China Molybdenum Co., Ltd., First Quantum Minerals Ltd., Southern Copper Corporation, Codelco, Rio Tinto, BHP Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper in Electric Vehicle Market Strategic Shifts & Innovations
The market's evolution is defined by the industrialization of the copper supply chain to meet automotive-grade specifications for quality, sustainability, and traceability. This transition moves copper from a traded commodity to a highly engineered material critical for vehicle performance and brand reputation.
Advanced Process Control
Digital twin technology for copper foil electrodeposition provides a virtual replica of the manufacturing process. Battery manufacturers in South Korea and China are the primary adopters, seeking to improve yield and consistency for high-performance cells. This technology is digitizing quality control, reducing reliance on physical testing and accelerating the validation of foils for new battery chemistries.
Sustainability as a Mandate
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a pivotal regulatory shift. It requires large companies to disclose detailed information on supply chain risks and environmental impacts, including carbon emissions and sourcing practices. Global automotive OEMs are the most affected segment, now compelling their Tier 1 and Tier 2 copper component suppliers to provide auditable sustainability data.
Direct Sourcing by OEMs
A notable behavioral shift involves automotive OEMs establishing direct, long-term offtake agreements with copper mining and refining companies. This model of securing captive supply bypasses a portion of the volume traditionally handled by metal traders on spot or short-term markets. The practice is most advanced among automakers in North America and Europe aiming to de-risk supply for their gigafactory roadmaps.
Copper in Electric Vehicle Market Segmentation
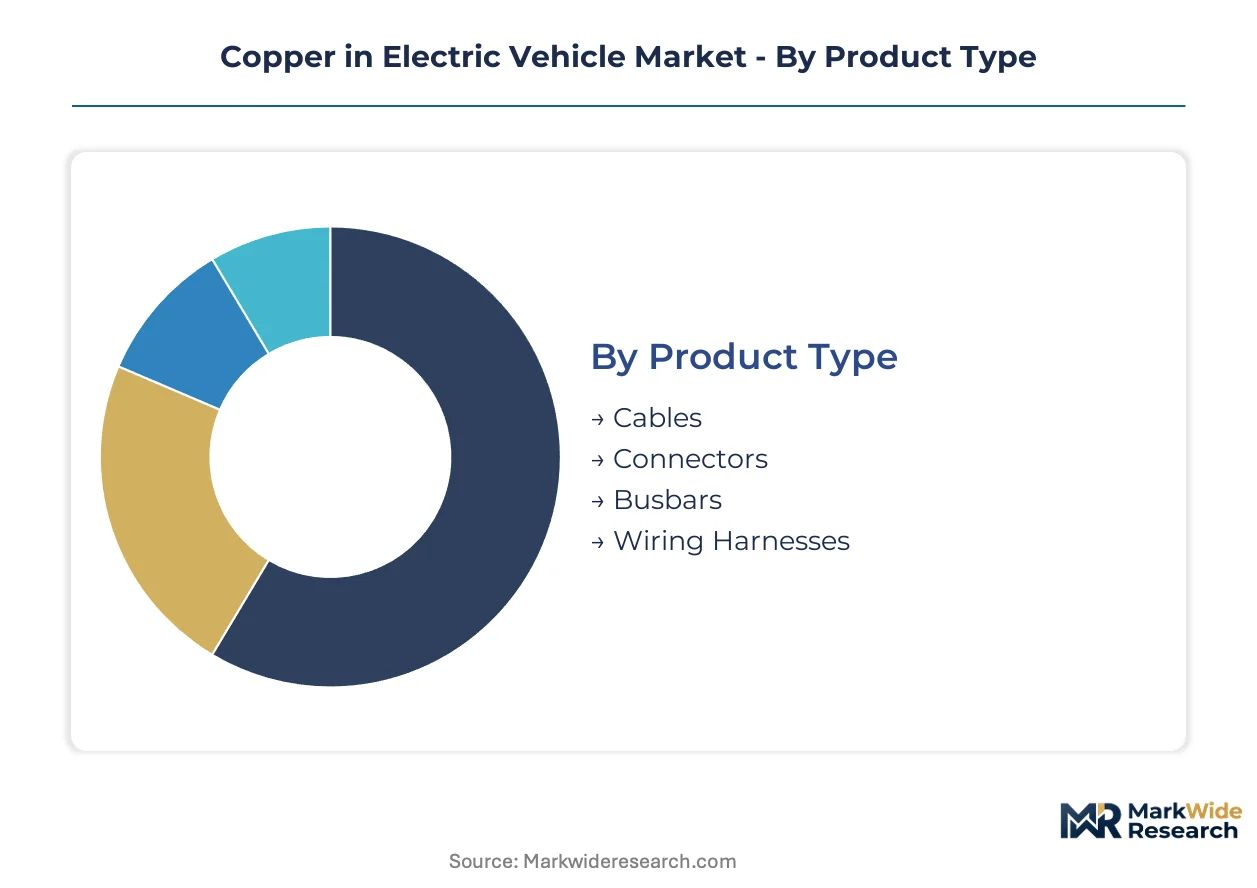
The Copper in Electric Vehicle Market exhibits distinct segmentation across various dimensions, reflecting the complex interplay of material science, application requirements, and end-user demands. Understanding these segments is crucial for stakeholders to identify high-growth areas and tailor product development or market entry strategies.
Product Type:
The product type segment spans both mature and emerging copper applications within electric vehicles.
- Wiring Harnesses:These complex bundles of electrical wires and connectors transmit power and signals throughout the vehicle. Demand concentrates in all EV production hubs, particularly China, driven by the sheer volume of vehicle output and the need for efficient power delivery.
- Busbars:Solid metallic strips or bars of copper, busbars efficiently distribute high currents from the battery to various components within the EV. Their demand is increasing with higher power densities in batteries and faster charging requirements, especially in European and North American EV models.
- Cables:High-conductivity copper cables facilitate power transmission between major EV components and to the charging port.
- Connectors:Copper-based connectors ensure secure and low-resistance electrical junctions within the vehicle's electrical architecture.
Wiring Harnesses retain volume leadership; Busbars hold the steepest expansion curve.
Application:
The application segment differentiates copper demand based on technical complexity and required purity levels.
- Battery Manufacturing:High-purity copper foils serve as current collectors for battery anodes, demanding precise thickness and surface characteristics. Demand is concentrating in South Korea and China, driven by gigafactory expansion and the pursuit of higher energy density battery cells.
- Electric Motors:Specialized copper windings form the core of electric motors, requiring high thermal stability and electrical conductivity for efficient power conversion. This technically demanding segment sees significant demand from European and North American automotive OEMs focused on performance and efficiency.
- Power Distribution:Copper is essential for robust and efficient power flow from the battery to all vehicle systems.
- Charging Infrastructure:High-capacity copper cables and components are crucial for fast-charging stations and home charging units.
Battery Manufacturing drives specialized copper demand; Electric Motors require high-precision winding solutions.
End User:
The end user segment reflects the diverse procurement patterns across the EV value chain.
- OEMs:Automotive original equipment manufacturers integrate copper components directly into vehicle production, driving specifications and sourcing strategies. Their demand is concentrated in Germany and the US, influenced by domestic content rules and sustainability mandates like the EU's CSRD.
- Charging Station Manufacturers:These entities produce and deploy charging infrastructure, requiring high-conductivity copper for power delivery and thermal management. Demand is expanding rapidly in China and the European Union, driven by government incentives for EV adoption and charging network build-out.
- Aftermarket Providers:These suppliers offer replacement copper components for repair and maintenance of existing EV fleets.
- Fleet Operators:Companies managing large electric vehicle fleets require durable copper components for long-term operational reliability.
OEMs dictate material specifications; Charging Station Manufacturers require robust thermal management solutions.
Technology:
The technology segment delineates copper consumption based on the vehicle's electrification degree and power requirements.
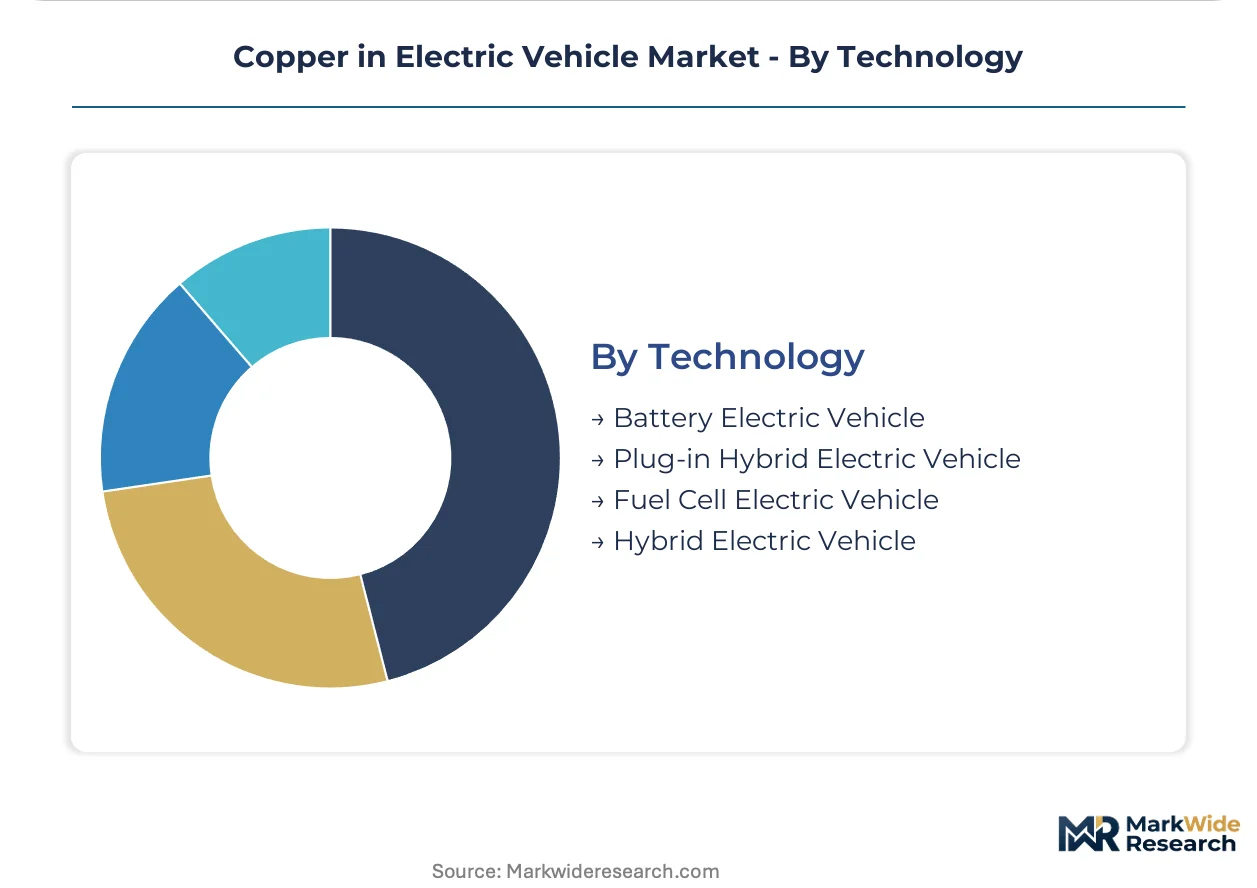
- Battery Electric Vehicle:BEVs are fully electric vehicles, relying solely on battery power and consuming the largest volume of copper per unit. Demand for BEV copper components is highest in China and the US, reflecting their dominant market shares in EV sales and production.
- Plug-in Hybrid Electric Vehicle:PHEVs combine an electric motor with an internal combustion engine, requiring copper for both electric and conventional powertrain components. This segment sees significant demand in Europe, where PHEVs bridge the transition to full electrification.
- Fuel Cell Electric Vehicle:FCEVs use hydrogen to generate electricity, employing copper in their fuel cell stacks and electric drive systems.
- Hybrid Electric Vehicle:HEVs use a combination of gasoline engine and electric motor, utilizing copper for their smaller electric drive systems.
Battery Electric Vehicles command the largest share of copper volume; Fuel Cell Electric Vehicles represent a niche but growing segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's pricing power in copper components for electric vehicles often contrasts with the premium pricing commanded by specialized solutions in European markets. This regional asymmetry influences global supply chain strategies for automotive OEMs. Manufacturers seek to balance cost efficiencies with high-performance requirements across diverse geographies.
China
China's vast electric vehicle production and integrated battery manufacturing ecosystems drive immense demand for automotive-grade copper. Its dual carbon goals further stimulate investment in EV infrastructure and related copper components. The Yangtze River Delta region, with its numerous gigafactories, concentrates significant demand for high-purity copper foils.
United States
The US Inflation Reduction Act incentivizes domestic sourcing for EV battery components, boosting demand for North American copper processing. This legislation aims to build a resilient local supply chain for critical materials. Michigan's automotive corridor and Arizona's copper mining operations are seeing increased investment to support EV production.
Germany
European automotive OEMs in Germany prioritize specialized copper windings for high-performance electric motors, focusing on efficiency and durability. The EU's Corporate Sustainability Reporting Directive (CSRD) influences sourcing decisions towards ethically produced copper. Bavaria and Baden-Württemberg host key automotive innovation hubs driving demand for advanced copper solutions.
South Korea
South Korea's leadership in battery manufacturing fuels a concentrated demand for ultra-thin, high-purity copper foils for anodes. The country's strong R&D focus on advanced battery chemistries requires stringent material specifications. Gyeonggi Province, a hub for battery gigafactories, is a significant consumer of specialized copper materials.
India
India's growing focus on electric mobility and its Production Linked Incentive (PLI) scheme are stimulating domestic copper component manufacturing. This policy aims to localize EV supply chains and reduce import dependency. Maharashtra and Gujarat are emerging as key automotive manufacturing states, increasing their demand for automotive-grade copper.
Copper in Electric Vehicle Market Key Industry Players
Mining giants and specialized refiners split the market for automotive-grade copper, reflecting distinct capabilities across the value chain. The industry exhibits a tiered structure, with large-scale producers supplying raw materials and niche players focusing on high-purity processing for specific EV applications. This landscape is characterized by strategic partnerships between miners and OEMs, alongside significant capital investment in advanced recycling facilities. Companies are also pursuing geographic expansion to secure new markets and diversify supply sources while de-risking supply chains.
Among established mining corporations, Glencore exemplifies a diversified approach, leveraging its recycling operations to offer certified low-carbon copper solutions, appealing to ESG-focused automotive buyers. Freeport-McMoRan, with its significant assets in the Americas, anchors the market through its large-scale, low-cost production capabilities, sustaining a strong competitive position. Codelco, a state-owned enterprise, represents a key supplier for direct long-term offtake agreements with automotive manufacturers, particularly in Europe and North America. These entities collectively shape the foundational supply dynamics for the electric vehicle industry, influencing material availability and pricing.
| Leading Market Players |
|---|
| Glencore |
| Antofagasta PLC |
| Freeport-McMoRan |
| China Molybdenum Co., Ltd. |
| First Quantum Minerals Ltd. |
| Southern Copper Corporation |
| Codelco |
| Rio Tinto |
| BHP Group |
| Others |
Cost & Logistics Intelligence
China's concentrated EV and battery manufacturing ecosystems directly influence margin pooling for copper component suppliers. This upstream concentration dictates pricing power for high-purity copper materials and their specialized processing.
Pricing Analysis
Configured-to-order pricing for specialized copper applications like electric motor windings contrasts with commodity spot pricing for high-volume wiring harnesses. The dominant pricing structure combines long-term offtake agreements for raw copper with transactional per-unit pricing for components. Price differentiation stems from copper purity levels for battery foils and technical specifications for motor windings, alongside ESG certifications for low-carbon copper. Margin pressure for component manufacturers intensifies due to London Metal Exchange price volatility on fixed-price contracts. OEMs exhibit lower price sensitivity for mission-critical, high-performance components, while aftermarket providers are highly price-sensitive.
Supply Chain Analysis
Specialized copper refiners in China and South Korea hold significant capacity for high-purity copper foils and wires. Geographic supply concentration for raw copper centers in Chile and Peru, while advanced processing capacity is strong in China and South Korea. The supply chain draws from copper ore and increasingly from recycled scrap copper. Geopolitical instability in South American mining regions poses a structural risk to raw material availability. Distribution runs through direct long-term offtake agreements between miners and OEMs, alongside traditional metal traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Copper in Electric Vehicle Market is poised for a cyclical recovery, driven by an accelerating global electric vehicle production cycle. This rebound underscores the sustained demand for high-purity copper across the automotive industry.
For Market Incumbents: Harden supply chain resilience through direct, long-term offtake agreements with automotive OEMs. Invest significantly in advanced recycling facilities to offer certified low-carbon copper, mitigating regulatory pressure from the EU's CSRD and the substitution threat from aluminum in lower-value segments. Expand processing capacity in North America to capitalize on the US IRA incentives. Leveraging ESG certification becomes a critical lever for competitive differentiation.
For New Entrants and Emerging Players: Build out capabilities in ultra-thin copper foils for next-generation battery anodes and advanced thermal management solutions for fast-charging infrastructure. The Indian EV market represents a penetrable geography for specialized copper foil and winding wire suppliers. A focused go-to-market angle involves forming joint ventures with local component manufacturers to navigate regional regulatory landscapes and establish domestic production.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across copper mining and advanced processing for EV components, indicating sustained long-term viability. The market will see continued demand for high-purity copper over the next 5-10 years. Acquisition targets should focus on specialized refiners with proprietary electrodeposition technologies and companies offering advanced copper recycling solutions. Quarterly review of regulatory shifts in critical mineral sourcing and battery technology roadmaps is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Offtake Agreements | Secures long-term copper supply for automotive OEMs, de-risking gigafactory roadmaps. |
| Investment in Recycling Infrastructure | Provides certified low-carbon copper, meeting EU CSRD requirements for ESG-focused buyers. |
| Advanced Electrodeposition R&D | Improves yield and consistency for ultra-thin copper foils, critical for battery manufacturers. |
| North American Manufacturing Expansion | Capitalizes on US Inflation Reduction Act incentives, building resilient domestic supply chains. |
| Thermal Management System Development | Addresses extreme thermal loads from fast-charging infrastructure, enabling higher power delivery. |
Research Approach
Findings reconcile primary fieldwork against secondary review of LME pricing data, government EV production statistics, company financial filings, and regulatory documents. The analysis incorporates insights from primary interviews with automotive OEM procurement leads, battery cell engineers, copper mine operations managers, and Tier 1 component suppliers. This approach employed both bottom-up market sizing and top-down validation to ensure data accuracy.
Forecast inputs considered include global EV production forecasts, battery chemistry advancements, and regulatory shifts impacting material sourcing. The analytical framework modeled volume and value across the analysis window, segmented by product type, application, end user, technology, and copper purity grade. Compound Annual Growth Rates were derived from historical trends and projected electric vehicle production volumes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by mining giants or battery technology disruptors would shift outcomes. Forecasts reflect assumptions regarding stable regulatory environments and sustained EV adoption rates. Geopolitical supply disruptions or rapid material substitution in critical applications represent key risk factors. Quarterly review of EV production targets and copper commodity prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Electric Vehicle Home Charger Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
Spain Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
EV Charging Management Software Platform Market