
 Battery Liquid Cooling Plates for Electric Vehicle Market | 2026-2036
Battery Liquid Cooling Plates for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Liquid Cooling Plates for Electric Vehicle Market Insights
ISO 26262 functional safety certification is bifurcating supplier eligibility as battery thermal management complexity escalates. Valeo leverages its European manufacturing footprint to sustain high-volume aluminum stamping capacity for OEM programs. MAHLE GmbH anchors its position through R&D intensity in serpentine-channel designs that optimize coolant flow uniformity across cell arrays.
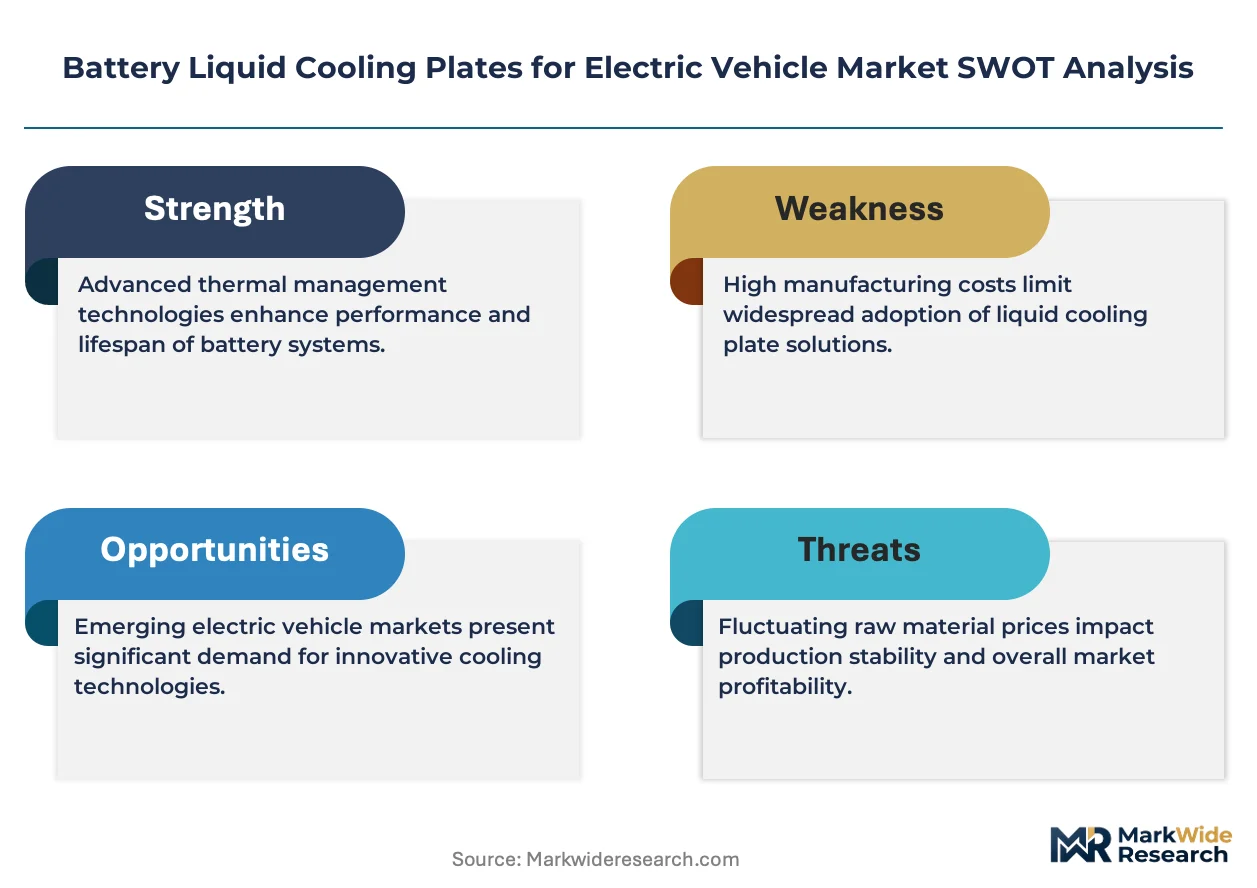
Battery liquid cooling plates are aluminum or copper stamped assemblies with internal channel geometries engineered to maintain cell temperatures within 2-5°C variance, primarily preventing thermal runaway in lithium-ion packs. Active cooling plates dominate current procurement volumes due to their compatibility with fast-charging architectures, while composite material variants represent the fastest-growing segment as manufacturers seek weight reduction without sacrificing thermal conductivity. Passenger vehicles occupy the largest end-user margin pool, though commercial vehicle integration is accelerating as fleet operators specify extended-duty thermal cycles.
NHTSA battery safety investigations in the US, ECE R100 type approval in Europe, and China's GB/T standards collectively mandate validated thermal propagation containment, forcing suppliers to redesign plate geometries and material stacks. The EU Green Deal's embedded carbon reporting requirements are reshaping sourcing decisions for aluminum extrusion and brazing processes. Stakeholders must monitor how solid-state battery architectures alter cooling load profiles and whether OEMs internalize plate production to capture thermal system integration value.
Market Dynamics
Cell-to-pack battery architectures are compressing thermal management integration timelines, forcing cooling plate suppliers to synchronize development cycles with platform engineering rather than module-level procurement.
Growth Catalysts
- Fast-charging infrastructure mandates:China's GB/T standards and Europe's ECE R100 type approval require validated thermal propagation containment, pulling precision-engineered liquid cooling systems into OEM specification sheets.
- Aluminum stamping capability expansion:European tier suppliers are scaling high-volume stamping capacity to meet premium EV platform demand in Germany and adjacent production clusters.
- Commercial fleet electrification:Extended-duty thermal cycle specifications from logistics operators are accelerating integration of active cooling plates into heavy-duty battery packs.
Market Restraints
- Aluminum extrusion cost volatility:Energy-intensive brazing and extrusion processes face input cost pressure from EU Green Deal embedded carbon reporting requirements.
- ISO 26262 certification scarcity:Functional safety qualification bottlenecks are constraining supplier eligibility as thermal management complexity escalates.
- Solid-state battery substitution timeline:Reduced cooling load profiles from emerging solid-state architectures threaten long-term demand for conventional liquid cooling plate volumes.
Strategic Opportunities
- Composite material convergence:Weight-optimized cooling plates combining aluminum channels with polymer structural layers address payload-sensitive commercial vehicle segments.
- India PLI scheme localization:Domestic cell manufacturing incentives are creating captive demand for localized cooling plate fabrication capacity.
- Aftermarket thermal retrofit channels:Independent service networks for battery pack refurbishment represent an underdeveloped distribution pathway for replacement cooling plate sales.
Industry Challenges
- Serpentine-channel engineering talent scarcity:Specialized CFD modeling expertise for optimizing coolant flow uniformity remains concentrated among a limited pool of thermal systems engineers.
- Platform-specific tooling amortization:Cell-to-pack integration requires dedicated stamping die investments with uncertain program volume guarantees from OEM customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Liquid Cooling Plates for Electric Vehicle Market |
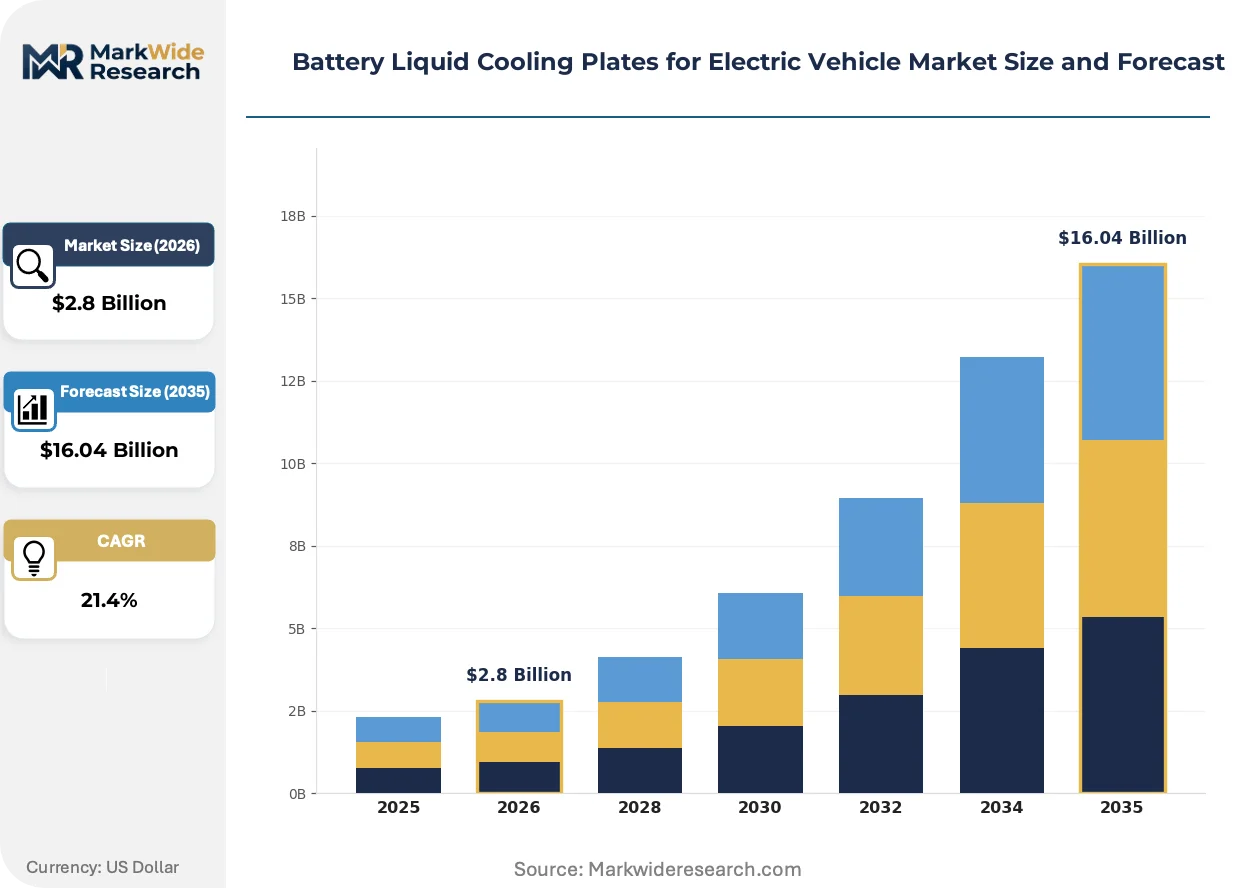
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $16.04 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Cooling Plates, Passive Cooling Plates, Hybrid Cooling Plates, Heat Exchangers Material: Aluminum, Copper, Composite Materials, Thermally Conductive Plastics End User: Passenger Vehicles, Commercial Vehicles, Electric Buses, Two-Wheelers Integration Level: OEM Integration, Aftermarket Solutions, Independent Suppliers, Modular Systems |
| Companies Covered | Valeo, MAHLE GmbH, Dana Limited, Sanhua Automotive, Boyd Corporation, BorgWarner Inc., Modine Manufacturing Company, Hanon Systems, Sogefi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Liquid Cooling Plates for Electric Vehicle Market Trends and Innovations
Cooling plate architectures are pivoting from modular bolt-on components to structurally integrated thermal management systems that bear mechanical load while maintaining cell temperature uniformity.
Serpentine-channel geometries are bifurcating supplier technical capabilities. Advanced designs from MAHLE GmbH and specialized European manufacturers optimize coolant distribution across irregular cell arrays. Premium EV platforms in Germany specify these precision-engineered channels for fast-charging compatibility. The technology gap is compressing margin pools for stamped-plate commodity producers while rewarding R&D-intensive specialists.
ECE R100 type approval and China's NMPA cell-to-pack regulations are forcing redesign cycles across supplier engineering departments. Validation protocols now mandate thermal propagation containment demonstration under abuse conditions. Plate geometries and material stacks require recertification, extending development timelines and concentrating procurement decisions around pre-qualified suppliers with established regulatory dossiers.
Fleet operators are consolidating thermal system specification authority away from vehicle OEMs toward direct supplier engagement. Large logistics customers in Germany and China now issue extended-duty thermal cycle requirements as standalone procurement documents. This disintermediation compresses pricing transparency and rewards cooling plate manufacturers with direct fleet engineering relationships and aftermarket service infrastructure.
Battery Liquid Cooling Plates for Electric Vehicle Market Segmentation
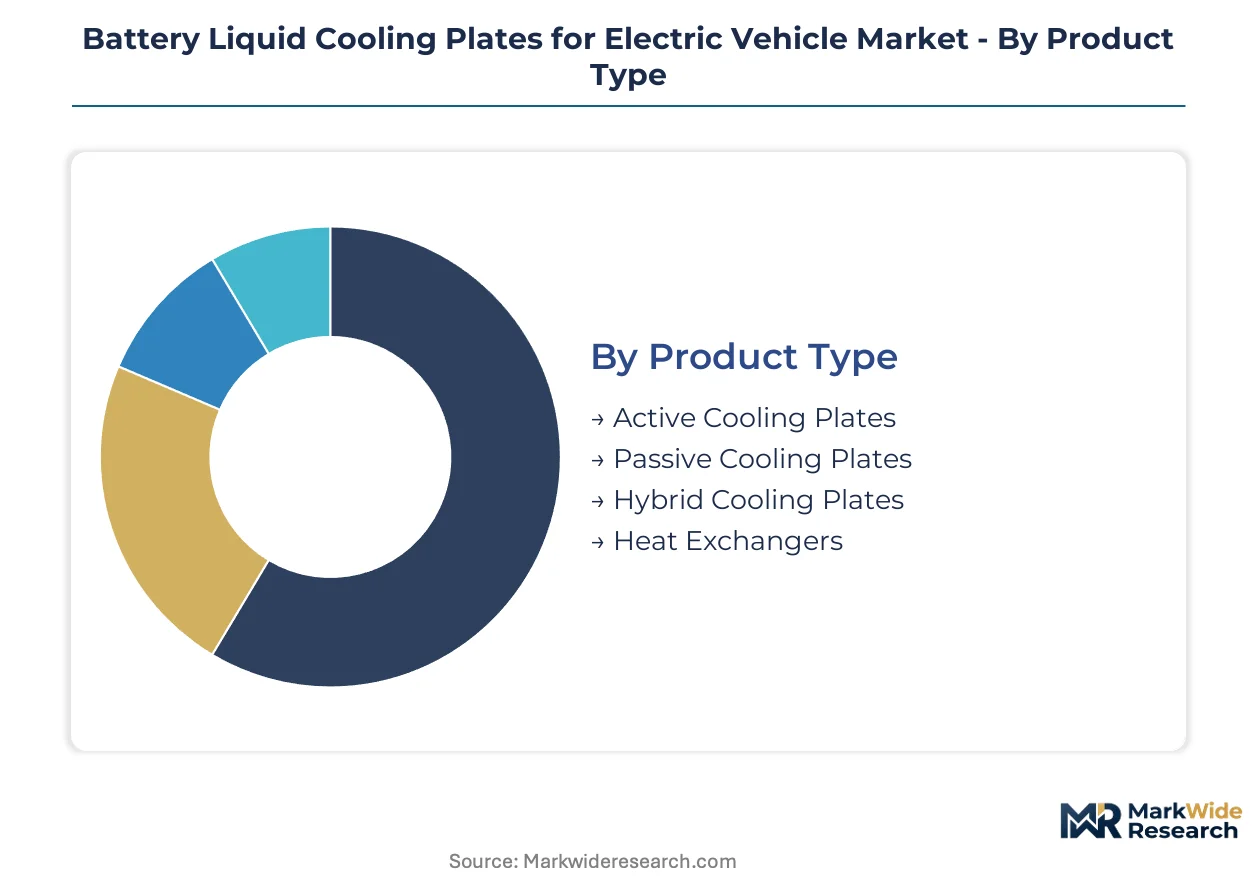
Cooling plate procurement diverges sharply across thermal load profiles and regulatory validation tiers. Each segment category reflects distinct engineering trade-offs between fast-charging compatibility, weight constraints, and manufacturing scalability.
Product Type:
Active Cooling Plates and Passive Cooling Plates dominate procurement volumes, though regulatory differentiation around thermal propagation containment is compressing supplier eligibility for legacy designs. China's GB/T standards and Europe's ECE R100 type approval mandate validated active cooling architectures for fast-charging platforms.
- Active Cooling Plates:Pump-driven liquid circulation systems with precision-engineered internal channel geometries maintain cell temperatures within narrow variance bands during high-C-rate charging cycles. Demand concentrates in Germany's premium EV platforms where OEMs specify serpentine-channel designs for thermal uniformity validation under ECE R100 protocols.
- Passive Cooling Plates:Conductive aluminum or copper stampings rely on ambient dissipation and thermal mass, suited for lower energy density packs with modest duty cycles. Procurement is accelerating in India's two-wheeler electrification programs where cost sensitivity outweighs fast-charging requirements.
- Hybrid Cooling Plates:Dual-mode architectures combine passive baseline operation with active supplemental loops for thermal spike events. Fleet operators in extended-duty logistics applications specify these for reduced parasitic pump load during highway cruising.
- Heat Exchangers:Plate-to-refrigerant interfaces enable direct cooling integration with vehicle HVAC systems. Japanese OEMs favor these for platform thermal system consolidation.
Active Cooling Plates handle the majority of throughput; Hybrid Cooling Plates are climbing the fastest on share as fleet electrification accelerates.
Material:
Material selection pivots on the EU Green Deal's embedded carbon reporting requirements, reshaping sourcing for energy-intensive aluminum extrusion and brazing processes. Suppliers are repositioning around lower-carbon primary aluminum and recycled content verification.
- Aluminum:Stamped 3xxx and 6xxx series alloys deliver optimal thermal conductivity-to-weight ratios for cell-to-pack architectures. European tier suppliers are scaling high-volume stamping capacity to meet German OEM demand, though brazing process emissions face tightening EU carbon border scrutiny.
- Copper:Superior thermal conductivity suits high-performance applications with extreme fast-charging duty cycles. Procurement concentrates in Chinese NEV platforms where MIIT efficiency mandates prioritize thermal management effectiveness over material cost.
- Composite Materials:Aluminum-channel-polymer-structural laminates address payload-sensitive commercial vehicle segments. These are gaining share fastest as weight reduction targets harden.
- Thermally Conductive Plastics:Injection-moldable polymer matrices with ceramic fillers enable complex geometries at reduced tooling cost. Two-wheeler manufacturers in India specify these for cost-optimized thermal management.
Aluminum commands the dominant material share; Composite Materials are expanding most quickly as commercial fleet specifications tighten.
End User:
End-user segmentation reflects divergent thermal cycle specifications and procurement authority structures. Fleet operators are consolidating direct supplier engagement away from vehicle OEM intermediation.
- Passenger Vehicles:Premium EV platforms in Germany specify precision-engineered liquid cooling systems with ISO 26262 functional safety certification. Cell-to-pack integration timelines compress development cycles around platform engineering synchronization.
- Commercial Vehicles:Extended-duty thermal cycle requirements from logistics operators drive active cooling plate integration into heavy-duty battery packs. Direct fleet procurement documents now specify thermal performance independent of OEM platform selection.
- Electric Buses:High-capacity pack architectures with continuous operation profiles demand redundant cooling loop designs. Chinese municipal procurement mandates NMPA-validated thermal propagation containment.
- Two-Wheelers:Cost-optimized passive or hybrid cooling solutions dominate India's PLI scheme-supported domestic manufacturing programs.
Passenger Vehicles anchor current volume; Commercial Vehicles are gaining share fastest as fleet electrification accelerates.
Integration Level:
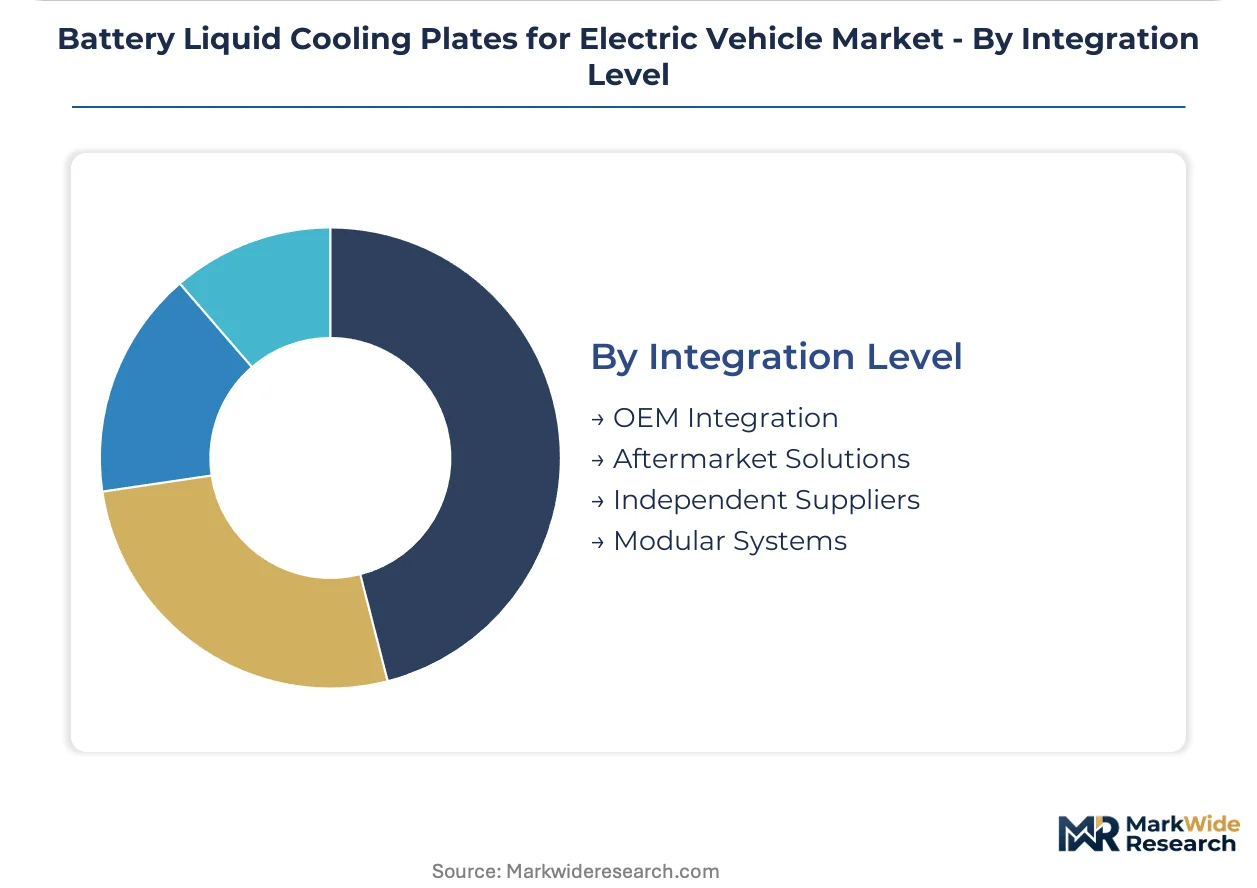
Integration architecture determines margin capture and supplier relationship durability. Cell-to-pack trends are displacing modular procurement in favor of structurally integrated thermal management systems.
- OEM Integration:Captive thermal system engineering by vehicle manufacturers internalizes plate production to capture integration value. Premium German OEMs are expanding in-house aluminum stamping for platform control.
- Aftermarket Solutions:Independent service networks for battery pack refurbishment represent underdeveloped distribution pathways. Validation protocols for replacement plates remain inconsistent across national type approval frameworks.
- Independent Suppliers:Specialized manufacturers with established regulatory dossiers concentrate procurement decisions for cell-to-pack programs. ECE R100 and NMPA pre-qualification creates supplier tiering.
- Modular Systems:Bolt-on cooling architectures persist in retrofit applications and lower-volume platforms with extended model cycles.
OEM Integration captures the dominant value pool; Aftermarket Solutions are expanding most quickly as first-generation EV battery packs approach refurbishment thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT efficiency mandates and Germany's KBA safety protocols are redrawing procurement geography for battery liquid cooling plates. National regulators now embed thermal management requirements directly into vehicle type approval frameworks.
China
MIIT dual carbon goals and NMPA cell-to-pack regulations mandate validated thermal propagation containment for domestic NEV platforms. GB/T standards pull precision-engineered liquid cooling systems into OEM specification sheets. Yangtze River Delta manufacturing clusters concentrate aluminum stamping capacity for BYD and CATL supply programs.
Germany
Premium EV platforms from BMW and Mercedes-Benz specify serpentine-channel designs for ECE R100 type approval compliance. KBA enforcement of thermal uniformity validation compresses supplier qualification timelines. Bavaria's automotive engineering corridor anchors European R&D intensity in coolant flow optimization.
United States
NHTSA battery safety investigations accelerate thermal management procurement for Detroit Three electrification programs. IRA domestic content incentives reshape sourcing decisions for aluminum extrusion and brazing processes. Michigan's battery belt concentrates cooling plate integration with cell manufacturing facilities.
India
PLI scheme localization creates captive demand for domestic cooling plate fabrication capacity alongside cell manufacturing investments. BIS standards for two-wheeler thermal management prioritize cost-optimized passive and hybrid solutions. Tamil Nadu and Gujarat automotive corridors attract tier supplier stamping investments.
South Korea
MFDS alignment with international battery safety protocols drives thermal system validation requirements for Hyundai-Kia platforms. Government EV subsidies tie to NMPA-equivalent thermal propagation standards. Seoul Capital Area engineering centers specialize in CFD modeling for irregular cell array geometries.
Battery Liquid Cooling Plates for Electric Vehicle Market Competitive Landscape
Player mix skews toward European automotive thermal specialists with established regulatory dossiers. Market structure concentrates procurement decisions around pre-qualified suppliers capable of ECE R100 and NMPA validation. Three archetypes dominate: integrated thermal system houses with captive stamping capacity, independent aluminum fabricators with serpentine-channel expertise, and diversified industrial conglomerates leveraging materials science portfolios. Competitive moves center on backward integration into aluminum extrusion and strategic partnerships with cell manufacturers for co-development programs.
Among European thermal system houses, Valeo and MAHLE GmbH occupy positions within the premium-tier supplier vector. Valeo represents the integrated archetype with manufacturing footprint advantages, while MAHLE GmbH exemplifies R&D-intensive specialization in precision channel geometries. Dana Limited anchors the diversified industrial conglomerate tier with materials science capabilities spanning multiple thermal management applications.
| Leading Market Players |
|---|
| Valeo |
| MAHLE GmbH |
| Dana Limited |
| Sanhua Automotive |
| Boyd Corporation |
| BorgWarner Inc. |
| Modine Manufacturing Company |
| Hanon Systems |
| Sogefi Group |
| Others |
Pricing and Supply Chain Analysis
High-volume aluminum stamping capacity utilization above 85% in Germany and China's Yangtze River Delta manufacturing clusters compresses margin pools for mid-tier suppliers while reinforcing price floors for ECE R100 and NMPA pre-qualified manufacturers. OEM platform engineering synchronization demands and ISO 26262 certification scarcity concentrate procurement authority around established European thermal system houses.
Pricing Analysis
Certification grade creates the primary spread between supplier tiers, with ISO 26262 functional safety qualification commanding premium positioning against commodity stamped-plate producers. Three-tier pricing structure separates ECE R100-validated serpentine-channel specialists from standard active cooling plate manufacturers and passive aluminum stamping suppliers. Cost compression in the passive tier intensifies as India's PLI scheme localization attracts cost-optimized domestic fabrication. Fleet operators issuing direct thermal cycle specifications exhibit lowest price sensitivity; two-wheeler manufacturers in India show highest sensitivity to unit economics.
Supply Chain Analysis
China, Germany, and South Korea anchor precision aluminum stamping and serpentine-channel engineering capacity for battery liquid cooling plates. Raw material sourcing draws from 3xxx and 6xxx series aluminum alloy producers, copper cathode suppliers for high-conductivity variants, and polymer resin providers for composite structural laminates. Single-source vulnerability concentrates in European brazing process equipment and specialized CFD modeling talent pools. Distribution runs through Tier 1 thermal system integrators with direct OEM platform engineering relationships, supplemented by emerging aftermarket refurbishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized serpentine-channel engineering expertise and ECE R100 regulatory dossier compilation capabilities remain concentrated among a limited supplier pool, constraining market entry and amplifying returns for incumbents with validated thermal propagation containment protocols.
For Market Incumbents: Compound ISO 26262 certification depth across multiple OEM platform programs to solidify supplier tiering advantages against emerging aluminum fabricators from India. Backward integration into lower-carbon primary aluminum sourcing addresses EU Green Deal embedded carbon reporting requirements before carbon border adjustments tighten. Defensive positioning against solid-state battery substitution timelines requires R&D allocation to hybrid cooling architectures compatible with reduced thermal load profiles. For New Entrants and Emerging Players: Anchor in India's PLI scheme-supported domestic manufacturing corridor where localized cooling plate fabrication capacity lags cell manufacturing investments. Target aftermarket thermal retrofit channels for first-generation EV battery packs approaching refurbishment thresholds. Go-to-market leverage rests on BIS standards alignment for cost-optimized passive and hybrid cooling solutions in two-wheeler electrification programs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized manufacturers with established NMPA and ECE R100 regulatory dossiers over diversified industrial conglomerates lacking thermal systems focus. Long-term viability hinges on serpentine-channel engineering talent retention and cell-to-pack co-development program pipelines. Acquisition target archetype: European mid-cap aluminum fabricators with dormant ISO 26262 certification pathways and underutilized stamping capacity. Signal to monitor: OEM announcements of in-house thermal system integration decisions that displace independent supplier volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Serpentine-Channel R&D Intensification | MAHLE GmbH's precision geometries establish technical moats against commodity stamped-plate competitors. |
| Cell-to-Pack Co-Development Programs | Direct engineering synchronization with CATL and BYD compresses competitor qualification timelines. |
| EU Green Deal Carbon Reporting Compliance | Lower-carbon aluminum sourcing secures procurement preference from BMW and Mercedes-Benz platforms. |
| Aftermarket Service Infrastructure Buildout | Independent battery pack refurbishment networks unlock replacement cooling plate revenue streams. |
| Composite Material Manufacturing Scale-Up | Aluminum-polymer laminates address payload-sensitive commercial vehicle fleet specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, thermal systems R&D leads, and aftermarket service network operators; and secondary validation against MIIT efficiency mandate filings, ECE R100 type approval databases, KBA enforcement protocols, and aluminum trade flow customs records. Bottom-up unit demand modeling across vehicle production clusters triangulated with top-down thermal management content-per-vehicle estimates derived from OEM specification sheet analysis.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, material stack, end-user thermal cycle specification, and integration architecture. CAGRs were derived from regression analysis of historical procurement patterns against regulatory mandate implementation timelines. Industry-specific forecast inputs included cell-to-pack adoption curves, solid-state battery commercialization trajectories, and fleet operator direct procurement authority consolidation rates.
Material uncertainties — solid-state battery thermal load profile reductions, OEM vertical integration decisions, and EU carbon border adjustment enforcement timing — sit outside the modeled envelope. Forecasts reflect assumptions about aluminum extrusion cost stability and serpentine-channel engineering talent pool expansion. Recalibration cycles align with material shifts in NMPA regulatory updates and ECE R100 revision protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Electric Vehicle Showroom Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Global EV Charging Adapter Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market