
 Combined Charging System Market | 2026-2036
Combined Charging System Market Size, Share, and Industry Trends Forecast 2026-2036
Combined Charging System Market Outlook
ISO 15118-20 certification is redrawing competitive boundaries for bidirectional power flow capabilities. ABB leverages its European manufacturing footprint to sustain high-volume CCS2 production for highway corridors. Siemens AG anchors its position through integrated grid-to-charger software stacks that manage load balancing across utility networks.
The Combined Charging System is an open-standard charging architecture combining AC and DC charging through a single inlet, supporting power levels from 50 kW to 350 kW via pulse-width modulation communication between vehicle and station. Its primary purpose is enabling interoperable fast charging across multiple original equipment manufacturers without proprietary adapters. CCS1 connectors dominate North American passenger car installations, while CCS2 variants lead European deployments where Type 2 AC compatibility is mandated. The 350 kW charging power rating segment attracts the strongest infrastructure investment as commercial fleets and highway operators seek sub-20-minute recharge cycles for long-haul electric trucks.
The European Union's Alternative Fuels Infrastructure Regulation and the U.S. National Electric Vehicle Infrastructure program are accelerating standardized connector deployment through binding interoperability mandates and federal funding eligibility rules. Germany's KBA enforces type-approval protocols that filter non-compliant charging hardware from public roadway access. Stakeholders must monitor how NEVI funding disbursement timelines interact with state-level electrical permitting backlogs to gauge actual station commissioning velocity.
Market Dynamics
The Combined Charging System market is being fundamentally restructured by the EU's Alternative Fuels Infrastructure Regulation mandating uniform fast-charging standards along major transport corridors, which forces hardware manufacturers to consolidate around certified CCS2 configurations and eliminates proprietary connector variants from public infrastructure eligibility.
Growth Catalysts
- AFIR corridor mandates:The EU's binding interoperability requirements for trans-European transport networks are compelling highway operators to standardize on CCS2 hardware, creating guaranteed demand pools for certified equipment manufacturers.
- Commercial fleet electrification:Logistics operators deploying electric delivery vehicles across Germany, France, and the Netherlands require high-power charging infrastructure that CCS architecture uniquely supports through its 350 kW pulse-width modulation protocol.
- ISO 15118-20 certification:The new standard for bidirectional power flow is opening revenue streams for vehicle-to-grid services, incentivizing utilities to fund CCS infrastructure deployment as distributed energy assets.
Market Restraints
- Semiconductor supply concentration:Power electronics for DC fast chargers depend on silicon carbide modules concentrated among East Asian foundries, exposing European and North American station builders to input cost volatility and allocation constraints.
- Grid interconnection bottlenecks:Utility approval timelines for high-capacity transformer installations frequently exceed 18 months in jurisdictions with understaffed electrical permitting offices, compressing actual commissioning velocity relative to equipment manufacturing capacity.
- Chademo residual base:Existing Japanese-designed fast-charging infrastructure in early-adopter markets creates stranded asset risk for operators considering full CCS migration before hardware end-of-life.
Strategic Opportunities
- NEVI funding eligibility:The U.S. federal program's interoperability requirements create a captive demand window for CCS1-certified hardware through 2026, favoring suppliers with established North American manufacturing footprints.
- Heavy-duty truck corridors:Long-haul electric freight routes along Rhine-Alpine and Scandinavian-Mediterranean corridors represent underpenetrated demand for megawatt-class charging extensions of CCS architecture.
- Software-integrated charging:Convergence between charger management systems and utility demand-response platforms enables operators to capture grid services revenue beyond electricity sales.
Industry Challenges
- ISO 15118-20 implementation timeline:The certification process for bidirectional communication stacks requires 12-18 months of validation testing, compressing product launch windows for suppliers targeting 2025-2026 infrastructure funding cycles.
- Legacy fleet integration:Mixed-voltage charging requirements from first-generation electric commercial vehicles complicate station design for operators serving heterogeneous fleet compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combined Charging System Market |
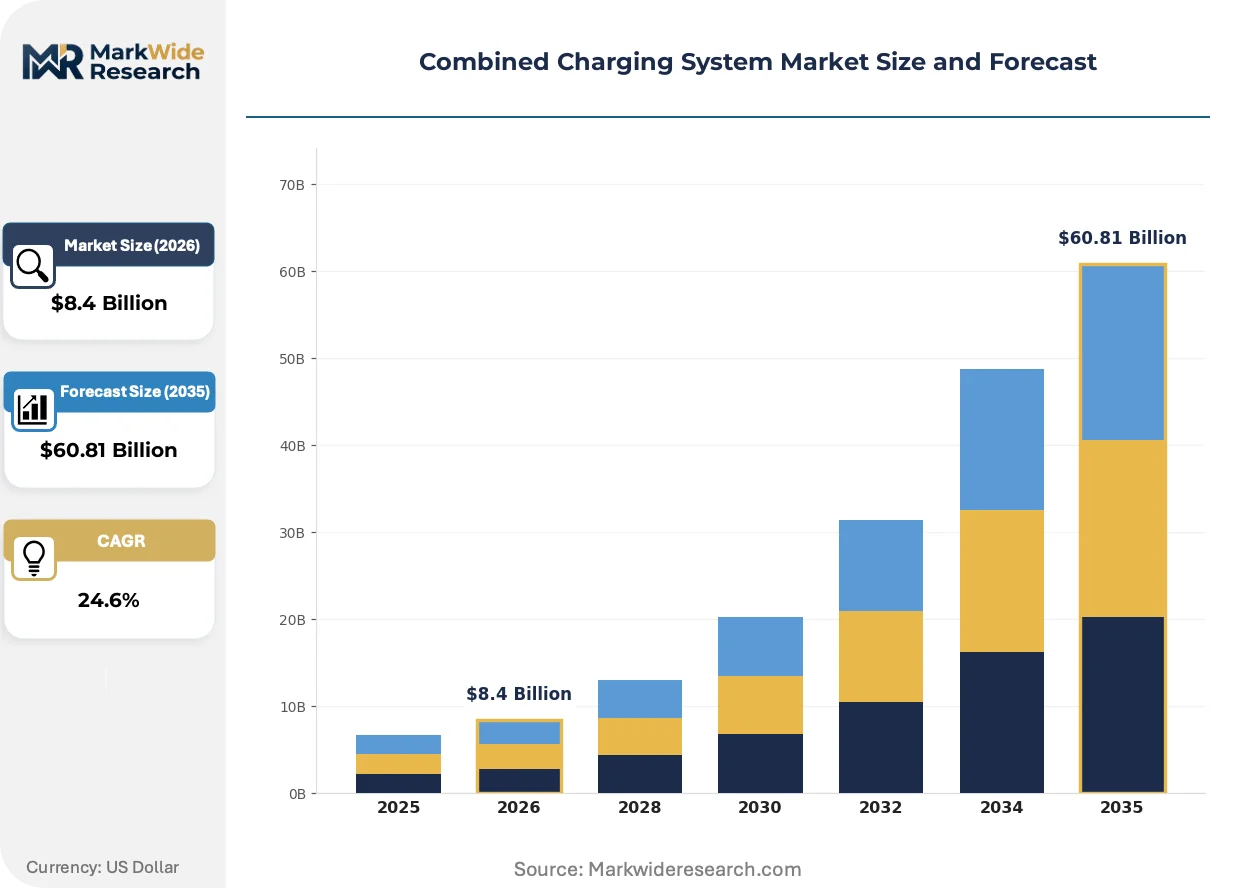
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connector Type: Type 1, Type 2, CCS1, CCS2, CHAdeMO, Tesla Charging Power Rating: 7 kW, 22 kW, 50 kW, 150 kW, 350 kW, 500 kW Vehicle Type: Passenger Cars, Commercial Vans, Buses, Trucks, Two-Wheelers, Delivery Vehicles Charging Station Ownership: Private Operators, Fleet Operators, Public Entities, Retail Chains, Utility Companies, Workplace Facilities |
| Companies Covered | ChargePoint, Eaton, ABB, General Electric Company, EVBox, Siemens AG, Tesla, BP Chargemaster, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combined Charging System Market Strategic Shifts
Three forces are actively restructuring the Combined Charging System landscape: silicon carbide power electronics compressing hardware footprints, regulatory mandates accelerating standardization timelines, and procurement models shifting from equipment sales to charging-as-a-service platforms.
Silicon carbide MOSFETs in DC power conversion modules are supplanting traditional silicon IGBT designs across 350 kW CCS installations. Highway corridor operators in Germany and the Netherlands are specifying SiC-based rectifiers for new stations, drawn by 40% reductions in cooling system mass and transformer footprint. This technology compression is enabling containerized charging depots that bypass on-site construction timelines.
REACH substance restrictions and the EU F-Gas Regulation are reshaping thermal management material selection for liquid-cooled charging cables. Manufacturers must reformulate dielectric fluids and cable jacket compounds to maintain fire safety ratings while eliminating perfluorinated substances. The compliance burden falls heaviest on high-amperage cable suppliers serving the 500 A charging segment where thermal loads are most severe.
Fleet operators are consolidating procurement decisions at the corporate level, displacing decentralized site-by-site purchasing that previously dominated commercial charging infrastructure. Large logistics providers now negotiate master service agreements covering hardware, installation, and energy management across hundreds of depots. This concentration is most visible in the Netherlands where consolidated tendering for electric delivery vehicle infrastructure has reduced supplier counts by half since 2022.
Combined Charging System Market Segmentation
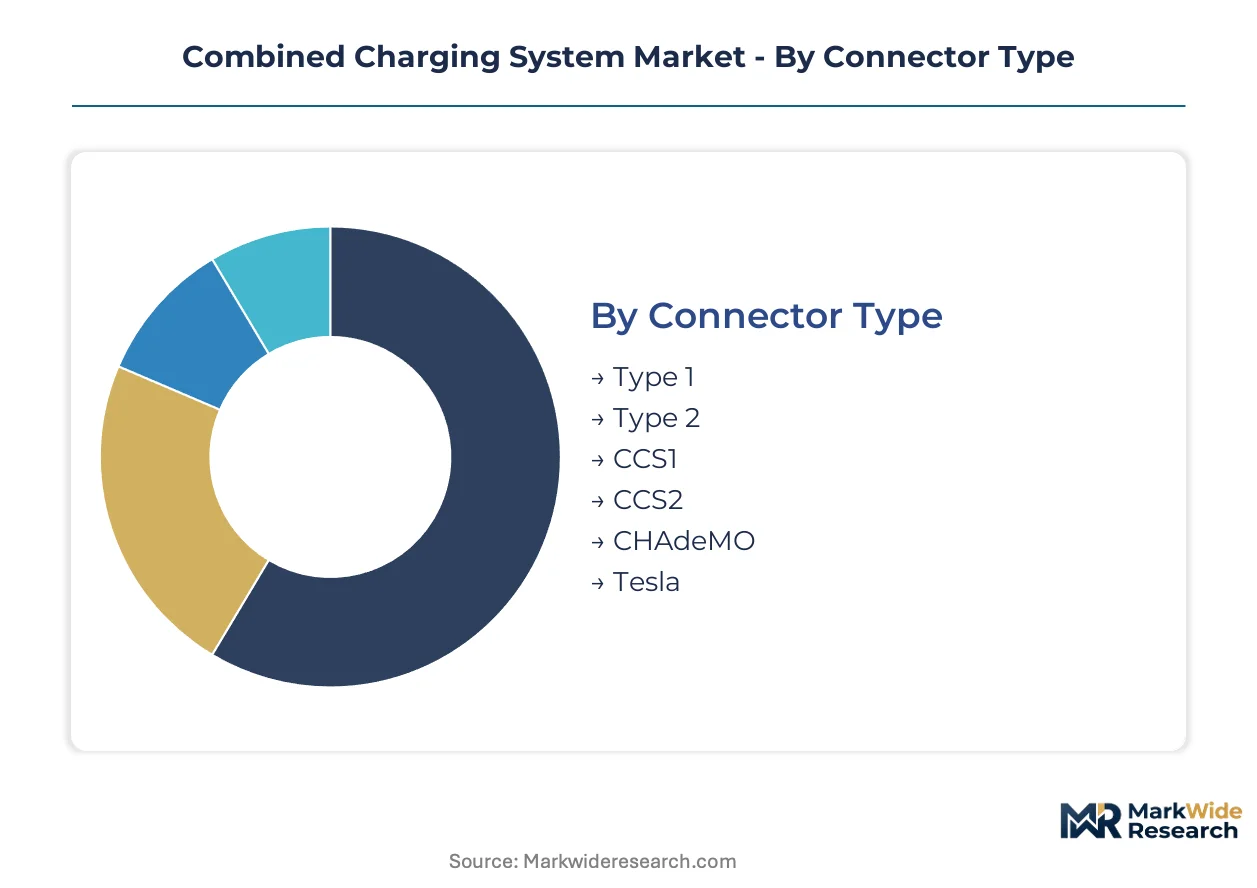
Segmentation in the Combined Charging System market reveals how connector standards, power ratings, and ownership models fragment procurement decisions across geographies. Fleet operators in Germany and the Netherlands select different hardware configurations than highway corridor developers in France or workplace facility managers in Belgium.
Connector Type:
Type 2 and CCS2 dominate European domestic installations, while CCS1 serves North American export markets. CHAdeMO and Tesla connectors persist in legacy infrastructure but face exclusion from AFIR-funded corridors.
- Type 1:Single-phase AC connector supporting up to 7.4 kW charging through J1772 inlet geometry. Demand concentrates in North American residential and workplace installations where single-phase distribution dominates suburban electrical infrastructure.
- Type 2:Three-phase AC connector delivering up to 43 kW through Mennekes-designed inlet with additional signal pins for DC fast charging preparation. German and Dutch public charging networks specify Type 2 for AC destination charging at retail and municipal sites.
- CCS1:Combined inlet integrating J1772 AC connector with two DC fast charging pins below. U.S. NEVI program eligibility requirements channel federal funding toward CCS1-certified hardware for interstate highway corridors.
- CCS2:European variant combining Type 2 AC inlet with DC power pins in single housing. EU AFIR mandates standardize CCS2 as the sole connector eligible for trans-European transport network funding.
- CHAdeMO:Japanese-developed DC fast charging protocol enabling bidirectional power flow through separate connector from AC inlet. Early-adopter markets in Japan and limited European deployments retain installed base despite declining new installations.
- Tesla:Proprietary connector design supporting AC and DC charging through unified inlet geometry. Tesla maintains parallel Supercharger network while offering CCS adapter compatibility for third-party station access.
CCS2 commands the established base across European public infrastructure. The steepest expansion runs through CCS1 as NEVI disbursements accelerate U.S. highway corridor buildout.
Charging Power Rating:
Power rating selection tracks vehicle battery capacity and dwell time economics. Commercial fleet operators prioritize higher kW ratings to minimize asset downtime, while residential and workplace sites optimize for lower-cost, lower-power hardware.
- 7 kW:Single-phase AC residential charging delivering overnight full charges for passenger cars with battery capacities below 80 kWh. German single-family home installations favor 7 kW wallboxes to avoid three-phase electrical service upgrades.
- 22 kW:Three-phase AC charging supporting faster residential turnaround and workplace opportunity charging. French workplace facility managers specify 22 kW for employee charging to accommodate multiple vehicles during standard work shifts.
- 50 kW:Entry-level DC fast charging enabling 80% battery replenishment in 30-60 minutes for early electric vehicle models. Urban retail chains in Belgium deploy 50 kW units to attract customers with complimentary charging during shopping visits.
- 150 kW:Mid-tier DC fast charging reducing dwell times to 20-30 minutes for 400V architecture passenger vehicles. Dutch highway service area operators install 150 kW as baseline specification for corridor coverage.
- 350 kW:High-power DC charging supporting 800V battery architectures with sub-20-minute recharge cycles. Long-haul electric truck corridors along Rhine-Alpine routes specify 350 kW for mandatory driver rest period charging.
- 500 kW:Megawatt-class charging extension for heavy-duty freight applications requiring continuous operation with minimal stops. German logistics operators pilot 500 kW depot charging for electric tractor-trailers on fixed distribution routes.
350 kW hardware captures the infrastructure investment priority. The steepest expansion trajectory belongs to 500 kW as heavy-duty electrification accelerates.
Vehicle Type:
Vehicle electrification maturity varies sharply across segments, dictating connector and power rating requirements. Passenger car standardization enables scale economies that commercial vehicle segments have yet to achieve.
- Passenger Cars:Dominant electrification segment with standardized CCS compatibility across European and North American original equipment manufacturers. Battery capacities from 50 kWh to 120 kWh drive demand for 150 kW corridor charging.
- Commercial Vans:Last-mile delivery electrification concentrating in Dutch and German urban logistics fleets. Mercedes-Benz eSprinter and Ford E-Transit compatibility with CCS2 enables shared depot infrastructure.
- Buses:Municipal transit electrification with overnight depot charging and opportunity charging at route terminals. Belgian and Dutch public transport authorities specify 150-350 kW pantograph or plug-in systems.
- Trucks:Long-haul freight electrification requiring megawatt-class charging for regulatory compliance with driver hour restrictions. German KBA type-approval protocols for electric heavy-duty vehicles mandate CCS2 compatibility.
- Two-Wheelers:Electric motorcycle and scooter charging through adapted connectors or standard residential outlets. French and Italian urban mobility programs subsidize charging infrastructure for light electric vehicle adoption.
- Delivery Vehicles:Dedicated last-mile logistics segment with standardized battery swap and fast-charging protocols. Consolidated tendering by Netherlands-based fleet operators specifies 150 kW CCS2 for electric delivery van depots.
Passenger cars anchor installed charging capacity. Delivery vehicles are climbing the fastest as fleet electrification procurement concentrates at corporate level.
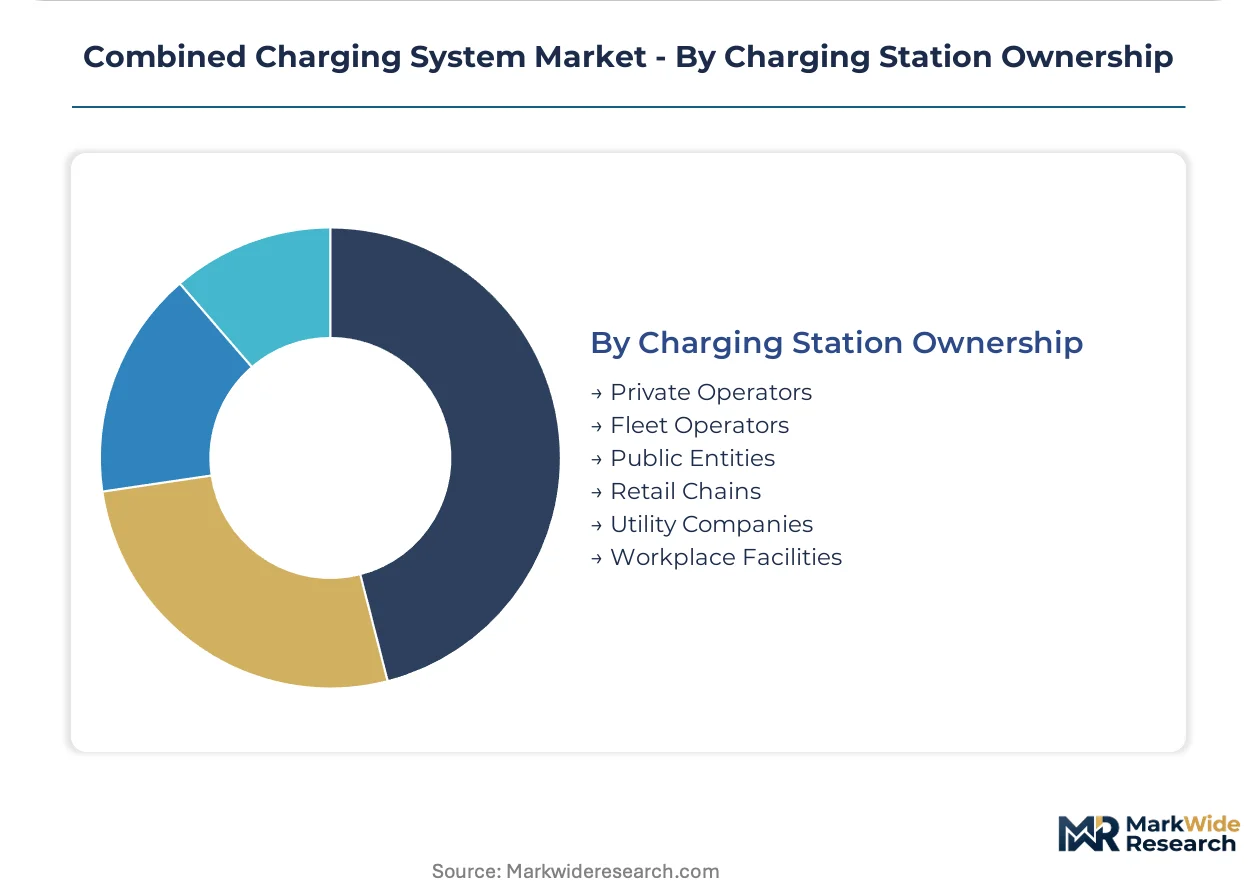
Charging Station Ownership:
Ownership model determines procurement sophistication and operational priorities. Utility companies integrate grid services revenue, while retail chains treat charging as customer acquisition cost.
- Private Operators:Independent charging network developers securing sites through commercial leases and revenue-sharing agreements. Dutch charging network operators expand through municipal concession contracts for public street parking integration.
- Fleet Operators:Logistics and transport companies deploying captive charging infrastructure for vehicle electrification commitments. German parcel delivery operators build depot charging at distribution centers to support electric van deployment targets.
- Public Entities:Municipal and regional governments installing charging as public service infrastructure with subsidy support. French communes leverage EU Recovery Fund allocations for rural charging coverage expansion.
- Retail Chains:Supermarkets and shopping centers deploying charging to extend customer dwell time and visit frequency. Belgian retail groups specify 50-150 kW units at hypermarket locations with 45-minute average shopping duration.
- Utility Companies:Electricity suppliers integrating charging infrastructure with demand response and grid balancing services. German municipal utilities capture ISO 15118-20 bidirectional revenue streams through vehicle-to-grid pilot programs.
- Workplace Facilities:Employer-sponsored charging for employee and fleet vehicle access during working hours. Netherlands workplace charging mandates for large employers accelerate AC destination charging installation.
Fleet operators command the most aggressive expansion timelines. Utility companies are gaining share fastest through integrated energy service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government funding eligibility rules and binding interoperability mandates are channeling infrastructure investment toward standardized CCS hardware across major economies. National programs in North America and Europe create guaranteed demand windows for certified equipment manufacturers.
United States
NEVI program disbursements prioritize CCS1-certified hardware for interstate highway corridors. The Federal Highway Administration coordinates with state DOTs to resolve electrical permitting backlogs. Texas and California account for the densest concentration of new station commissioning activity.
Germany
KBA type-approval protocols filter non-compliant charging hardware from public roadway access. The EU AFIR mandates standardize CCS2 as the sole connector eligible for trans-European transport network funding. Bavaria and North Rhine-Westphalia lead depot charging deployment for electric freight fleets.
France
EU Recovery Fund allocations support rural charging coverage expansion through municipal concession contracts. The French communes leverage AFIR corridor mandates to accelerate CCS2 standardization. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate workplace charging installation for large employers.
Netherlands
Consolidated tendering by logistics operators has reduced supplier counts by half since 2022. Workplace charging mandates for large employers accelerate AC destination charging installation. The Randstad and Eindhoven Region anchor electric delivery vehicle depot infrastructure.
China
GB standards and MIIT regulations shape domestic charging architecture parallel to CCS development. Dual carbon goals accelerate commercial fleet electrification procurement at the corporate level. The Yangtze River Delta and Pearl River Delta concentrate silicon carbide power electronics manufacturing for DC fast charger modules.
Combined Charging System Market Competitive Environment
Listed leaders compete with private specialists across hardware certification and software integration capabilities. The vendor base organizes around three strategic tiers: integrated industrial conglomerates with grid-to-charger software stacks, pure-play charging network operators with site acquisition expertise, and component specialists in power electronics and thermal management. Consolidation pressure intensifies as fleet operators consolidate procurement decisions at the corporate level. Dominant competitive moves include strategic partnerships with utilities for grid services revenue and capacity expansion to capture NEVI and AFIR funding windows.
Within the integrated industrial tier, ABB and Siemens AG occupy positions spanning European manufacturing footprints and utility-scale project execution. ChargePoint represents the pure-play network operator archetype with North American site density. Among component specialists, Eaton anchors power electronics supply relationships with station builders seeking silicon carbide module sourcing.
| Leading Market Players |
|---|
| ChargePoint |
| Eaton |
| ABB |
| General Electric Company |
| EVBox |
| Siemens AG |
| Tesla |
| BP Chargemaster |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
EU AFIR corridor mandates gate both supplier qualification and price differentiation by restricting public infrastructure eligibility to CCS2-certified hardware, compressing margins for uncertified manufacturers while allowing validated producers to command premium positioning for highway corridor deployments.
Pricing Analysis
Certification level creates the primary spread between hardware tiers. Pricing stratifies across ISO 15118-20 certified bidirectional systems, baseline CCS2-compliant units, and legacy non-compliant inventory. Cost compression in entry-level 50 kW hardware is intensifying because silicon carbide module shortages force margin sacrifice to secure allocation. Fleet operators exhibit the highest price sensitivity due to volume procurement consolidation, while utility companies prioritize grid services integration over unit economics.
Supply Chain Analysis
Strategic stockpiling of silicon carbide MOSFETs and liquid-cooled cable assemblies dominates inventory strategy as lead times for power electronics extend beyond station commissioning windows. Manufacturing concentrates in China, Germany, and the Netherlands for rectifier modules, with South Korean foundries anchoring silicon carbide wafer supply. Cable jacket compounds and dielectric fluids draw from Belgian and Italian chemical suppliers. Single-source vulnerability in East Asian semiconductor foundries threatens European station builders. Distribution runs through direct OEM relationships with highway operators and fleet procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
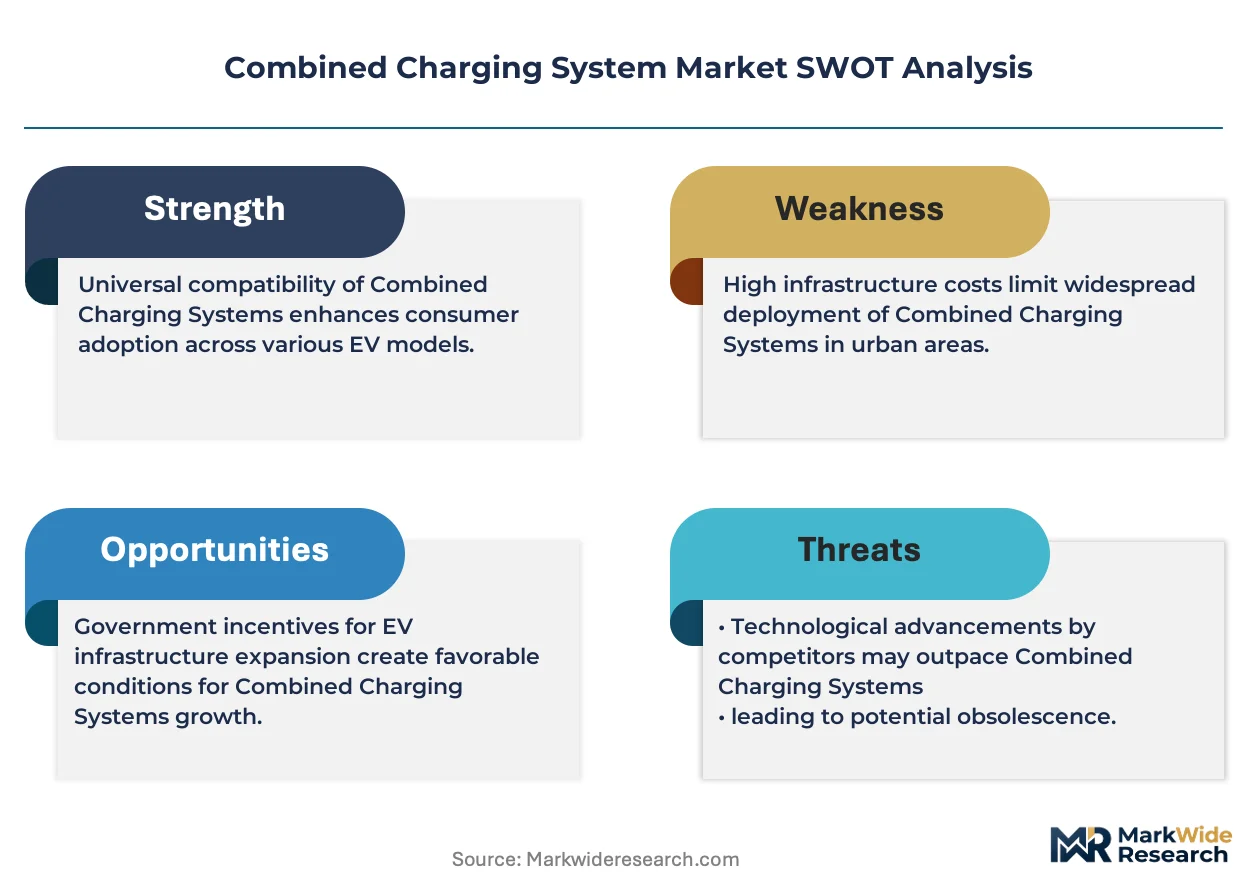
Incumbents must defend against Tesla's proprietary connector ecosystem and China's GB/T standard expansion, which threaten to fragment interoperability gains and strand CCS infrastructure investments.
For Market Incumbents: Secure ISO 15118-20 certification ahead of funding cycle deadlines to lock in AFIR and NEVI eligibility. Anchor backward integration into silicon carbide sourcing through South Korean foundry partnerships, reducing exposure to allocation constraints that disrupt delivery commitments to fleet operators. For New Entrants and Emerging Players: Lead with software-integrated charging management platforms targeting utility demand-response contracts, the most penetrable segment as German municipal utilities seek vehicle-to-grid revenue streams. Pursue white-label hardware partnerships with established manufacturers to bypass 18-month certification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across megawatt-class charging hardware as 500 kW and 1 MW systems require transformer and cooling infrastructure beyond standard DC fast charger footprints. Target acquisition candidates with certified CCS2 production lines and existing utility software integration. Watch NEVI disbursement velocity against state-level electrical permitting backlogs as the inflection signal for actual commissioning capacity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15118-20 Certification Investment | Unlocks bidirectional revenue streams for ABB and Siemens AG through German utility pilots. |
| Silicon Carbide Supply Agreement | Secures module allocation for Eaton and EVBox against East Asian foundry concentration risk. |
| Utility Software Platform Integration | Enables ChargePoint to capture grid services revenue beyond electricity sales through FERC-compliant demand response. |
| Heavy-Duty Corridor Deployment | Positions Schneider Electric for Rhine-Alpine electric freight infrastructure with 500 kW CCS2 hardware. |
| NEVI Funding Compliance Pathway | Guarantees federal eligibility for BP Chargemaster across Texas and California highway networks. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and infrastructure commissioning databases. Primary inputs drew from charging network operators, fleet procurement directors, utility planning officers, and power electronics manufacturing executives. Secondary validation incorporated EU AFIR implementation reports, U.S. Federal Highway Administration NEVI disbursement records, and KBA type-approval registries. Bottom-up station deployment counts triangulated against top-down funding allocation analysis.
Segmentation dimensions modeled span connector standard, charging power rating, vehicle type, and ownership model across the projection horizon. CAGRs derived from equipment shipment trajectories weighted by funding cycle timing and electrical permitting velocity. Industry-specific inputs incorporated silicon carbide module supply forecasts and ISO 15118-20 certification pipeline status.
Forecasts assume regulatory continuity in EU AFIR and U.S. NEVI regimes; material policy shifts would require re-modeling. Revision becomes warranted when semiconductor allocation constraints or grid interconnection backlogs cross thresholds that compress actual commissioning below equipment manufacturing capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Heavy-Duty Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market