
 EV Charging Management Software Platform Market | 2026-2036
EV Charging Management Software Platform Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charging Management Software Platform Market Analytics
Fleet operators are redrawing demand patterns in the EV charging management software platform space, overtaking charging station owners as the dominant buyer archetype. ChargePoint leverages its integrated hardware-software stack to sustain channel control across North American fleet deployments. Driivz anchors European utility partnerships with load-balancing capabilities that stabilize grid-interactive charging. Geotab competes through telematics convergence, embedding charging optimization within broader fleet intelligence workflows.
EV charging management software platforms orchestrate the operation, monitoring, and financial settlement of electric vehicle charging infrastructure through real-time communication with charge point controllers via protocols such as OCPP and ISO 15118. These systems execute dynamic load management, tariff optimization, and user authentication to maximize asset utilization and energy cost efficiency. Cloud-based deployment leads the technology architecture segment due to lower capital barriers and centralized scalability for multi-site operators. Smart charging functionality captures the fastest expansion trajectory as grid operators impose time-of-use constraints and demand response requirements. Payment processing remains a mature margin pool where transaction fee structures have stabilized across major markets.
The Federal Energy Regulatory Commission in the United States and the European Union's Alternative Fuels Infrastructure Regulation shape demand by mandating interoperability standards and transparent pricing disclosure for public charging networks. China's Ministry of Industry and Information Technology enforces GB/T protocol compliance and data localization requirements that condition market access for foreign platform providers. Stakeholders must monitor evolving cybersecurity certification requirements and dynamic electricity tariff structures as these regulatory layers increasingly determine platform architecture decisions and competitive differentiation.
Market Dynamics
Fleet electrification mandates are compressing procurement cycles and forcing platform vendors to integrate telematics, energy management, and payment settlement into unified stacks. This structural pull is reconfiguring competitive boundaries between pure-play software providers and hardware-integrated incumbents.
Growth Catalysts
- EU AFIR Interoperability Mandates:The Alternative Fuels Infrastructure Regulation requires OCPP compliance across public networks, compelling platform upgrades and standardization investments.
- California Fleet Rules:The state's Advanced Clean Trucks regulation accelerates commercial EV deployment, generating concentrated demand for charging orchestration tools.
- Vehicle-to-Grid Integration:Bidirectional charging protocols are unlocking new revenue streams through grid services participation and peak demand reduction.
Market Restraints
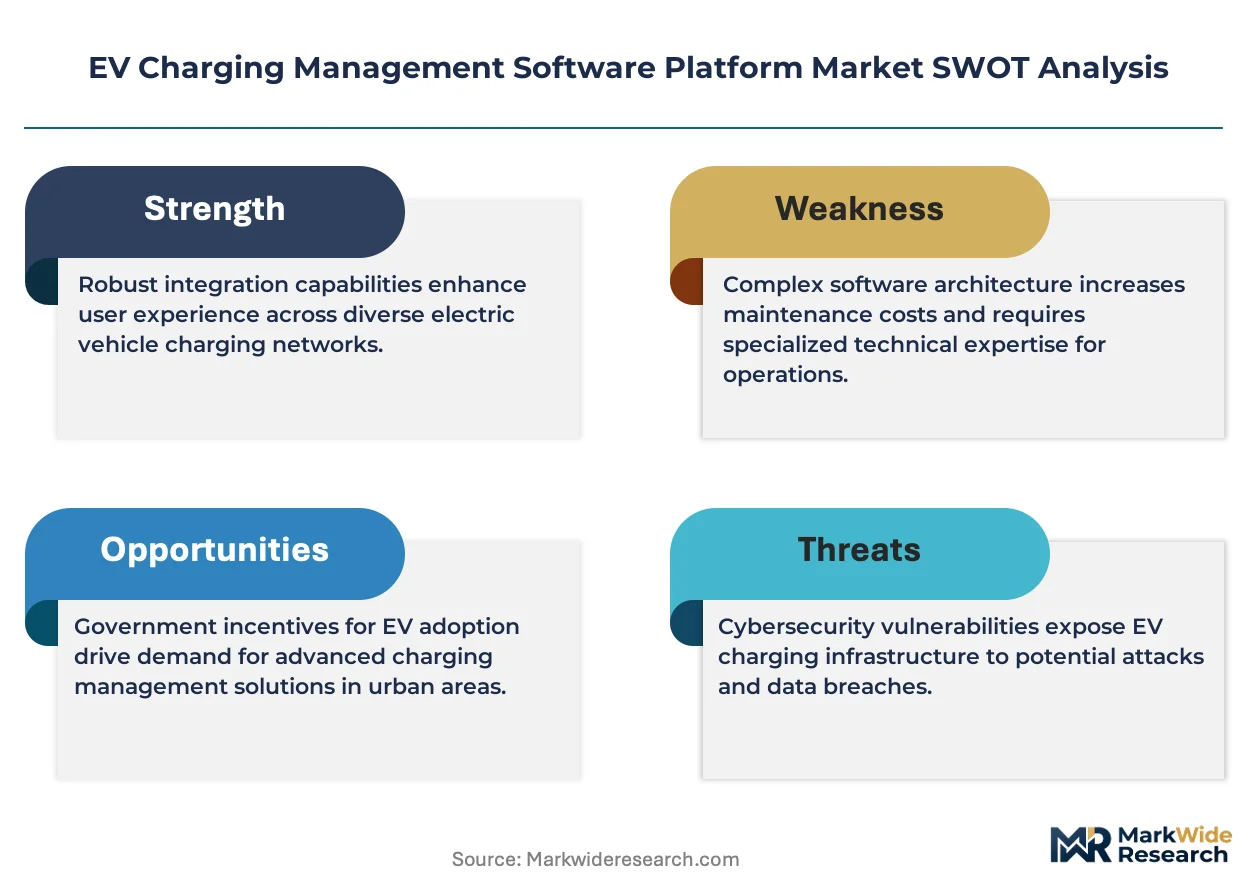
- Silicon Supply Concentration:Semiconductor fabrication for charge point controllers remains concentrated in Taiwan and South Korea, exposing platforms to input volatility.
- Utility Interconnection Queues:Grid connection approval timelines in Germany and the United States extend 18-36 months, throttling deployment velocity.
- Protocol Fragmentation:Coexistence of OCPP, ISO 15118, and China's GB/T standards forces multi-protocol engineering overhead without near-term convergence.
Strategic Opportunities
- India Fleet Electrification:The country's FAME III subsidy scheme and state-level EV policies create whitespace for platform localization and utility partnerships.
- Workplace Charging Expansion:Corporate sustainability commitments are shifting charging investment from public networks to captive workplace infrastructure.
- Dynamic Tariff Optimization:Real-time electricity pricing APIs from utilities enable automated load shifting and new margin capture for multi-site operators.
Industry Challenges
- Cybersecurity Certification Complexity:IEC 62443 and emerging national standards impose fragmented compliance pathways across jurisdictions.
- Legacy Fleet Management Integration:Incumbent telematics systems from diesel-era platforms resist API interoperability, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charging Management Software Platform Market |
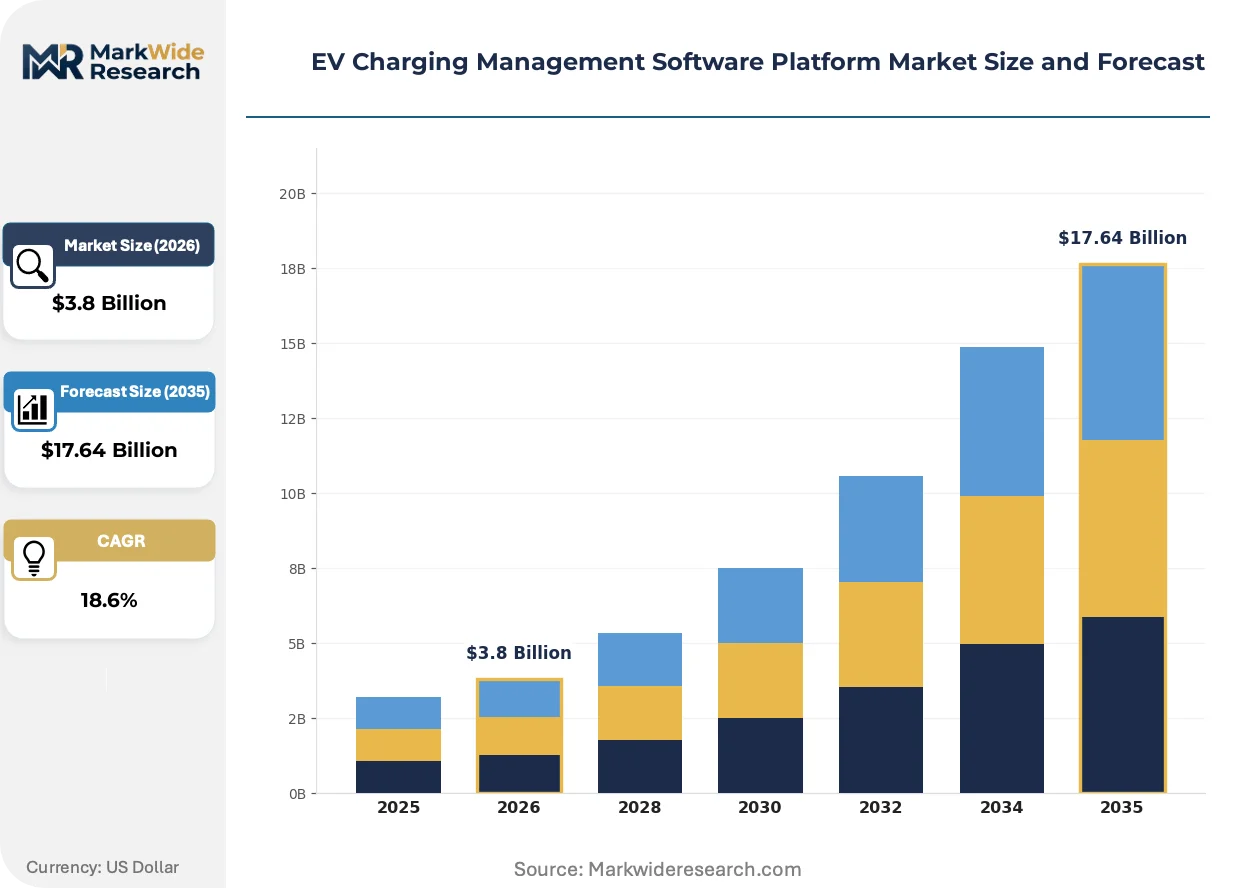
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Tenant Technology: Smart Charging, Load Management, Payment Processing, User Authentication End User: Fleet Operators, Charging Station Owners, Utilities, Real Estate Developers Service Type: Maintenance, Consulting, Integration, Support |
| Companies Covered | EV Connect, Geotab, ChargePoint, YoCharge, Pulse Energy, Driivz, Samsara, AMPECO, Ampcontrol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charging Management Software Platform Market Evolving Landscape
Software-defined charging infrastructure is dissolving boundaries between energy management, fleet operations, and grid interaction. Vendors are racing to embed intelligence deeper into the charging stack while regulators accelerate standardization timelines.
Edge computing architectures are fragmenting platform deployment models. Distributed processing at charge point level reduces cloud latency for real-time load balancing. Tier 1 automotive suppliers and charging hardware OEMs are adopting embedded controllers with local decision-making capacity. This technical shift is fragmenting the traditional cloud-centric vendor landscape and compressing margins for pure SaaS providers.
California's SB 233 vehicle-to-grid integration mandate is forcing platform architecture changes. The regulation requires bidirectional capability disclosure and standardized communication protocols for new EVs sold in the state. Charging management platforms serving California fleets must now orchestrate discharge events, grid service participation, and battery degradation accounting. European regulators are monitoring this framework for potential AFIR amendments.
Subscription-based pricing is displacing perpetual license models among mid-sized fleet operators. Monthly per-port fees reduce upfront capital requirements and align vendor incentives with uptime performance. This shift is most visible in Germany's municipal bus electrification programs, where procurement teams prioritize operational expenditure treatment over capital budget allocation. Hardware bundling and managed service wrap are becoming table stakes for vendor selection.
EV Charging Management Software Platform Market Segmentation
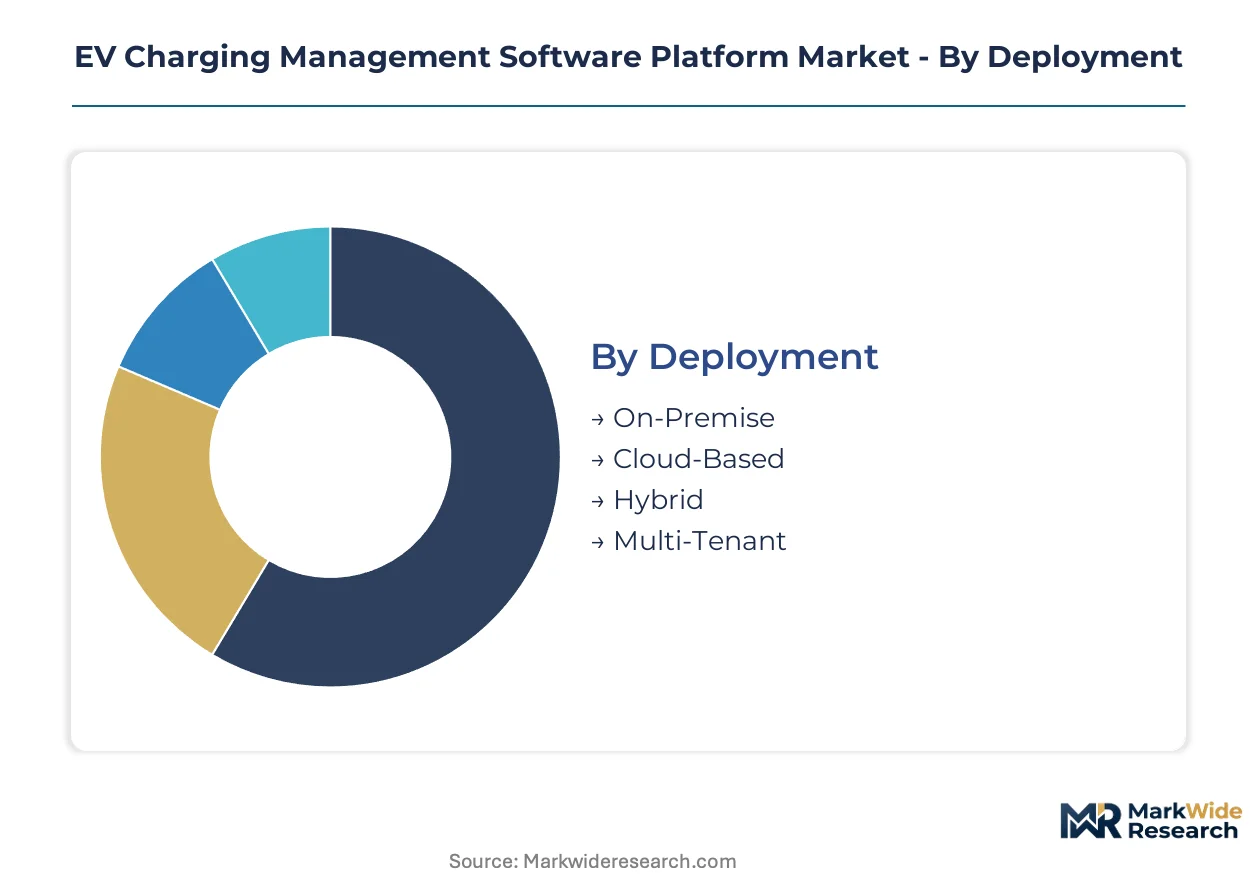
Segmentation in the EV charging management software platform market determines procurement patterns, margin structures, and vendor positioning. Deployment architecture choices dictate capital intensity and scalability limits. Technology functionality separates commodity transaction processing from premium grid-interactive services.
Deployment:
Substitution pressure concentrates on on-premise installations as cloud economics erode traditional capital expenditure models across fleet operator procurement cycles.
- Cloud-Based:Centralized architecture with API-driven scalability enables multi-site operators to manage distributed charge point networks without local server infrastructure. Demand concentrates among North American and European fleet operators facing FERC and EU AFIR interoperability mandates that require rapid software updates without hardware refresh cycles.
- On-Premise:Localized server deployment with dedicated hardware stacks satisfies data sovereignty requirements and air-gapped security protocols. Chinese operators under MIIT data localization rules and German municipal utilities with critical infrastructure designations sustain demand despite higher total cost of ownership.
- Hybrid:Edge-cloud split processing balances latency-sensitive load management with centralized analytics.
- Multi-Tenant:Shared infrastructure instances reduce per-operator costs for small charging network consolidators.
Cloud-Based retains volume leadership; Smart Charging within the Technology category holds the steepest expansion curve.
Technology:
Cost tier stratification separates high-margin grid-interactive capabilities from commoditized transaction processing as utility tariff complexity deepens.
- Smart Charging:Dynamic algorithms orchestrate time-of-use optimization, demand response participation, and vehicle-to-grid discharge events. California fleet operators under SB 233 bidirectional mandates and German utilities with redispatch requirements drive fastest adoption where electricity price volatility creates arbitrage value.
- Load Management:Real-time power distribution across charge point clusters prevents grid connection overload without infrastructure upgrades. German and United States markets with 18-36 month utility interconnection queues concentrate demand for software-defined capacity expansion.
- Payment Processing:Transaction settlement and roaming fee reconciliation across multi-network usage.
- User Authentication:RFID, mobile app, and plug-and-charge credential verification for access control.
Load Management captures the largest installed base; Smart Charging expands most quickly as regulatory pressure intensifies.
End User:
Customer type evolution shows fleet operators displacing charging station owners as the dominant buyer archetype with fundamentally different procurement specifications.
- Fleet Operators:Integrated telematics convergence demands unified platforms combining charging optimization with vehicle dispatch, route planning, and energy cost accounting. California Advanced Clean Trucks regulation compliance and European corporate electrification mandates compress procurement timelines toward comprehensive stack requirements.
- Charging Station Owners:Asset utilization maximization through roaming network participation and dynamic pricing tools. Public network density acceleration in Germany, China, and the United States sustains demand for interoperability-centric feature sets.
- Utilities:Grid stability services and distributed energy resource aggregation for demand response programs.
- Real Estate Developers:Workplace and residential charging infrastructure as amenity and tenant retention tool.
Fleet Operators command the steepest growth trajectory; Charging Station Owners maintain the largest current revenue pool.
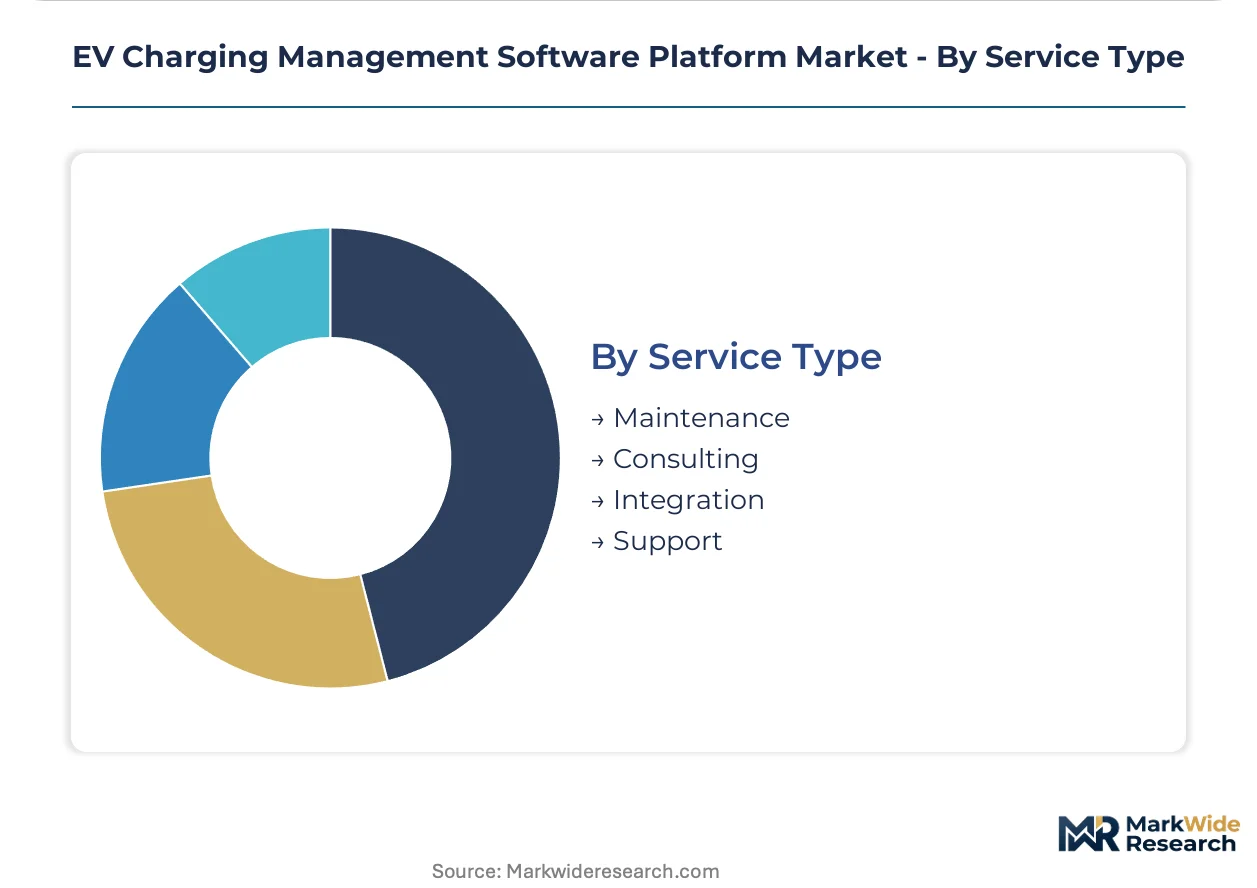
Service Type:
Supply concentration in specialized integration expertise creates margin differentiation between commodity support and complex legacy system connectivity.
- Integration:Middleware development connecting charging platforms with incumbent fleet management, ERP, and utility billing systems. Diesel-era telematics resistance to API interoperability in North American and European logistics fleets drives premium pricing for custom connectivity solutions.
- Consulting:Electrification roadmap planning, tariff structure optimization, and regulatory compliance strategy.
- Maintenance:Software update management, security patch deployment, and uptime monitoring.
- Support:Help desk operations and user training for platform administrators and drivers.
Integration services capture the highest margin expansion; Maintenance represents the most stable recurring revenue base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German platform providers export charging management solutions to fleet operators across Nordic markets, while Chinese vendors supply GB/T-compliant systems throughout Southeast Asian electrification corridors.
United States
California fleet electrification under Advanced Clean Trucks regulation drives concentrated demand for bidirectional charging orchestration. FERC interoperability mandates force platform upgrades across multi-state charging networks. The Los Angeles-San Diego corridor hosts the densest deployment of commercial fleet charging infrastructure.
Germany
Municipal bus electrification programs and corporate fleet mandates compress procurement timelines toward unified stack requirements. EU AFIR OCPP compliance rules standardize platform architecture across public charging networks. The Rhine-Ruhr metropolitan region anchors utility partnership activity for grid-interactive charging services.
China
State-owned fleet operators and logistics companies deploy charging management at scale under dual carbon policy targets. MIIT data localization requirements condition foreign platform market access. The Yangtze River Delta manufacturing cluster generates concentrated demand for industrial fleet charging coordination.
India
FAME III subsidy schemes and state-level EV policies create whitespace for platform localization and utility partnerships. The national regulator enforces cybersecurity certification pathways for critical charging infrastructure. Maharashtra and Karnataka host the fastest-growing commercial fleet electrification pilots.
United Kingdom
Corporate sustainability commitments shift charging investment toward workplace captive infrastructure. The national regulator mandates transparent pricing disclosure for public network interoperability. London's ultra-low emission zone enforcement accelerates last-mile delivery fleet platform adoption.
EV Charging Management Software Platform Market Competitive Landscape
Listed leaders compete with private specialists across capitalization and customer segment dimensions, producing a tiered structure where scale advantages concentrate with hardware-integrated incumbents. Pure-play software vendors occupy mid-market positions through API-first architectures and faster deployment cycles. Three archetypes dominate: integrated hardware-software stacks, telematics-converged platforms, and utility-anchored grid service providers. Competitive moves center on strategic partnerships with automotive OEMs and vertical integration into charge point controller supply.
Within the telematics-converged tier, Geotab and Samsara exemplify fleet intelligence workflow integration. ChargePoint occupies a position representing the integrated hardware-software archetype with channel control across North American deployments. Driivz anchors the utility-partnership vector with European grid-interactive capabilities. These three companies collectively illustrate the competitive boundary reconfiguration between pure software and hardware-coupled offerings.
| Leading Market Players |
|---|
| EV Connect |
| Geotab |
| ChargePoint |
| YoCharge |
| Pulse Energy |
| Driivz |
| Samsara |
| AMPECO |
| Ampcontrol |
| Others |
Value Network & Pricing Analysis
Long-term subscription contracts with embedded hardware refresh cycles lock fleet operators into predictable per-port fees while securing platform vendors against semiconductor input volatility. This structure concentrates pricing power with integrated hardware-software providers and compresses margins for pure SaaS vendors lacking captive controller supply.
Pricing Analysis
Next-generation smart charging capabilities with bidirectional V2G orchestration command premium subscription tiers, while legacy payment-processing-only platforms face commoditization pressure. Pricing stratifies across premium grid-interactive tiers, standard load-management bundles, and economy transaction-processing baselines. Cost compression in the economy tier is intensifying because cloud-native entrants are undercutting on per-port fees. Fleet operators with electrification mandates show lowest price sensitivity; small charging network consolidators exhibit highest.
Supply Chain Analysis
Inventory buffers for charge point controllers have compressed to 8-12 weeks as foundry capacity concentrates in Taiwan and South Korea. Semiconductor fabrication draws from concentrated wafer supply in East Asia, with controller assembly tethered to Chinese and Mexican electronics manufacturing clusters. Single-source vulnerability in automotive-grade microcontroller supply creates exposure to geopolitical disruption. Distribution runs through Tier 1 charging hardware OEMs who bundle embedded software licenses with controller shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors face substitution pressure from telematics-converged fleet intelligence providers embedding charging optimization as a feature rather than standalone product. Defense requires structural moves to deepen integration moats.
For Market Incumbents: Fortify API interoperability with legacy diesel-era fleet management systems to resist displacement by telematics-native competitors. Backward integration into charge point controller design secures supply continuity against Taiwan semiconductor concentration risk. Prioritize California SB 233 compliance certification to maintain access to the fastest-growing bidirectional charging segment.
For New Entrants and Emerging Players: Anchor in India's FAME III-funded municipal bus electrification programs where localized platform requirements create whitespace against established Western vendors. Target German utility partnership channels for grid-interactive charging services, where redispatch regulations demand new software capabilities. Lead with dynamic tariff optimization APIs as differentiated entry wedge.
For Investors and Strategic Acquirers: Edge-computing-native charging platform specialists with embedded controller partnerships represent the highest-conviction acquisition archetype for automotive Tier 1 suppliers seeking software differentiation. Monitor California vehicle-to-grid mandate enforcement timelines as inflection indicator for bidirectional charging revenue acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Legacy Telematics | API middleware connecting charging optimization to incumbent fleet management systems defends against displacement by native converged platforms. |
| Backward Integration into Controller Design | In-house semiconductor specification and embedded firmware development secures supply continuity against Taiwan foundry concentration. |
| Strategic Partnership with Utility Operators | Grid-interactive service contracts with German municipal utilities unlock redispatch revenue streams and regulatory compliance positioning. |
| Acquisition of Edge-Computing Specialists | Distributed processing capabilities at charge point level reduce cloud latency for real-time load balancing and demand response. |
| Geographic Expansion into India Fleet Programs | FAME III subsidy-aligned platform localization captures whitespace in municipal bus electrification and state-level EV policy corridors. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, charging infrastructure procurement managers, utility demand response program leads, and platform engineering executives and refined through secondary validation against SEC filings of listed charging network operators, FERC interconnection queue databases, EU AFIR regulatory implementation guidance, and IEA EV policy tracking reports. Bottom-up deployment volume estimates from country-level charging network databases were triangulated against top-down platform revenue aggregation across the analysis window.
Variance decomposition across deployment architecture, technology functionality, and end-user segments structured the analytical framework. Modeled dimensions included cloud versus on-premise deployment, smart charging versus load management capability tiers, and fleet operator versus charging station owner procurement patterns. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs incorporated utility interconnection timeline data and OCPP protocol adoption curves.
Material uncertainties — semiconductor supply disruption, regulatory timeline acceleration or delay, and fleet electrification mandate enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding protocol standardization convergence and grid tariff structure evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Charging Software Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market