
 Russia Thermal Power Market | 2026-2036
Russia Thermal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Thermal Power Market Analytics
A capital-intensity divergence between integrated energy majors and regional generating companies is reorganizing competitive hierarchies across Russia's thermal power base. Unipro PJSC leverages its ultra-supercritical coal fleet to sustain baseload contracts in European Russia. PJSC Gazprom anchors gas-fired generation through captive fuel supply, while Inter RAO YEES PAO competes on cross-border electricity trading capacity.
Russia thermal power encompasses electricity and heat generation from fossil fuel combustion, typically operating at thermal efficiencies between 33% and 60% depending on turbine technology and cogeneration configuration. Steam turbine plants dominate installed capacity but face margin compression from aging boiler infrastructure, while combined cycle gas turbine installations capture expanding share in greenfield development due to superior heat rates and operational flexibility. Gas turbine technology leads new investment flows, and heat recovery steam generator integration is concentrating in utility-scale projects seeking combined heat and power certification.
The Ministry of Energy enforces grid connection codes and capacity payment mechanisms that shape investment timelines, while Rostekhnadzor oversees safety standards for thermal power equipment and emissions monitoring protocols. Federal tariff regulation through the Federal Antimonopoly Service constrains revenue models for legacy coal plants. Stakeholders must monitor how carbon border adjustment discussions in neighboring trade corridors reshape fuel switching economics and equipment procurement standards.
Market Dynamics
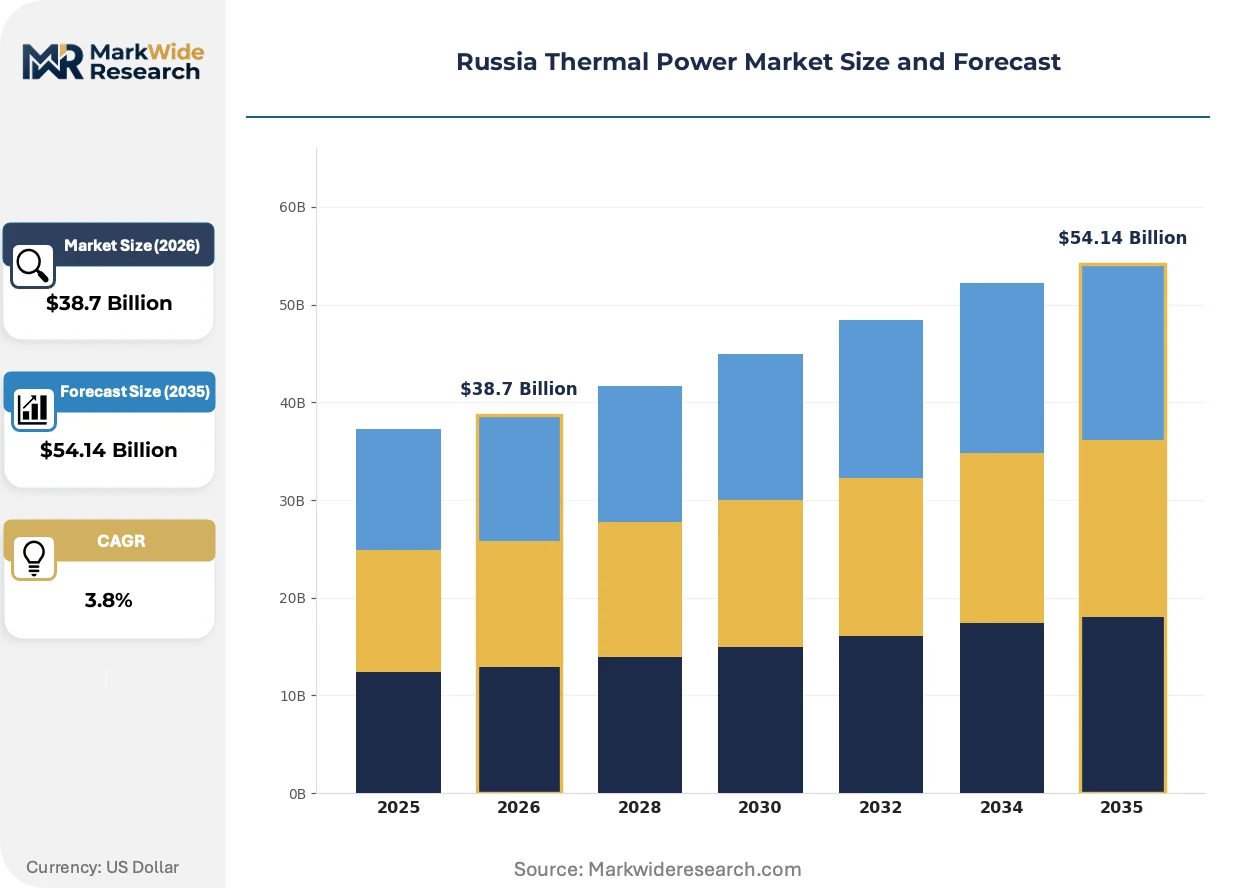
Federal capacity payment mechanisms and carbon intensity benchmarks from the Ministry of Energy are redirecting investment flows from steam turbine baseload plants toward combined cycle gas turbine configurations with heat recovery integration.
Growth Catalysts
- Capacity Market Mechanisms:The Ministry of Energy's capacity payment auctions guarantee revenue streams for new gas-fired capacity, de-risking long-term investment in combined cycle projects.
- Urals Industrial Demand:Metallurgical and petrochemical clusters in Chelyabinsk and Sverdlovsk Oblasts are expanding captive power generation to secure electricity supply independence from grid congestion.
- Gas Turbine Efficiency Gains:Advanced F-class and H-class turbines achieving 62% thermal efficiency are capturing greenfield development share from legacy coal steam cycles.
Market Restraints
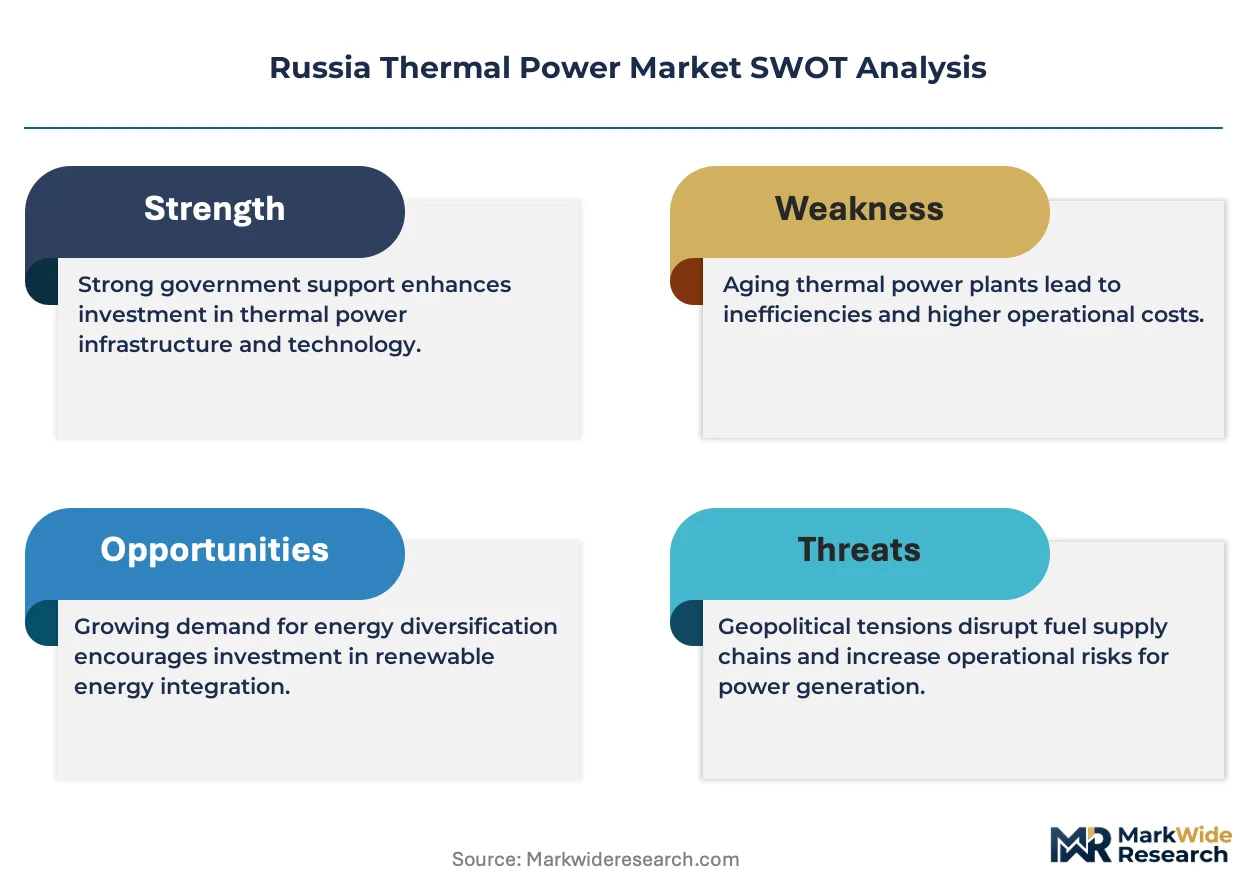
- Boiler Infrastructure Age:Over 40% of installed steam turbine capacity operates beyond original design life, requiring costly retrofits or retirement decisions without clear tariff recovery pathways.
- Domestic Equipment Concentration:Turbine and generator manufacturing concentrates at Power Machines and Silovye Mashiny, creating procurement bottlenecks for regional generating companies.
- Coal-to-Gas Switching Costs:Pipeline connection fees and gas supply contract restructuring impose capital barriers on legacy coal plant conversions in Siberian Federal District.
Strategic Opportunities
- Far East Grid Integration:Isolated power systems in Sakha Republic and Primorsky Krai present captive opportunities for modular gas turbine and energy storage hybrid configurations.
- Combined Heat and Power Certification:Federal tariff premiums for efficient cogeneration create margin expansion potential for utilities retrofitting steam extraction capabilities.
- Carbon Border Adjustment Preparation:Anticipatory equipment upgrades to EU-equivalent emissions standards position export-facing industrial consumers for compliance with emerging trade corridor regulations.
Industry Challenges
- Specialized Welding and Rotor Balancing Expertise:Aging workforce demographics in high-precision turbine maintenance create service backlogs and extended outage durations.
- Rostekhnadzor Certification Timelines:Safety case documentation and emissions compliance verification for new gas turbine installations extend project commissioning schedules.
- Legacy Control System Integration:Digital turbine control upgrades require interface engineering with Soviet-era distributed control systems still operating at baseload coal facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Thermal Power Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Coal, Natural Gas, Oil, Biomass Technology: Steam Turbine, Gas Turbine, Combined Cycle, Heat Recovery Steam Generator End User: Utilities, Industrial Plants, Commercial Sector, Residential Sector Installation: Onshore, Retrofit, Greenfield, Replacement |
| Companies Covered | Unipro PJSC, Inter RAO YEES PAO, SUEK JSC, PJSC Gazprom, Rosatom State Atomic Energy Corporation, PJSC OGK-2, PJSC Lukoil, Gazprom Energoholding, JSC Tatenergo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Thermal Power Market Evolving Landscape
Equipment procurement patterns are pivoting from unit-based turbine sales toward integrated power island contracts, while digital monitoring systems penetrate operational asset management. These shifts compress supplier margins and reconfigure after-market service relationships.
Air-cooled condenser technology is displacing water-intensive once-through cooling systems at greenfield gas turbine sites. Generating companies in water-stressed regions of Volga Federal District are specifying dry cooling to secure siting permits. This hardware shift is displacing traditional cooling tower suppliers from project engineering, procurement, and construction contracts.
Carbon intensity benchmarking protocols from the Ministry of Energy now mandate emissions disclosure for capacity market participants. Plants exceeding 350 grams CO2 per kilowatt-hour face payment coefficient reductions. Coal-fired baseload units in Central Federal District are responding with biomass co-firing retrofits and selective catalytic reduction upgrades to maintain tariff competitiveness.
Industrial offtakers in metallurgy and chemicals are consolidating electricity procurement through direct supply contracts with independent power producers, bypassing traditional utility intermediaries. This channel disintermediation concentrates buyer power among large consumers. The pattern is most visible in Sverdlovsk and Chelyabinsk Oblasts where aluminum smelters and steel mills negotiate multi-year power purchase agreements with dedicated gas-fired capacity.
Russia Thermal Power Market Segmentation
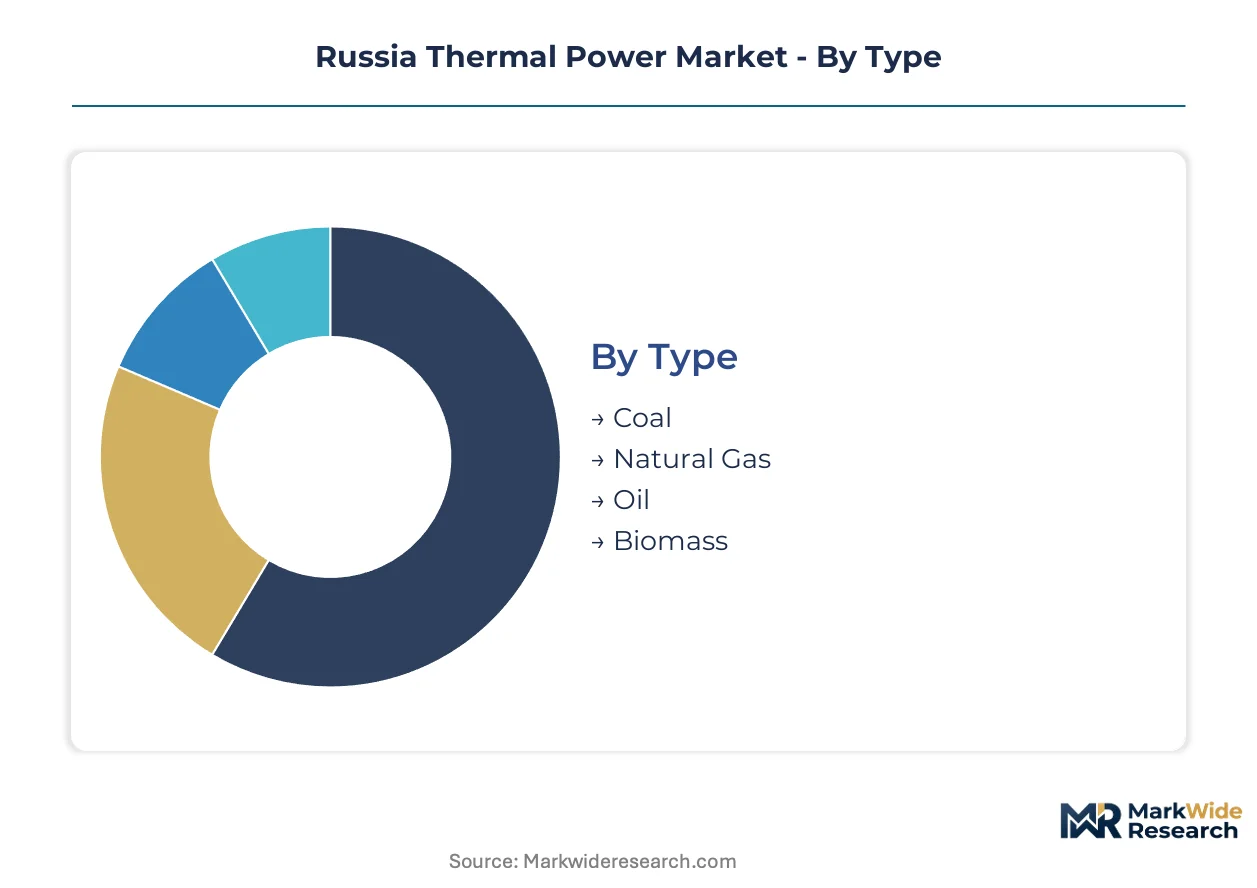
Russia's thermal power market segments reflect divergent regulatory treatment across fuel types and technology vintages. Federal capacity payment mechanisms and carbon intensity benchmarks from the Ministry of Energy create distinct investment economics for each configuration, reshaping procurement patterns and project development timelines.
Type:
The Ministry of Energy's carbon intensity benchmarks impose differentiated payment coefficients based on fuel-specific emissions profiles, restructuring competitive economics across generation sources.
- Coal:Ultra-supercritical steam cycles dominate existing installed base in Central and Siberian Federal Districts. Plants exceeding 350 grams CO2 per kilowatt-hour face tariff coefficient reductions, forcing biomass co-firing retrofits at baseload facilities in Kemerovo and Novosibirsk Oblasts.
- Natural Gas:Combined cycle configurations achieve 62% thermal efficiency with F-class and H-class turbines, capturing greenfield development share. Gazprom's captive fuel supply anchors project economics in European Russia, while pipeline connection fees constrain conversions in remote Siberian clusters.
- Oil:Peaking and backup applications persist in isolated power systems of Sakha Republic and Far Eastern Federal District where gas infrastructure remains undeveloped.
- Biomass:Wood pellet co-firing retrofits at legacy coal plants qualify for federal tariff premiums under efficient cogeneration certification protocols.
Established volume favors coal; emerging adoption favors natural gas.
Technology:
Capital intensity and operational flexibility separate competitive tiers, with heat rate performance determining capacity market auction outcomes.
- Steam Turbine:Aging boiler infrastructure exceeding original design life concentrates in Ural and Volga Federal Districts. Over 40% of installed capacity requires costly retrofits or retirement without clear tariff recovery pathways under Federal Antimonopoly Service regulation.
- Gas Turbine:Advanced turbines displace legacy steam cycles in greenfield development. Air-cooled condenser specifications penetrate water-stressed regions of Volga Federal District, displacing traditional cooling tower suppliers from engineering contracts.
- Combined Cycle:Heat recovery steam generator integration captures utility-scale projects seeking combined heat and power certification and associated federal tariff premiums.
- Heat Recovery Steam Generator:Modular configurations enable industrial captive power expansion in Chelyabinsk and Sverdlovsk metallurgical clusters.
Steam turbine capacity dominates installed base; combined cycle installations are climbing the fastest.
End User:
Procurement concentration and contract structure differentiate revenue stability across customer categories.
- Utilities:Federal grid codes and capacity payment mechanisms shape long-term investment timelines. Regional generating companies face procurement bottlenecks from domestic equipment concentration at Power Machines and Silovye Mashiny.
- Industrial Plants:Aluminum smelters and steel mills in Sverdlovsk and Chelyabinsk Oblasts negotiate direct multi-year power purchase agreements, bypassing traditional utility intermediaries and concentrating buyer power.
- Commercial Sector:Distributed generation demand concentrates in Moscow and Saint Petersburg urban cores.
- Residential Sector:District heating networks in European Russia sustain seasonal load patterns for cogeneration assets.
Utility offtake anchors baseload contracting; industrial direct procurement is gaining share fastest.
Installation:
Project delivery mode determines regulatory pathway complexity and commissioning timeline exposure.
- Onshore:Standard grid-connected development dominates European Russia capacity additions.
- Retrofit:Digital turbine control upgrades require interface engineering with Soviet-era distributed control systems at baseload coal facilities, extending outage durations.
- Greenfield:Isolated power systems in Primorsky Krai and Sakha Republic present captive opportunities for modular gas turbine and energy storage hybrid configurations.
- Replacement:Aging workforce demographics in specialized welding and rotor balancing create service backlogs for equipment swap-out projects.
Retrofit activity sustains service revenues; greenfield development offers steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Russian thermal power markets. Industrial offtakers in the Urals exhibit high price sensitivity, while Moscow's utility sector absorbs tariff premiums for reliability. Remote Far East regions face inelastic demand due to supply isolation.
Central Federal District
Moscow's district heating networks sustain seasonal baseload for cogeneration assets. The Federal Antimonopoly Service constrains legacy coal plant revenue models through tariff regulation. Power Machines anchors turbine manufacturing in the capital region, supplying equipment to regional generating companies.
Ural Federal District
Aluminum smelters and steel mills in Chelyabinsk and Sverdlovsk Oblasts negotiate direct multi-year power purchase agreements. Ministry of Energy capacity payment auctions guarantee revenue streams for new gas-fired installations. Captive power expansion concentrates in metallurgical clusters seeking electricity supply independence.
Siberian Federal District
Coal-to-gas switching faces capital barriers from pipeline connection fees and supply contract restructuring. Kemerovo and Novosibirsk Oblasts retrofit biomass co-firing at baseload facilities to maintain tariff competitiveness under carbon intensity benchmarks. Aging boiler infrastructure exceeds original design life across over 40% of installed steam turbine capacity.
Volga Federal District
Water-stressed regions specify air-cooled condenser technology for greenfield gas turbine sites, displacing traditional cooling tower suppliers. Dry cooling specifications secure siting permits where once-through systems face regulatory restriction. Federal grid codes reshape investment timelines toward combined cycle configurations.
Far Eastern Federal District
Isolated power systems in Sakha Republic and Primorsky Krai present captive opportunities for modular gas turbine and energy storage hybrids. Oil-fired peaking persists where gas infrastructure remains undeveloped. Rostekhnadzor certification timelines extend project commissioning schedules in remote deployment zones.
Russia Thermal Power Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Russia's thermal power market. State-affiliated energy majors leverage captive fuel supply and grid access to anchor baseload contracting. Regional generating companies compete on localized industrial relationships and district heating service territories. Competitive moves concentrate on equipment modernization cycles and direct supply contract negotiations with metallurgical offtakers.
Among integrated energy majors, Unipro PJSC and PJSC Gazprom exemplify contrasting strategic positions. Unipro leverages ultra-supercritical coal fleet assets to sustain baseload contracts in European Russia. Gazprom anchors gas-fired generation through captive natural gas supply integration. Inter RAO YEES PAO occupies a position emphasizing cross-border electricity trading capacity rather than pure domestic generation scale.
| Leading Market Players |
|---|
| Unipro PJSC |
| Inter RAO YEES PAO |
| SUEK JSC |
| PJSC Gazprom |
| Rosatom State Atomic Energy Corporation |
| PJSC OGK-2 |
| PJSC Lukoil |
| Gazprom Energoholding |
| JSC Tatenergo |
| Others |
Value Network & Pricing Analysis
Air-cooled condenser substitution for once-through cooling systems is redrawing equipment procurement geography while compressing margins for traditional cooling tower suppliers across Volga Federal District greenfield projects. This hardware pivot simultaneously extends siting permit timelines and fragments pricing power among engineering-procurement-construction contractors competing for integrated power island contracts.
Pricing Analysis
After-market service contracts and rotor balancing maintenance packages command lifetime value multiples exceeding original equipment sales for turbine manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates F-class and H-class turbine configurations from refurbished Soviet-era steam units and modular peaking installations. Pricing pressure stems from Federal Antimonopoly Service tariff caps on legacy coal baseload capacity. Industrial aluminum smelters in Sverdlovsk Oblast exhibit acute price sensitivity, while Moscow district heating utilities absorb reliability premiums with minimal elasticity.
Supply Chain Analysis
Extended lead times for specialized welding consumables and H-class turbine blade castings now stretch eighteen to thirty-six months for non-priority customers. Manufacturing concentrates in Russia's Power Machines and Silovye Mashiny facilities, with critical alloy sourcing drawing from Germany, Japan, and domestic VSMPO-AVISMA titanium operations. Supply chain risk centers on Rostekhnadzor certification bottlenecks that delay commissioning. Distribution runs through Gazprom Energoholding's captive fuel supply integration and regional generating company procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat where Ministry of Energy capacity payment mechanisms and carbon intensity benchmarks create entrenched switching costs for baseload offtakers. Federal grid code compliance and Rostekhnadzor safety certification erect barriers that protect incumbent revenue streams.
For Market Incumbents: Secure ultra-supercritical coal fleet modernization timelines ahead of biomass co-firing mandate phase-ins. Deepen backward integration into captive fuel supply through Gazprom supply contract restructuring to defend margin position against independent power producer encroachment in Ural metallurgical clusters. For New Entrants and Emerging Players: Lead with modular gas turbine and energy storage hybrid configurations targeting isolated power systems in Sakha Republic and Primorsky Krai where grid congestion creates offtaker urgency. Position for direct supply contract negotiations with aluminum smelters bypassing traditional utility intermediaries. For Investors and Strategic Acquirers: Capital is best deployed toward regional generating companies holding district heating service territories in European Russia with embedded cogeneration tariff premiums. Monitor carbon border adjustment mechanism developments in EU trade corridors as the inflection signal for anticipatory emissions upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Combined Cycle Capacity Buildout | F-class turbine installations capture greenfield share under Ministry of Energy capacity auction terms. |
| Backward Integration into Gas Supply | Gazprom captive fuel contracts anchor project economics against pipeline connection fee volatility. |
| Biomass Co-firing Retrofit Program | Kemerovo Oblast coal plants secure tariff competitiveness under 350g CO2 per kWh benchmarks. |
| Air-cooled Condenser Specification | Dry cooling technology penetrates Volga Federal District siting permits displacing traditional suppliers. |
| Direct Power Purchase Agreement | Sverdlovsk aluminum smelters consolidate procurement bypassing utility intermediaries. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, independent power producer project developers, EPC contractors, grid operators, and fuel supply specialists. Primary interview insights combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity addition tracking and top-down tariff revenue modeling were triangulated.
Across the analysis window, forecasts incorporate fuel source segmentation, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from installed base retirement curves and greenfield development pipelines. Specific inputs include Ministry of Energy capacity auction clearing prices and Rostekhnadzor certification timeline distributions.
Underlying assumptions cover Federal Antimonopoly Service tariff regulation stability and carbon intensity benchmark enforcement, with deviation risk concentrated in EU carbon border adjustment mechanism implementation timing and pipeline infrastructure expansion delays in Siberian Federal District. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Southeast Asia Thermal Power Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
North America Thermal Energy Storage Market