
 Gas Insulated Transmission Lines Market | 2026-2036
Gas Insulated Transmission Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Insulated Transmission Lines Market Intelligence
The development of SF6-free insulation technologies is reorganizing the market for gas insulated transmission lines. This shift pressures incumbents to innovate beyond the industry standard gas. Siemens Energy leads in developing and deploying alternative insulation mediums like clean air. Hitachi Energy leverages its extensive high-voltage portfolio to integrate these new systems. General Electric competes by focusing on advanced gas mixture research to find viable, lower-impact SF6 replacements.
Gas Insulated Transmission Lines are high-voltage conductors enclosed within a metallic tube, using a compressed dielectric gas for insulation. This design enables the bulk transmission of electrical power with minimal spatial footprint, making it ideal for urban substations, underground tunnels, and bridge crossings. While SF6 technology remains the dominant installation type, vacuum and composite insulation alternatives represent the fastest-growing technology segment. Among end users, electric utilities account for the largest share for grid expansion, with renewable energy integration projects following closely.
Regulatory frameworks are a primary force shaping product development and material selection. The EU's F-Gas Regulation and the EPA's SF6 reporting rules in the United States create significant compliance pressures and incentivize the search for alternatives. In parallel, China's national dual carbon goals encourage the adoption of high-efficiency, low-loss transmission technologies. Stakeholder decisions now center on balancing the proven reliability of SF6 against the long-term regulatory risk and lifecycle costs of adopting new insulation materials.
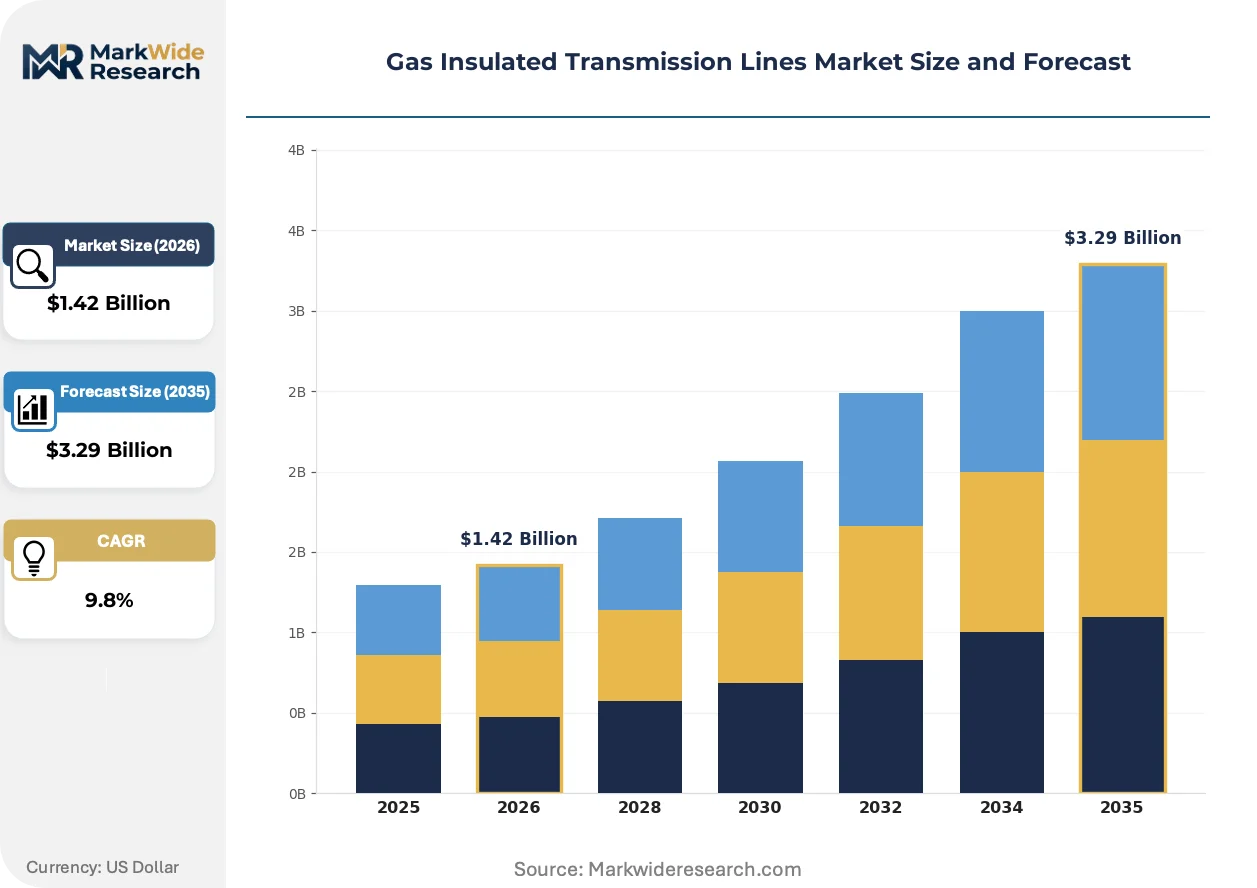
Market Dynamics
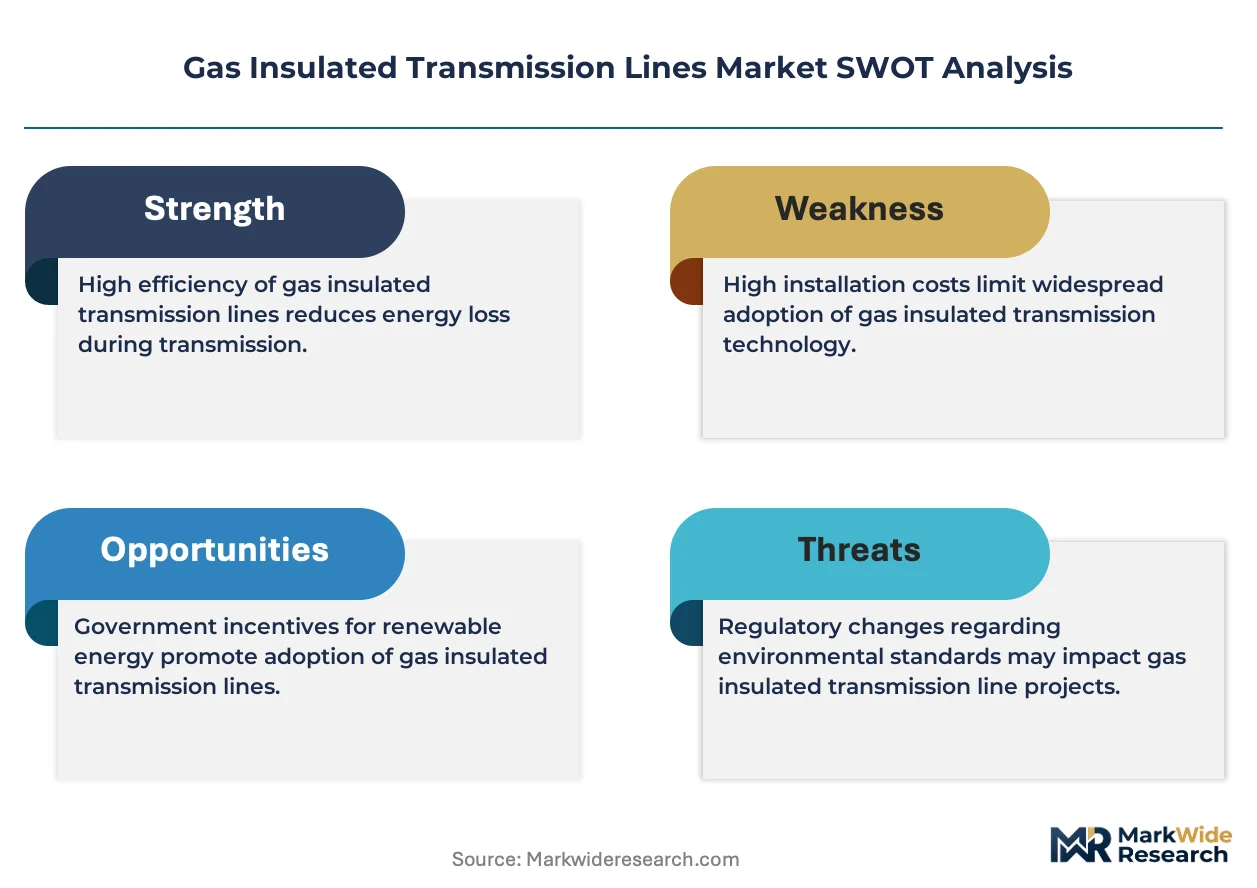
The regulatory-driven transition away from sulfur hexafluoride (SF6) gas is the central force shaping the market. This environmental imperative compels innovation in insulation materials, altering product design, supply chains, and competitive hierarchies across the industry.
Growth Catalysts
- Renewable Energy Integration:Connecting large-scale offshore wind and solar farms to national grids requires high-capacity, compact transmission, particularly for subsea or underground routes where space is limited.
- Grid Modernization in China:China's national dual carbon goals and extensive power grid expansion projects necessitate the deployment of high-efficiency, low-loss transmission technologies to support its energy transition.
- Urban Density:Increasing urbanization worldwide drives demand for space-efficient power infrastructure, making GITL an ideal solution for high-load urban substations and underground cable tunnels.
Market Restraints
- High Initial Investment:The significant upfront capital cost of Gas Insulated Transmission Lines compared to conventional air-insulated overhead lines remains a primary barrier to adoption, especially for budget-constrained utilities.
- Technical Complexity:On-site assembly, gas handling, and maintenance of GITL systems require specialized equipment and highly trained personnel, adding to operational complexity and lifetime costs.
- SF6 Technology Inertia:The long-established track record and proven reliability of SF6-based systems create significant market inertia, slowing the adoption of newer, less field-tested SF6-free alternative technologies.
Strategic Opportunities
- Digitalization and Monitoring:Integrating advanced sensors and IoT-based diagnostic systems with GITL offers opportunities for predictive maintenance, asset performance management, and improved grid reliability.
- DC Transmission Systems:The development of high-voltage direct current (HVDC) GITL creates new applications for long-distance bulk power transmission with lower energy losses compared to AC systems.
- Grid Expansion in India:Government initiatives to strengthen the national power grid in India present a substantial opportunity for GITL deployment to reduce transmission congestion and improve energy access.
Industry Challenges
- Specialized Skills Gap:A shortage of engineers and technicians with the specific expertise required for the design, installation, and servicing of high-voltage GITL systems can lead to project delays and increased labor costs.
- Supply Chain Reconfiguration:The shift to SF6-free alternatives necessitates establishing new supply chains for alternative gases and components, creating logistical challenges and potential material sourcing risks.
- Legacy System Integration:Ensuring seamless and safe interoperability when connecting new, eco-friendly GITL segments with the vast installed base of existing SF6-insulated equipment is a major technical hurdle for utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Insulated Transmission Lines Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.29 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voltage Source Converter, Current Source Converter, Hybrid Converter, Gas Insulated Switchgear Technology: SF6, Vacuum Insulation, Air Insulation, Composite Insulation End User: Utilities, Industrial, Commercial, Renewable Energy Application: Substations, Power Distribution, Renewable Integration, Grid Expansion |
| Companies Covered | General Electric, Larsen & Toubro, Siemens Energy, China XD Group, Schneider Electric, ABB, Toshiba Corporation, Mitsubishi Electric Corporation, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Insulated Transmission Lines Market Strategic Shifts & Innovations
The imperative to decarbonize energy systems while enhancing grid resilience is accelerating technological change. This evolution is driven by stringent environmental regulations targeting potent greenhouse gases and a demand-side pull for smarter, more reliable transmission assets.
SF6-free insulation technologies, which use mediums like clean air or novel gas mixtures, provide dielectric strength without the environmental drawbacks of sulfur hexafluoride. Electric utilities and renewable project developers are adopting these alternatives, especially within jurisdictions governed by strict environmental laws like the European Union. This adoption is bifurcating the market between legacy SF6 systems, valued for their proven performance, and new eco-friendly installations driven by regulatory mandates.
The European Union's F-Gas Regulation is a primary instrument accelerating the phase-down of SF6 in new high-voltage equipment. This policy directly incentivizes R&D into viable alternatives and forces manufacturers to develop compliant product portfolios to maintain market access. Consequently, transmission system operators in Europe and other environmentally conscious regions are increasingly weighting lifecycle greenhouse gas emissions in their procurement criteria for new grid assets.
A notable behavioral shift involves utilities moving from procuring discrete components to demanding fully integrated and digitally enabled transmission systems. This change disrupts the traditional supplier model, creating an advantage for vendors that can bundle GITL hardware with embedded sensors, diagnostic software, and asset management platforms. This trend is most visible in grid modernization projects across developed economies like Japan and Germany, where maximizing uptime and enabling predictive maintenance are critical priorities.
Gas Insulated Transmission Lines Market Segmentation
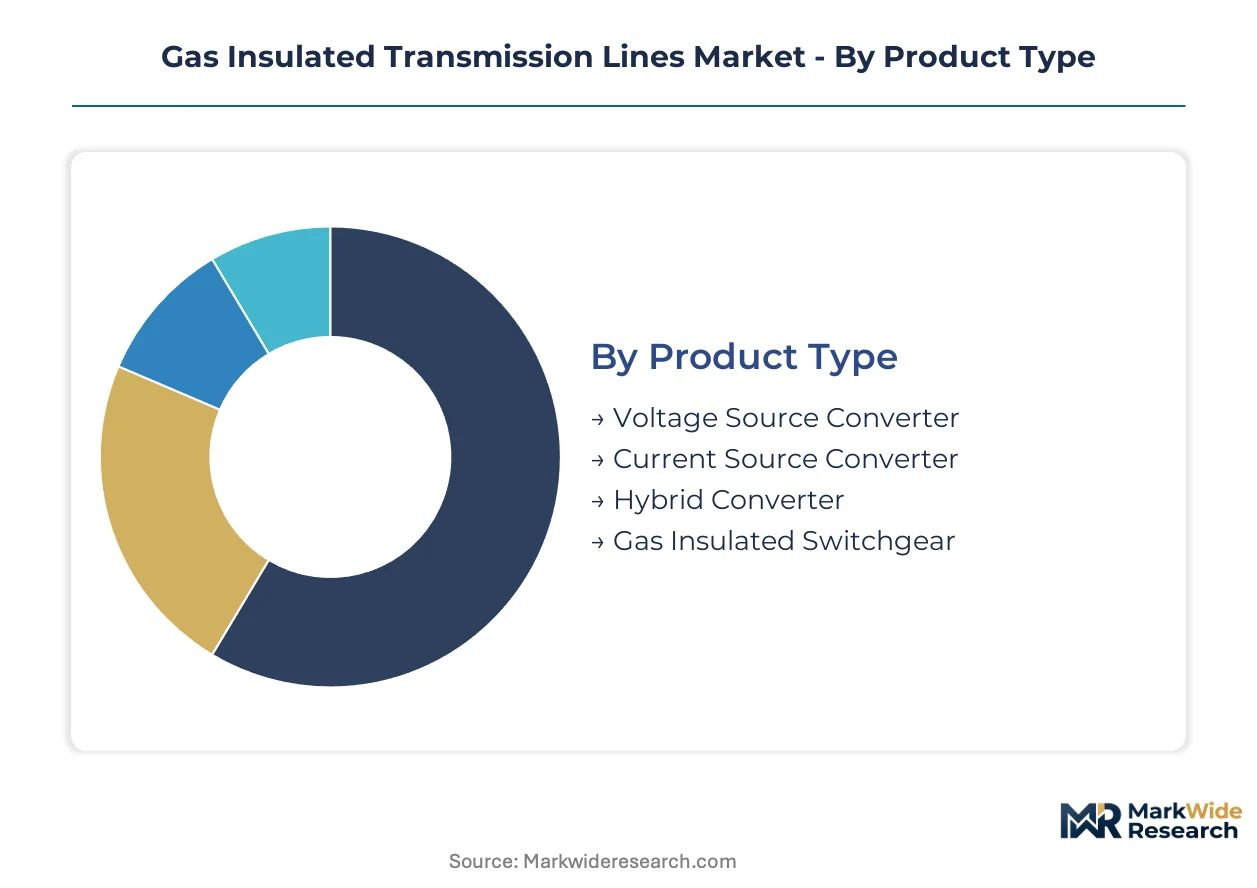
Understanding the segmentation within the Gas Insulated Transmission Lines market reveals distinct value propositions and operational considerations for various stakeholders. Each segment addresses specific technical requirements, environmental mandates, or infrastructure challenges across different regions.
Product Type:
Margin pools within the product type category often concentrate in advanced converter technologies that enable long-distance high-voltage direct current (HVDC) transmission. These systems command higher value due to their complexity and efficiency benefits.
- Voltage Source Converter:This technology uses power electronics to convert AC to DC and vice versa, offering independent control of active and reactive power. Demand is concentrating in offshore wind farm connections in Europe, where grid stability and power quality are critical.
- Current Source Converter:Utilizing thyristor-based technology, current source converters are well-suited for high-power, long-distance DC transmission with robust short-circuit capabilities. China's extensive grid expansion projects are driving demand for these reliable bulk power transfer systems.
- Hybrid Converter:Hybrid converters combine aspects of both voltage and current source technologies, providing flexibility for specific grid integration challenges. These systems find niche applications in complex grid modernization efforts requiring adaptable power flow control.
- Gas Insulated Switchgear:GIS integrates various high-voltage components like circuit breakers and disconnectors into a compact, gas-insulated metal enclosure. Urban substations in densely populated areas like Japan rely on GIS for space-efficient power distribution.
Gas Insulated Switchgear holds installed capacity. Voltage Source Converter is rotating up the share rankings.
Technology:
The cost tier for GITL technologies is heavily influenced by material innovation and regulatory compliance. SF6-free alternatives typically carry a higher initial cost due to ongoing research and development, but offer lower long-term environmental liabilities.
- SF6:Sulfur hexafluoride (SF6) technology utilizes SF6 gas as a dielectric medium, offering excellent insulation properties and compact designs. Despite environmental concerns, its proven reliability and established infrastructure maintain its presence in existing grid assets globally.
- Vacuum Insulation:This technology employs a vacuum as the primary insulating medium, eliminating the need for insulating gases and offering an environmentally benign solution. Renewable energy integration projects, particularly in environmentally sensitive regions, are adopting vacuum-insulated equipment.
- Air Insulation:Air insulation systems use atmospheric air as the dielectric, requiring larger physical footprints compared to gas-insulated alternatives. These systems are prevalent in conventional overhead lines and some outdoor substation applications.
- Composite Insulation:Composite insulation combines various materials, often including solid dielectrics and gases, to optimize performance and reduce environmental impact. Such systems are emerging in specialized applications where a balance of compactness and eco-friendliness is required.
The shift towards Vacuum Insulation is driven by environmental regulations. SF6 maintains its market presence due to established performance.
End User:
The volume of demand within the end-user segments is primarily driven by large-scale infrastructure investments and energy transition initiatives. Electric utilities represent the largest segment due to their responsibility for national grid operations and expansion.
- Utilities:Electric utilities operate and maintain national and regional power grids, requiring GITL for substation upgrades, new transmission lines, and grid reinforcement. Grid modernization projects in countries like India are a significant demand source for utilities.
- Renewable Energy:This segment includes developers and operators of large-scale renewable energy projects, such as offshore wind farms and large solar installations. Connecting these remote generation sites to the main grid necessitates high-capacity, compact GITL solutions.
- Industrial:Industrial end-users, such as heavy manufacturing plants or large data centers, deploy GITL for reliable internal power distribution and connection to high-voltage grids. Specific industrial applications prioritize uninterrupted power supply and safety.
- Commercial:Commercial applications typically involve smaller-scale power distribution within urban centers, including large office complexes or commercial districts. Space-saving GITL solutions are beneficial for these dense environments.
Demand from Utilities underpins market stability. Renewable Energy expands rapidly due to global decarbonization efforts.
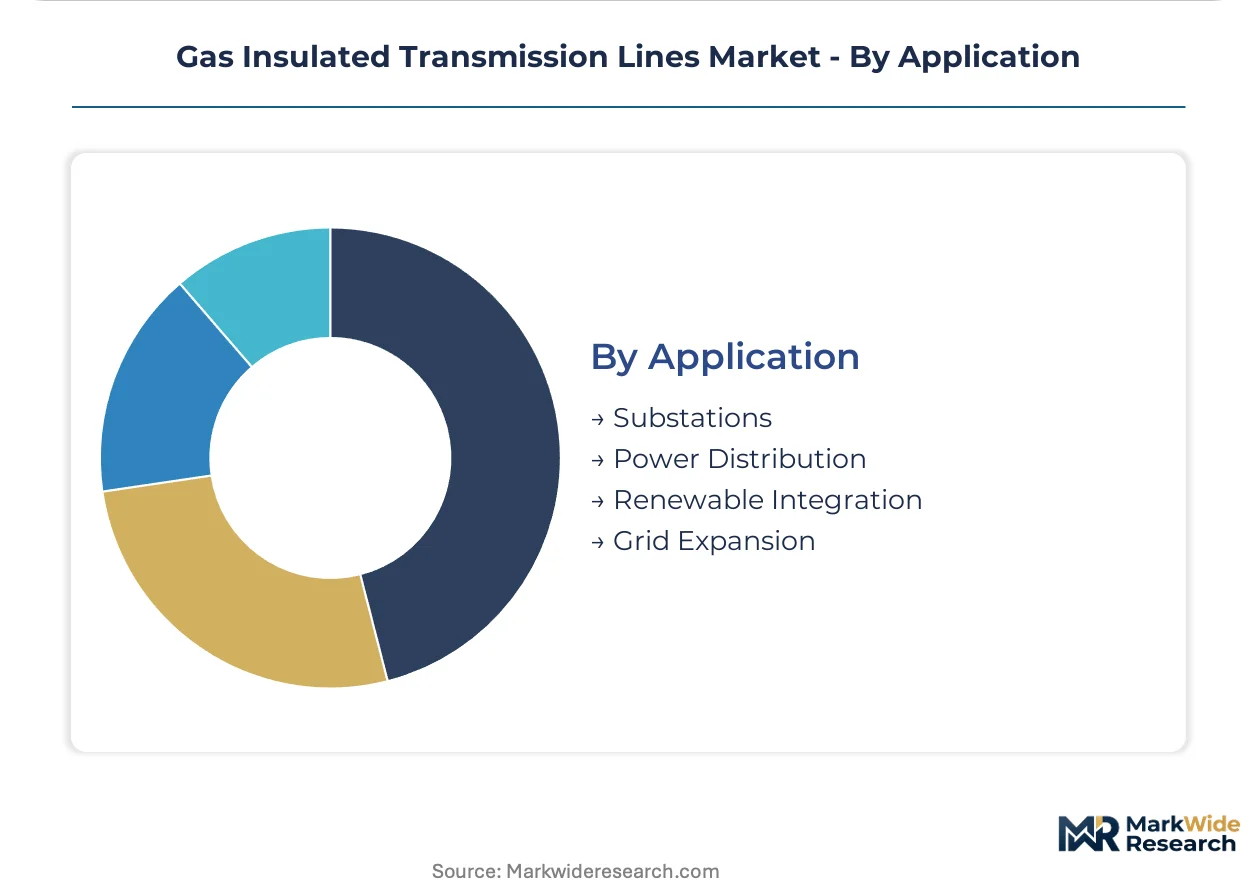
Application:
The application segment highlights the diverse deployment scenarios for GITL, with substations and renewable integration representing areas of intense activity. These applications leverage GITL's compact design and high reliability.
- Substations:GITL is critical for modernizing and expanding substations, especially in urban areas where land is scarce and environmental impact must be minimized. These installations ensure efficient power transformation and distribution within metropolitan networks.
- Power Distribution:This application involves the delivery of electricity from substations to end-users, often through underground or encapsulated systems in densely populated regions. Power distribution networks in developed economies like Germany utilize GITL for enhanced reliability.
- Renewable Integration:Connecting large-scale renewable generation sources, particularly offshore wind and remote solar farms, to existing grids is a key application for GITL. These lines facilitate the efficient and stable transfer of green energy over long distances.
- Grid Expansion:Building new transmission infrastructure to meet growing electricity demand or to enhance grid resilience constitutes grid expansion. China's national dual carbon goals are driving significant GITL deployment for new high-capacity transmission corridors.
Specific requirements for Substations drive innovation. The need for Renewable Integration solutions is intensifying.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for gas insulated transmission lines exhibits significant regional variations in supply and demand dynamics. Manufacturing capabilities for advanced GITL components are concentrating in specific industrial hubs. These centers are driving innovation in SF6-free technologies and efficient grid solutions.
China
Demand for high-capacity, low-loss transmission is immense due to rapid grid expansion and urbanization. China's national dual carbon goals accelerate the deployment of efficient GITL solutions. Beijing and Shanghai metropolitan areas require compact substations and underground lines for power distribution.
Germany
Renewable energy integration, especially from offshore wind, drives demand for compact, environmentally compliant GITL. The EU F-Gas Regulation mandates the phase-down of SF6, pushing adoption of alternative insulation. The Rhine-Ruhr region utilizes advanced GIS for industrial power supply and urban grid modernization.
United States
Grid modernization initiatives and the need for resilient infrastructure fuel demand for advanced transmission solutions. EPA's SF6 reporting rules incentivize utilities to explore and adopt SF6-free alternatives. Major utility centers like those in California are investing in GITL for urban undergrounding and substation upgrades.
India
Strengthening the national power grid and reducing transmission congestion are primary demand drivers. Government initiatives to improve energy access across India support extensive GITL deployment. The Mumbai and Delhi industrial corridors are seeing increased installation of GIS for reliable power delivery.
Japan
Urban density and land scarcity necessitate compact power infrastructure, making GIS essential for substations. METI guidelines encourage the use of space-efficient and environmentally sound transmission technologies. Tokyo's dense urban environment relies heavily on GIS for efficient power distribution and resilience.
Gas Insulated Transmission Lines Market Key Industry Players
Concentration sits with established multinational engineering conglomerates that offer integrated power solutions for large-scale grid projects. The market exhibits a tiered structure, with a few global leaders dominating high-value segments like HVDC GITL systems. Competitive dynamics are driven by strategic partnerships for technology development and continuous portfolio diversification into SF6-free alternatives. Geographic expansion into emerging markets also represents a significant competitive move.
Among the global engineering powerhouses, Siemens Energy exemplifies leadership in developing and deploying alternative insulation mediums, particularly clean air solutions. Hitachi Energy, a global technology and services company, occupies a strong position by leveraging its extensive high-voltage portfolio to integrate these new SF6-free systems into comprehensive grid solutions. General Electric, an American industrial giant, anchors the segment focusing on advanced gas mixture research to find viable, lower-impact SF6 replacements, highlighting continuous innovation in complex electrical infrastructure.
| Leading Market Players |
|---|
| General Electric |
| Larsen & Toubro |
| Siemens Energy |
| China XD Group |
| Schneider Electric |
| ABB |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Hitachi Energy |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized SF6-free components directly influence the market's supply chain configuration, thereby impacting the pricing power of manufacturers capable of rapid delivery.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure for new SF6-free GITL systems. Project-based contracts dominate, with price differentiation driven by customization level for specific grid integration challenges and comprehensive after-sales service packages. Pricing pressure stems from the high initial investment required for GITL projects. Renewable energy project developers exhibit higher price sensitivity compared to electric utilities, which prioritize long-term grid reliability.
Supply Chain Analysis
Specialized manufacturing capacity for high-voltage SF6-free components underwrites the supply chain for Gas Insulated Transmission Lines. Supply concentrates in China for core components, Germany for advanced engineering, and Japan for compact GIS solutions. The market relies on a few key suppliers for advanced dielectric gases and high-grade metallic enclosures. Single-source vulnerability for these specialized SF6-free materials presents a structural supply chain risk, and distribution runs primarily through direct sales channels to electric utilities and large EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gas Insulated Transmission Lines market is an early-cycle expansion story, driven by the accelerating global penetration of large-scale renewable energy projects requiring compact, high-capacity grid connections.
For Market Incumbents: Shield core market share by accelerating R&D into next-generation SF6-free insulation materials and advanced gas mixtures. Deepen vertical integration into specialized component manufacturing for these new technologies to mitigate supply chain risks from emerging alternative insulation providers. This protects against the regulatory shift away from SF6 and the competitive pressure from new eco-friendly solutions. Siemens Energy and Hitachi Energy must continuously innovate.
For New Entrants and Emerging Players: Anchor in niche applications like offshore wind farm connections or urban substation upgrades where compact, SF6-free solutions are critical. Target regions with stringent environmental regulations, such as the European Union, to leverage compliant product portfolios. Offer bundled solutions combining GITL hardware with advanced IoT-based diagnostic software for predictive maintenance. This provides a distinct value proposition against established SF6 incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as an essential infrastructure modernization play because global grid expansion and decarbonization efforts mandate high-efficiency, compact transmission. Investors should seek acquisition targets among specialized component manufacturers for advanced SF6-free insulation or firms offering integrated digital monitoring platforms. The signal to watch is the adoption rate of mandatory SF6 phase-out schedules in major economies beyond the European Union.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Manufacturers can reduce environmental footprint across production of SF6-free components, enhancing brand reputation among eco-conscious utilities. |
| Technology Licensing | Licensing advanced SF6-free insulation patents accelerates market adoption of alternatives and establishes new revenue streams. |
| Strategic Partnership | Partnering with large-scale renewable energy developers ensures early integration of GITL into major green power projects. |
| Capacity Expansion | Increasing production of compact Gas Insulated Switchgear addresses growing demand from dense urban substations and grid modernization. |
| Software-Defined Grid Investment | Integrating advanced diagnostic software into GITL offerings enhances predictive maintenance capabilities and overall grid reliability for operators. |
Research Approach
A standing panel of utility planning officers, EPC contractors, high-voltage engineers, and renewable project developers provided ongoing calibration for market sizing and trend validation. This analysis integrated primary interviews with industry stakeholders and secondary validation from CIGRE reports and national grid development plans. A robust bottom-up and top-down triangulation approach ensured data consistency across all segments.
Quantitative outputs were consistently checked against external benchmarks, including national grid investment forecasts and renewable energy deployment targets over the projection horizon. The analytical framework modeled product type, technology, end user, and application segmentation. Compound annual growth rates were derived through iterative modeling, incorporating projected infrastructure investments. Government grid modernization budgets were a key forecast input.
Decision-makers should treat outputs as directional under assumptions of stable regulatory environment and consistent grid investment; material deviation would warrant model refresh. Forecasts reflect these assumptions. Practitioners should keep alternative scenarios live as regulatory mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Fuse Rails Market