
 EV DC Fast Charger Market | 2026-2036
EV DC Fast Charger Market Size, Share, and Industry Trends Forecast 2026-2036
EV DC Fast Charger Market Foresight
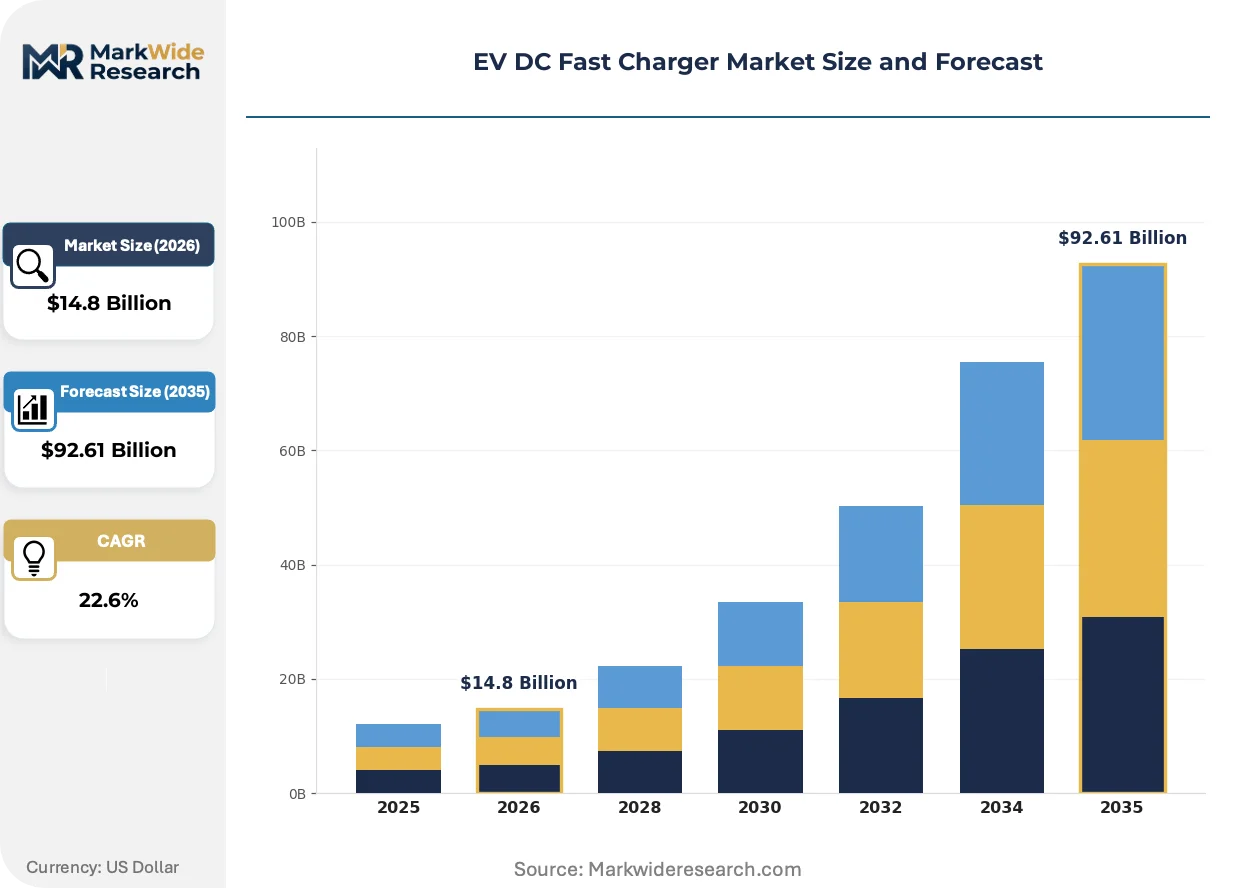
Commercial fleet electrification is broadening the addressable base for high-power charging infrastructure beyond early retail adopters. Tesla anchors the North American landscape through proprietary connector dominance and captive vehicle demand. ABB competes on manufacturing scale across European and Asian utility contracts. ChargePoint leverages software-integrated hardware to control urban and suburban installation networks.
An EV DC Fast Charger converts alternating current from the grid to direct current delivered at 50 kW to 350 kW, bypassing onboard vehicle inverters to compress refueling intervals toward parity with liquid fuels. Standalone units dominate highway corridor deployments where space and grid capacity permit dedicated infrastructure, while wall-mounted systems penetrate constrained retail and fleet depot settings. CCS connectors lead in European and North American interoperability mandates, though Tesla Supercharger technology sustains proprietary ecosystem loyalty.
The US Department of Transportation, the European Union through its Alternative Fuels Infrastructure Regulation, and China's National Development and Reform Commission each mandate minimum charging density targets along transport corridors. These frameworks shape product standards for connector compatibility, payment interoperability, and grid integration protocols. Stakeholders must monitor evolving power level classifications and bi-directional charging standards as fleet operators evaluate vehicle-to-grid revenue streams against capital recovery timelines.
Market Dynamics
The transition from 150 kW to 350 kW+ power tiers is compressing dwell times for commercial fleets while straining transformer substations and distribution networks. This power escalation rewrites site economics and forces hardware-software co-design.
Growth Catalysts
- Alternative Fuels Infrastructure Regulation:The EU mandate requires charging stations every 60 kilometers along core transport corridors by 2025, compelling hardware procurement cycles across Germany, France, and the Netherlands.
- Commercial fleet electrification:Last-mile delivery operators and regional trucking companies are converting depot parking into megawatt-scale charging hubs, expanding addressable infrastructure demand beyond highway retail.
- Silicon carbide power electronics:Wider bandgap semiconductors cut thermal losses and enable compact 350 kW cabinet designs, reducing footprint requirements for constrained urban sites.
Market Restraints
- Copper and rare earth price volatility:Power cable assemblies and permanent magnet components in cooling systems face input cost swings that compress hardware margins.
- Transformer lead times:North American utility equipment backlogs extend site energization timelines, delaying revenue recognition for infrastructure developers.
- CCS-NACS connector fragmentation:Competing physical interface standards force multi-cable hardware configurations that raise unit costs and complicate inventory management.
Strategic Opportunities
- Vehicle-to-grid integration:Bi-directional charging standards under IEEE 1547 revision open revenue stacking models for fleet operators arbitraging peak demand charges.
- India's FAME III subsidy framework:Central government incentives for 50 kW+ public charging along national highways create first-mover positioning for equipment suppliers.
- Autonomous charging robotics:Automated connector alignment systems address accessibility compliance and reduce labor costs for unattended highway plazas.
Industry Challenges
- High-voltage technician scarcity:Installation and maintenance of 1000V DC systems requires certified electricians with utility-scale experience, creating labor bottlenecks in secondary markets.
- Utility intercoordination complexity:Feeder upgrades, demand charge negotiations, and time-of-use rate optimization require specialized regulatory affairs capacity that stretches mid-size operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV DC Fast Charger Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $92.61 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Portable, Standalone, Networked Technology: CCS, CHAdeMO, Tesla Supercharger, IEC End User: Commercial Fleets, Retail Outlets, Highway Stations, Residential Installation: On-Site, Off-Site, Urban Area, Suburban Area |
| Companies Covered | Tesla, ChargePoint, ABB, EVgo, Blink Charging, Delta Electronics, Star Charge, TELD New Energy, EVBox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV DC Fast Charger Market Shifts & Advancements
Power module architecture and energy management software are converging to enable dynamic load sharing across multi-vehicle sessions. These advances compress infrastructure capital per charging point while raising utilization economics.
Modular power stacks with 50 kW building blocks are decentralizing capacity deployment for fleet depots. Logistics operators in California and Texas are adopting scalable configurations that expand from 150 kW to 500 kW without full hardware replacement. This architecture defers capital commitment until vehicle counts justify incremental power investment.
The US Department of Transportation's National Electric Vehicle Infrastructure program mandates payment interoperability and 97% uptime reliability. State transportation departments are embedding these requirements into RFP scoring, disadvantaging hardware-only vendors lacking integrated network operations centers. Equipment suppliers are responding by acquiring software platforms or forming exclusive service partnerships.
Fleet procurement teams are consolidating vendor relationships around full-service availability guarantees rather than unit purchase models. Large logistics operators in Germany and the United Kingdom now contract for guaranteed charge delivery per vehicle-day, transferring utilization risk to infrastructure providers. This compresses hardware margins while expanding recurring software and services revenue pools.
EV DC Fast Charger Market Segmentation
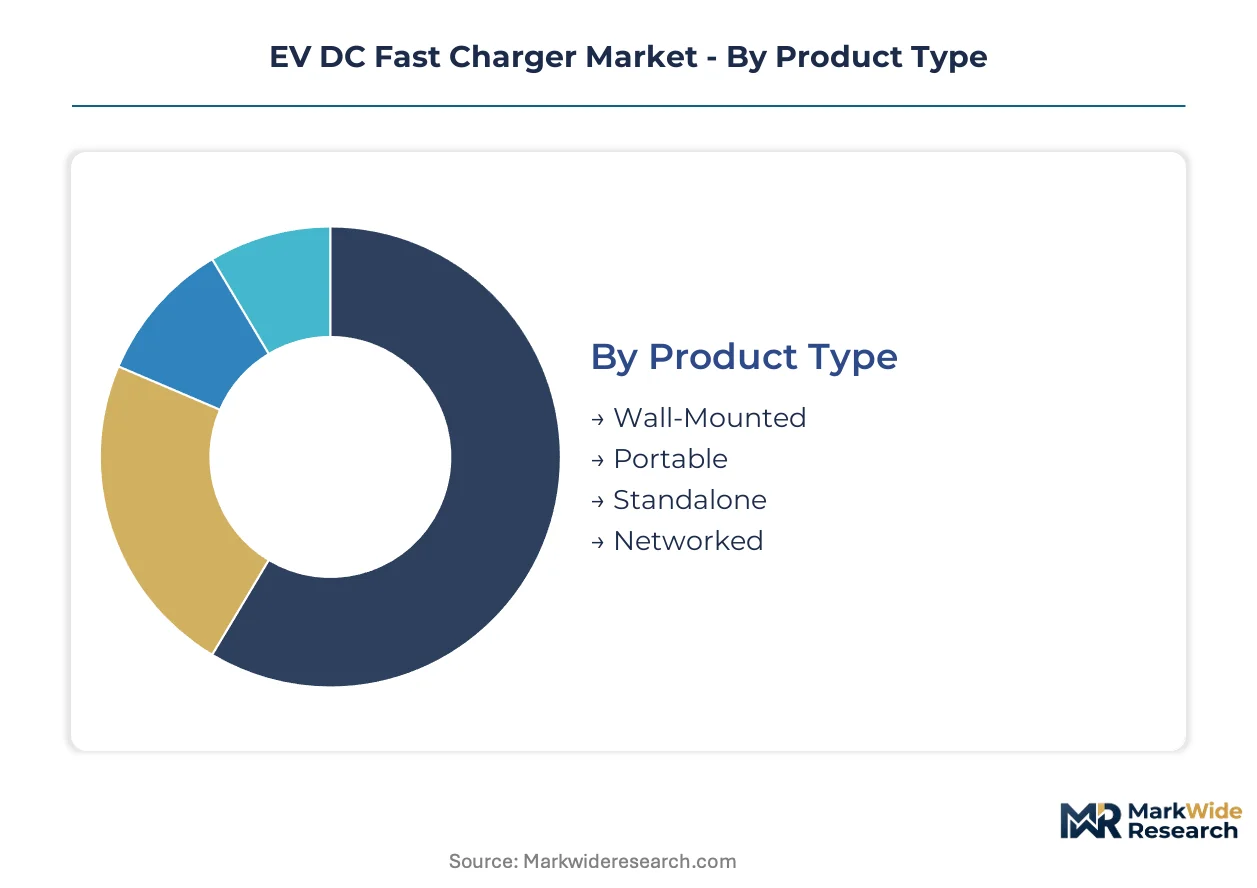
Segmentation in the EV DC Fast Charger Market reveals how certification requirements, connector standards, and site economics fragment procurement decisions across fleet operators and infrastructure developers. Understanding these divides illuminates where hardware margins concentrate and where software-integrated solutions command pricing power.
Product Type:
Wall-Mounted and Standalone units face divergent certification burdens under NEC Article 625 and IEC 61851-23, while Portable systems trigger additional transport safety protocols.
- Wall-Mounted:Compact cabinet designs mount directly to depot walls or retail building facades, reducing civil works costs. Demand clusters at urban logistics hubs in California and Germany where real estate constraints limit ground footprint.
- Portable:Mobile DC units deploy on trailers for temporary events or emergency roadside assistance. Fleets in Texas and Florida use these for seasonal demand spikes without permanent grid interconnection.
- Standalone:Self-supporting cabinets dominate highway corridor deployments with dedicated transformer capacity. These systems require full utility coordination and NEVI-compliant payment interoperability.
- Networked:Cloud-connected hardware enables dynamic load balancing and remote diagnostics. Operators prioritize these for multi-site fleet contracts where uptime guarantees determine vendor selection.
Standalone sits at the top of the volume ranking, with Networked climbing the fastest.
Technology:
Connector technology segmentation maps directly to regional regulatory mandates and vehicle OEM alignment, with certification costs varying sharply across standards bodies.
- CCS:Combined Charging System dominates European and North American interoperability mandates, supporting power levels up to 350 kW. German highway stations and California corridor sites standardize on CCS2 and CCS1 respectively.
- CHAdeMO:Japanese-origin standard retains installed base among older Nissan and Mitsubishi fleets. Declining new vehicle adoption limits growth to replacement cycles in Japan and select Southeast Asian markets.
- Tesla Supercharger:Proprietary connector sustains captive ecosystem loyalty through NACS standardization push. Opening to non-Tesla vehicles under NEVI funding requirements expands addressable hardware demand.
- IEC:International Electrotechnical Commission standards govern grid integration protocols and communication layers. Utility-scale projects in China and India reference IEC 61851 for bidirectional charging readiness.
CCS captures the largest installed base, while Tesla Supercharger gains share fastest through network licensing deals.
End User:
End user segmentation determines capital recovery timelines, with commercial fleets demanding availability guarantees that reshape vendor pricing models.
- Commercial Fleets:Depot-based charging for last-mile delivery and regional trucking converts parking assets into energy hubs. Amazon, DHL, and UPS contracts in Germany and the United States specify megawatt-scale installations with 99% uptime SLAs.
- Retail Outlets:Shopping centers and fuel stations deploy chargers to extend dwell time and capture ancillary revenue. Site hosts prioritize compact wall-mounted units with minimal grid upgrade requirements.
- Highway Stations:Interstate corridor sites require 350 kW+ capacity and multi-connector redundancy under federal mandate programs. NEVI funding scoring favors locations with 97% reliability commitments.
- Residential:Single-family home installations rarely justify DC fast charging economics, limiting this segment to high-net-worth early adopters with luxury EV portfolios.
Commercial Fleets anchor procurement volume, with Highway Stations expanding most quickly under infrastructure stimulus programs.
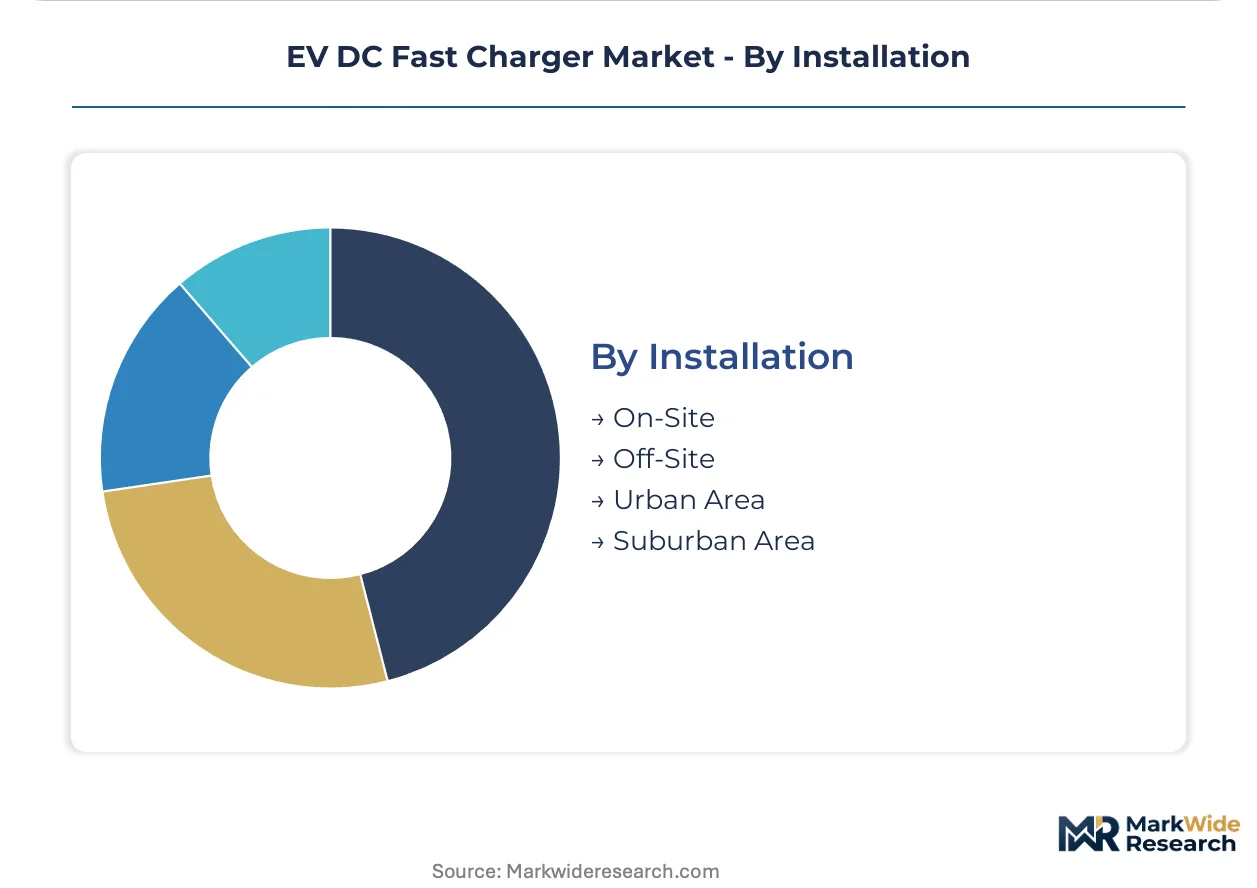
Installation:
Installation geography determines grid interconnection complexity and permitting timelines, with urban sites facing transformer scarcity that extends project schedules.
- On-Site:Charging infrastructure co-located with fleet depots or retail properties enables controlled access and demand charge optimization. California and Texas operators favor on-site configurations for vehicle-to-grid revenue stacking.
- Off-Site:Third-party charging plazas serve dispersed fleet routes and public demand without captive real estate. These installations require negotiated roaming agreements and interoperable payment systems.
- Urban Area:Dense city centers face distribution network constraints and underground utility coordination. Silicon carbide power electronics reduce footprint for constrained Manhattan, London, and Singapore sites.
- Suburban Area:Peripheral locations offer available grid capacity and lower land costs for standalone highway-adjacent plazas. Suburban corridors in Ohio, Pennsylvania, and Bavaria concentrate new 350 kW deployments.
On-Site leads deployment counts, with Urban Area facing the steepest expansion constraints from transformer lead times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor along the Rhine-Main-Neckar region concentrates Europe's densest deployment of high-power charging infrastructure for commercial electrification.
United States
Interstate highway corridors and urban logistics hubs drive procurement volume from last-mile delivery operators and regional trucking fleets. The US Department of Transportation's National Electric Vehicle Infrastructure program mandates 97% uptime reliability and payment interoperability, reshaping vendor selection criteria. California's Central Valley and Texas Triangle anchor megawatt-scale depot installations serving Amazon and UPS electrification commitments.
Germany
Commercial fleet operators and highway service stations dominate hardware demand along the Autobahn network. The EU's Alternative Fuels Infrastructure Regulation requires charging stations every 60 kilometers along core transport corridors by 2025, accelerating procurement cycles. The Rhine-Ruhr metropolitan region concentrates 350 kW deployments serving DHL and DB Schenker electrification timelines.
China
National highway networks and municipal bus depots sustain the world's largest installed base of DC fast charging capacity. The National Development and Reform Commission mandates minimum charging density targets along transport corridors under dual carbon policy frameworks. The Yangtze River Delta region clusters manufacturing and deployment activity for 500 kW+ liquid-cooled systems.
India
National highway corridors and state transport corporation depots emerge as priority sites under central subsidy frameworks. The FAME III scheme incentivizes 50 kW+ public charging infrastructure along Golden Quadrilateral routes. Maharashtra and Gujarat anchor early deployment clusters serving Tata Motors and Ashok Leyland electric bus procurement.
EV DC Fast Charger Market Competitive Landscape
Technology licensing dominates the current landscape as proprietary connector standards fragment procurement decisions across regional markets. The vendor base organizes around three strategic archetypes: integrated automotive OEMs with captive charging networks, industrial electrical manufacturers leveraging utility-scale project experience, and pure-play charging network operators bundling software with hardware deployment. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers position for NEVI-funded highway corridor awards and fleet depot megacontracts.
Among integrated automotive OEMs, Tesla exemplifies the proprietary ecosystem model through its Supercharger network and NACS standardization push. ABB represents the industrial electrical archetype with manufacturing scale across European and Asian utility contracts. ChargePoint occupies a position within the network-operator tier, leveraging software-integrated hardware to control urban and suburban installation networks.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVgo |
| Blink Charging |
| Delta Electronics |
| Star Charge |
| TELD New Energy |
| EVBox |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up charging network specialists have consolidated fragmented installation contractors across California and Texas, compressing field-service margins while concentrating pricing power with hardware-software integrated vendors serving NEVI-funded highway corridors.
Pricing Analysis
Distributor margin layers vary sharply between direct-to-fleet depot contracts and retail site-host arrangements. Three-tier pricing structure across premium 350 kW cabinets, standard 150 kW units, and economy 50 kW hardware reflects silicon carbide component differentiation and UL certification tiers. Pricing pressure stems from transformer lead times extending project timelines and forcing vendors to absorb carrying costs. Commercial fleet procurement teams exhibit lowest price sensitivity due to availability-guarantee requirements, while independent retail site hosts negotiate aggressively on upfront hardware costs.
Supply Chain Analysis
Power module supply rests on Chinese and German semiconductor packaging facilities, with silicon carbide wafers drawing from Japanese substrate producers and Malaysian backend assembly. Copper busbar assemblies and liquid-cooled cable harnesses anchor component dependencies alongside rare-earth permanent magnets for thermal management pumps. Single-source vulnerability concentrates in 1000V-rated capacitor films sourced from Japanese specialty chemical producers. Distribution runs through electrical wholesale channels serving utility-scale EPC contractors and direct OEM relationships with fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on silicon carbide cost curves flattening and fleet operators accepting premium pricing for guaranteed uptime SLAs.
For Market Incumbents: Deploy dynamic load-balancing software as the anchor lever to defend against pure-play hardware vendors. Acquire certified high-voltage technician training programs to alleviate installation bottlenecks in secondary markets. Consolidate backward integration into power module assembly to offset rare-earth magnet cost volatility. For New Entrants and Emerging Players: Fleet depot operators in India's Maharashtra and Gujarat corridors represent the most penetrable channel partner type for first-mover positioning. Target 50 kW+ highway-adjacent installations under FAME III subsidy frameworks before incumbent networks establish density. Pursue white-label hardware partnerships with established network operators lacking manufacturing scale. For Investors and Strategic Acquirers: Valuations sit cheapest among regional installation contractors with NEVI-compliant project pipelines but limited software capabilities. Long-term viability favors vendors with integrated network operations centers and recurring services revenue exceeding hardware margins. Monitor bi-directional charging standard finalization under IEEE 1547 revision as the signal for vehicle-to-grid revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Integration | Reduces thermal losses and enables compact 350 kW cabinet designs for constrained urban sites. |
| NEVI-Compliant Network Operations Center Buildout | Satisfies 97% uptime mandates and payment interoperability requirements for federal highway funding. |
| Certified High-Voltage Technician Training Programs | Alleviates labor bottlenecks for 1000V DC installation and maintenance in secondary markets. |
| Vehicle-to-Grid Software Platform Development | Captures peak demand charge arbitrage revenue under emerging IEEE 1547 bi-directional standards. |
| Modular Power Stack Architecture Deployment | Enables fleet depots to scale from 150 kW to 500 kW without full hardware replacement. |
Research Methodology
Direct dialogue with fleet electrification directors, utility interconnection planners, charging network operations executives, and high-voltage installation contractors grounded qualitative findings. Secondary validation drew from NEVI program filings, FERC interconnection queue data, state transportation department RFP documents, and SEC disclosures from publicly traded charging network operators. Bottom-up unit deployment estimates across product types, connector standards, and end-user segments were triangulated against top-down infrastructure spending projections.
Installed base and revenue estimates across the projection horizon reflect segmentation by power tier, connector technology, installation geography, and fleet operator contract structure. CAGRs were derived from regression analysis against vehicle electrification timelines, regulatory mandate schedules, and utility grid upgrade cycles. Forecast inputs incorporated silicon carbide adoption curves, transformer manufacturing capacity constraints, and bi-directional charging standardization progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to utility intercoordination timelines, copper and rare-earth commodity trajectories, and CCS-NACS connector standard resolution. A small set of triggers—including FAME III disbursement velocity, IEEE 1547 revision finalization, and NEVI funding allocation patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Wireless Electric Vehicle Charger Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Europe Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market