
 EV Charging Infrastructure Market | 2026-2036
EV Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charging Infrastructure Market Analysis
Certified electrical technician shortages across major economies is unwinding installation timelines and inflating project costs for network operators. Tesla leverages its Supercharger manufacturing scale to control hardware deployment cadence in priority corridors. ABB sustains technology leadership in high-power DC rectifier systems for commercial fleet depots. ChargePoint competes through software-integrated hardware that anchors recurring revenue from network management services.
EV charging infrastructure encompasses the full stack of electrical equipment, communication protocols, and grid-interconnection systems that transfer energy from distribution networks to battery-electric vehicles, typically operating at power levels from 1.4 kW residential Level 1 up to 350 kW DC fast charging with liquid-cooled cables. The primary purpose is to replenish vehicle energy stores at speeds matched to dwell-time economics across residential, workplace, and en-route scenarios. DC Fast Charger deployments command the dominant share of capital allocation due to their critical role in highway corridor completion and fleet turnaround requirements. Workplace charging within the Application dimension exhibits structural growth as employers integrate EV benefits into retention strategies and Scope 3 emissions accounting.
The US Inflation Reduction Act and FERC interconnection rules shape demand by subsidizing charger capital costs and standardizing grid-access timelines for large installations. Europe's EU Green Deal and AFIR regulation mandate minimum fast-charging coverage density along trans-European transport corridors by specified deadlines. Stakeholders must monitor utility rate-case proceedings and dynamic pricing pilots, as these will determine whether demand charges or time-of-use structures govern the operating economics of high-utilization public stations.
Market Dynamics
Fleet electrification mandates and IRA tax credits are compressing deployment timelines while certified electrical technician shortages inflate installation costs and extend project backlogs.
Growth Catalysts
- US Inflation Reduction Act:Tax credits for charger hardware and installation accelerate private capital deployment into highway corridor fast-charging networks.
- Germany's autobahn fast-charging mandate:Minimum coverage density requirements along federal motorways force OEMs and operators to accelerate infrastructure buildout.
- Workplace charging integration:Employers deploy Level 2 stations as Scope 3 emissions accounting and employee retention tools drive facility electrification.
Market Restraints
- Copper and silicon carbide supply concentration:Power electronics and cable raw material sourcing concentrates in limited geographies, exposing hardware manufacturers to input cost volatility.
- Grid interconnection queues:Utility upgrade timelines for high-power DC installations extend 18-36 months in congested distribution territories.
- Dynamic pricing uncertainty:Unresolved demand charge structures and time-of-use rate cases prevent operators from underwriting station economics.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Domestic cell manufacturing scale creates adjacent opportunity for integrated charging-plus-storage depot solutions.
- Vehicle-to-grid convergence:Bidirectional charging protocols unlock grid services revenue streams for fleet operators with stationary battery assets.
- Curbside residential charging:Municipal right-of-way access programs in dense urban districts address multi-unit dwelling access gaps.
Industry Challenges
- Certified electrician scarcity:Journeyman technician pipeline constraints delay commissioning timelines and inflate labor rates for network operators.
- OCPP and ISO 15118 interoperability:Protocol fragmentation between vehicle onboard chargers and station management systems complicates roaming and payment integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charging Infrastructure Market |
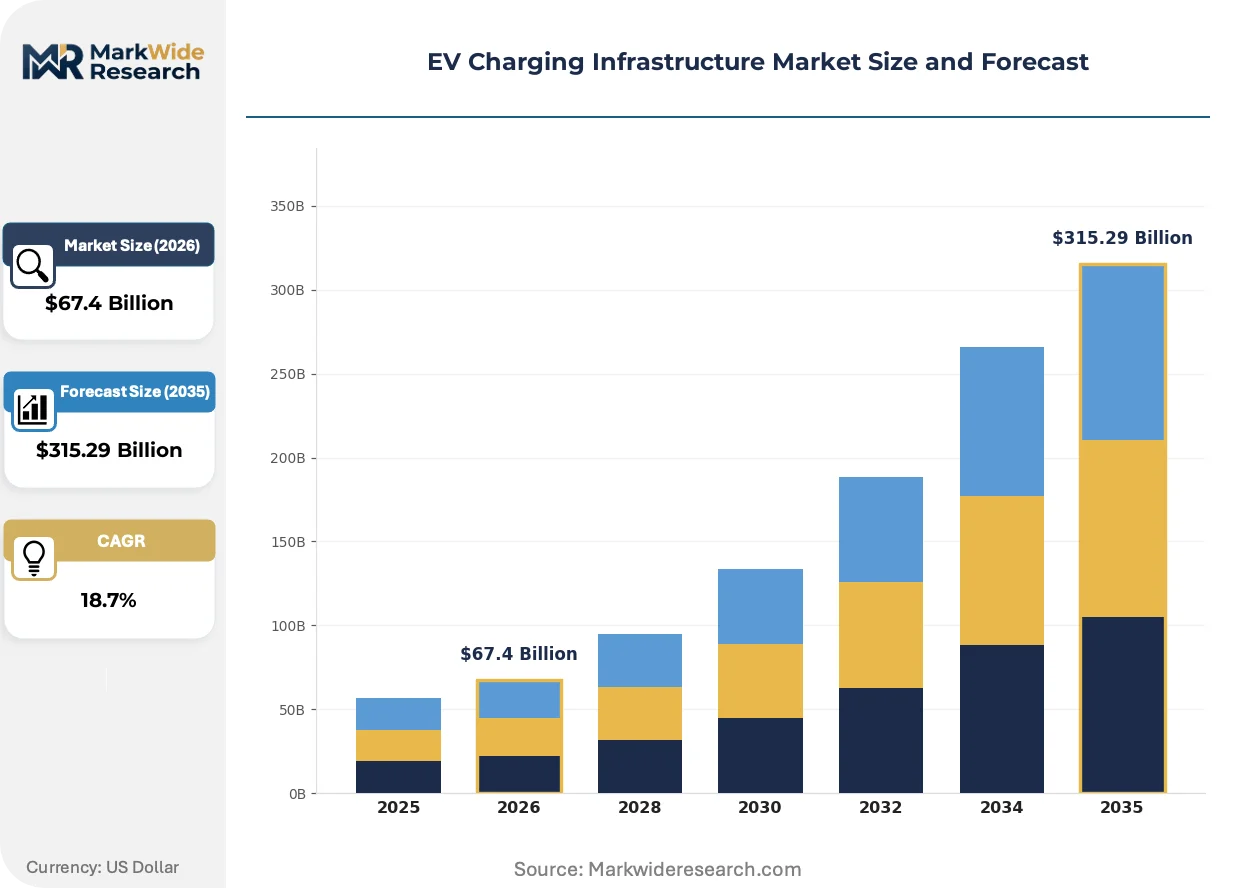
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $315.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: Level 1, Level 2, DC Fast Charger, Wireless Charger, Ultra-Fast Charger Application: Public Parking, Workplace, Fleet Depots, Commercial Complexes, Highway Stations Deployment Model: Residential, Public, Commercial, Private Fleet, Destination Charging End User: Vehicle Owners, Fleet Operators, Charging Network Providers, Utilities, Service Stations |
| Companies Covered | Tesla, ChargePoint, ABB, EVgo, Shell Recharge, BP Pulse, Electrify America, EVBox, Blink Charging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charging Infrastructure Market Emerging Trajectories
Hardware modularity and software-defined power conversion are compressing capital deployment cycles while regulatory mandates force standardization across previously fragmented protocols.
Silicon carbide power semiconductors replace legacy IGBT modules in DC fast charger rectifier stages. OEMs and charging network operators adopt SiC-based 350 kW systems for highway corridor deployments. This technology is decomposing thermal management costs and enabling higher power density in constrained site footprints.
EU AFIR regulation mandates minimum fast-charging coverage density along trans-European transport corridors with binding deadlines. Member states must enforce interoperability and pricing transparency requirements. Commercial fleet operators in Germany, France, and the Netherlands accelerate depot electrification to meet compliance timelines.
Fleet procurement departments now require charging-as-a-service contracts with guaranteed uptime SLAs rather than capital hardware purchases. Energy retailers and oil majors displace traditional equipment vendors as primary contracting parties. This shift concentrates most visibly in North American heavy-duty trucking electrification programs.
EV Charging Infrastructure Market Segmentation
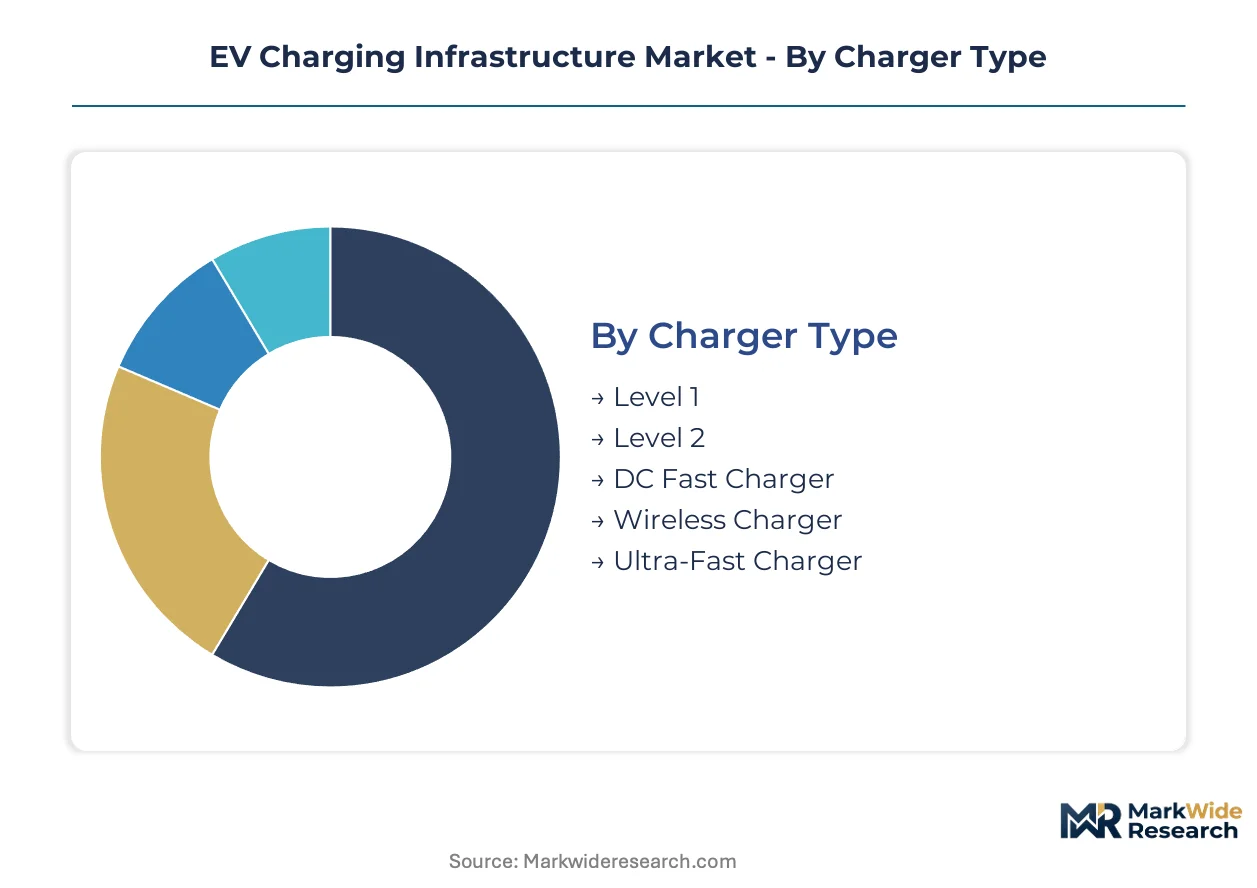
Segmentation in EV charging infrastructure reveals how capital allocation, installation complexity, and utilization economics vary dramatically across power levels and deployment contexts. Understanding these divides enables operators to match hardware specifications to dwell-time requirements and revenue models.
Charger Type:
Hardware procurement channels bifurcate between residential retail distribution, commercial electrical supply houses, and direct OEM relationships for high-power DC systems.
- DC Fast Charger:Liquid-cooled cable systems operating at 150-350 kW dominate highway corridor and fleet depot deployments. Demand concentrates in Germany's autobahn network buildout and US IRA-subsidized interstate corridors where turnaround time economics mandate sub-30-minute charging cycles.
- Level 2:7-19 kW AC systems with J1772 or Type 2 connectors anchor workplace and multi-unit dwelling installations. North American employers and European commercial landlords drive procurement through sustainability-linked facility budgets and employee benefit programs.
- Level 1:Standard 120V residential outlets delivering 1.4 kW serve overnight home charging with minimal hardware cost. US single-family homeowners represent the primary channel.
- Ultra-Fast Charger:350+ kW systems with advanced thermal management target heavy-duty trucking electrification and premium passenger segments. Pilot deployments cluster along California's I-5 freight corridor and Netherlands-Germany border crossings.
- Wireless Charger:Inductive pad systems eliminate connector wear for autonomous fleet applications. Limited commercial deployment in Singapore taxi trials and Detroit automaker R&D partnerships.
By volume, Level 2 leads. By growth pace, DC Fast Charger is ahead.
Application:
Site control and electricity rate structures determine margin profiles more than power level alone.
- Workplace:Employer-subsidized Level 2 installations with extended dwell periods (6-8 hours) generate stable utilization through captive commuter demand. US corporate campuses and German industrial parks anchor procurement.
- Fleet Depots:Centralized DC fast charging with depot energy management systems serves return-to-base logistics and municipal bus operations. California transit agencies and Dutch delivery fleets drive deployment scale.
- Highway Stations:High-power DC installations at retail fuel and convenience locations depend on traffic volume and grid interconnection availability. US Interstate corridors and France's autoroute network concentrate investment.
- Public Parking:Mixed-use Level 2 and DC systems in municipal garages and curbside locations serve opportunistic charging. London borough programs and New York City curbside pilots define channel development.
- Commercial Complexes:Retail-anchored charging extends customer dwell time and captures discretionary spending. Scandinavian shopping centers and Australian supermarket chains lead integration.
Fleet Depots capture the highest per-site revenue. Workplace installations are expanding most quickly.
Deployment Model:
Ownership structures determine who bears interconnection costs and demand charge exposure.
- Private Fleet:Captive depot charging with guaranteed offtake eliminates utilization risk for capital-intensive DC systems. US last-mile delivery operators and German supermarket chains dominate procurement.
- Public:Open-network fast charging with roaming interoperability requirements serves variable-demand highway and urban locations. EU AFIR-mandated coverage density drives European deployment.
- Residential:Single-family home Level 1/2 installations with behind-the-meter solar integration. California and Norway lead penetration rates.
- Commercial:Workplace and retail-hosted systems with employer or landlord capital commitment. US corporate sustainability programs and Japanese convenience store chains anchor growth.
- Destination Charging:Hospitality and leisure-anchored Level 2 serving extended-stay guests. Ski resorts in Colorado and Alpine regions define premium positioning.
Private Fleet delivers the steadiest returns. Public networks face the steepest utilization curves.
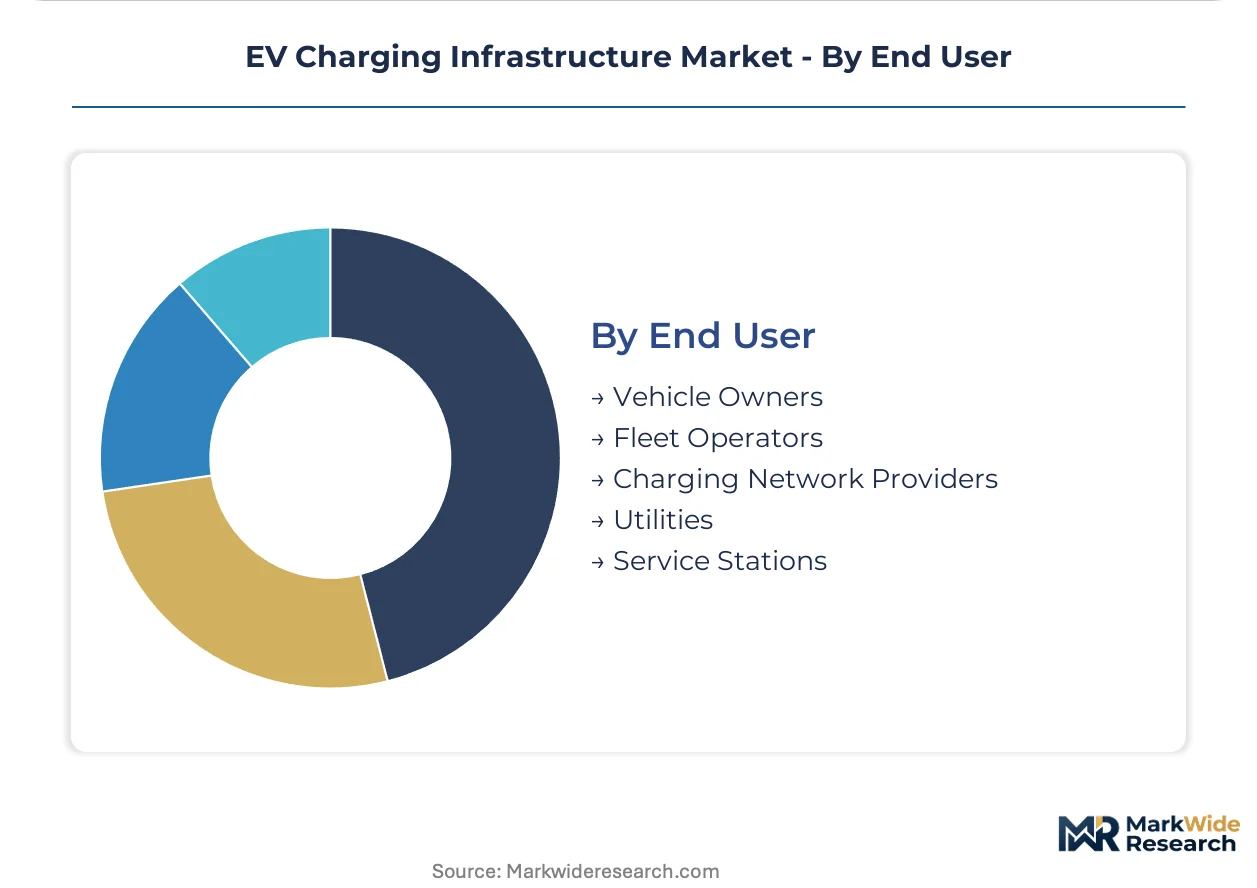
End User:
Procurement sophistication and contract structures diverge sharply across buyer types.
- Fleet Operators:Charging-as-a-service contracts with guaranteed uptime SLAs replace capital purchases. North American heavy-duty trucking electrification programs concentrate demand.
- Charging Network Providers:Pure-play operators and energy retailers competing on roaming coverage and software integration. European incumbents and US oil-major entrants drive consolidation.
- Utilities:Grid-edge infrastructure investments with managed charging and vehicle-to-grid integration pilots. California IOUs and German municipal utilities lead regulatory filings.
- Vehicle Owners:Individual residential and public charging consumption with price-sensitive behavior. Norwegian and Chinese EV penetration rates define market maturity.
- Service Stations:Fuel retail incumbents retrofitting locations with DC fast charging to retain mobility customers. Shell and BP network rollouts span UK, Germany, and Netherlands.
Fleet Operators command the largest contract values. Charging Network Providers are scaling most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands hardware pricing premiums through its autobahn fast-charging mandate, while the United States captures installation cost advantages via IRA tax credits that compress capital deployment cycles.
United States
Fleet electrification mandates from Amazon, UPS, and FedEx are compressing depot deployment timelines across the Midwest and Southeast. FERC interconnection rules standardize grid-access timelines for large installations, reducing utility queue uncertainty. California's I-5 freight corridor anchors ultra-fast charging pilot programs targeting heavy-duty trucking electrification.
Germany
OEM fleet electrification timelines from BMW, Mercedes-Benz, and Volkswagen are accelerating infrastructure buildout along federal motorways. EU AFIR regulation mandates minimum fast-charging coverage density with binding deadlines. The Ruhr industrial cluster concentrates depot electrification projects serving return-to-base logistics operations.
China
State Grid Corporation's nationwide charging network expansion targets highway corridor completion by specified deadlines under dual carbon goals. MIIT standardization drives interoperability across previously fragmented protocols. The Yangtze River Delta region anchors high-power DC manufacturing scale for domestic and export markets.
Netherlands
Shell and BP network rollouts concentrate investment along the Netherlands-Germany border crossings serving premium passenger segments. EU Green Deal subsidies accelerate curbside residential charging programs in Amsterdam and Rotterdam municipal right-of-way access pilots. Randstad urban density creates multi-unit dwelling charging access gaps that workplace and public installations address.
India
Domestic cell manufacturing scale under the PLI scheme for ACC batteries creates adjacent opportunity for integrated charging-plus-storage depot solutions. CEA regulatory filings standardize grid interconnection requirements for high-power DC installations. Maharashtra and Gujarat industrial corridors anchor fleet operator procurement of charging-as-a-service contracts.
EV Charging Infrastructure Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated manufacturers controlling hardware deployment cadence while pure-play software operators capture recurring revenue from network management services. The vendor base spans automotive OEM captive units, electrical equipment conglomerates, energy retailers, and oil-major mobility divisions. Three strategic archetypes dominate: manufacturing-scale hardware suppliers, software-integrated platform operators, and charging-as-a-service providers. M&A activity concentrates among energy retailers acquiring network operators, while capacity expansion focuses on silicon carbide power electronics manufacturing.
Within the manufacturing-scale tier, Tesla and ABB occupy positions that exemplify divergent strategic approaches to corridor and depot deployments. Among software-integrated operators, ChargePoint represents the platform archetype that anchors recurring revenue models through network management services. Shell Recharge and BP Pulse sit within the energy retailer category that is displacing traditional equipment vendors as primary contracting parties for fleet procurement departments.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVgo |
| Shell Recharge |
| BP Pulse |
| Electrify America |
| EVBox |
| Blink Charging |
| Others |
Supply Flow & Price Mechanics
Charging-as-a-service contracts with guaranteed uptime SLAs lock in multi-year offtake commitments that simultaneously secure silicon carbide power electronics supply and stabilize per-kWh pricing visibility for fleet operators navigating volatile utility rate cases. This contractual structure concentrates procurement leverage among energy retailers and oil-major mobility divisions while compressing margins for pure-play hardware vendors exposed to spot-market copper and cable assemblies.
Pricing Analysis
The customization-premium spread between configured-to-order depot systems and standard highway corridor hardware runs wide, with fleet-specific energy management integrations commanding substantial uplifts over plug-and-play DC fast charger SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by power density, thermal management sophistication, and software integration depth. Cost compression in standard highway corridor equipment is intensifying because Tesla's captive manufacturing scale forces competitive matching on hardware deployment cadence. Fleet operators exhibit the lowest price sensitivity due to charging-as-a-service contract structures that outsource capital risk, while municipal curbside programs face acute budget constraints that favor economy-tier Level 2 procurement.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific manufacturing hubs through congested West Coast ports inflate landed costs for silicon carbide wafers and liquid-cooled cable assemblies, with container availability fluctuations adding 15-20% variability to procurement budgets. Power electronics manufacturing concentrates in China, Germany, and the United States, while copper cable extrusion and connector fabrication centers on Mexico, Vietnam, and South Korea. The supply chain draws from concentrated rare earth processing for permanent magnet components in motor drives and rectifier stages. Single-source vulnerability in silicon carbide substrate supply creates exposure to export restriction scenarios. Distribution runs through direct OEM relationships for high-power DC systems and electrical supply houses for commercial Level 2 deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
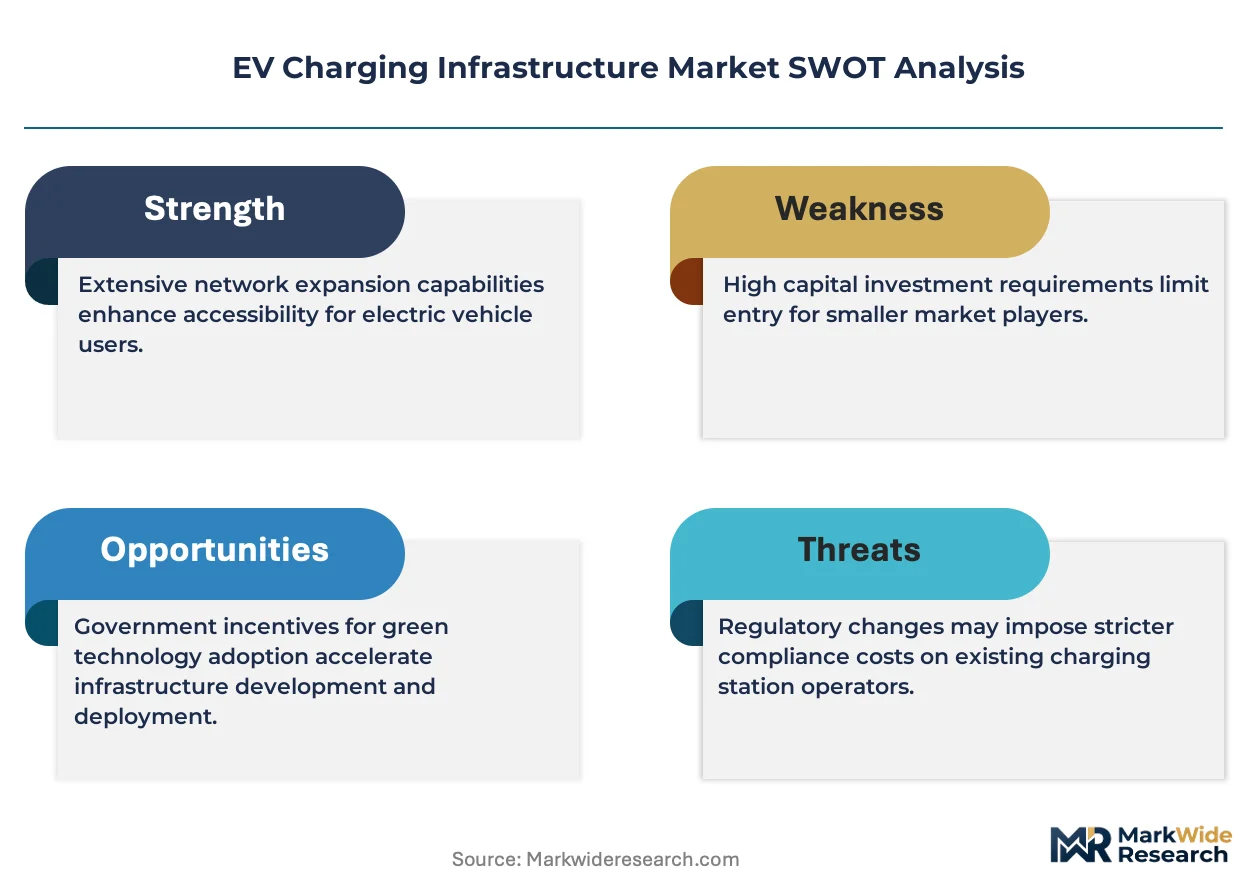
The EV charging infrastructure market represents high-growth disruption as the US Inflation Reduction Act's tax credit architecture compresses capital deployment cycles from 36 months to 18 months for highway corridor networks. Silicon carbide power semiconductor adoption is forcing a generational hardware refresh that rewards manufacturing scale and punishes component assemblers without rectifier-stage capabilities.
For Market Incumbents: Consolidate manufacturing-scale positions through backward integration into silicon carbide wafer supply and captive cable assembly production to defend against Tesla's vertical cost advantages. Prioritize certification investment in UL 2594 and ISO 15118-2 compliance to maintain interoperability leadership as EU AFIR mandates force protocol standardization. Channel control through exclusive electrical contractor networks protects installation timelines against certified technician scarcity.
For New Entrants and Emerging Players: Managed charging software for multi-asset fleet depots represents a service-layer gap where incumbents under-serve with generic hardware-centric offerings. Target India's PLI scheme corridors where integrated charging-plus-storage solutions lack established vendors with local regulatory expertise. A go-to-market angle anchored to CEA interconnection filing support and guaranteed grid-access timelines differentiates against hardware-only competitors.
For Investors and Strategic Acquirers: Pure-play software operators with recurring revenue from network management services and established roaming interoperability present the most attractive acquisition target archetype for energy retailers seeking charging-as-a-service capabilities. Long-term viability hinges on vehicle-to-grid protocol adoption creating grid services revenue streams that transform charging infrastructure from cost center to profit contributor. Watch FERC demand charge reform proceedings as the inflection indicator that would restructure station economics and accelerate capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Manufacturing Scale-Up | Tesla and ABB's captive wafer supply secures cost leadership in 350 kW rectifier deployments. |
| Charging-as-a-Service Platform Launch | Shell Recharge and BP Pulse displace equipment vendors as primary fleet contracting parties. |
| Vehicle-to-Grid Protocol Integration | Bidirectional charging unlocks grid services revenue for fleet operators with stationary battery assets. |
| Curbside Residential Access Program | Amsterdam and Rotterdam municipal right-of-way pilots address multi-unit dwelling charging gaps. |
| EU AFIR Compliance Certification | Interoperability and pricing transparency mandates force consolidation among fragmented network operators. |
Methodological Framework
Cross-validation between utility interconnection filing databases and fleet operator procurement records anchors the qualitative findings on deployment timeline compression and capital allocation priorities. Primary interviews with charging network executives, electrical contractor operations managers, utility planning officers, and fleet procurement directors combined with secondary validation against FERC dockets, CEA regulatory filings, EU AFIR implementation reports, and customs trade data for power electronics imports. Bottom-up installation tracking and top-down infrastructure investment surveys triangulate market sizing across charger type, application, and deployment model segments.
Sensitivity analysis on IRA tax credit phase-out scenarios and utility rate case outcomes frames the projection horizon, with volume and value outputs reflecting modeled adoption curves across the analysis window. Segmentation dimensions include charger power level, site application context, ownership structure, and end-user procurement sophistication, with CAGRs derived from least-squares fitting of historical deployment trajectories. Industry-specific forecast inputs incorporate silicon carbide cost decline curves and certified electrician pipeline constraints.
Forecasts assume regulatory continuity in US IRA tax credit structures and EU AFIR coverage mandates; material policy shifts would require re-modeling interconnection queue dynamics and hardware procurement incentives. Technology disruption risks from solid-state battery commercialization or wireless charging breakthroughs could compress DC fast charger demand. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Battery Swapping Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
Electric Car Charging Pile Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market