
 Electric Vehicle (EV) Charging Infrastructure Market | 2026-2036
Electric Vehicle (EV) Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Charging Infrastructure Market Analytics
Aftermarket service revenue from charger maintenance and network management is rewriting margin economics across the value chain. Tesla Inc. leverages its Supercharger network density to anchor a proprietary ecosystem that extends beyond vehicle sales. ABB Ltd. competes on industrial-scale manufacturing of high-power dispensers for highway corridor deployments. ChargePoint, Inc. specializes in software-integrated hardware that controls site-level energy management for commercial hosts.
Electric Vehicle Charging Infrastructure encompasses the physical and digital systems that deliver electrical energy from grid sources to battery-electric vehicles, incorporating power conversion electronics, connector interfaces rated up to 350 kW, and backend networking protocols for authentication and load balancing. DC Fast Chargers command premium positioning due to their 150 kW output capability that reduces dwell time for commercial fleet operators and highway travelers. Residential Users represent a mature volume base where Level 2 Chargers at 7 kW dominate home garage installations, while Public Charging Stations emerge as the fastest-growing end user category driven by municipal decarbonization targets and retail site host partnerships.
The US Federal Highway Administration's National Electric Vehicle Infrastructure program mandates Buy America compliance for federally funded charger deployments, reshaping supplier qualification requirements. The EU's Alternative Fuels Infrastructure Regulation binds member states to distance-based coverage targets along trans-European transport corridors, accelerating standardization around CCS2 connectors. China's GB/T charging standards and dual carbon goals enforce domestic technical specifications that filter market access for foreign equipment providers. Stakeholders must monitor how interoperability mandates and local content rules recalibrate competitive positioning across deployment geographies.
Market Dynamics
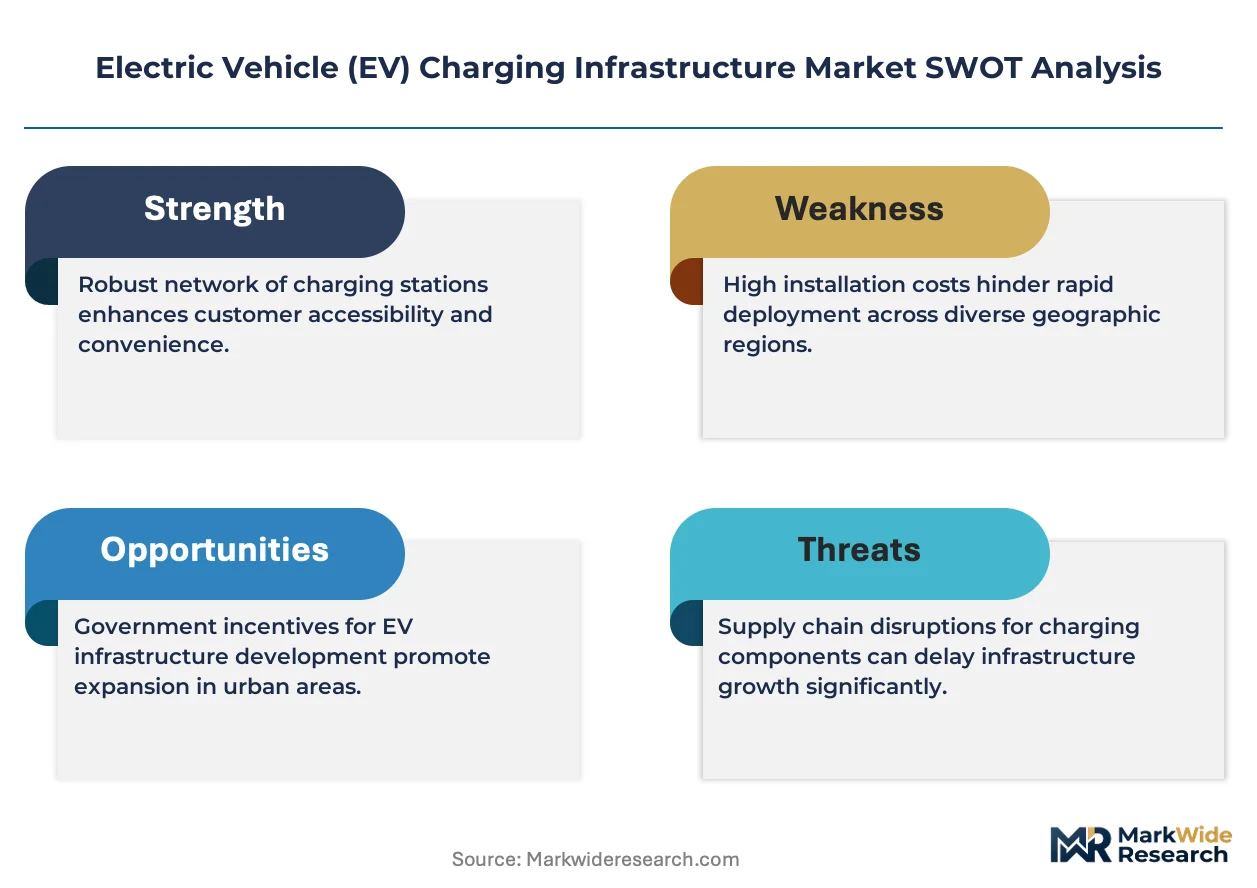
The US Inflation Reduction Act's domestic content mandates are forcing charger manufacturers to reconfigure supply chains around North American-sourced steel and power electronics, compressing deployment timelines for federally funded highway corridor projects.
Growth Catalysts
- California's SB 100 Directive:The state's 100% zero-emission vehicle sales mandate by 2035 is compelling commercial fleet operators to accelerate depot charging installations ahead of vehicle procurement cycles.
- Bi-directional charging hardware:Vehicle-to-grid integration technology is creating new revenue streams for site hosts through frequency regulation services and peak demand arbitrage.
- Texas utility make-ready programs:Oncor and CenterPoint Energy infrastructure incentives are lowering upfront capital barriers for retail and workplace charging deployments across metropolitan corridors.
Market Restraints
- Power semiconductor supply concentration:Silicon carbide MOSFET fabrication capacity remains concentrated in East Asian foundries, creating 26-32 week lead times for 350 kW dispenser production.
- Buy America compliance friction:The Federal Highway Administration's NEVI program requirements for 55% domestic content are disqualifying established European and Asian equipment suppliers from federally subsidized projects.
- Grid interconnection queues:Utility upgrade timelines for high-capacity DC fast charging sites in California and Texas now extend 18-24 months, delaying revenue activation for host properties.
Strategic Opportunities
- Multi-unit dwelling penetration:Florida's condominium and apartment stock represents an underwired addressable base where managed charging software can unlock resident billing and load management services.
- ISO 15118-20 Plug and Charge:The updated communication protocol standard enables automated authentication and payment, reducing friction for highway corridor deployments and eliminating app-based enrollment barriers.
- Renewable energy pairing:On-site solar-plus-storage integration at commercial charging depots is qualifying projects for Investment Tax Credit stacking under modified IRA provisions.
Industry Challenges
- Certified electrical contractor scarcity:The specialized workforce for 480V commercial installations with utility coordination experience cannot scale to match deployment targets in California, Texas, and Florida.
- Interoperability testing complexity:Multi-network roaming agreements require extensive hardware-software validation across CCS1, NACS, and legacy CHAdeMO connector variants, extending commissioning timelines.
- Depot charging integration:Fleet management software must reconcile telematics data, energy management systems, and utility demand response signals, creating IT architecture complexity for logistics operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Charging Infrastructure Market |
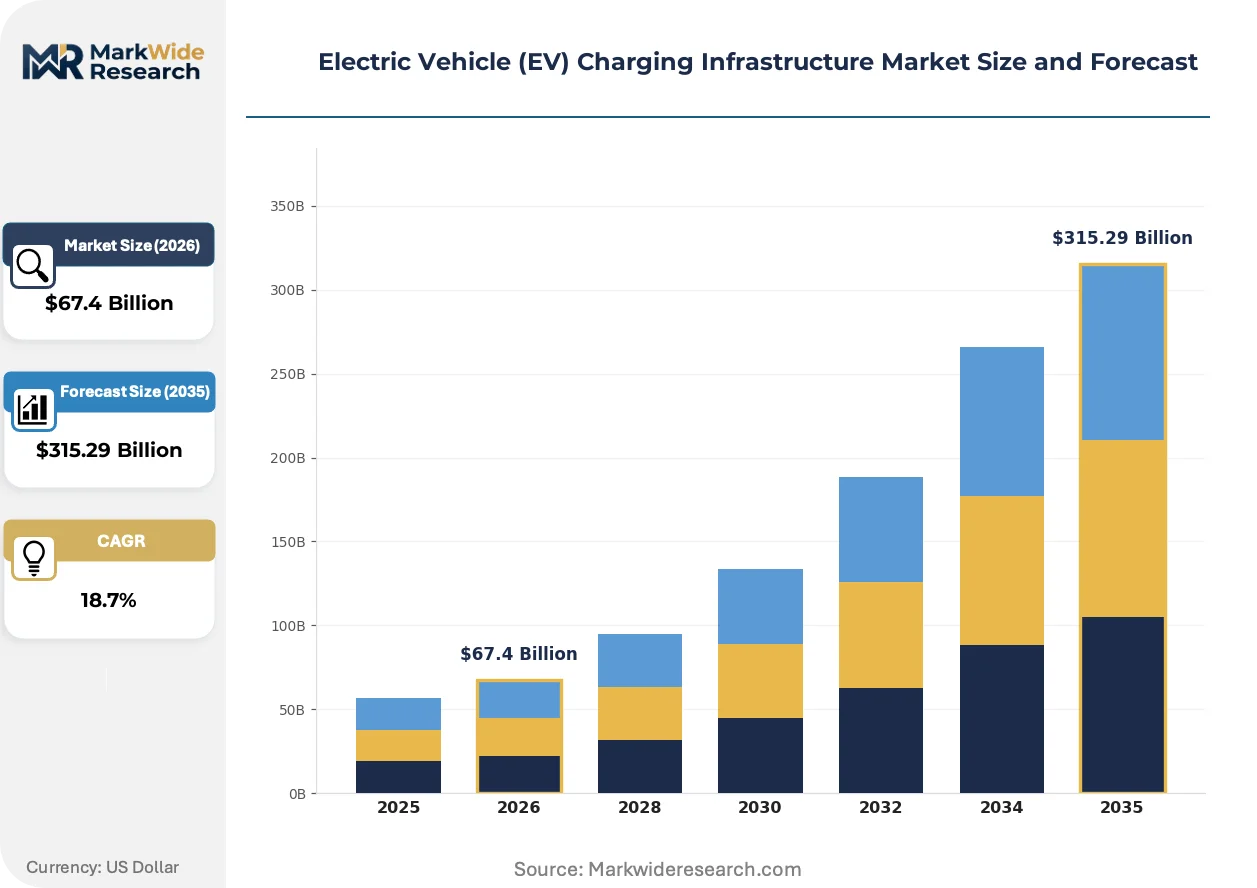
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $315.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Chargers End User: Residential Users, Commercial Fleet Operators, EV Manufacturers, Public Charging Stations Installation Type: On-Street Charging, Off-Street Charging, Home Charging, Worksite Charging Power Rating: 7 kW, 22 kW, 50 kW, 150 kW |
| Companies Covered | ChargePoint, Inc., Tesla Inc., ABB Ltd., Blink Charging Co., EVBox, EVgo, bp pulse, Schneider Electric, Webasto Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Charging Infrastructure Market Evolving Landscape
Charger hardware is converging with energy management software and grid-interactive controls, transforming standalone dispensers into distributed energy assets that participate in wholesale electricity markets.
Dynamic load balancing algorithms are digitizing site-level power distribution across multiple charging ports. Commercial fleet operators in California and Texas are deploying these systems to avoid demand charge penalties while maximizing vehicle throughput. The technology is digitizing how charging assets communicate with building energy management systems and utility SCADA networks, compressing the operational boundary between transportation and grid infrastructure.
The EU's Alternative Fuels Infrastructure Regulation is mandating 150 kW coverage every 60 kilometers along trans-European transport corridors by 2025. Equipment suppliers must certify to EN 50620 and IEC 61851-23 standards, accelerating consolidation around CCS2 connector architectures. Highway corridor operators in Germany, France, and the Netherlands are responding with 350 kW hub deployments that prioritize commercial freight electrification over passenger vehicle convenience.
Fleet procurement departments are unbundling charging hardware from network management software, creating separate vendor evaluation tracks for capital equipment and ongoing SaaS subscriptions. Logistics operators with 500+ vehicle electrification commitments in North America now require open-API integration with existing dispatch and telematics platforms. This pattern is most visible among parcel delivery and grocery distribution fleets in California's Central Valley and Texas's Dallas-Fort Worth metroplex, where charging infrastructure decisions have migrated from facilities management to chief sustainability officer oversight.
Electric Vehicle (EV) Charging Infrastructure Market Segmentation
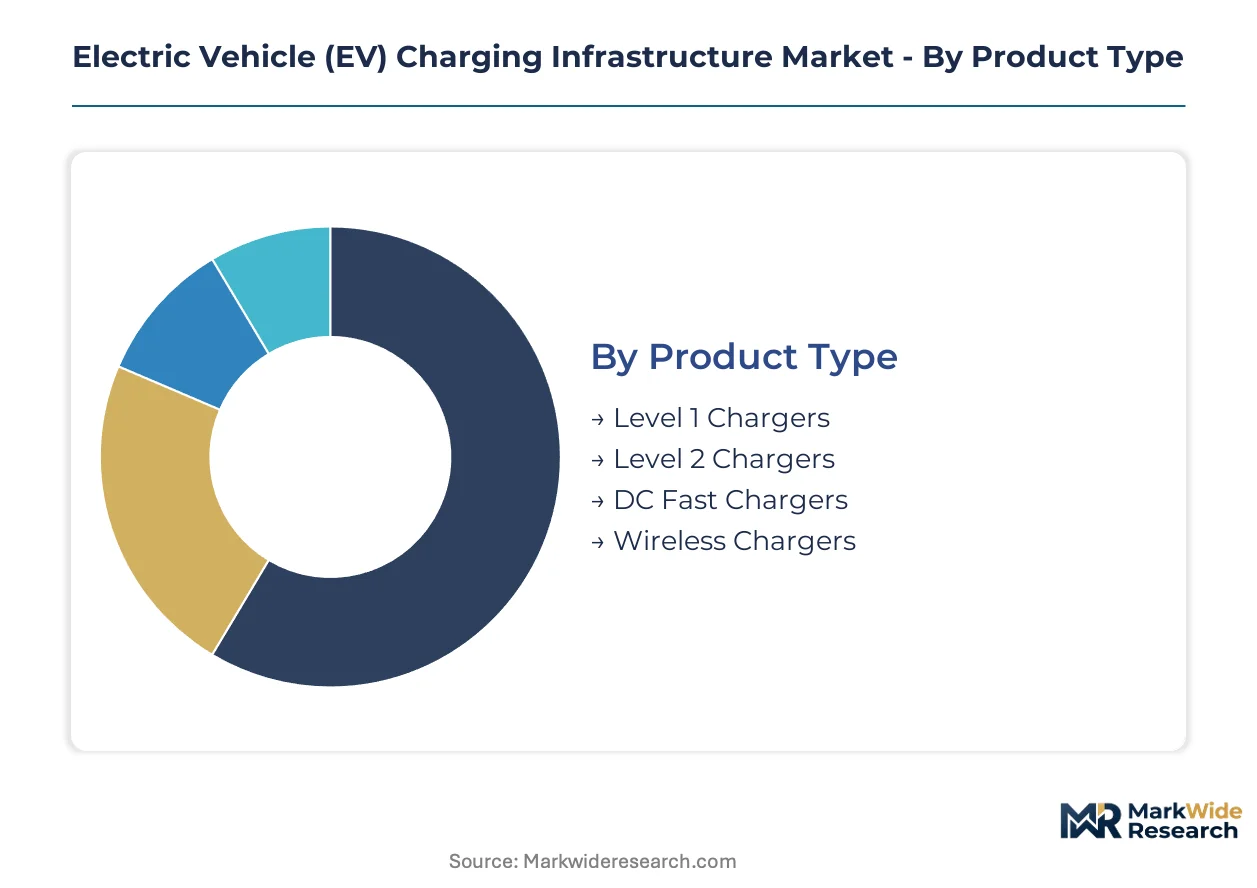
Segmentation reveals how capital allocation and deployment velocity diverge across charger hardware categories, end-use applications, and power specifications. Understanding these fault lines helps suppliers calibrate product roadmaps against actual procurement patterns rather than aggregate demand signals.
Product Type:
Maturity varies sharply across this spectrum, with legacy AC technologies yielding ground to high-power DC architectures in commercial deployments.
- Level 1 Chargers:These 120V residential units deliver 1.4 kW through standard household outlets, requiring no electrical upgrades. Demand persists among urban apartment dwellers in California and Florida where overnight parking access is unreliable and Level 2 installation costs are prohibitive.
- DC Fast Chargers:High-voltage direct current dispensers convert grid power externally, bypassing onboard vehicle rectifiers to deliver 150 kW or 350 kW. Highway corridor operators in Texas and fleet depots across California's Central Valley are prioritizing these units to minimize vehicle dwell time and maximize throughput per port.
- Level 2 Chargers:240V AC units providing 7-19 kW dominate home garage retrofits and workplace installations where vehicles park 6-8 hours.
- Wireless Chargers:Inductive pad systems transfer power across air gaps, currently deployed in limited autonomous vehicle trials and premium residential settings.
Level 2 Chargers retain volume leadership; DC Fast Chargers hold the steepest expansion curve.
End User:
Customer archetypes split between price-sensitive individual owners and total-cost-of-optimizing fleet procurement departments with divergent technical requirements.
- Commercial Fleet Operators:Logistics companies, delivery services, and municipal utilities electrifying 100-plus vehicle deployments. These buyers prioritize depot charging with telematics integration and demand charge management, driving procurement in Texas's Dallas-Fort Worth metroplex and California's San Joaquin Valley.
- Public Charging Stations:Retail hosts, highway service plazas, and municipal parking operators monetizing dwell time through per-kWh or per-session pricing. Florida's utility-backed make-ready programs and California's SB 100 compliance pressure are accelerating site host partnerships with network providers.
- Residential Users:Single-family homeowners installing Level 2 units in garages, representing a mature replacement market rather than net new growth.
- EV Manufacturers:Automakers bundling home charging hardware with vehicle sales or building proprietary fast-charging networks to anchor brand ecosystems.
Commercial Fleet Operators command the highest per-site revenue; Public Charging Stations are expanding most quickly.
Installation Type:
Physical siting determines grid interconnection complexity, permitting timelines, and the viability of renewable energy pairing.
- Home Charging:Residential garage and driveway installations where Level 2 units connect to existing electrical panels. California's Title 24 building codes now mandate EV-ready conduit in new construction, embedding futureproofing without immediate hardware deployment.
- Worksite Charging:Employer-sponsored installations serving employee vehicles during business hours, concentrated in Texas's Austin-San Antonio tech corridor and California's Bay Area where parking ratios support dedicated EV stalls.
- Off-Street Charging:Parking garage and surface lot deployments in retail, hospitality, and multi-unit dwelling settings.
- On-Street Charging:Curb-side dispensers integrated into street furniture, requiring coordination with municipal transportation departments and underground utility mapping.
Home Charging retains volume leadership; Worksite Charging holds the steepest expansion curve.
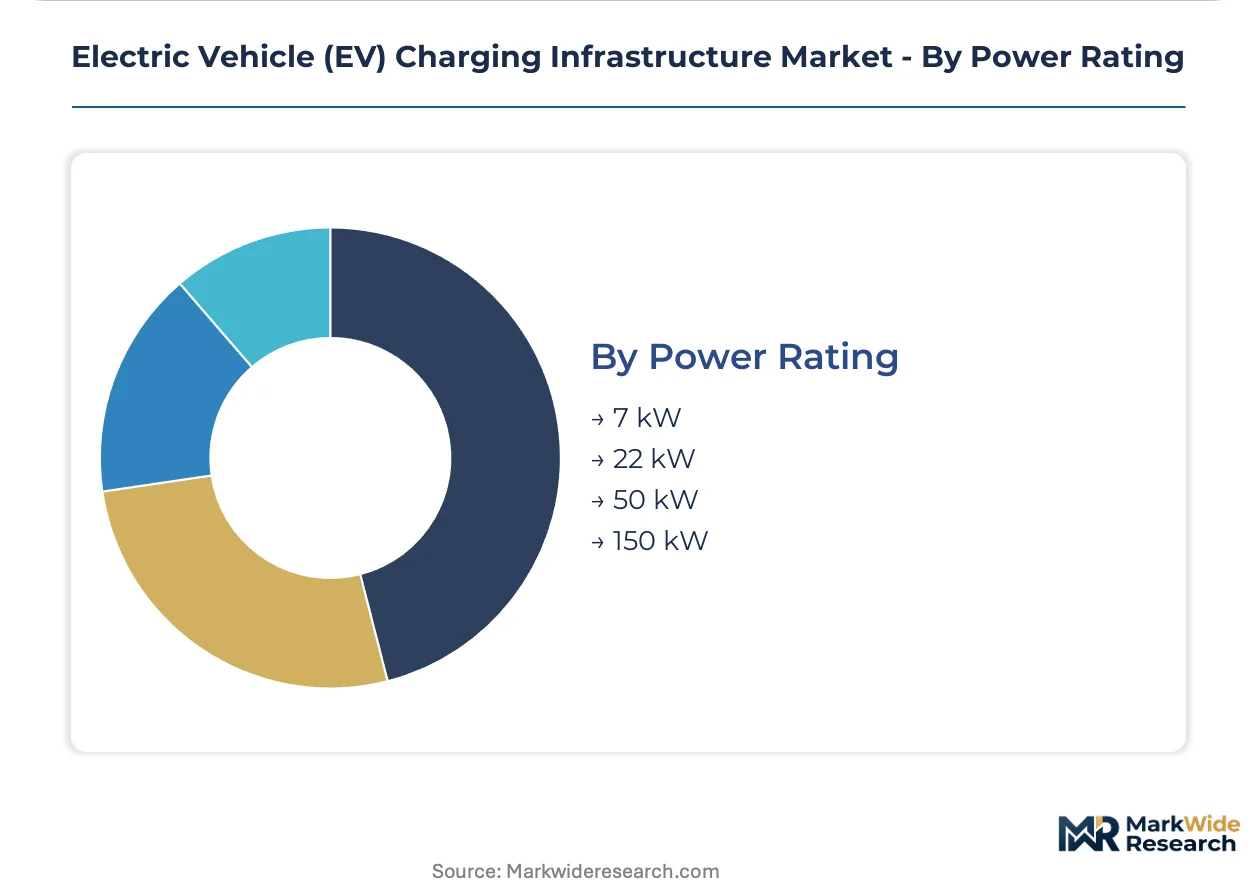
Power Rating:
Output specification directly correlates with hardware cost, grid upgrade requirements, and target vehicle segment compatibility.
- 150 kW:High-output dispensers serving commercial freight and passenger highway travel, requiring 480V three-phase service and liquid-cooled cable assemblies. The Federal Highway Administration's NEVI program mandates this minimum for federally funded corridor projects, reshaping supplier qualification.
- 7 kW:Standard Level 2 output for overnight residential charging, matching the acceptance rate of most passenger EVs and minimizing home electrical panel stress.
- 22 kW:Three-phase Level 2 standard common in European deployments, gaining limited traction in US commercial settings with compatible vehicle fleets.
- 50 kW:Entry-level DC fast charging now considered legacy output, being bypassed by fleet operators and highway operators in favor of 150 kW minimums.
7 kW retains volume leadership; 150 kW holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in fleet-heavy markets absorb premium hardware costs readily, while residential adopters in price-sensitive regions delay upgrades until utility incentives compress payback periods. This elasticity gap is widening deployment velocity between commercial corridor projects and home garage retrofits.
United States
Fleet electrification mandates in California and Texas are accelerating depot charging procurement ahead of vehicle delivery schedules. The Federal Highway Administration's NEVI program enforces 55% domestic content requirements for federally funded highway corridor installations. Dallas-Fort Worth metroplex logistics operators are deploying 350 kW hub architectures to minimize commercial vehicle dwell time.
China
Dual carbon goals and GB/T charging standards are filtering market access for foreign equipment providers while accelerating domestic manufacturing scale. MIIT enforcement of technical specifications prioritizes state-owned grid operators for corridor deployment contracts. Yangtze River Delta metropolitan clusters are integrating charging infrastructure with smart city grid management platforms.
Germany
Commercial freight electrification along trans-European transport corridors is prioritizing 350 kW highway hub deployments over passenger convenience infrastructure. The EU's Alternative Fuels Infrastructure Regulation mandates 150 kW coverage every 60 kilometers by 2025, compressing equipment certification timelines. Bavaria's automotive supplier belt is co-locating charging assets with manufacturing facilities to anchor captive fleet demand.
India
FAME-II subsidy extensions and state-level electric vehicle policies are concentrating procurement in Maharashtra and Gujarat manufacturing corridors. BIS certification requirements for charging equipment are creating compliance lead times that favor established domestic electrical equipment suppliers. Delhi-NCR urban agglomerations are deploying depot charging for municipal bus electrification ahead of intercity highway coverage.
United Kingdom
Workplace charging schemes and fleet decarbonization commitments are driving commercial site host partnerships across London and Southeast England. OZEV grant structures favor open-network hardware over proprietary ecosystems, reshaping supplier qualification criteria. Midlands logistics corridors are prioritizing 150 kW installations for regional distribution fleet electrification.
Electric Vehicle (EV) Charging Infrastructure Market Competitive Landscape
Capability concentration sits with integrated hardware-software providers; scale advantage sits with industrial electrical equipment conglomerates with captive manufacturing footprints. The market structures around three tiers: vertically integrated network operators controlling proprietary ecosystems, industrial-scale fabricators supplying highway corridor dispensers, and software-centric platform vendors unbundling network management from capital equipment. Consolidation pressure is intensifying through strategic partnerships between automotive OEMs and charging network providers, alongside capacity expansion announcements for North American power electronics assembly.
Within the integrated network operator tier, Tesla Inc. exemplifies ecosystem control through proprietary connector standards and captive demand from vehicle sales. ABB Ltd. and Schneider Electric occupy positions as industrial-scale suppliers with manufacturing depth for high-output dispensers. ChargePoint, Inc. represents the software-centric archetype, anchoring open-network positioning for commercial site hosts seeking vendor flexibility.
| Leading Market Players |
|---|
| ChargePoint, Inc. |
| Tesla Inc. |
| ABB Ltd. |
| Blink Charging Co. |
| EVBox |
| EVgo |
| bp pulse |
| Schneider Electric |
| Webasto Group |
| Others |
Value Network & Pricing Analysis
Undercapacity in silicon carbide MOSFET fabrication across East Asian foundries is compressing supplier pricing power for 350 kW DC fast charger dispensers while inflating procurement costs for North American equipment providers seeking Buy America compliance.
Pricing Analysis
Aftermarket service revenue from network management SaaS and preventive maintenance contracts now drives lifetime value capture, with three-tier pricing structure across premium, standard, and economy levels separating integrated hardware-software bundles from standalone dispenser sales. Price differentiation rests on UL certification tier and volume procurement scale, with fleet operators commanding 15-20 point discounts against retail site hosts. Cost compression in entry-level Level 2 hardware is intensifying because of commoditized power electronics assembly, while commercial DC fast charging maintains pricing resilience. Residential users exhibit highest price sensitivity, deferring upgrades until utility incentives compress payback periods; commercial fleet operators absorb premium hardware costs readily.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Jabil, and Flex holding power electronics assembly capacity for North American charger OEMs. Geographic supply concentration centers on China for power semiconductors, Taiwan for advanced MOSFET foundry services, and Mexico for final assembly serving US NEVI compliance. Raw material dependencies draw from copper busbar stock, liquid-cooled cable assemblies, and high-grade electrical steel for transformer cores. Single-source vulnerability in silicon carbide substrate supply creates 26-32 week lead time exposure for high-output dispensers. Distribution runs through direct OEM sales to fleet operators, electrical contractor channels for commercial installations, and retail partnerships for residential Level 2 units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from hydrogen fuel cell corridor infrastructure and battery swapping networks for commercial freight, requiring defensive repositioning around integrated energy management capabilities.
For Market Incumbents: Insulate proprietary network density through backward integration into power electronics assembly and captive certification investment for NEVI compliance. Automakers building captive charging ecosystems represent the primary substitution threat; vertical control over site-level energy software anchors switching costs for commercial hosts. Prioritize 350 kW hub deployments along Texas and California logistics corridors to preempt hydrogen corridor development.
For New Entrants and Emerging Players: Florida's multi-unit dwelling stock offers the most penetrable white-space target, where managed charging software for condominium associations remains underserved. ISO 15118-20 Plug and Charge protocol adoption creates entry pathway through automated authentication elimination of app-based enrollment friction. Target site host partnerships with retail parking operators in Miami-Dade and Tampa metropolitan areas, offering revenue-sharing models that transfer capital risk from property owners.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-centric platform vendors unbundling network management from capital equipment, with SaaS gross margins exceeding hardware fabrication by 20-30 points. Long-term viability across the analysis window favors acquisition targets with open-API architectures enabling fleet telematics integration and utility demand response program participation. Monitor utility make-ready program expansion velocity across Texas and Florida as inflection indicator for commercial deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | IRA manufacturing credits redirect capital toward North American power electronics assembly for NEVI compliance. |
| Bi-directional Charging Certification | Vehicle-to-grid integration unlocks frequency regulation revenue streams for commercial depot operators. |
| Fleet Software Platform Integration | Open-API architectures with telematics providers anchor switching costs for logistics electrification commitments. |
| Utility Partnership Expansion | Make-ready program enrollment in Texas and Florida compresses upfront capital barriers for site hosts. |
| Renewable Energy Pairing | Solar-plus-storage co-location qualifies commercial depots for Investment Tax Credit stacking under modified IRA provisions. |
Research Methodology
A standing panel of fleet electrification directors, utility demand response program managers, electrical contractor operations leads, and site host property managers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FHWA NEVI program filings, EIA electricity demand data, state utility commission dockets, and equipment supplier SEC disclosures. Bottom-up deployment tracking across California, Texas, and Florida metros triangulated against top-down market sizing from vehicle registration projections and charging port density models.
Scenario-bracketing framed optimistic and conservative deployment paths based on utility interconnection queue clearance rates and Buy America compliance timeline variance. Segmentation dimensions modeled include charger power rating tier, end-user archetype, installation siting category, and regional regulatory cluster across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical EV adoption patterns and infrastructure buildout elasticity estimates. Key forecast inputs incorporated fleet procurement cycle timing and IRA incentive phase-out assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by automotive OEMs building captive charging networks or hydrogen corridor developers would shift outcomes beyond modeled ranges. Supply chain disruption from semiconductor fabrication capacity constraints or tariff regime changes represent primary revision triggers. Quarterly review of utility interconnection queue lengths and NEVI funding obligation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
Electric Vehicle Charging System Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Products Market
Electric Vehicle Charging
Electric Vehicle Home Charger Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Battery Swapping Charging Infrastructure Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market