
 Electric Vehicle Charging Systems Testing Market | 2026-2036
Electric Vehicle Charging Systems Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charging Systems Testing Market Analysis
Modular test-platform bundling is consolidating buyer preferences around integrated hardware-software validation suites rather than discrete instrument purchases. Keysight Technologies leverages its RF and power-electronics instrumentation heritage to anchor premium positioning in high-voltage DC fast-charger validation. Fluke Corporation sustains channel density across field-service technician segments with handheld diagnostic tools for operational charging infrastructure. GMC Instruments competes on specialized European grid-code conformance modules that address regional frequency-response and harmonic-distortion requirements.
Electric vehicle charging systems testing encompasses electrical safety verification, communication-protocol validation, and grid-interoperability assessment for conductive and wireless power-transfer equipment, typically spanning voltage classes from 120V AC residential levels through 1000V DC fast-charging rails. Its primary commercial purpose is certifying that charging hardware meets electromagnetic-compatibility, efficiency, and safety thresholds before deployment in public or fleet environments. DC fast chargers represent the fastest-growing product category as 350kW and megawatt-class systems strain legacy test architectures. CCS and ISO 15118 technology segments command concentrated R&D investment because bidirectional power-flow and plug-and-charge authentication requirements multiply test-case complexity. Charging network operators emerge as the most demanding end-user segment due to their need for continuous uptime assurance across geographically dispersed asset bases.
FCC Part 15 emissions rules and NHTSA electrical-safety guidelines shape US market access requirements for charging-system imports, while the EU AI Act and CE marking under the MDR framework extend conformity obligations to software-defined charging management. China's GB standards and MIIT certification protocols create a parallel compliance track for equipment serving the world's largest EV fleet. Stakeholders must monitor divergence between regional cybersecurity mandates for vehicle-to-grid communication as protocol fragmentation threatens to multiply certification costs for multi-market product families.
Market Dynamics
Bidirectional charging architectures and vehicle-to-grid communication protocols are forcing test-equipment manufacturers to rebuild validation frameworks around dynamic power-flow scenarios rather than static unidirectional load profiles.
Growth Catalysts
- EU Green Deal mandates:Germany, France, and the Netherlands impose tightening conformance requirements for grid-integrated charging hardware, expanding mandatory pre-deployment testing cycles for all public-facing infrastructure.
- Fleet electrification:Commercial vehicle operators building high-utilization charging depots demand continuous uptime validation protocols that exceed residential-grade certification thresholds.
- 350kW DC fast-charger proliferation:Megawatt-class systems strain legacy test architectures and compel replacement of aging validation equipment across certification laboratories.
Market Restraints
- Semiconductor component volatility:Power-electronics instrumentation relies on specialized wide-bandgap device availability subject to foundry allocation constraints.
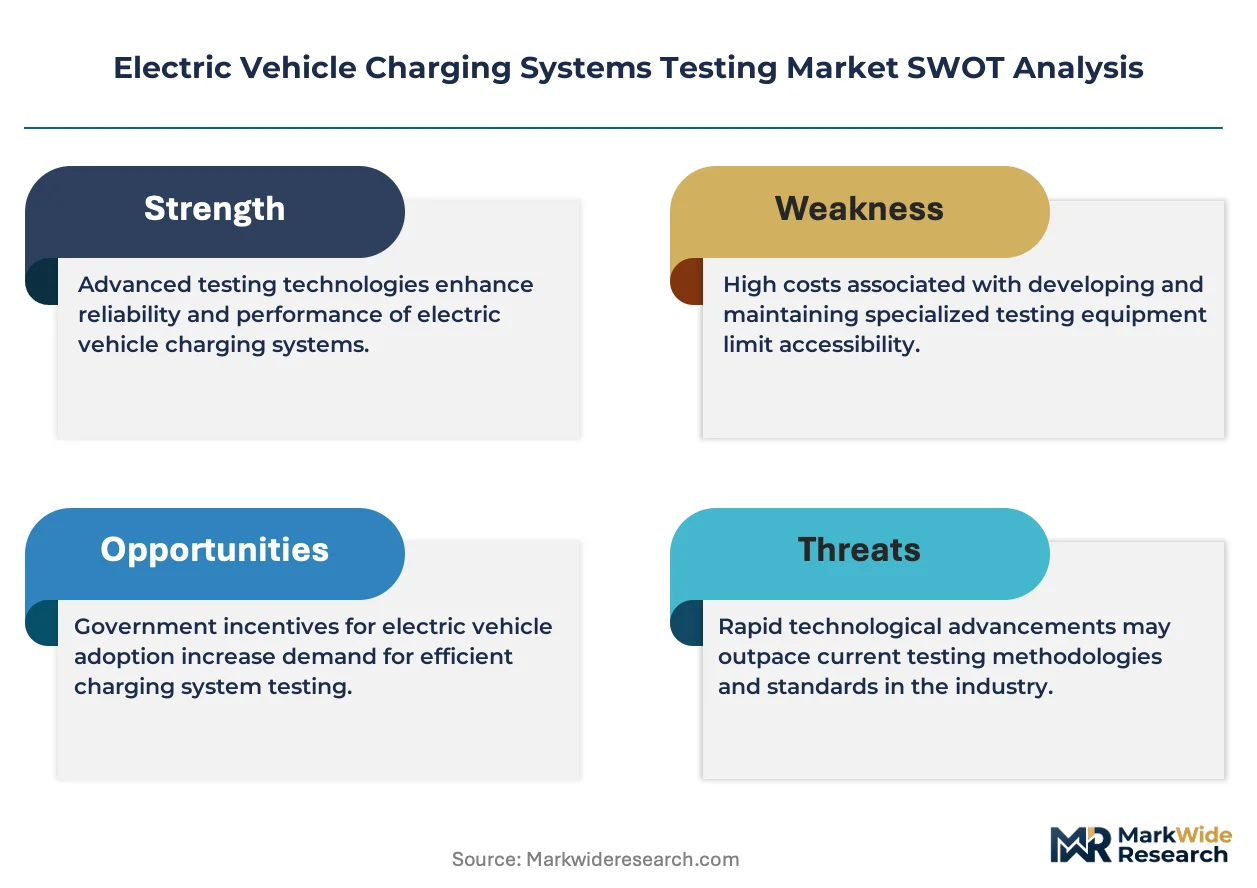
- Regulatory fragmentation:Divergence between FCC Part 15 emissions rules, EU CE marking under MDR framework, and China's GB standards multiplies certification costs for multi-market product families.
- Capital intensity of high-voltage test cells:DC fast-charger validation requires specialized 1000V-capable safety enclosures and isolation transformers that constrain laboratory expansion.
Strategic Opportunities
- Wireless power-transfer testing:Inductive charging systems for autonomous mobility applications remain underpenetrated by established validation protocols, creating first-mover positioning for specialized electromagnetic-compatibility suites.
- Software-defined charging management:EU AI Act conformity obligations extend to machine-learning-based charge optimization algorithms, opening advisory services for algorithmic transparency documentation.
- Aftermarket diagnostic services:Charging network operators seek unbundled field-service technician tools separate from integrated hardware-software validation suites, fragmenting procurement patterns.
Industry Challenges
- ISO 15118 protocol engineering talent:Bidirectional power-flow and plug-and-charge authentication requirements multiply test-case complexity beyond current workforce capabilities in power-electronics software integration.
- Certification timeline compression:Pre-certification testing cycles in China's eastern manufacturing corridor accelerate as domestic EV production volumes strain laboratory capacity.
- Legacy grid-code module integration:European frequency-response and harmonic-distortion conformance modules must interface with next-generation high-voltage DC architectures without full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charging Systems Testing Market |
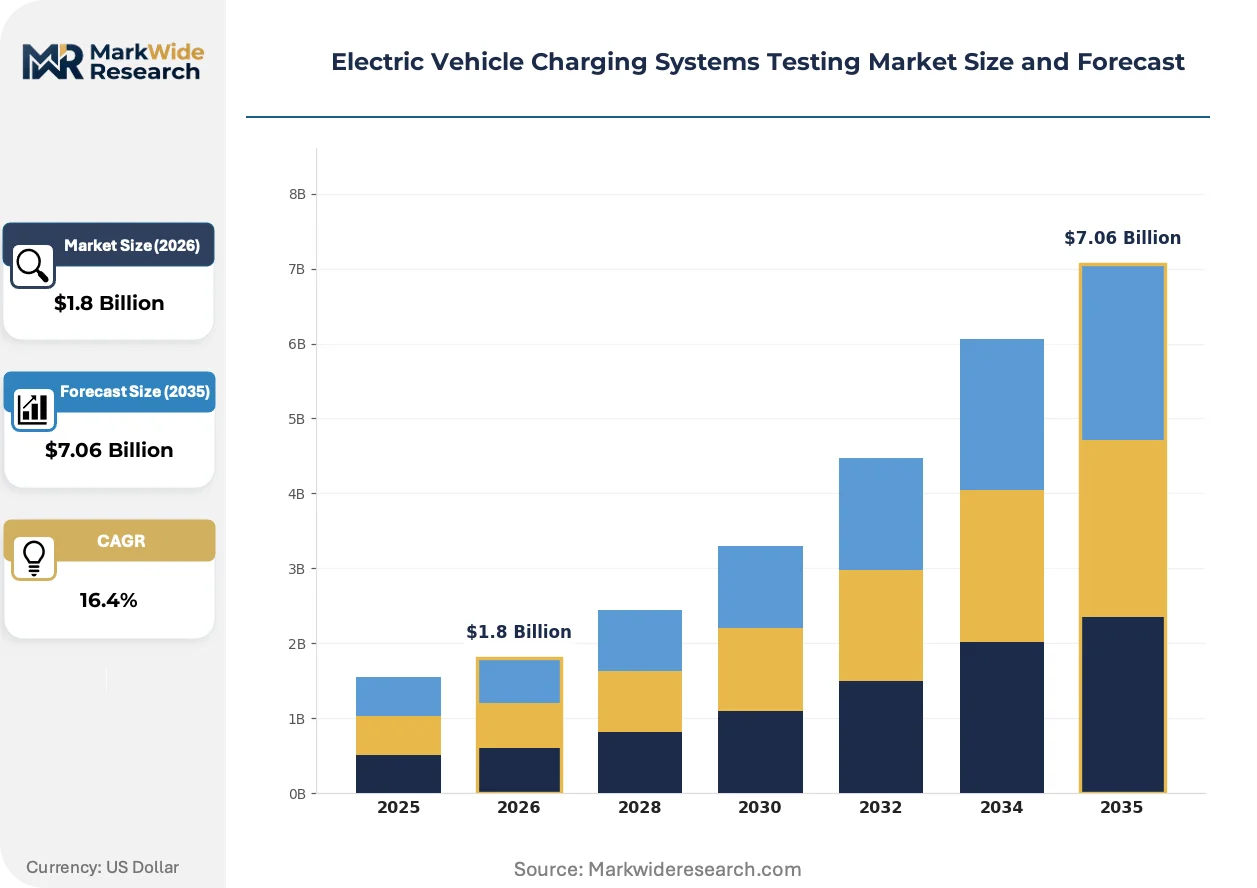
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers Technology: CHAdeMO, CCS, Tesla Supercharger, ISO 15118 End User: Automotive Manufacturers, Charging Network Operators, Fleet Operators, Commercial Establishments Installation: Residential, Public Charging Stations, Commercial Locations, On-Street |
| Companies Covered | Comemso, ITECH, GMC Instruments, Fluke Corporation, Keysight Technologies, HT Instruments, Triplett Test Equipment, ZERA GmbH, Megger Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charging Systems Testing Market Emerging Trajectories
Test-platform architectures are fragmenting as buyer preferences consolidate around integrated validation suites while hardware-software convergence accelerates protocol complexity beyond discrete instrument capabilities.
Modular power-electronics test beds are decentralizing laboratory infrastructure by enabling distributed validation nodes at manufacturing sites rather than centralized certification facilities. Tier-1 suppliers in China's eastern manufacturing corridor adopt these configurations to compress pre-certification cycles. This decentralization is collapsing the traditional boundary between production-line quality assurance and formal third-party certification.
The EU AI Act extends conformity obligations to software-defined charging management systems, compelling test houses to build algorithmic transparency documentation capabilities alongside hardware validation. Industrial consequence includes expanded scope clauses in laboratory accreditation contracts. Megawatt-class charging infrastructure serving commercial vehicle depots faces the most acute compliance burden as dynamic load-balancing algorithms trigger AI system classification thresholds.
Charging network operators now unbundle field-service diagnostics from integrated validation suite procurement, fragmenting historical bundled purchasing patterns. Handheld diagnostic tools for operational infrastructure displace periodic laboratory recertification in geographically dispersed asset bases. This unbundling is most visible across Germany's autobahn fast-charging corridor where uptime assurance contracts prioritize rapid fault isolation over comprehensive system revalidation.
Electric Vehicle Charging Systems Testing Market Segmentation
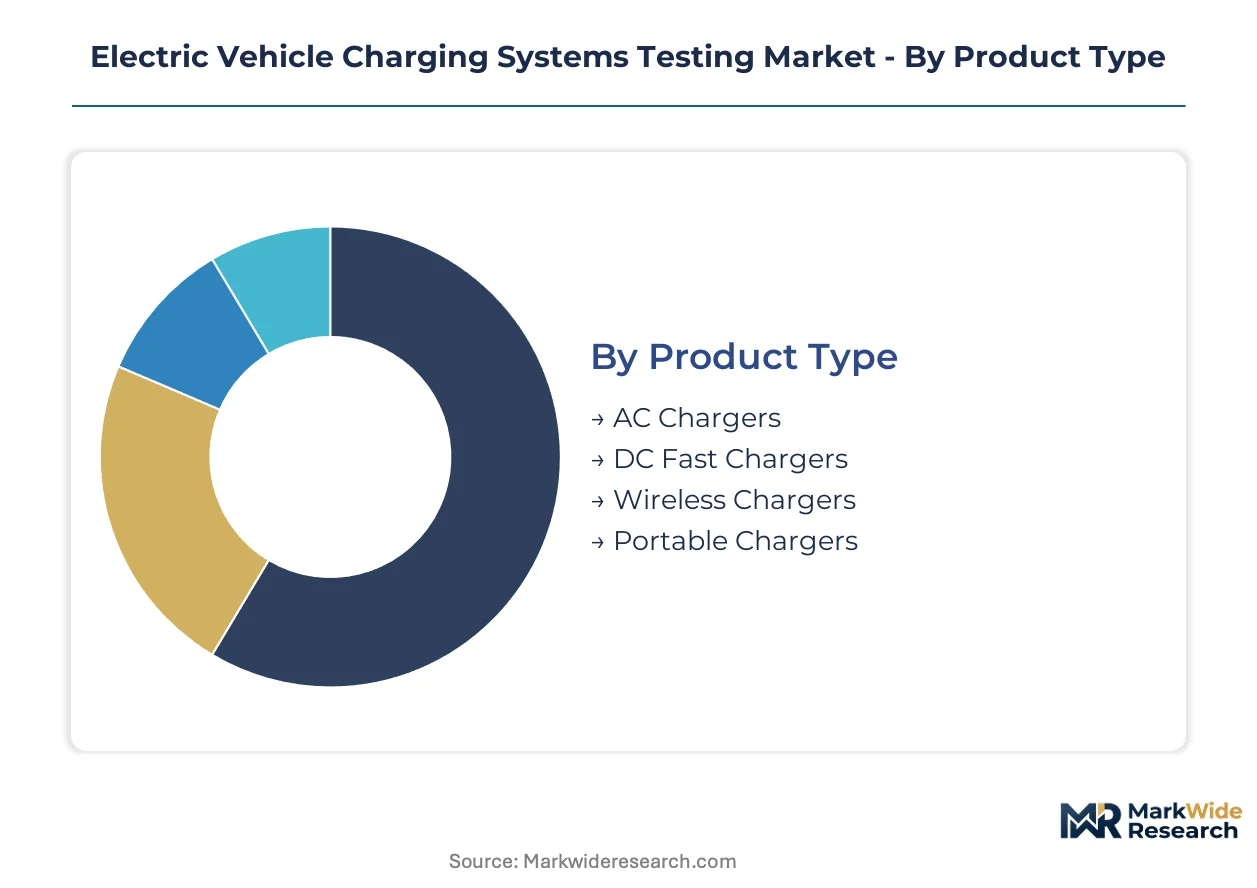
Segmentation in electric vehicle charging systems testing reflects divergent technical requirements across voltage classes and communication protocols. Equipment replacement cycles and certification complexity vary substantially between residential AC validation and megawatt-class DC infrastructure.
Product Type:
Upgrade cycles for test equipment accelerate as higher voltage ratings displace legacy validation architectures.
- AC Chargers:Residential and workplace charging hardware operating at 120V to 240V single-phase or three-phase configurations. Validation concentrates in China's eastern manufacturing corridor where domestic EV production volumes strain pre-certification laboratory capacity.
- DC Fast Chargers:High-voltage conductive systems spanning 50kW to 350kW and emerging megawatt-class commercial vehicle applications. Fleet operators building high-utilization depots demand continuous uptime protocols that exceed residential-grade certification thresholds.
- Wireless Chargers:Inductive power-transfer systems for autonomous mobility and premium passenger segments.
- Portable Chargers:Mobile emergency and supplemental charging units with lower power ratings.
DC Fast Chargers sits at the top of the volume ranking, with Wireless Chargers climbing the fastest.
Technology:
Protocol complexity determines test-case multiplication and laboratory accreditation scope.
- CCS:Combined Charging System integrating AC and DC power delivery with ISO 15118 communication backbone. Germany's autobahn fast-charging corridor and Netherlands public infrastructure mandates drive concentrated conformance investment.
- ISO 15118:Vehicle-to-grid communication standard enabling plug-and-charge authentication and bidirectional power flow. EU AI Act conformity obligations extend to machine-learning-based charge optimization algorithms embedded in this protocol stack.
- CHAdeMO:Japanese-origin DC fast-charging specification with established bidirectional capability.
- Tesla Supercharger:Proprietary connector and communication architecture with expanding network access.
CCS commands the largest installed base for new validation equipment, while ISO 15118 expands most quickly as V2G requirements tighten.
End User:
Procurement scale and technical sophistication fragment across buyer categories with distinct uptime requirements.
- Charging Network Operators:Public and semi-public infrastructure managers with geographically dispersed asset bases. Germany's autobahn corridor operators unbundle field-service diagnostics from integrated validation suites, fragmenting historical bundled purchasing.
- Fleet Operators:Commercial vehicle and logistics companies building high-utilization charging depots. Continuous uptime validation protocols exceed residential-grade certification thresholds as electrification accelerates.
- Automotive Manufacturers:OEM validation laboratories for pre-deployment hardware certification.
- Commercial Establishments:Workplace and retail destination charging with moderate utilization profiles.
Charging Network Operators generate the highest equipment revenue per account, with Fleet Operators gaining share fastest as depot electrification scales.
Installation:
Site constraints and grid-integration depth differentiate testing requirements across deployment environments.
- Public Charging Stations:High-visibility infrastructure subject to strict electromagnetic-compatibility and safety mandates under EU Green Deal conformance frameworks. France and Netherlands impose tightening grid-integration requirements for all public-facing hardware.
- Commercial Locations:Workplace and retail installations with intermediate utilization and reliability expectations.
- Residential:Single-family and multi-unit dwelling installations at lower voltage and power ratings.
- On-Street:Curb-side urban deployments with space constraints and vandalism exposure.
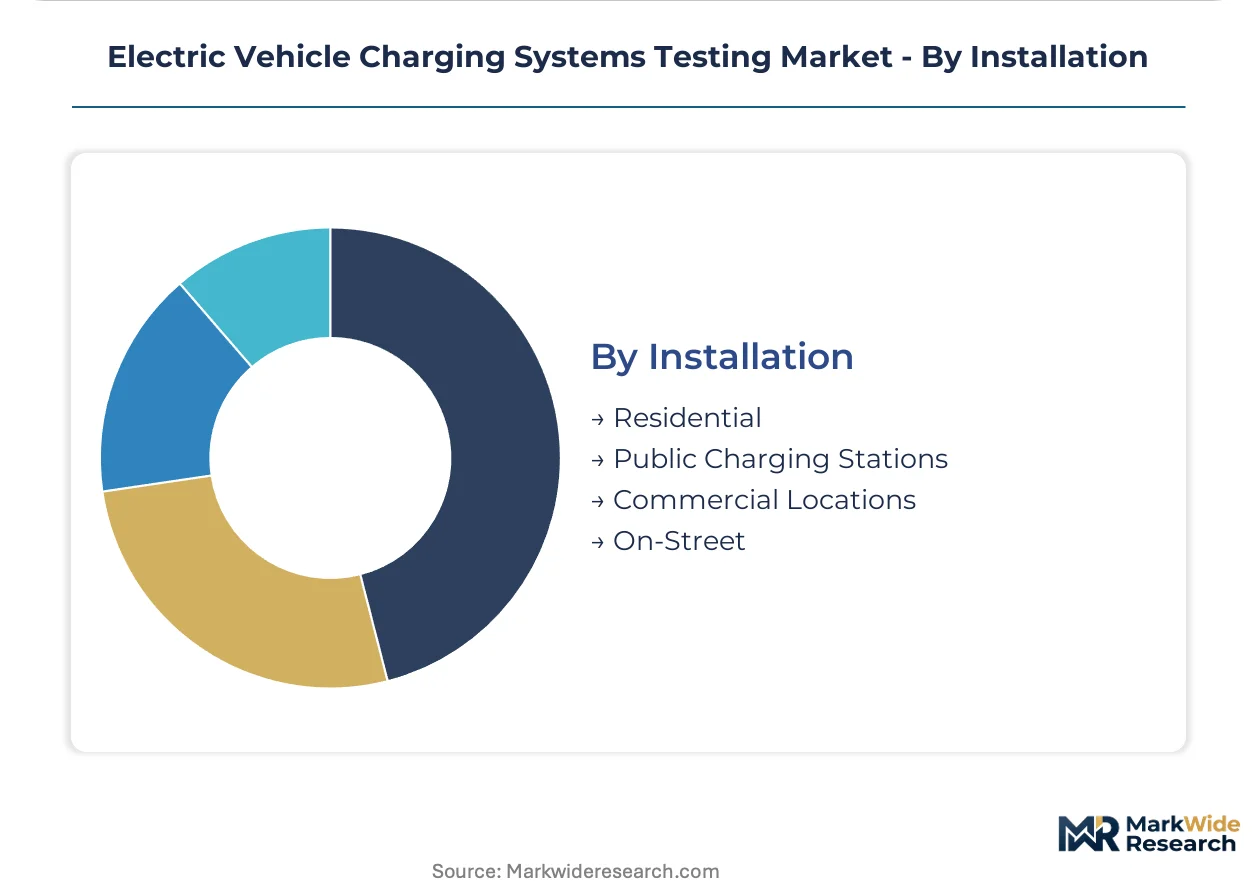
Public Charging Stations anchors equipment demand by installation type, with Commercial Locations showing steepest expansion trajectory as workplace charging mandates spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test-equipment manufacturing originated in Germany's precision-engineering tradition and the United States' electronics instrumentation sector, with both regions establishing the foundational standards that now govern high-voltage DC validation protocols worldwide.
China
Pre-certification testing cycles concentrate in the Yangtze River Delta manufacturing corridor, where domestic EV production volumes strain laboratory capacity. MIIT certification protocols under GB standards create a parallel compliance track distinct from Western frameworks. Shenzhen and Shanghai host decentralized validation nodes that collapse the boundary between production-line quality assurance and formal third-party certification.
Germany
The autobahn fast-charging corridor drives concentrated CCS conformance investment as fleet operators unbundle field-service diagnostics from integrated validation suites. KBA enforces tightening grid-integration requirements under EU Green Deal mandates for all public-facing infrastructure. Bavaria and Baden-Württemberg anchor premium-tier test-equipment development leveraging regional power-electronics heritage.
United States
FCC Part 15 emissions rules and NHTSA electrical-safety guidelines shape market access requirements for charging-system imports and domestic deployment. The IRA's clean vehicle tax credits accelerate fleet electrification, expanding demand for high-utilization depot validation protocols. Michigan and California host automotive OEM validation laboratories with specialized 1000V-capable test cells.
France
ANSM and national regulators impose stringent electromagnetic-compatibility mandates for public charging infrastructure under converging EU frameworks. The Paris-Saclay cluster and Lyon region concentrate grid-code conformance module development addressing frequency-response requirements. Île-de-France charging network operators prioritize rapid fault isolation over comprehensive system revalidation in uptime assurance contracts.
Netherlands
Zero-emission vehicle mandates drive intensive pre-deployment testing cycles for public-facing charging hardware across densely populated urban corridors. Rotterdam and Eindhoven serve as testbeds for bidirectional charging architectures with vehicle-to-grid communication protocols. National regulators enforce CE marking conformity that extends to software-defined charging management systems under evolving EU AI Act obligations.
Electric Vehicle Charging Systems Testing Market Vendor Landscape
Premium-margin players sit above commodity-margin players across instrumentation sophistication and protocol coverage depth. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with RF and power-electronics heritage, specialized European grid-code conformance houses, and channel-dense field-service diagnostic suppliers. Consolidation pressure intensifies as modular test-platform bundling favors integrated hardware-software validation suites over discrete instrument purchases. Dominant competitive moves include strategic partnerships for bidirectional charging protocol development and geographic expansion into China's eastern manufacturing corridor.
Among diversified instrumentation conglomerates, Keysight Technologies and Fluke Corporation occupy positions spanning laboratory-grade validation through field-service deployment. Keysight anchors premium-tier positioning in high-voltage DC fast-charger validation, while Fluke sustains channel density across operational infrastructure diagnostic segments. GMC Instruments exemplifies the specialized European archetype with focused grid-code conformance capabilities. These three represent distinct margin tiers rather than direct substitutes, with procurement patterns increasingly fragmenting between integrated validation suites and unbundled aftermarket tools.
| Leading Market Players |
|---|
| Comemso |
| ITECH |
| GMC Instruments |
| Fluke Corporation |
| Keysight Technologies |
| HT Instruments |
| Triplett Test Equipment |
| ZERA GmbH |
| Megger Group |
| Others |
Supply Flow & Price Mechanics
Power-electronics software engineers concentrated in Bavaria and Baden-Württemberg command wage premiums that compress margins at the premium tier while widening spreads between integrated validation suites and unbundled field-service tools. Labor-cost differentials between German engineering clusters and China's Yangtze River Delta manufacturing corridor directly shape three-tier pricing stratification across certification-grade equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates laboratory-grade integrated suites from modular field diagnostics and commodity handheld meters. Price differentiation hinges on ISO 15118 protocol coverage depth and CE marking accreditation scope under EU AI Act extensions. Pricing pressure stems from semiconductor component volatility constraining wide-bandgap device availability. Fleet operators building high-utilization depots show lowest price sensitivity, while independent charging network operators in fragmented European markets drive hardest bargain negotiations.
Supply Chain Analysis
Freight cost volatility for specialized 1000V-capable safety enclosures and isolation transformers constrains laboratory expansion timelines across certification facilities. Component manufacturing concentrates in Germany, China, and the United States, with precision instrumentation feeds anchored in Bavaria's power-electronics heritage. Raw material dependencies span silicon carbide substrates, high-frequency magnetic cores, and RF shielding alloys. Single-source vulnerability in wide-bandgap semiconductor foundry allocation threatens equipment delivery schedules. Distribution runs through authorized channel partners for field-service segments and direct OEM relationships for integrated validation suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's tightening conformance requirements for grid-integrated charging hardware compound demand across every voltage class and protocol type, making this market a regulatory compounder with durable expansion tailwinds.
For Market Incumbents: Anchor premium positioning through backward integration into ISO 15118 protocol engineering talent pools, defending against specialized European grid-code conformance houses eroding CCS validation margins. Fortify channel control across Germany's autobahn fast-charging corridor where uptime assurance contracts fragment procurement patterns toward unbundled aftermarket diagnostics. For New Entrants and Emerging Players: Bidirectional charging validation for vehicle-to-grid communication protocols offers the most penetrable white-space as legacy test-equipment manufacturers rebuild frameworks around dynamic power-flow scenarios. Target wireless power-transfer testing for autonomous mobility applications where electromagnetic-compatibility suites remain underpenetrated by established protocols. Pursue advisory services positioning for EU AI Act algorithmic transparency documentation as a services-led entry path. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized European grid-code conformance houses with captive frequency-response module expertise and MIIT certification track access in China. Long-term viability centers on software-defined charging management capabilities extending beyond hardware validation. Watch for bidirectional charging mandate announcements from national regulators as the critical inflection signal for protocol complexity multiplication.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protocol Engineering | Captive ISO 15118 talent pools defend margin compression from specialized conformance competitors in Germany. |
| Wireless Power-Transfer Testing Suite Launch | First-mover electromagnetic-compatibility positioning addresses autonomous mobility validation gaps in premium passenger segments. |
| EU AI Act Advisory Services Expansion | Algorithmic transparency documentation capabilities capture software-defined charging management compliance obligations under CE marking. |
| Decentralized Validation Node Deployment | Distributed manufacturing-site infrastructure collapses pre-certification cycle times in China's Yangtze River Delta corridor. |
| Channel Partnership for Field-Service Diagnostics | Unbundled handheld tool procurement patterns across charging network operators fragment historical bundled suite purchasing. |
Methodological Framework
Bottom-up charging network operator and fleet operator demand modeling reconciled against top-down test-equipment manufacturing capacity tracking forms the analytical core. Primary interviews with laboratory accreditation managers, power-electronics R&D directors, charging infrastructure procurement leads, and field-service technician supervisors combined with secondary validation from MIIT certification filings, KBA type-approval databases, FCC Part 15 equipment authorization records, and EU Green Deal implementation progress reports.
Input-output matrices map voltage class penetration, protocol adoption curves, and end-user procurement scale across the projection horizon. Segmentation dimensions span product type, technology standard, end-user category, and installation environment. CAGRs derive from equipment replacement cycle acceleration patterns and laboratory capacity expansion trajectories. Industry-specific forecast inputs include 350kW DC fast-charger deployment pipelines and bidirectional charging regulatory mandate calendars.
The model holds under stable EU Green Deal implementation timelines and sustained fleet electrification investment; deviation in wide-bandgap semiconductor foundry allocation or protocol fragmentation between FCC Part 15 and GB standards would shift equipment availability and certification cost assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Car Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Asia-Pacific Portable EV Charger Market
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Smart EV Battery Charger Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market