
 Electric Vehicle Home Charger Market | 2026-2036
Electric Vehicle Home Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Home Charger Market Insights
The gap between premium smart chargers and basic Level 2 hardware is expanding as buyers split between price-sensitive entry-level EV owners and technology-focused early adopters seeking load management and solar integration. ChargePoint leverages its software ecosystem to sustain recurring revenue beyond hardware sales. Wallbox competes through design-forward units that anchor European residential channels.
An electric vehicle home charger converts alternating current from residential grids into direct current suitable for battery storage, typically delivering 3.7 kW to 19.2 kW depending on circuit capacity and onboard vehicle acceptance rates. Its primary purpose is to replenish battery state-of-charge during overnight parking periods when grid demand and time-of-use rates are lowest. Level 2 chargers dominate installed base economics while smart chargers with Wi-Fi connectivity represent the fastest-expanding margin pool as utilities and grid operators mandate demand-response compatibility. Portable installation types occupy a niche among rental properties where permanent electrical work faces landlord restrictions.
The US National Electrical Code through NFPA standards governs circuit sizing and safety disconnect requirements, while the EU F-Gas Regulation and CE marking framework shape product compliance for units with integrated cable management and cooling systems. The EU AI Act will soon classify certain load-balancing algorithms as high-risk, adding conformity assessment burdens for smart charger firmware. Stakeholders must monitor whether utility rate structures evolve to penalize unmanaged peak charging or reward vehicle-to-grid participation.
Market Dynamics
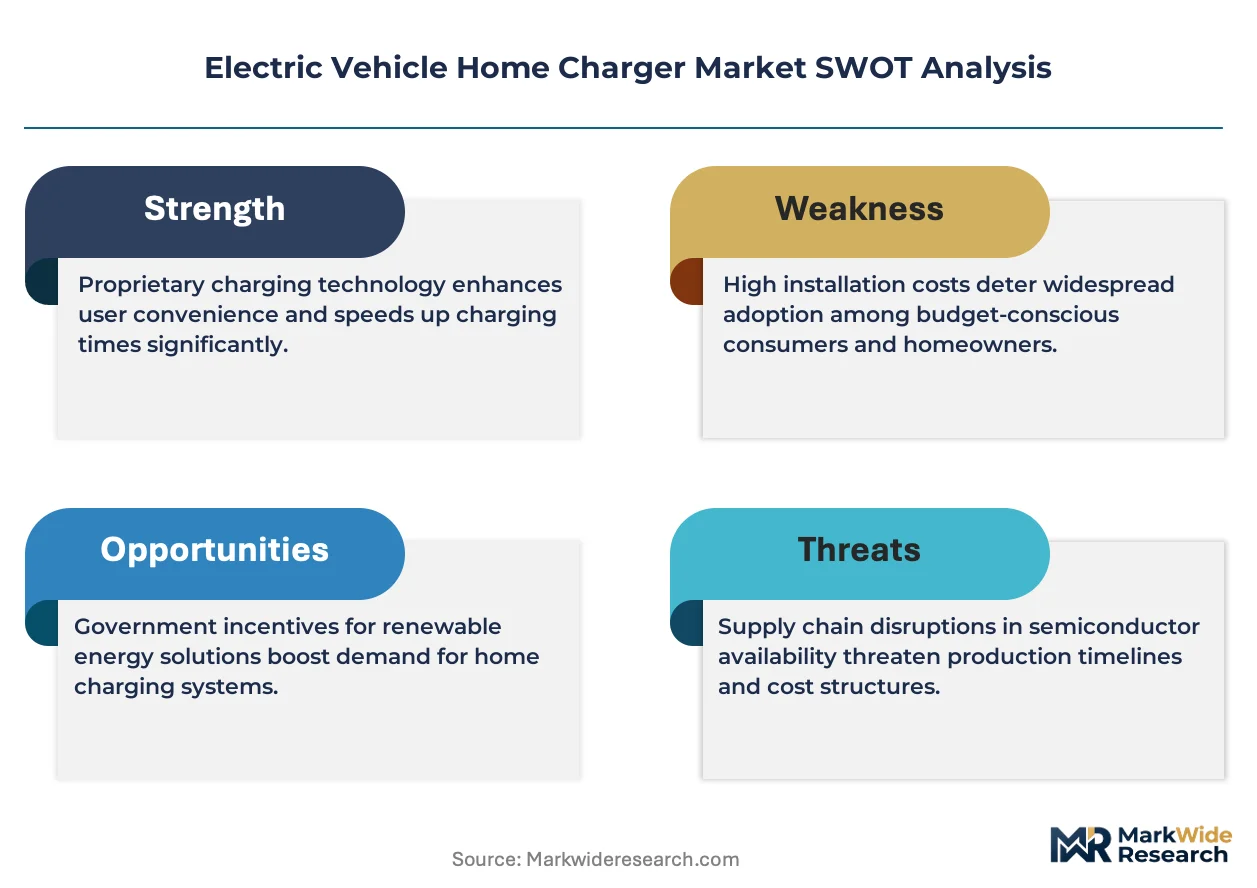
Load-balancing algorithms embedded in smart chargers are forcing hardware manufacturers to requalify firmware under emerging AI governance frameworks, compressing development timelines and redrawing competitive moats around software competency.
Growth Catalysts
- EU Green Deal building mandates:New construction across Germany, France, and the Netherlands must pre-wire parking infrastructure for EV-ready circuits, creating embedded demand for Level 2 hardware before vehicle purchases occur.
- Suburban garage ownership economics:United States households with attached garages in Texas, Florida, and California corridors face favorable time-of-use rate structures that make overnight charging cost-competitive with public DC fast charging.
- Silicon carbide power electronics:Wider bandgap semiconductors reduce thermal losses in onboard chargers, enabling 19.2 kW residential units without forced-air cooling systems that degrade reliability.
Market Restraints
- Copper conductor cost volatility:Raw material swings in copper cathode pricing transmit directly into cable assembly costs, squeezing margin on entry-level 32-amp units where price elasticity is highest.
- Multi-tenant electrical access fragmentation:German rental housing associations lack standardized load allocation protocols, delaying installations in apartment blocks where 40% of households reside.
- Grid interconnection queue delays:Utility transformer upgrades in United States suburban circuits face 18-24 month backlogs, capping addressable market growth in high-penetration postal codes.
Strategic Opportunities
- Vehicle-to-grid participation frameworks:FERC Order 2222 aggregation rules in United States wholesale markets enable residential chargers to bid demand response, creating recurring revenue streams beyond hardware sale.
- India multi-unit residential retrofit:BIS standards for EV supply equipment are formalizing, opening compliance pathways for smart chargers in Mumbai and Bangalore apartment towers currently unserved.
- Solar-storage-charger convergence:DC-coupled home energy systems pairing rooftop PV with bidirectional chargers bypass inverter conversion losses, targeting California NEM 3.0 ratepayers seeking bill optimization.
Industry Challenges
- Firmware certification timeline compression:EU AI Act high-risk system classification for autonomous load management will extend CE marking procedures by 8-12 months, straining smaller OEM development budgets.
- Electrician labor scarcity:Qualified installer pools in United States Midwest and Southeast markets cannot scale with permit application volumes, creating installation backlogs that defer revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Home Charger Market |
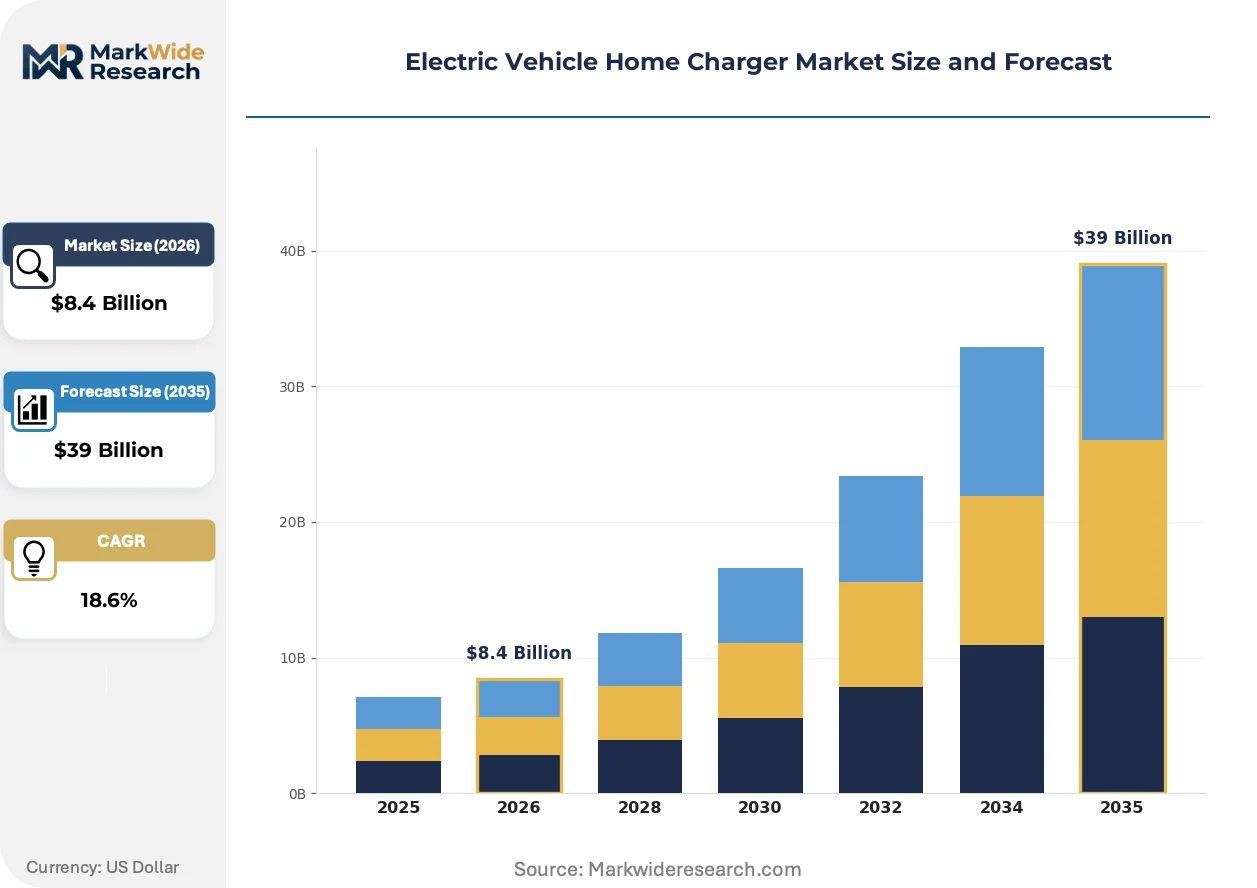
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, Smart Chargers, Ultra-Fast Chargers Installation Type: Wall-Mounted, Standalone, Portable, Hardwired End User: Residential, Commercial, Fleet Operators, Rental Properties Connectivity: Wi-Fi, Bluetooth, Ethernet, Cellular |
| Companies Covered | ChargePoint, ABB, Wallbox, EVBox, Eaton, Schneider Electric, Delta Electronics, Tesla, Blink Charging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Home Charger Market Trends and Innovations
Bi-directional power flow capabilities are migrating from commercial demonstration to residential product roadmaps, with utility rate design and interconnection standards racing to catch hardware availability.
Vehicle-to-home (V2H) power electronics is decentralizing residential energy architecture by enabling EV batteries to serve as backup power sources during grid outages. Early adopters in California and Texas are installing V2H-capable units at 3x the rate of standard unidirectional chargers. This topology is decentralizing the traditional home backup generator market by displacing natural gas standby systems in new construction.
EU AI Act algorithmic governance is reclassifying predictive load-balancing software as high-risk artificial intelligence, triggering mandatory third-party conformity assessment for smart charger firmware. Manufacturers must now document training data provenance and failure-mode mitigation strategies before CE marking. German and French certification bodies are expanding capacity to handle anticipated submission volumes from residential EVSE vendors.
Subscription-based charging management is displacing perpetual-license software sales as utilities seek operational control over distributed flexibility assets. United States municipal utilities in Colorado and Vermont are bundling charger hardware with demand-response enrollment, capturing customer lifetime value through rate bill credits rather than upfront equipment margins. This model concentrates in vertically integrated utility territories where ratebase treatment of smart infrastructure remains favorable.
Electric Vehicle Home Charger Market Segmentation
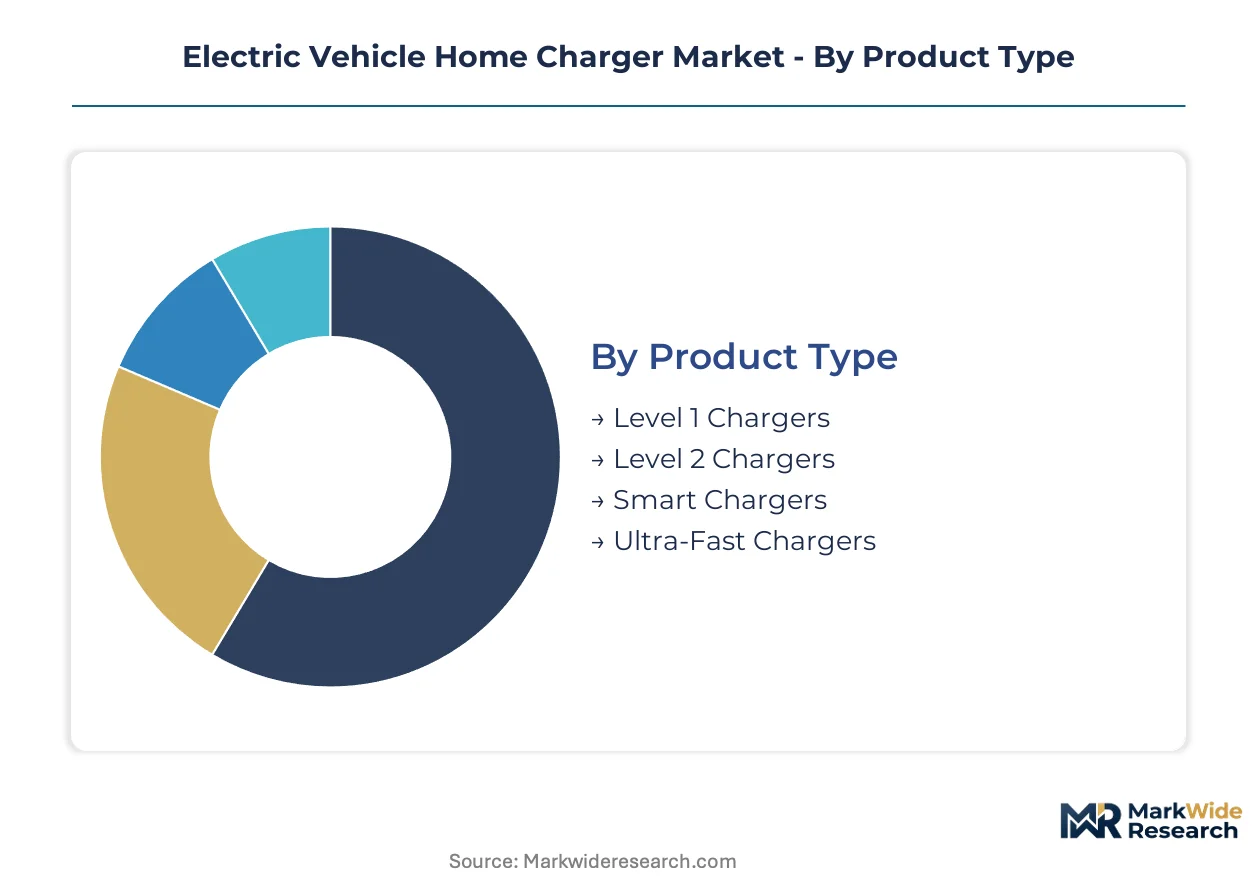
Segmentation in the electric vehicle home charger market reveals how certification burdens, installation constraints, and connectivity requirements fragment addressable demand across distinct buyer profiles and regulatory pathways.
Product Type:
Level 2 and smart chargers carry heavier compliance loads under EU AI Act algorithmic governance and NFPA electrical safety standards, while Level 1 and ultra-fast units face lighter firmware scrutiny but tighter circuit infrastructure constraints.
- Level 1 Chargers:These 120-volt units draw from standard residential outlets without dedicated circuit installation, serving apartment dwellers and rental properties where electrical modifications face landlord restrictions. Demand concentrates in urban Japanese condominiums where parking space scarcity limits infrastructure investment.
- Level 2 Chargers:Operating at 240 volts with 3.7 kW to 19.2 kW output, these units require dedicated branch circuits and GFCI protection under NEC Article 625. Installation volumes cluster in Texas and Florida suburban corridors where attached garage ownership exceeds 80% and time-of-use rate structures reward overnight charging.
- Smart Chargers:Wi-Fi-enabled units with load-balancing firmware face emerging EU AI Act high-risk system classification, extending CE marking timelines. These devices command premium positioning through utility demand-response compatibility and solar integration APIs.
- Ultra-Fast Chargers:Residential units exceeding 19.2 kW demand three-phase electrical service rare in North American single-family homes, limiting deployment to estate properties and commercial-adjacent installations.
Level 2 chargers sit at the top of the volume ranking, with smart chargers climbing the fastest as utilities mandate grid-responsive functionality.
Installation Type:
Cost tiers separate permanent infrastructure investments from flexible deployment options, with hardwired and wall-mounted units anchoring premium pricing while portable alternatives capture price-sensitive rental market segments.
- Wall-Mounted:Bracket-fixed units dominate garage installations where permanent parking allocation permits dedicated hardware placement. German multi-unit residential complexes favor these for basement parking retrofits under Green Deal pre-wiring mandates.
- Standalone:Pedestal-mounted chargers serve driveway and carport applications without wall attachment points, common in California ranch-style homes with detached parking structures.
- Portable:Cord-and-plug units bypass electrical permitting entirely, capturing renter demand in Mumbai and Bangalore apartment towers where BIS standards now formalize compliance pathways.
- Hardwired:Direct electrical connection without receptacle interface maximizes amperage capacity and weather resistance, requiring licensed electrician installation that creates 18-24 month bottlenecks in US Midwest markets.
Wall-mounted configurations hold the largest installed base, with portable installations expanding most quickly in Asian rental housing corridors.
End User:
Customer type determines procurement authority complexity, with single-family homeowners exercising direct purchasing decisions while fleet operators and rental property managers navigate multi-stakeholder approval chains.
- Residential:Single-family homeowners with dedicated parking represent the core revenue pool, particularly in US suburban corridors where garage ownership and daily commuting patterns create favorable Level 2 economics.
- Commercial:Workplace and retail destination charging serves employee and customer dwell-time opportunities, with installation decisions hinging on property manager capital allocation rather than end-user demand.
- Fleet Operators:Delivery and service vehicle depots require coordinated overnight charging for multiple assets, driving demand for load management systems that prevent simultaneous peak demand charges.
- Rental Properties:German rental housing associations and US multi-family landlords face tenant-installed charger requests without standardized cost-recovery mechanisms, fragmenting addressable market penetration where 40% of households reside in apartments.
Residential buyers command the highest unit volumes, with fleet operators gaining share fastest as commercial electrification accelerates.
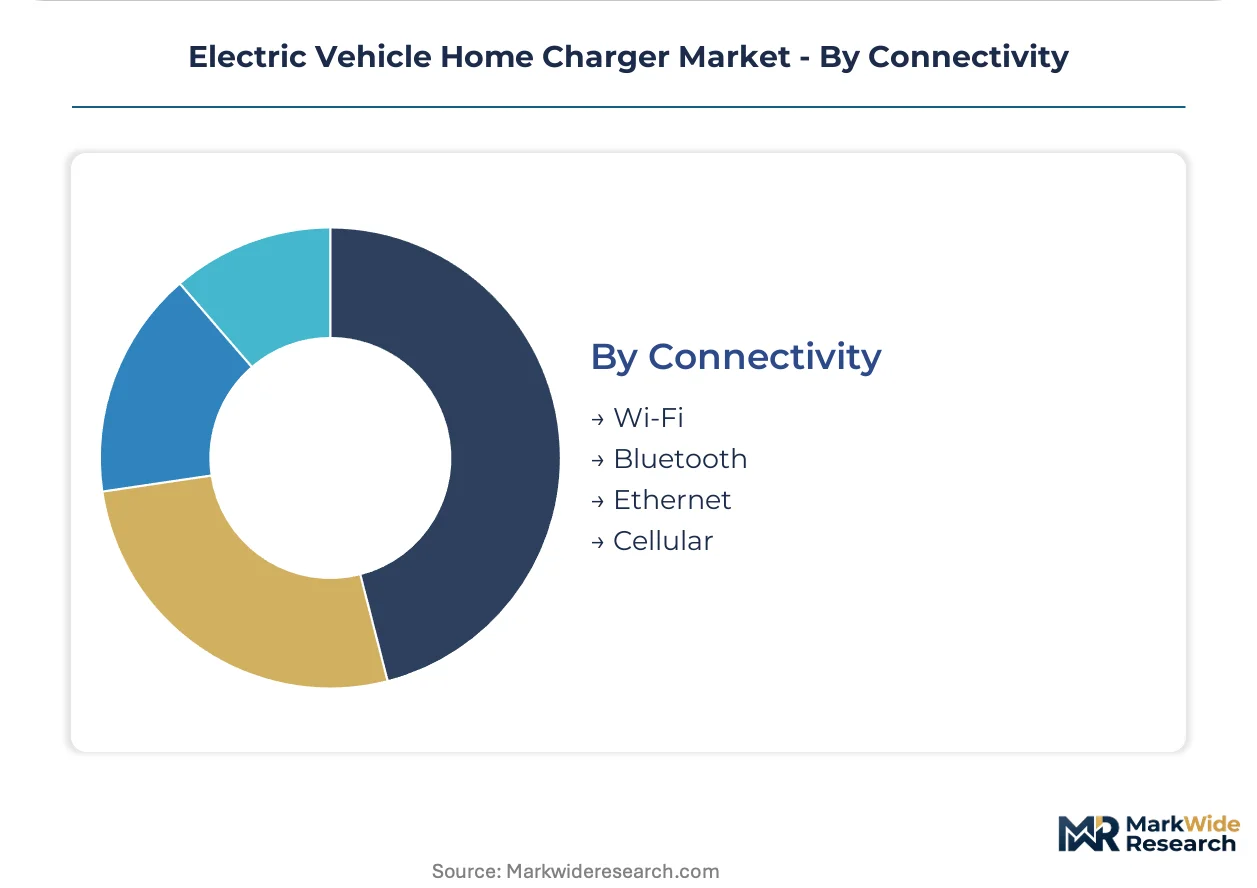
Connectivity:
Margin structure stratifies sharply across communication protocols, with cellular-enabled units capturing recurring software revenue while Bluetooth-only hardware competes on upfront equipment cost.
- Wi-Fi:Broadband-dependent connectivity dominates smart charger deployments, enabling over-the-air firmware updates and real-time utility rate optimization. California NEM 3.0 ratepayers favor these for solar-charger coordination.
- Bluetooth:Short-range pairing suffices for basic commissioning and local diagnostics, serving entry-level buyers without home internet reliability or privacy concerns about cloud data transmission.
- Ethernet:Wired network connection eliminates wireless interference risks in dense urban RF environments, preferred by commercial installations with existing structured cabling infrastructure.
- Cellular:Embedded LTE modems bypass homeowner network configuration entirely, commanding premium positioning in utility-managed demand-response programs where operational control requires guaranteed connectivity.
Wi-Fi connectivity leads current shipments, with cellular modules showing the steepest expansion trajectory as vertically integrated utilities bundle hardware with grid services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's rental housing associations are installing basement parking chargers at triple the rate of US apartment landlords, even though American suburban garage ownership exceeds 80 percent in Texas and Florida corridors.
United States
Texas and Florida suburban corridors drive Level 2 installation volumes where attached garage ownership surpasses 80 percent and time-of-use rates reward overnight charging. FERC Order 2222 aggregation rules enable residential chargers to bid demand response into wholesale markets. California NEM 3.0 ratepayers in the Bay Area and Los Angeles metro are adopting solar-integrated smart chargers fastest.
Germany
Multi-unit residential complexes represent the fastest-growing buyer segment as EV ownership broadens beyond single-family homeowners. EU Green Deal building mandates require pre-wired parking infrastructure in all new construction. Installation clusters concentrate in Berlin and Munich where rental housing associations retrofit basement parking under national building code deadlines.
China
Residential charger deployment lags vehicle sales in tier-one cities where apartment living dominates and parking space allocation remains scarce. MIIT standards for EV supply equipment are tightening interoperability requirements. Shenzhen and Shanghai municipal governments are piloting centralized load management systems for high-rise residential towers.
India
Mumbai and Bangalore apartment towers currently lack standardized EV infrastructure, creating retrofit demand as BIS formalizes compliance pathways for smart chargers. The country's national electrical regulator is drafting circuit capacity guidelines for multi-tenant buildings. Maharashtra state is mandating EV-ready parking in all new residential construction above 3,000 square meters.
United Kingdom
London's borough councils are accelerating on-street residential charger deployment where off-street parking remains below 50 percent of households. Building regulations now require EV-ready infrastructure in all new dwellings with parking. Installer networks in the Southeast and Midlands are scaling capacity to meet permit application volumes.
Electric Vehicle Home Charger Market Competitive Landscape
Top-tier vendors anchor premium smart charger tiers, while mid-market specialists compete on installation speed and regional electrical contractor relationships. The vendor base splits between vertically integrated hardware-software platforms and component assemblers sourcing power electronics from third-party foundries. Two strategic archetypes dominate: utility-facing demand-response platform providers and design-forward residential channel specialists. Competitive moves concentrate on firmware certification pre-emption under emerging AI governance frameworks and captive installer network expansion.
Within the utility-facing platform tier, ChargePoint exemplifies the recurring-revenue archetype through software ecosystem monetization, while Wallbox occupies a position among design-forward European residential channel anchors. Among diversified electrical equipment conglomerates, ABB and Schneider Electric represent scale-driven end-to-end infrastructure providers. These named entities illustrate how competitive positioning stratifies across software competency, industrial design differentiation, and integrated power management portfolio breadth.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| Wallbox |
| EVBox |
| Eaton |
| Schneider Electric |
| Delta Electronics |
| Tesla |
| Blink Charging |
| Others |
Pricing and Supply Chain Analysis
Utility fleet procurement managers and vertically integrated power companies anchor demand for cellular-enabled smart chargers, locking in subscription-based pricing models that bundle hardware with demand-response enrollment and recurring software revenue streams.
Pricing Analysis
Bundled service contracts now outpace unbundled hardware transactions as municipal utilities in Colorado and Vermont package installation with rate bill credits. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked AI-compliant units from basic Level 2 hardware and entry-level portable models. Cost compression in copper-dependent cable assemblies is intensifying because raw material volatility transmits directly into 32-amp unit margins. Fleet operators show least price sensitivity due to operational control requirements, while apartment renters in Mumbai and Bangalore remain most elastic.
Supply Chain Analysis
CE marking and UL certification gating concentrates qualified manufacturing in Germany, China, and Taiwan where power electronics foundries maintain regulatory compliance infrastructure. Silicon carbide semiconductors and copper cathode conductors anchor component sourcing, with firmware development tethered to EU AI Act conformity assessment timelines. Single-source vulnerability runs through Taiwan-based SiC wafer supply. Distribution runs through electrical contractor networks and utility direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications now dominate procurement criteria as utilities mandate demand-response compatibility and solar integration APIs, shifting buyer preference toward premium smart chargers with certified load-balancing algorithms.
For Market Incumbents: Deploy firmware certification pre-emption as the primary defensive lever. Accelerate CE marking submissions under EU AI Act high-risk system classification before smaller competitors exhaust development budgets. Capture captive installer network capacity in US Midwest and Southeast markets where electrician labor scarcity creates 18-24 month bottlenecks. Counter emerging design-forward specialists through utility-facing platform consolidation. For New Entrants and Emerging Players: EU Green Deal building mandates in Germany open a window for basement parking retrofit specialists serving Berlin and Munich rental housing associations. Target portable installation formats for Mumbai and Bangalore apartment towers where BIS standards formalize compliance pathways. Pursue direct partnerships with Indian state electricity regulators to secure load allocation protocols for multi-tenant buildings. For Investors and Strategic Acquirers: Vertically integrated electrical equipment conglomerates are the most active acquirer in this space, seeking software competency and demand-response platform capabilities. The 5-10 year viability window favors targets with pre-qualified AI Act firmware and captive installer relationships. Monitor FERC Order 2222 implementation velocity as the inflection signal for vehicle-to-grid revenue materialization.| Strategic Initiative | Industry Significance |
|---|---|
| AI Act Firmware Certification | CE marking pre-emption creates 8-12 month competitive moats against undercapitalized rivals. |
| Installer Network Expansion | Captive electrician capacity in US Midwest defends revenue recognition timelines against labor scarcity. |
| Utility Demand-Response Partnership | FERC Order 2222 aggregation rules enable recurring revenue streams beyond hardware margins. |
| Solar-Storage-Charger Convergence | DC-coupled systems targeting California NEM 3.0 ratepayers bypass inverter conversion losses. |
| Vehicle-to-Grid Capability Roadmap | Bidirectional power electronics displace natural gas standby generators in Texas and California new construction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged smart charger OEM product managers, utility demand-response program directors, electrical contractor operations heads, and BIS certification officials. Secondary validation drew from FERC filings, EU AI Act implementation guidance, NEC Article 625 standards documentation, and IEA EV charging infrastructure databases. Bottom-up installation volume modeling and top-down market sizing triangulated across utility procurement records and customs trade data.
Historical reference periods anchored the projection horizon to pre-pandemic baselines and post-IRA policy implementation trajectories. Segmentation dimensions spanned product type, installation format, connectivity protocol, and regional regulatory cluster. CAGRs derived from logistic adoption curve fitting against EV penetration rates and building code mandate timelines. Silicon carbide cost curves and copper price volatility indices fed power electronics margin sensitivity.
Revisions become necessary when EU AI Act enforcement intensity shifts, FERC Order 2222 aggregation rules stall, or copper cathode pricing breaks historical bands. Forecasts reflect documented assumptions about EV adoption velocity and building code compliance deadlines. A model refresh is warranted upon material change in utility rate structure design or vehicle-to-grid interconnection standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Solar Charge Controller Market
Electric Vehicle Charging
North America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market