
 EV Charging Facilities Market | 2026-2036
EV Charging Facilities Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charging Facilities Market Insights
Asset-light leasing and project finance models is tilting competitive dynamics toward operators with balance-sheet capacity rather than pure equipment makers. Tesla leverages its integrated vehicle-charging ecosystem to sustain high utilization rates at proprietary stations. ChargePoint anchors a network-agnostic platform that competes across retail, workplace, and multifamily installations. ABB differentiates through industrial-grade hardware and grid integration expertise for high-power applications.
EV charging facilities comprise the physical infrastructure, power electronics, and control systems that deliver electrical energy from grid or on-site generation to electric vehicle batteries, typically spanning power ratings from 7 kW residential units to 350 kW+ DC fast chargers with liquid-cooled cables and dynamic load management protocols. Their primary purpose is to bridge the energy supply gap between battery-electric vehicle range limitations and the distributed travel patterns of commercial and private transport. DC fast chargers capture the largest share of capital deployment as fleet operators and highway corridor developers prioritize throughput velocity over installation cost. Public charging stations generate the densest network competition, while fleet charging solutions represent the fastest-expanding installation category driven by logistics electrification mandates and total-cost-of-ownership optimization.
FERC interconnection rules, NHTSA charging reliability standards, and EPA clean fleet regulations collectively shape site permitting timelines, equipment certification requirements, and procurement incentives across the United States. State public utility commissions in California, New York, and Texas further modulate demand through time-varying rate structures and make-ready programs that reduce upfront capital burdens for hosts. Stakeholders must monitor how evolving grid capacity allocation protocols and interoperability certification timelines reshape site economics and network compatibility obligations.
Market Dynamics
Fleet electrification mandates and utility rate reforms are compressing payback periods for high-power charging assets, while grid interconnection queues create site-level bottlenecks that favor operators with pre-permitted real estate portfolios.
Growth Catalysts
- US federal infrastructure incentives:The Inflation Reduction Act's 30% investment tax credit for charging equipment reduces capital barriers for highway corridor developers and workplace hosts.
- Logistics fleet mandates:California's Advanced Clean Trucks regulation requires zero-emission vehicle sales percentages that force depot electrification at scale.
- Silicon carbide power electronics:Wider bandgap semiconductors enable 350 kW+ charging with reduced thermal losses, cutting station footprint and cooling costs.
Market Restraints
- Copper and rare earth magnet costs:Power cable assemblies and permanent magnet motors in cooling systems face input price volatility from concentrated Chilean and Chinese supply.
- Transformer lead times:North American electrical equipment manufacturing capacity constraints extend grid-side infrastructure delivery to 12-18 months.
- Interconnection protocol fragmentation:Differing ISO 15118 implementation timelines across OEMs delay plug-and-charge deployment and increase integration costs.
Strategic Opportunities
- German highway corridor gaps:Autobahn-adjacent sites with 1 MW+ grid connections remain underdeveloped relative to traffic density and fleet routing patterns.
- Vehicle-to-grid aggregation:Bidirectional charging protocols paired with fleet battery assets create frequency regulation revenue streams for depot operators.
- Multifamily make-ready programs:New York's Public Service Commission incentives reduce landlord capital exposure for Level 2 retrofits in parking structures.
Industry Challenges
- High-voltage technician scarcity:DC fast charger maintenance requires certified electricians with 480V+ and liquid cooling system expertise that training pipelines have not scaled.
- Permitting timeline variance:Local fire marshal interpretations of NFPA 70E arc flash requirements create unpredictable site approval durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charging Facilities Market |
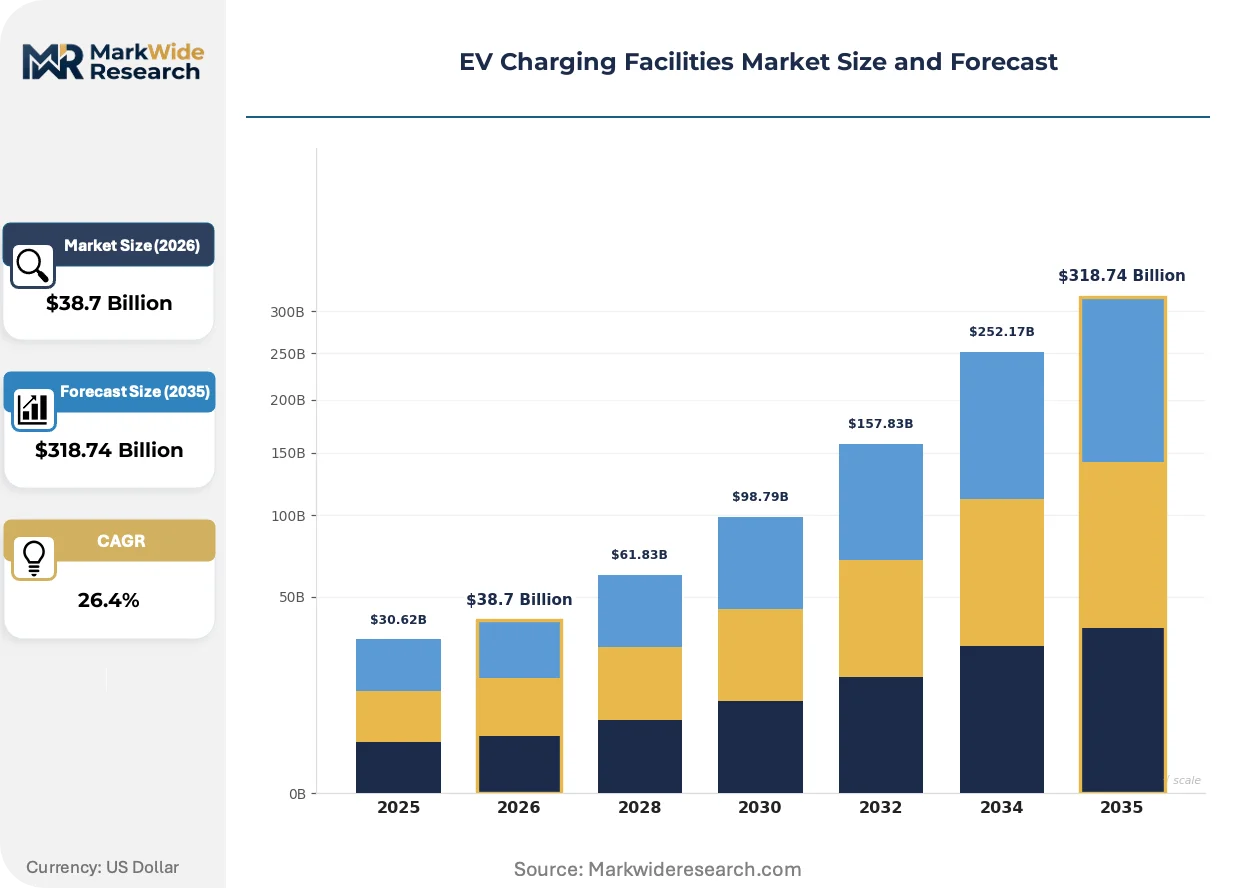
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $318.74 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Chargers Installation Type: Public Charging Stations, Corporate Charging Stations, Residential Charging Solutions, Fleet Charging Solutions Power Rating: 7 kW, 22 kW, 50 kW, 150 kW End User: Individual Consumers, Businesses, Government Agencies, Fleet Operators |
| Companies Covered | Tesla, ChargePoint, ABB, EVBox, Shell, BYD, Wallbox, EVgo, Star Charge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charging Facilities Market Trends and Innovations
Battery-buffered charging systems and dynamic load management software are decoupling station deployment from immediate grid upgrades, allowing higher-power installations at constrained sites.
Silicon carbide MOSFETs in power conversion modules handle higher switching frequencies with lower losses than silicon IGBTs. Fleet operators in Germany and California are specifying SiC-based rectifiers for 350 kW depots to minimize demand charges. This semiconductor transition is hybridizing hardware architectures, merging on-site battery storage with direct grid coupling to flatten peak loads.
The EU's Alternative Fuels Infrastructure Regulation mandates standardized payment interoperability and minimum power outputs at highway stations by operator category. Equipment vendors must recertify existing hardware for Combined Charging System 2.0 compliance ahead of enforcement deadlines. Commercial corridor developers face accelerated replacement cycles for non-compliant legacy installations.
Fleet procurement teams now bundle charging infrastructure with vehicle supply agreements, treating electrons as a managed service rather than capital equipment. This unbundles hardware ownership from energy delivery, with logistics operators in Texas and South Korea contracting kilowatt-hour throughput guarantees. The shift compresses vendor selection criteria toward network reliability metrics and software integration depth.
EV Charging Facilities Market Segmentation
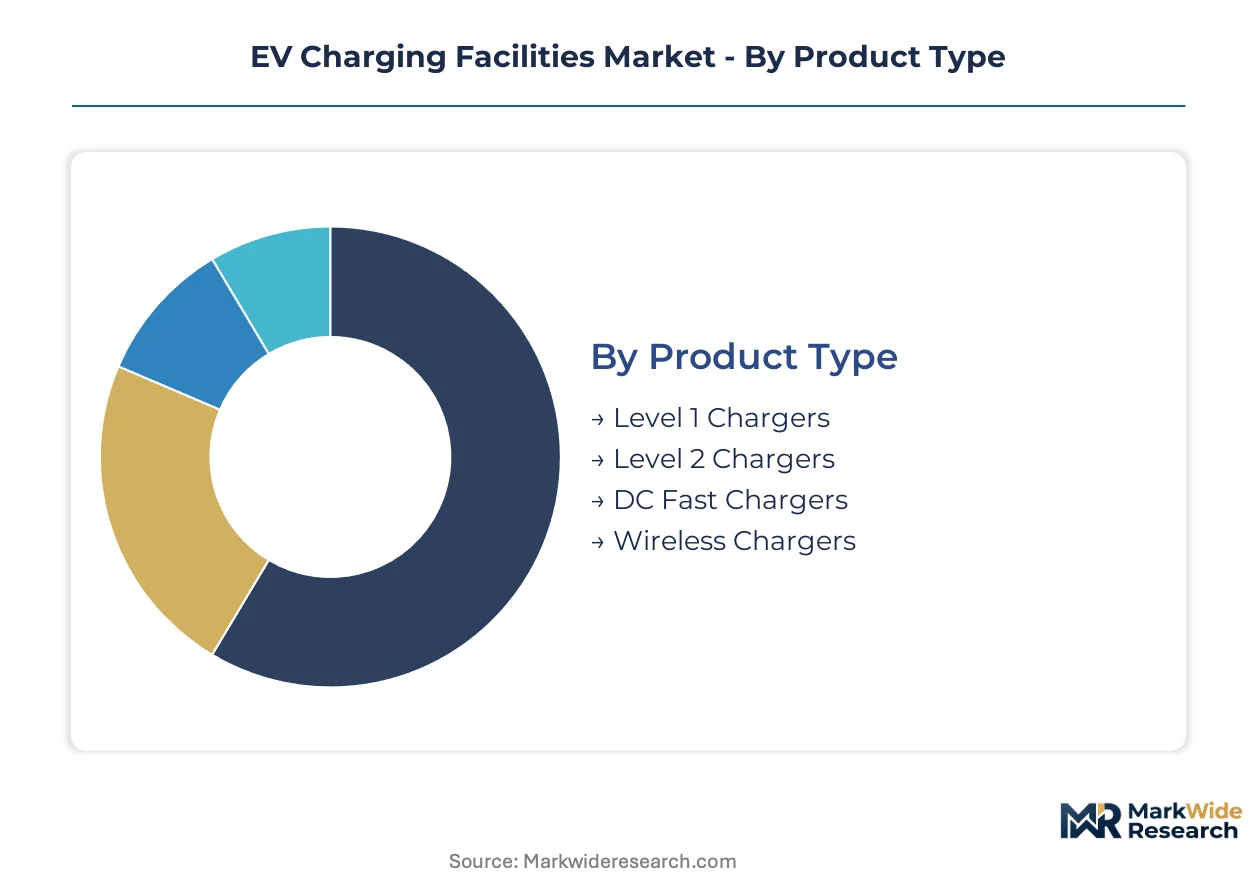
Segmentation in EV charging facilities reveals how power electronics, deployment models, and customer economics create distinct investment profiles. Equipment specifications and installation contexts determine capital intensity, utilization patterns, and regulatory exposure across the value chain.
Product Type:
Mature AC charging hardware dominates installed base volumes while emerging high-power DC architectures capture deployment capital.
- Level 1 Chargers:These 120V residential units deliver 1.4 kW through standard household outlets with minimal installation requirements. Demand concentrates in North American single-family retrofits where overnight dwell times offset slow charging speeds. Their low hardware cost sustains appeal in rental housing markets with limited electrical upgrades.
- DC Fast Chargers:High-power rectifiers convert three-phase AC to DC at 50-350 kW for direct battery injection. Fleet operators in California and Germany prioritize these for depot throughput, while highway corridor developers specify liquid-cooled 350 kW variants to minimize dwell time. Silicon carbide power modules are displacing silicon IGBTs to cut thermal losses and station footprint.
- Level 2 Chargers:240V AC equipment delivering 3.3-19.2 kW through dedicated circuits, now standard for workplace and multifamily installations.
- Wireless Chargers:Inductive pad systems transferring power across air gaps at 3-11 kW, currently deployed in premium automotive trials and autonomous fleet staging areas.
DC Fast Chargers handle the majority of throughput; Fleet Charging Solutions is the fastest mover on share.
Installation Type:
Cost tier separation runs from subsidized residential make-ready programs to self-financed corporate depots with private grid infrastructure.
- Public Charging Stations:Highway corridor and urban curbside assets serving transient vehicles with payment interoperability mandates. California's NEVI-funded sites and Germany's Autobahn network attract the densest competitive positioning due to high utilization visibility.
- Fleet Charging Solutions:Dedicated depot infrastructure serving logistics, transit, and municipal vehicle pools with scheduled charging windows. California's Advanced Clean Trucks regulation and Amazon's electrification commitments are forcing warehouse-scale deployments with megawatt-level grid connections.
- Corporate Charging Stations:Workplace installations subsidizing employee charging as retention and sustainability signaling.
- Residential Charging Solutions:Garage and driveway equipment owned or leased by individual vehicle owners, often bundled with utility time-of-use rates.
Fleet Charging Solutions handles the majority of throughput; Fleet Charging Solutions is expanding most quickly on share.
Power Rating:
Volume concentration sits at 7 kW residential baseline, with margin migration toward 150 kW fleet and highway applications.
- 150 kW:High-output hardware enabling 20-80% battery replenishment in 30 minutes for highway corridor service. German and South Korean operators specify this tier to balance equipment cost against throughput velocity, with silicon carbide rectifiers reducing cooling overhead.
- 7 kW:Single-phase residential standard matching overnight charging needs for typical daily driving distances. North American and European utilities favor this tier for grid stability, with smart load management preventing distribution transformer overload.
- 22 kW:Three-phase AC ceiling for European workplace and multifamily installations where grid connection permits.
- 50 kW:Entry-level DC fast charging for urban retail locations with constrained electrical service.
7 kW handles the majority of throughput; 150 kW is gaining share fastest.
End User:
Customer type determines procurement sophistication, from individual price sensitivity to fleet total-cost-of-ownership optimization.
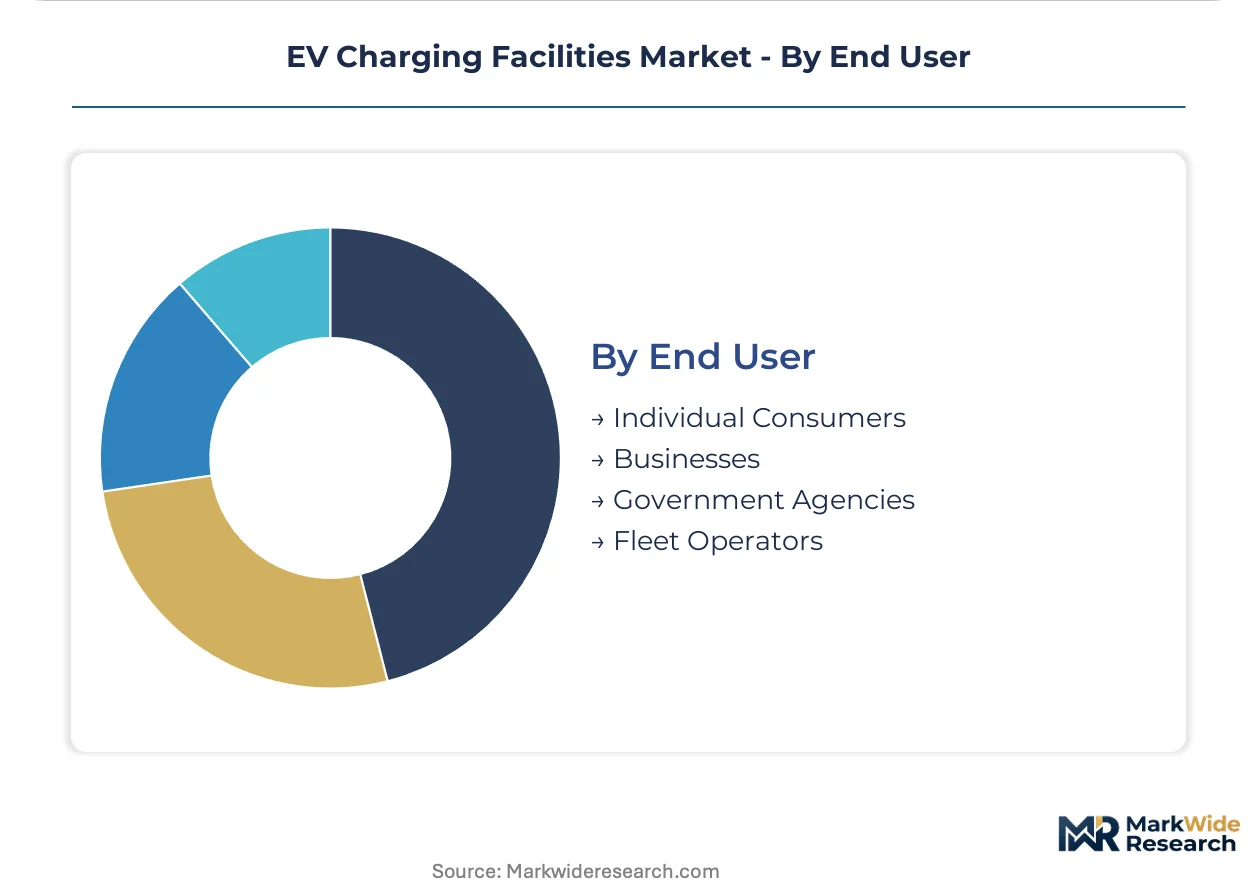
- Fleet Operators:Logistics, transit, and delivery enterprises treating charging as operational infrastructure with uptime guarantees. California's CARB mandates and total-cost-of-ownership targets are forcing depot electrification at scale, with procurement teams bundling hardware, software, and energy supply into service contracts.
- Businesses:Corporate entities installing workplace and retail charging for employee retention, customer dwell extension, and sustainability reporting.
- Individual Consumers:Residential owners and renters purchasing or leasing equipment through automotive dealerships, utilities, or direct retail channels.
- Government Agencies:Municipal, state, and federal entities deploying public infrastructure with NEVI, IRA, and equivalent national funding.
Fleet Operators handles the majority of throughput; Fleet Operators is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for power electronics and copper cabling tilts procurement costs toward Asian manufacturing hubs, while domestic assembly capacity in Germany and the United States absorbs final integration stages. Export flows of charging hardware concentrate in Chinese and South Korean production bases serving European and North American deployment pipelines. Grid interconnection standards and utility rate structures determine regional deployment velocity more than equipment availability.
United States
Fleet depot electrification and highway corridor development drive capital allocation toward California, Texas, and the Midwest manufacturing belt. The Inflation Reduction Act's investment tax credit and NHTSA charging reliability standards compress project timelines for NEVI-funded sites. Dallas-Fort Worth logistics hubs and Detroit automotive corridors anchor megawatt-scale charging installations serving commercial vehicle transition mandates.
Germany
Autobahn-adjacent corridor gaps and industrial fleet electrification create concentrated demand in Bavaria and North Rhine-Westphalia. The EU Alternative Fuels Infrastructure Regulation mandates standardized payment interoperability and minimum power outputs by enforcement deadlines. Munich and Stuttgart automotive clusters integrate charging infrastructure with OEM vehicle supply agreements under bundled service contracts.
China
Domestic EV penetration rates and state-grid utility coordination enable rapid deployment scaling across Yangtze River Delta manufacturing zones. MIIT technical standards and GB certification protocols govern power module interoperability and dynamic load management system integration. Shenzhen and Shanghai urban clusters host the densest fast-charging network concentrations serving ride-hail and delivery fleet electrification.
South Korea
Chaebol-affiliated fleet operators and government-mandated clean city zones accelerate depot infrastructure investment in Seoul Capital Area and Busan-Ulsan industrial corridors. MFDS equipment safety certification and KEPCO time-varying rate structures shape site economics for high-power installations. Incheon logistics hubs and Gwangju-Honam manufacturing bases concentrate 350 kW+ silicon carbide rectifier deployments.
United Kingdom
Workplace charging mandates and multifamily retrofit programs stimulate demand across London-Southeast and Midlands urban corridors. Ofgem regulatory frameworks and local authority planning permissions modulate installation velocity for public and private sites. Birmingham logistics clusters and Manchester transit authorities anchor fleet charging solutions under total-cost-of-ownership procurement models.
EV Charging Facilities Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in power electronics and thermal management subsystems. The vendor base separates into three strategic layers: network-agnostic software platforms, industrial-grade hardware fabricators, and integrated vehicle-charging ecosystems. Consolidation pressure concentrates among mid-scale operators lacking balance-sheet capacity for asset-heavy deployment models. Dominant competitive moves include strategic partnerships bundling hardware with energy supply contracts and geographic expansion into underdeveloped highway corridors.
Within the integrated ecosystem tier, Tesla exemplifies vertical control spanning vehicle production through proprietary charging infrastructure. ChargePoint occupies a network-agnostic position serving retail, workplace, and multifamily installation contexts without hardware exclusivity. ABB represents industrial-grade specialization in high-power applications and grid integration protocols. These three anchors illustrate how competitive positioning diverges between closed-loop vehicle-charging integration and open-platform hardware supply.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| EVBox |
| Shell |
| BYD |
| Wallbox |
| EVgo |
| Star Charge |
| Others |
Pricing and Supply Chain Analysis
Chinese silicon carbide wafer fabrication and copper cable assembly concentration feeds margin capture downstream toward power module integrators and depot operators with long-term service contracts. Fleet procurement teams now treat charging infrastructure as a managed service, shifting value pools from hardware markups toward software-enabled energy management and uptime guarantees.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification depth—UL 2594 and ISO 15118 compliance—plus liquid-cooled 350 kW architectures, while standard tiers compete on silicon IGBT cost curves. Cost compression in entry-level AC hardware is intensifying because of Shenzhen and Dongguan manufacturing scale. Fleet operators show the least price sensitivity, prioritizing throughput guarantees over capital outlay; residential consumers remain most price-sensitive, gravitating toward utility-subsidized make-ready programs.
Supply Chain Analysis
Tariff exposure between China and the United States dominates procurement risk calculus for North American developers. Silicon carbide substrates draw from Chinese and Japanese wafer growth facilities; copper cabling and rare earth magnets for cooling systems rest on Chilean mining and Chinese processing concentration. Single-source vulnerability in transformer core steel amplifies lead time uncertainty. Distribution runs through OEM-direct contracting for fleet depots and electrical distributor networks for residential and workplace installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Charging-as-a-service contracts and energy management software subscriptions are expanding faster than hardware shipments, creating attach-rate opportunities that compound customer lifetime value beyond initial equipment sales.
For Market Incumbents: Harden network reliability metrics as the primary defense against Tesla's integrated ecosystem lock-in. Deepen backward integration into silicon carbide power module sourcing to secure thermal performance advantages. Invest in UL certification pipelines ahead of NHTSA reliability standard enforcement timelines. For New Entrants and Emerging Players: German Autobahn-adjacent corridor gaps offer the most penetrable white-space for 1 MW+ grid-connected installations. Target multifamily retrofit programs in New York and California where make-ready incentives reduce landlord acquisition friction. Lead with dynamic load management software differentiation rather than hardware cost parity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed depot operators holding pre-permitted real estate portfolios in Dallas-Fort Worth and Detroit corridors. Five-to-ten-year viability hinges on contracted throughput visibility under fleet electrification mandates. Watch California CARB rulemaking acceleration as the inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Integration | Reduces thermal losses at 350 kW tiers, cutting station footprint for California and German fleet depots. |
| Dynamic Load Management Software Development | Enables peak shaving and demand charge optimization that improves depot economics under KEPCO and PG&E rate structures. |
| Pre-Permitted Real Estate Portfolio Acquisition | Compresses interconnection timelines that currently extend 12-18 months for transformer-dependent sites. |
| Vehicle-to-Grid Protocol Certification | Unlocks frequency regulation revenue streams for fleet operators under FERC Order 2222 aggregation frameworks. |
| Multifamily Make-Ready Program Partnerships | Captures landlord capital exposure reduction through New York PSC and California SGIP incentive channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FERC interconnection filings, NHTSA reliability standard drafts, utility rate case dockets, and OEM charging infrastructure announcements. Charging network operators, fleet procurement directors, utility demand-side management officers, and power electronics engineering leads provided operational perspective. Customs data on silicon carbide substrate imports and copper cable trade flows anchored supply-side validation. Bottom-up installation tracking across California, Texas, and Germany triangulates against top-down infrastructure incentive disbursement analysis.
Forecast inputs span power rating tiers, installation contexts from highway corridor to residential garage, end-user categories from fleet operators to individual consumers, and regional regulatory clusters shaped by IRA tax credits and EU Alternative Fuels Infrastructure Regulation mandates. CAGRs derive from elasticity modeling against vehicle electrification penetration curves and grid interconnection capacity expansion. Silicon carbide adoption rates and fleet electrification mandate enforcement timelines serve as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated vehicle OEMs or state-backed Chinese equipment manufacturers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Electric Vehicle Charging System Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market