
 United Kingdom Electric Vehicle Battery Manufacturing Market | 2026-2036
United Kingdom Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Electric Vehicle Battery Manufacturing Market Insights
The performance gap between premium nickel-cobalt-manganese cathodes and commodity lithium-iron-phosphate cells is broadening across UK supply chains. Envision AESC UK Ltd leverages its Sunderland gigafactory footprint to anchor high-volume output for Nissan's regional EV programs. AMTE Power plc specializes in high-power cell architectures for commercial vehicle duty cycles, while Nyobolt Ltd differentiates through ultra-fast-charging niobium anode technology aimed at premium automotive tiers.
United Kingdom Electric Vehicle Battery Manufacturing encompasses the industrial production of electrochemical energy storage systems, typically lithium-ion cells with energy densities exceeding 250 Wh/kg, assembled into modules and packs for traction power in road vehicles. The primary purpose is to enable zero-emission propulsion while meeting crash safety, thermal runaway containment, and cycle-life benchmarks set by OEM qualification protocols. Lithium-ion chemistry dominates current UK capacity installations owing to established supply chains and manufacturing equipment availability. Solid-state technology attracts concentrated R&D investment as developers target energy density thresholds above 400 Wh/kg with inherent flame resistance. Battery Management Systems represent the critical intelligence layer where margin pools deepen through software-defined performance optimization and predictive diagnostics.
The UK Department for Transport's zero-emission vehicle mandate and the Automotive Transformation Fund shape domestic demand by binding OEM sales to escalating EV quotas and conditioning grants on local content thresholds. BSI standards for battery safety and recycling create compliance barriers that favor producers with integrated testing and second-life recovery capabilities. Stakeholders must weigh the pace of solid-state maturation against lithium-ion capacity commitments that lock in decade-long supply agreements.
Market Dynamics
The UK government's ZEV mandate binds OEMs to escalating electric vehicle sales quotas, forcing domestic battery procurement commitments that reshape manufacturing investment patterns across the Midlands and North East corridors.
Growth Catalysts
- Automotive Transformation Fund:UK government capital grants condition funding on local content thresholds, pulling gigafactory construction toward British manufacturing corridors.
- Logistics electrification:Fleet operators across Britain are scaling battery-electric van and truck deployments, creating anchor demand for high-cycle commercial cell architectures.
- Solid-state R&D pipelines:British universities and startups are advancing sulfide electrolyte research targeting energy density thresholds above 400 Wh/kg with inherent flame resistance.
Market Restraints
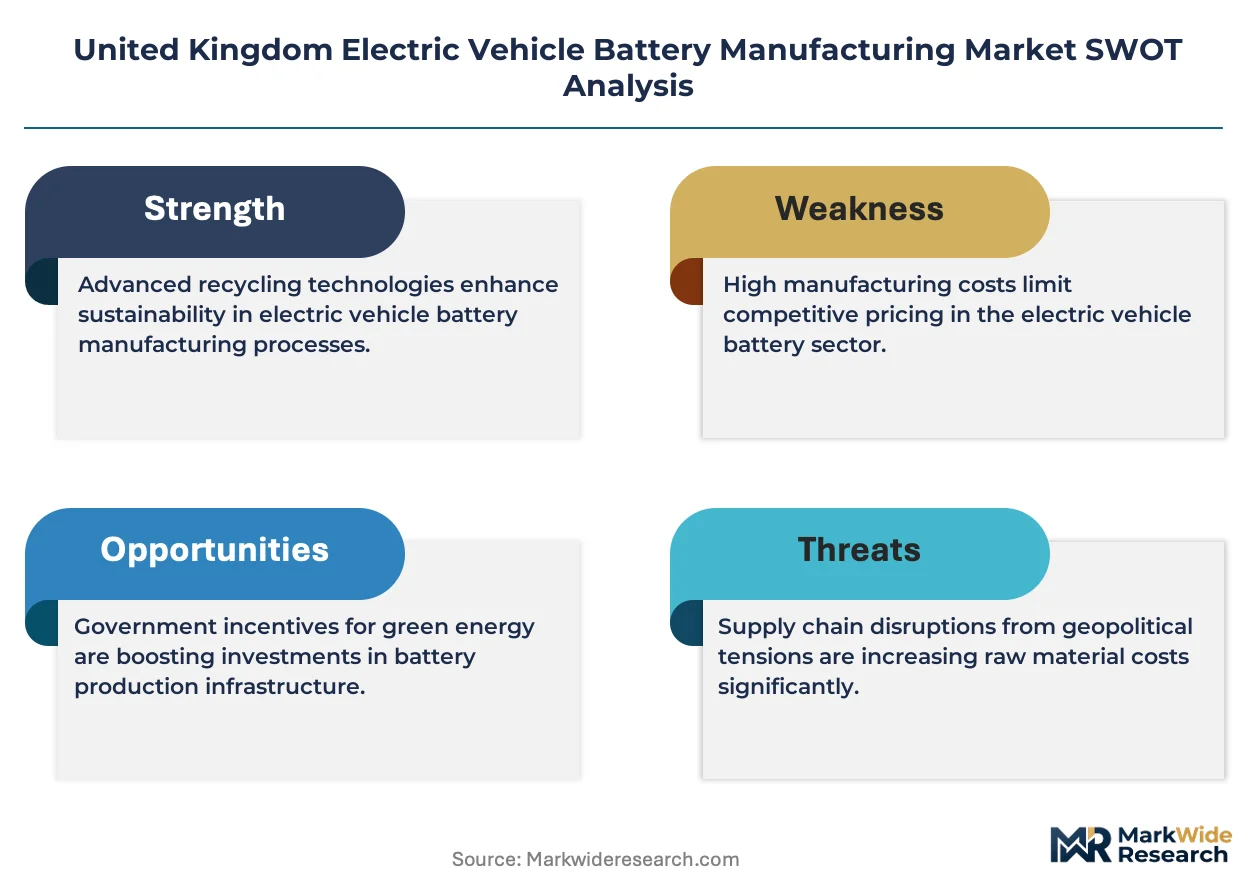
- Cathode material cost volatility:Nickel and cobalt price swings from Democratic Republic of Congo and Indonesian supply nodes compress margin predictability for UK cell producers.
- Electrolyte supply concentration:Chinese refiners dominate lithium hexafluorophosphate production, creating single-source vulnerability for British electrolyte formulation.
- Cell formation cycle time:Current lithium-ion manufacturing requires 14-21 day aging protocols that throttle throughput velocity at UK gigafactory scale.
Strategic Opportunities
- Scottish Highlands renewable integration:Grid-scale battery storage co-location with onshore wind creates second-life revenue streams for UK automotive cell retirees.
- BSI PAS 63119 certification:Early compliance with British battery passport standards opens preferential access to EU-UK trade corridors under post-Brexit rules of origin.
- Sodium-ion chemistry convergence:Hard carbon anode and Prussian white cathode combinations offer UK producers a lithium-hedged product line for stationary storage applications.
Industry Challenges
- Electrochemical engineering talent scarcity:UK universities produce insufficient cell scientists and manufacturing engineers to staff planned gigafactory expansions.
- UN 38.3 certification timelines:Lithium-ion pack safety testing protocols create 6-12 month approval bottlenecks that delay OEM program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Electric Vehicle Battery Manufacturing Market |
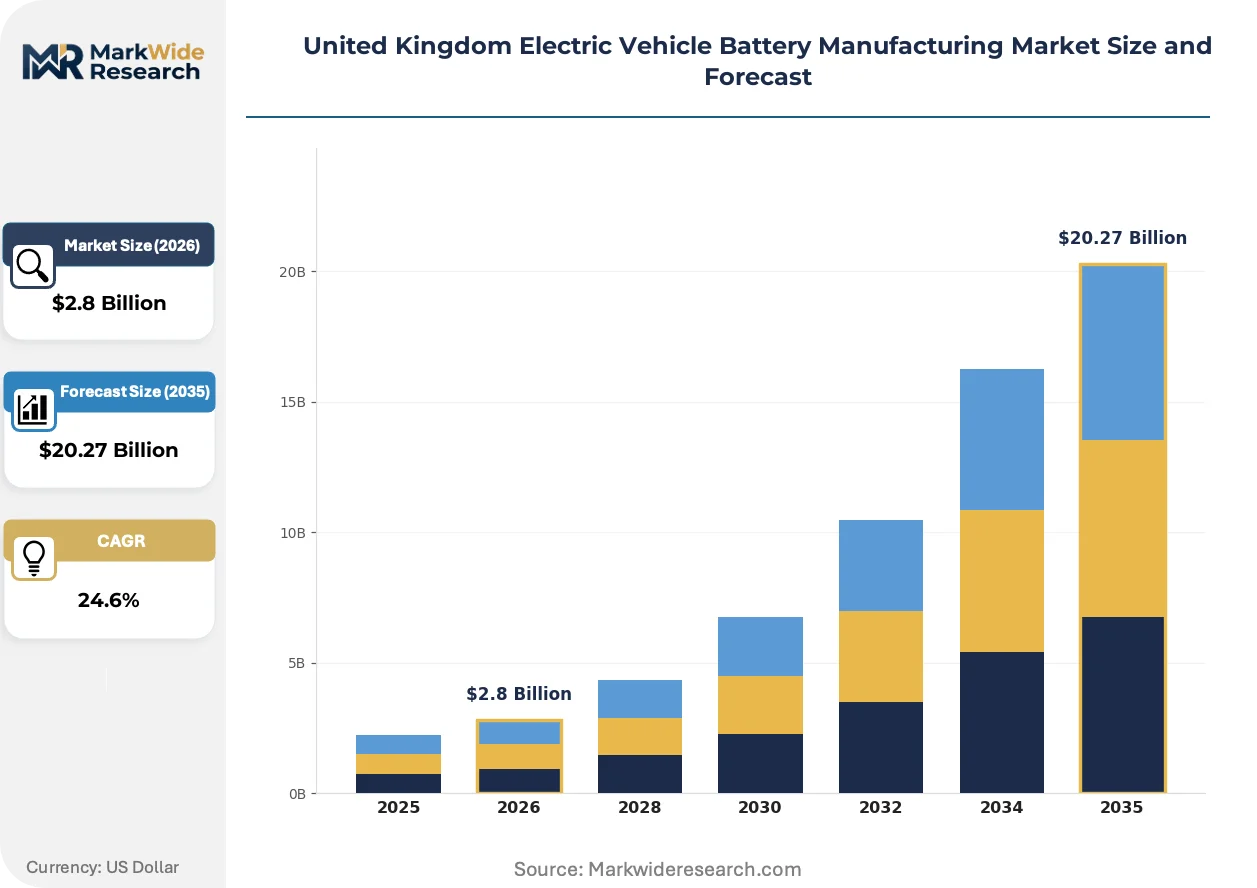
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Solid-state, Nickel-metal Hydride, Lead-acid Technology: Battery Management Systems, Thermal Management, Energy Density Optimization, Recycling Techniques End User: OEMs, Fleet Operators, Charging Infrastructure Providers, Aftermarket Services Application: Passenger Vehicles, Commercial Vehicles, Public Transport, Industrial Machinery |
| Companies Covered | Envision AESC UK Ltd, Agratas Energy Storage Solutions, Nissan Motor Manufacturing (UK) Ltd, AMTE Power plc, Nyobolt Ltd, LEAPENERGY, Nexeon, GS Yuasa, Johnson Matthey Battery Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Electric Vehicle Battery Manufacturing Market Trends and Innovations
Dry electrode coating processes are displacing solvent-based manufacturing across UK battery lines, cutting energy intensity and capital requirements while tightening particulate control standards.
Dry electrode deposition is automating electrode manufacturing by eliminating N-methyl-2-pyrrolidone solvent recovery systems. Envision AESC and emerging UK producers are piloting this transition at Sunderland and Coventry sites. The technology is automating throughput gains of 30-40% while reducing factory footprint requirements by half.
The UK Department for Transport's zero-emission vehicle mandate phases in escalating EV sales percentages through 2035. OEMs face penalties for non-compliance that internalize battery sourcing decisions toward domestic supply. Premium and mass-market automotive tiers are responding by binding multi-year offtake agreements to British cell production.
Fleet procurement departments are consolidating battery sourcing through power purchase agreements that bundle vehicle, charging infrastructure, and energy management. Commercial vehicle operators in Britain are displacing transactional purchasing with total cost of ownership contracts. This shift is most visible among last-mile delivery networks in the West Midlands where electrification timelines compress against Clean Air Zone deadlines.
United Kingdom Electric Vehicle Battery Manufacturing Market Segmentation
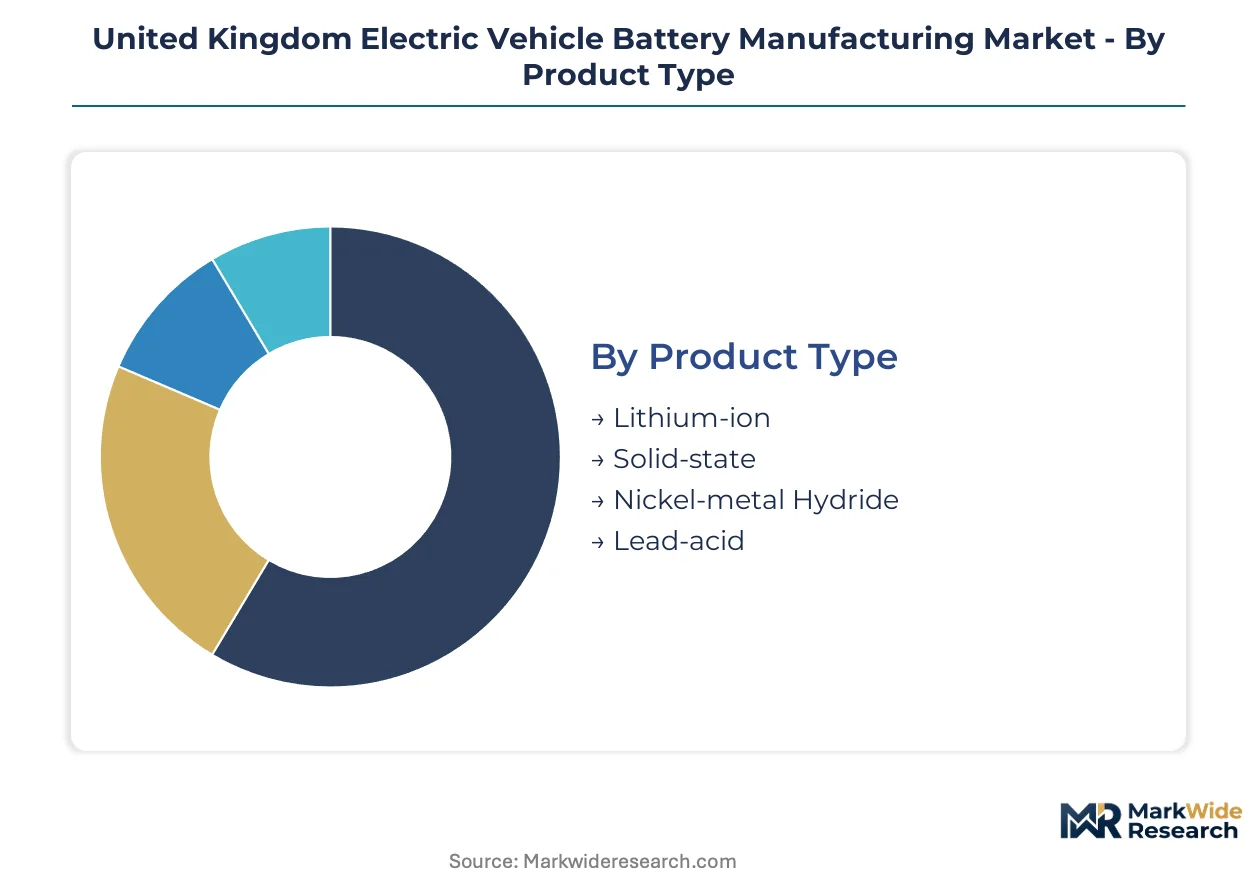
United Kingdom Electric Vehicle Battery Manufacturing segments reveal distinct margin profiles and capability requirements. Chemistry choices, thermal architectures, and end-user procurement patterns each create separate competitive battlegrounds for British producers.
Product Type:
The volume versus premium split separates mass-market lithium-ion deployments from emerging solid-state platforms targeting energy density breakthroughs.
- Lithium-ion:Nickel-cobalt-manganese and lithium-iron-phosphate chemistries dominate current UK gigafactory output. Midlands-based OEM programs anchor demand, though cathode material cost volatility from Indonesian nickel and DRC cobalt nodes compresses margin predictability for cell producers.
- Solid-state:Sulfide electrolyte architectures promise energy density above 400 Wh/kg with inherent flame resistance. British universities and startups concentrate R&D investment here, targeting premium automotive tiers where safety premiums offset higher unit costs.
- Nickel-metal Hydride:Legacy chemistry retains niche presence in hybrid powertrain applications. Toyota's UK hybrid programs represent residual demand concentration.
- Lead-acid:Conventional chemistry persists in auxiliary power and starter battery roles. Limited traction in primary EV propulsion outside lowest-cost conversion segments.
Mature deployment sits with lithium-ion. Newer deployment is concentrated in solid-state.
Technology:
Software-defined intelligence layers now capture deeper margin pools than commodity cell assembly.
- Battery Management Systems:Predictive diagnostics and performance optimization algorithms differentiate UK producers. BSI PAS 63119 certification requirements for battery passports create compliance barriers favoring integrated BMS developers.
- Thermal Management:Liquid cooling plates and phase-change materials prevent thermal runaway in high-power duty cycles. Commercial vehicle operators in the West Midlands prioritize these systems for last-mile delivery electrification timelines.
- Energy Density Optimization:Silicon-anode and high-nickel cathode combinations push gravimetric performance. Dry electrode coating processes at Envision AESC Sunderland cut energy intensity while tightening throughput.
- Recycling Techniques:Hydrometallurgical recovery and direct cathode regeneration enable second-life revenue streams. Scottish Highlands grid-scale storage co-location with onshore wind creates anchor demand for retired automotive cells.
Established revenue concentration centers on battery management systems. Steepest expansion trajectory belongs to recycling techniques.
End User:
Procurement consolidation is shifting from transactional purchasing toward total cost of ownership contracts.
- OEMs:Nissan, Jaguar Land Rover, and emerging British EV marques bind multi-year offtake agreements to domestic cell production. ZEV mandate penalties for non-compliance internalize sourcing decisions toward British supply.
- Fleet Operators:Power purchase agreements bundle vehicles, charging infrastructure, and energy management. Clean Air Zone deadlines across Birmingham and Manchester compress electrification timelines for van and truck deployments.
- Charging Infrastructure Providers:Grid-scale buffer storage and rapid-charge buffer systems create stationary demand for UK cell output.
- Aftermarket Services:Module replacement and remanufacturing operations serve extending vehicle lifecycles. UN 38.3 certification timelines create 6-12 month approval bottlenecks.
Volume concentration remains with OEMs. Procurement innovation is expanding most quickly among fleet operators.
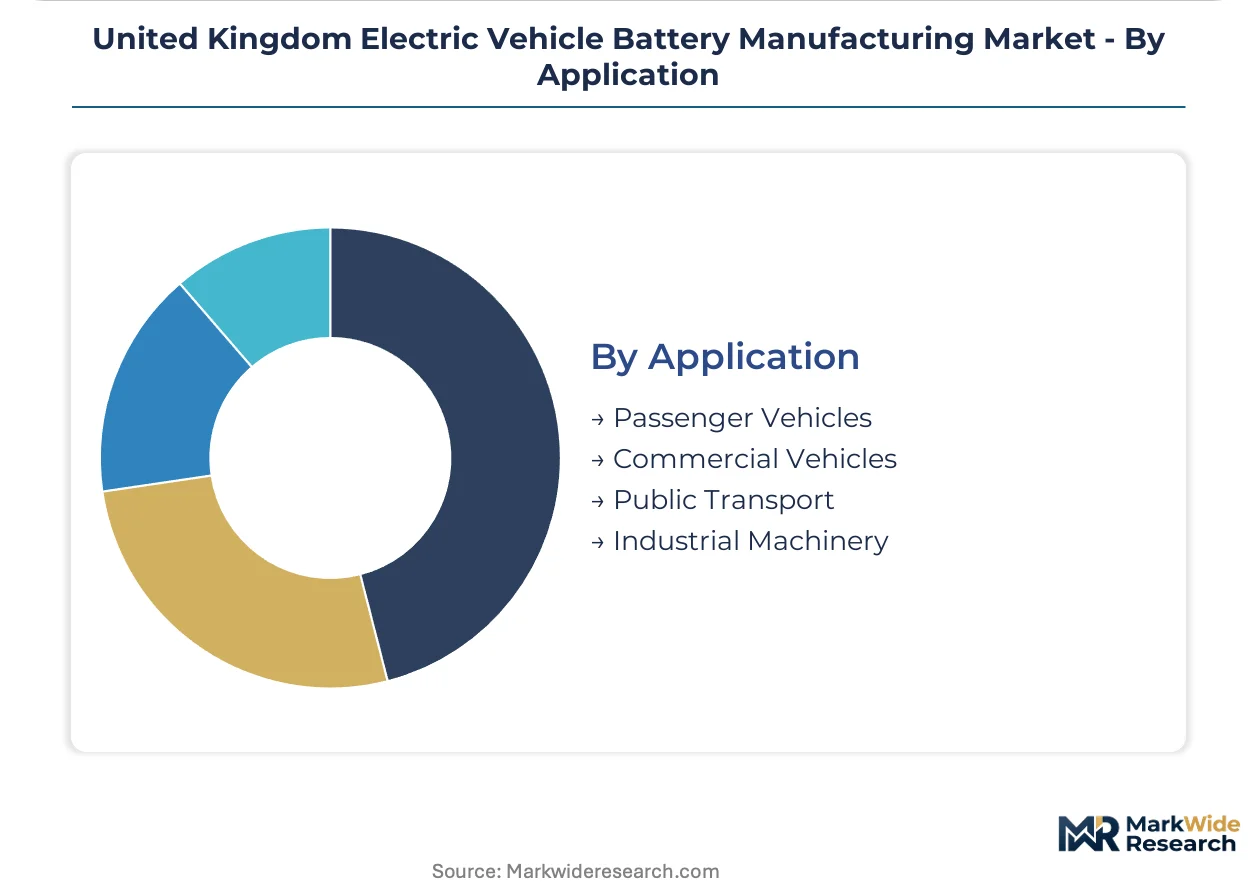
Application:
Duty cycle severity separates passenger vehicle energy density priorities from commercial vehicle cycle-life requirements.
- Passenger Vehicles:Premium and mass-market tiers demand competing cell architectures. Sunderland and Coventry production corridors serve this segment with divergent nickel-cobalt-manganese versus lithium-iron-phosphate strategies.
- Commercial Vehicles:High-cycle duty patterns favor AMTE Power's specialized architectures. Logistics electrification across Britain creates anchor demand for cells rated beyond 4,000 cycles.
- Public Transport:Bus depot charging infrastructure and opportunity charging protocols shape battery sizing. London and Birmingham municipal procurement drives standardization.
- Industrial Machinery:Forklift and port equipment electrification lags automotive timelines. Lower volumes fragment supplier attention.
Current capacity allocation favors passenger vehicles. Capacity expansion is gaining share fastest in commercial vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sunderland anchors UK battery production through Envision AESC's gigafactory footprint, while the Midlands corridor concentrates emerging cell assembly capacity near Jaguar Land Rover and commercial vehicle OEM programs.
England — Midlands
Coventry and Birmingham cluster around automotive OEM electrification timelines and Clean Air Zone enforcement for commercial fleets. The UK Department for Transport's ZEV mandate binds manufacturers to escalating EV quotas, pulling gigafactory investment toward the West Midlands manufacturing corridor.
England — North East
Sunderland's Nissan supply ecosystem and port infrastructure enable cathode material import and finished cell export logistics. The Automotive Transformation Fund conditions capital grants on local content thresholds, cementing the North East as Britain's highest-volume cell production node.
England — South East
Oxford and Milton Keynes concentrate solid-state R&D and battery management software development. BSI PAS 63119 certification requirements for battery passports favor integrated testing capabilities clustered near London's regulatory and financial infrastructure.
Scotland
The Scottish Highlands co-locate grid-scale storage with onshore wind generation, creating second-life revenue streams for retired automotive cells. Scottish Enterprise funding targets battery recycling and remanufacturing capabilities around Glasgow's industrial heritage zones.
Wales
South Wales hosts emerging cell component suppliers and materials processing operations feeding English gigafactories. The Welsh Government's Advanced Manufacturing Sector Deal prioritizes battery supply chain gaps in electrolyte formulation and separator production.
United Kingdom Electric Vehicle Battery Manufacturing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chemistry specialization and software integration depth. The UK market structures around three tiers: gigafactory-scale cell producers, high-power architecture specialists, and materials technology developers. Strategic archetypes include captive suppliers tied to OEM programs, independent cell producers serving fleet operators, and component innovators licensing intellectual property. Capacity expansion and strategic partnerships dominate competitive moves as firms secure offtake agreements before ZEV mandate penalties activate.
Within the gigafactory-scale tier, Envision AESC UK Ltd and Nissan Motor Manufacturing (UK) Ltd represent captive supply integration, while AMTE Power plc occupies a position among independent producers targeting commercial vehicle duty cycles. Nyobolt Ltd exemplifies the materials innovation archetype through its niobium anode specialization.
| Leading Market Players |
|---|
| Envision AESC UK Ltd |
| Agratas Energy Storage Solutions |
| Nissan Motor Manufacturing (UK) Ltd |
| AMTE Power plc |
| Nyobolt Ltd |
| LEAPENERGY |
| Nexeon |
| GS Yuasa |
| Johnson Matthey Battery Systems |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement departments consolidating battery sourcing through power purchase agreements anchor the dominant contract-based long-term offtake pricing model across UK cell production. This buyer concentration forces pricing discipline on gigafactory operators while creating volume commitments that lock in cathode material procurement schedules.
Pricing Analysis
Value-based pricing anchored to total cost of ownership outcomes dominates fleet operator negotiations, separating premium nickel-cobalt-manganese architectures from commodity lithium-iron-phosphate cells. Price differentiation rests on certification grade—BSI PAS 63119 compliance opens preferential EU-UK trade access—and volume scale, with multi-gigawatt-hour commitments commanding steeper discounts. Cost compression in the standard tier intensifies as Chinese cell imports pressure domestic margins. Fleet operators exhibit highest price sensitivity due to thin logistics margins, while premium automotive OEMs prioritize energy density and cycle-life guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers at Sunderland and the Midlands operate hub-and-spoke patterns feeding OEM assembly plants and fleet depots. Cathode active materials draw from Indonesian nickel and DRC cobalt nodes, while lithium hexafluorophosphate electrolyte feeds from Chinese refiners. Single-source vulnerability concentrates in electrolyte formulation, where domestic production capacity remains underdeveloped. Distribution runs through port-centric import corridors at Tyne and Tees, with finished cells moving via dedicated automotive logistics networks to Coventry and Birmingham manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK battery market sits in a technology-transition phase as dry electrode coating displaces solvent-based manufacturing, cutting energy intensity and factory footprints while accelerating throughput. Solid-state sulfide electrolyte R&D pipelines are advancing toward commercialization, threatening incumbent lithium-ion capacity investments with obsolescence risk.
For Market Incumbents: Extend BSI certification leadership into battery passport standards to lock in EU-UK trade corridor access before competitor compliance catches up. Secure captive cathode supply through backward integration into precursor processing or binding offtake with Indonesian and DRC mining consortia to hedge nickel-cobalt price volatility. Dry electrode pilot lines at Sunderland and Coventry must scale rapidly to maintain cost parity with Asian imports. For New Entrants and Emerging Players: Capture the sodium-ion stationary storage white space where lithium price hedging creates product differentiation against incumbent chemistries. Scottish Highlands grid-scale wind co-location offers the most penetrable geography for second-life automotive cell redeployment. A licensing-led go-to-market angle—partnering with British universities on sulfide electrolyte IP—sidesteps capital-intensive gigafactory construction. For Investors and Strategic Acquirers: The window for entry favors materials technology developers with niobium anode or silicon nanowire architectures that command premium automotive tier pricing. Long-term viability hinges on ZEV mandate enforcement trajectory and solid-state maturation timelines. Watch for UN 38.3 certification bottlenecks easing as testing capacity expands—this signal indicates OEM program launch acceleration and demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Manufacturing Scale-Up | Envision AESC Sunderland pilots cut energy intensity 30-40% while tightening particulate control standards. |
| BSI PAS 63119 Certification Investment | Early compliance opens preferential EU-UK trade access under post-Brexit rules of origin frameworks. |
| Cathode Precursor Backward Integration | Binding Indonesian nickel and DRC cobalt offtake hedges margin compression from supply node volatility. |
| Solid-State Sulfide Electrolyte R&D Partnership | British university pipelines target 400 Wh/kg thresholds with inherent flame resistance for premium tiers. |
| Scottish Highlands Second-Life Storage Deployment | Grid-scale wind co-location creates revenue streams for retired automotive cells nearing capacity fade. |
Research Methodology
Independent corroboration across OEM platform engineers, fleet procurement directors, and cell manufacturing executives underwrites the qualitative findings in this study. Primary interviews with Tier 1 supplier procurement leads, gigafactory operations managers, and BSI certification specialists combined with secondary validation from UK Department for Transport ZEV mandate filings, Automotive Transformation Fund disbursement records, and SEC 10-K disclosures from listed battery materials suppliers. Bottom-up capacity installation tallies and top-down OEM electrification commitment aggregates were reconciled to establish market sizing boundaries.
Rate-of-change decomposition across chemistry transitions, manufacturing process shifts, and regulatory enforcement timelines shaped the analytical framework. Segmentation dimensions modeled include product type, technology layer, end-user procurement pattern, and application duty cycle severity. CAGRs were derived from installed capacity buildout schedules against ZEV mandate compliance requirements. Forecast inputs incorporated cathode material cost trajectories from Indonesian and DRC supply nodes, plus dry electrode adoption curves at UK production facilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state technology maturation and post-Brexit trade rule evolution. Outputs reflect documented assumptions on ZEV mandate penalty enforcement, Chinese import tariff levels, and electrolyte supply diversification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
EV Batteries Market
EV Batteries
EV Battery Cells Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
North America Electric Vehicle Battery Anode Market