
 Oilfield Equipment Rental Services Market | 2026-2036
Oilfield Equipment Rental Services Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Equipment Rental Services Market Outlook
EPA methane performance standards is decoupling rental fleet renewal cycles from traditional capital expenditure timelines. Schlumberger Limited leverages its integrated drilling technology portfolio to bundle rental equipment with real-time analytics services. Baker Hughes Company anchors its position through proprietary drill bit and measurement-while-drilling systems paired with flexible rental terms. National Oilwell Varco dominates land rig rental markets through manufacturing scale that feeds captive refurbishment pipelines.
Oilfield equipment rental services encompass the short-term and long-term leasing of specialized drilling, production, and pressure-control apparatus rated for API specification 4F and 8C structural loads, typically deployed under day-rate or meterage contracts. These services eliminate capital lock-up for operators while ensuring access to assets certified under current blowout prevention and well control standards. Drilling Rigs command the largest share of rental revenue due to capital intensity and rapid technological obsolescence cycles. Offshore deployment represents the fastest-growing segment as deepwater projects in Brazil and West Africa favor rental models over owned fleet exposure. Short-Term Rental agreements concentrate margin pools around high-specification equipment during drilling campaign spikes.
OSHA process safety management requirements and BSEE well control rules mandate documented maintenance histories and recertification intervals that rental providers maintain as core competencies. The EPA's New Source Performance Standards for greenhouse gas emissions from oil and gas operations are reshaping equipment specifications, with compliant dual-fuel engines and vapor recovery units becoming standard rental offerings. Stakeholders must monitor how carbon border adjustment mechanisms in Europe and emerging methane intensity scoring in LNG offtake contracts redirect fleet investment toward lower-emission rental assets.
Market Dynamics
EPA methane performance standards are decoupling rental fleet renewal cycles from traditional capital expenditure timelines, forcing operators to access compliant equipment through rental channels rather than owned asset refurbishment. This regulatory pressure concentrates rental demand around certified low-emission rigs and dual-fuel systems.
Growth Catalysts
- EPA New Source Performance Standards:Methane emission limits are accelerating replacement of legacy owned equipment with certified rental assets that meet documented maintenance and recertification intervals.
- Pad drilling density economics:Multi-well pad development in the Permian Basin and Bakken formation justifies rental models over ownership through utilization rate optimization and logistics consolidation.
- Deepwater project exposure management:Offshore operators in Brazil and West Africa are limiting balance sheet risk through rental structures for subsea blowout preventers and managed pressure drilling systems.
Market Restraints
- Specialized steel alloy volatility:High-strength chromium-molybdenum steel prices for drill pipe and pressure-control equipment create margin compression during commodity spikes.
- Refurbishment pipeline concentration:Captive remanufacturing capabilities cluster in Houston-Gulf Coast corridors, creating geographic supply vulnerability for inland operators.
- API specification lag:Certification cycles for 16A blowout preventer stacks trail technological advancement in managed pressure drilling, limiting equipment interoperability.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU import tariffs on carbon-intensive goods are creating rental demand for methane-intensity-scored equipment serving LNG export projects.
- Real-time analytics bundling:Integration of measurement-while-drilling systems with rental day-rate contracts is unifying equipment access with performance optimization services.
- Geothermal energy crossover:Sedimentary heat extraction projects in Nevada and Utah are repurposing oilfield rental rigs for directional drilling in hard-rock formations.
Industry Challenges
- Blowout preventer technician scarcity:Deep expertise in subsea control system maintenance and API 53 pressure testing is concentrating among aging workforces in Gulf Coast hubs.
- Dual-fuel engine integration complexity:Field retrofitting of diesel-electric rigs for natural gas-diesel blends requires coordination between OEM control systems and rental fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Equipment Rental Services Market |
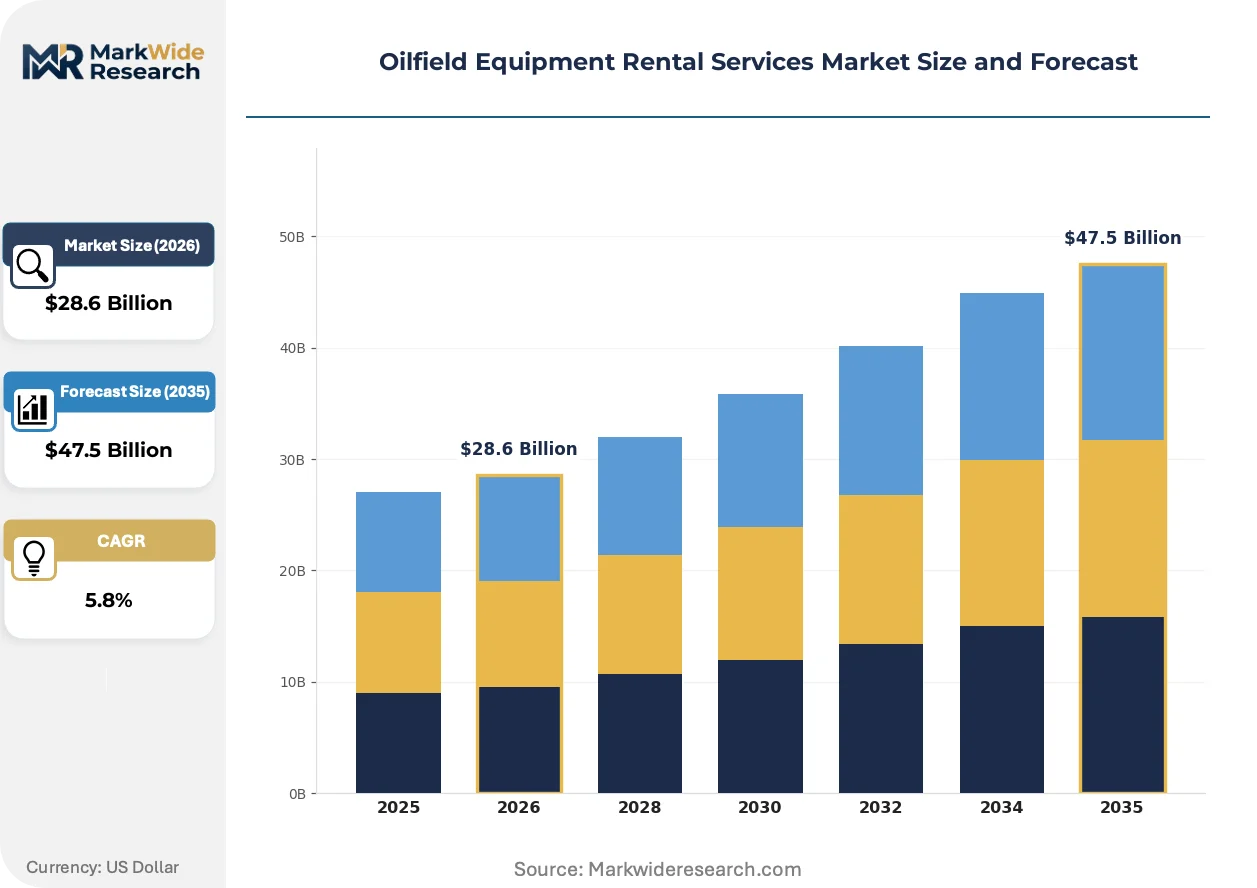
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Rigs, Pumping Units, Generators, Compressors End User: Oil & Gas Companies, Energy Producers, Drilling Contractors, Service Providers Deployment: Onshore, Offshore, Coastal, Deepwater Service Type: Short-Term Rental, Long-Term Rental, Maintenance Services, Logistics Support |
| Companies Covered | Weatherford International PLC, Transocean Ltd, Schlumberger Limited, Patterson-UTI Energy Inc., National Oilwell Varco, Baker Hughes Company, Superior Energy Services Inc., Ensign Energy Services Inc., Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Equipment Rental Services Market Strategic Shifts
Digital thread technologies are compressing the gap between physical asset deployment and performance accountability, enabling rental providers to monetize uptime guarantees rather than mere equipment availability. This shift redefines value capture in day-rate contracting structures.
Automated rig operating systems are unifying surface and downhole data streams into single control interfaces. Shale operators in the Permian Basin are deploying these integrated platforms across multi-rig campaigns to standardize drilling parameters and reduce non-productive time. The technology is unifying rental equipment provision with real-time operational decision support, compressing the traditional separation between asset supplier and drilling contractor functions.
EPA's methane performance standards are mandating continuous emissions monitoring and leak detection across all new and modified oil and gas facilities. Rental providers must now supply certified vapor recovery units and pneumatic controller retrofits as standard equipment configurations. The regulation most affects onshore production basins in Texas and North Dakota, where pad density concentrates monitoring obligations and rental fleets are being re-specified for compliance-ready deployment.
Consumption patterns are rotating toward meterage-based rental structures that tie payment to actual drilling progress rather than calendar day rates. Independent operators in the Appalachian Basin are adopting this model to align equipment costs with well completion timelines and reduce standby charges during weather delays. The shift is most visible among private equity-backed exploration companies managing tight capital deployment cycles and seeking to minimize committed fixed costs between drilling campaigns.
Oilfield Equipment Rental Services Market Segmentation
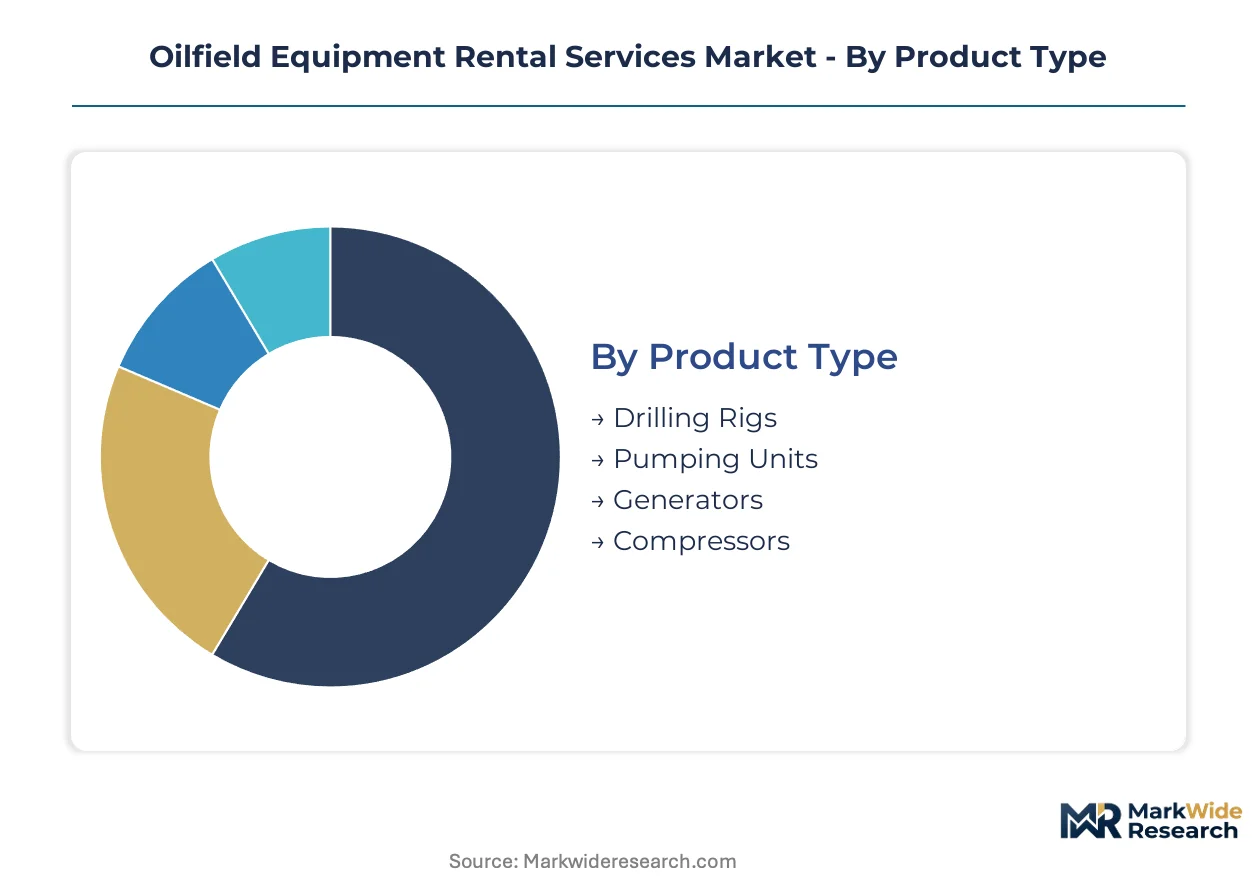
Equipment specification tiers determine rental economics across drilling campaigns. Operator capital constraints and regulatory compliance requirements reshape segment priorities continuously.
Product Type:
API specification ratings and structural load capacities differentiate rental fleet positioning across pressure-control applications.
- Drilling Rigs:Mobile and skid-mounted units rated for API 4F structural loads dominate rental revenue through capital intensity and rapid technology obsolescence cycles. Permian Basin shale operators deploy these assets for multi-well pad programs where utilization optimization justifies rental over ownership.
- Pumping Units:Beam pumps and hydraulic lift systems handle artificial lift operations in mature conventional fields. Bakken formation producers favor rental models for rod pump units during secondary recovery phases when production decline curves reduce capital commitment appetite.
- Generators:Diesel-electric and dual-fuel power modules supply rig site electricity with EPA New Source Performance Standards compliance. Bakken and Powder River Basin drilling sites specify these for emissions-scored equipment mandates.
- Compressors:Vapor recovery and gas lift compression units manage wellhead pressure and methane capture requirements. Gulf Coast operators rent these for continuous emissions monitoring obligations under evolving EPA frameworks.
Drilling Rigs leads on scale; Generators leads on momentum.
End User:
Capital deployment cycles and balance sheet risk tolerance segment rental demand across operator categories.
- Oil & Gas Companies:Integrated majors and independents access rental fleets to preserve liquidity for exploration budgets. Appalachian Basin private equity-backed operators concentrate here, favoring meterage-based contracts to align costs with drilling progress.
- Energy Producers:Power generation and midstream entities rent compression and processing equipment for infrastructure expansion. These customers prioritize long-term rental structures with embedded maintenance services.
- Drilling Contractors:Specialist firms supplement owned rig fleets with rental capacity during campaign spikes. West Africa and Brazil deepwater projects drive this segment through exposure management strategies.
- Service Providers:Completion and workover companies rent specialized pressure-control equipment for specific intervention jobs. Their demand concentrates around short-term agreements for high-specification blowout preventer stacks.
Oil & Gas Companies commands volume share; Drilling Contractors expands most quickly.
Deployment:
Water depth and logistical complexity determine rental contract structures and equipment specifications.
- Onshore:Land-based drilling and production equipment rentals dominate transaction volume through pad density economics. Texas and North Dakota basins concentrate this segment where logistics consolidation supports rental model viability.
- Offshore:Platform-based drilling systems and subsea equipment rentals limit balance sheet exposure for deepwater developments. Brazil's pre-salt fields and West African discoveries anchor this expanding category.
- Coastal:Shallow water jackup rig rentals and platform supply vessel equipment serve shelf developments. Gulf of Mexico operators deploy these assets for marginal field redevelopment programs.
- Deepwater:Managed pressure drilling systems and subsea blowout preventers rated for extreme pressure environments command premium rental rates. This segment climbs the fastest as pre-salt and ultra-deepwater projects proliferate.
Onshore leads on scale; Deepwater leads on momentum.
Service Type:
Contract duration and value-added bundling reshape margin capture across rental providers.
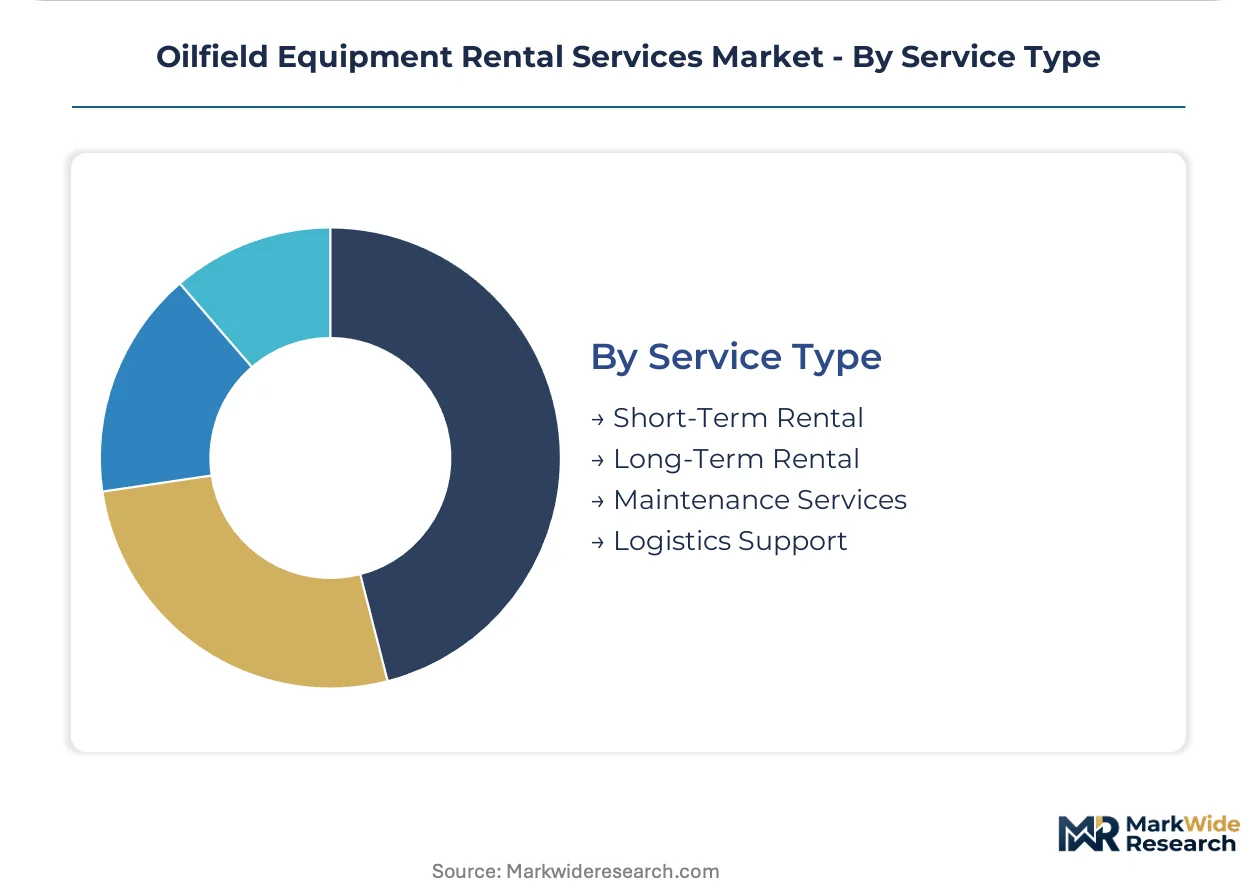
- Short-Term Rental:Day-rate and meterage agreements for campaign-specific equipment needs concentrate margin pools around high-specification assets during drilling spikes. Appalachian independents favor this structure to minimize committed fixed costs between campaigns.
- Long-Term Rental:Multi-year agreements with embedded maintenance and recertification services suit infrastructure-scale compression and power generation. Midstream operators in the Permian Basin anchor demand here.
- Maintenance Services:OSHA process safety management and BSEE well control compliance documentation bundled with rental contracts. Aging workforces in Gulf Coast hubs concentrate this specialized service capability.
- Logistics Support:Transportation, rig-up, and site preparation services bundled with equipment delivery. Houston-Gulf Coast corridors dominate this function through captive refurbishment pipeline proximity.
Short-Term Rental leads on scale; Maintenance Services leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled blowout preventer technicians and subsea control specialists concentrate in Houston-Gulf Coast corridors, anchoring regional rental service capabilities. Their expertise shapes where rental fleets deploy and how maintenance networks organize geographically.
United States
Permian Basin shale operators drive demand for multi-well pad drilling rigs and dual-fuel generator rentals. EPA New Source Performance Standards mandate methane-compliant equipment configurations across Texas and North Dakota production sites. Houston-Gulf Coast corridors host captive refurbishment pipelines that feed inland rental logistics.
Brazil
Pre-salt deepwater developments favor rental structures for managed pressure drilling systems and subsea blowout preventers. The national petroleum regulator ANP imposes local content requirements that shape foreign equipment rental terms. Macaé and Rio de Janeiro anchor offshore service clusters where rental providers co-locate with drilling contractors.
Norway
North Sea electrification projects and mature field redevelopment sustain demand for platform-based drilling rentals. The Norwegian Petroleum Safety Authority mandates continuous emissions monitoring that accelerates low-emission equipment replacement cycles. Stavanger and Bergen concentrate subsea technology expertise and rental fleet maintenance capabilities.
United Arab Emirates
Adnoc's expansion programs and third-party offshore concessions drive rental demand for high-specification land rigs and workover equipment. The Supreme Council for Financial and Economic Affairs oversees energy sector procurement frameworks that influence rental contract structures. Abu Dhabi and Dubai host regional headquarters for international rental providers serving Gulf Cooperation Council markets.
Saudi Arabia
Aramco's gas development initiatives and unconventional resource programs expand rental fleet deployment for directional drilling campaigns. The Ministry of Energy's In-Kingdom Total Value Add program shapes local partnership requirements for equipment suppliers. Dhahran and the Eastern Province concentrate drilling contractor operations and rental equipment staging yards.
Oilfield Equipment Rental Services Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: integrated oilfield services conglomerates with captive manufacturing, pure-play rental specialists with logistics scale, and regional fabricators with refurbishment expertise. Consolidation pressures favor players with backward integration into high-strength steel supply chains and captive remanufacturing pipelines. Geographic expansion and technology licensing dominate competitive moves as operators seek compliant equipment across dispersed basins.
Within the integrated services tier, Schlumberger Limited and Baker Hughes Company represent archetypes of technology-forward rental bundling with real-time analytics capabilities. National Oilwell Varco exemplifies manufacturing-scale players leveraging captive refurbishment pipelines for land rig rental dominance. Patterson-UTI Energy Inc. anchors the North American pure-play specialist position. These three entities collectively illustrate how competitive positioning stratifies across technology integration, manufacturing depth, and regional logistics scale.
| Leading Market Players |
|---|
| Weatherford International PLC |
| Transocean Ltd |
| Schlumberger Limited |
| Patterson-UTI Energy Inc. |
| National Oilwell Varco |
| Baker Hughes Company |
| Superior Energy Services Inc. |
| Ensign Energy Services Inc. |
| Halliburton Company |
| Others |
Value Chain & Pricing Dynamics
Dual-fuel engine retrofits and automated rig operating systems are compressing cost structures while concentrating procurement power among rental providers with captive refurbishment pipelines. This technological transition simultaneously lowers per-day operating expenses and reinforces geographic supply clustering around Houston-Gulf Coast corridors.
Pricing Analysis
Bundled day-rate contracts with embedded maintenance services command premium positioning against unbundled equipment-only rentals. Pricing stratifies across API certification tiers, with 16A blowout preventer stacks and managed pressure drilling systems capturing margin premiums over standard land rigs. Cost compression in standard drilling equipment intensifies as shale operators consolidate procurement volumes across multi-well pad programs. Private equity-backed independents in the Appalachian Basin exhibit highest price sensitivity, while deepwater operators in Brazil prioritize compliance-ready specifications over rate negotiation.
Supply Chain Analysis
Single-source vulnerability sits with high-strength chromium-molybdenum steel suppliers concentrated in Germany, Japan, and South Korea. Manufacturing draws from specialized alloy foundries, OEM control system providers, and API-certified inspection facilities. Tariff exposure on specialty steel imports creates margin volatility for pressure-control equipment fabricators. Distribution runs through Houston-Gulf Coast staging yards that feed inland logistics networks via rail and heavy-haul trucking corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates around compliant equipment premiums and meterage-based contract structures that align rental economics with operator drilling efficiency. EPA methane performance standards and carbon border adjustment mechanisms are shifting procurement toward certified low-emission assets.
For Market Incumbents: Deepen backward integration into high-strength steel supply chains to offset alloy price volatility eroding pressure-control equipment margins. Expand captive refurbishment pipeline capacity in the Permian Basin to reduce logistics costs for pad drilling operators. Defend against pure-play specialists by bundling real-time analytics with rental day-rates. For New Entrants and Emerging Players: Launch via geothermal energy crossover applications in Nevada and Utah, repurposing oilfield rental rigs for hard-rock directional drilling where competition remains sparse. Target short-term rental agreements for high-specification blowout preventer stacks during Appalachian Basin drilling campaign spikes. Build go-to-market around maintenance service capabilities to capture OSHA process safety management documentation demand. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with refurbishment expertise but lacking integrated analytics bundling. Five-to-ten year viability hinges on dual-fuel fleet conversion completion and methane intensity scoring adoption in LNG offtake contracts. Monitor EPA enforcement patterns on legacy equipment grandfathering as the inflection signal for accelerated rental fleet renewal cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Fleet Conversion | EPA New Source Performance Standards compliance positions rental assets for methane-scored LNG export contracts. |
| Meterage-Based Contract Expansion | Appalachian Basin independents align equipment costs with actual drilling progress, reducing standby exposure. |
| Geothermal Equipment Repurposing | Nevada and Utah heat extraction projects diversify revenue beyond hydrocarbon drilling cycles. |
| Real-Time Analytics Bundling | Schlumberger and Baker Hughes unify equipment access with measurement-while-drilling performance optimization. |
| Captive Refurbishment Pipeline Expansion | National Oilwell Varco leverages manufacturing scale to compress land rig rental turnaround times. |
Study Parameters
Bottom-up drilling campaign modeling reconciled against top-down rental fleet capacity tracking forms the analytical core of this study. Primary interviews with drilling contractors, equipment procurement managers at shale operators, maintenance directors at Gulf Coast service hubs, and EPA compliance officers combined with secondary validation from BSEE well control filings, SEC 10-K equipment disclosure segments, and API certification registries. Triangulation across these sources anchors volume estimates to actual rig deployment patterns.
Historical trendline analysis of rental day-rate movements and fleet utilization rates established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated equipment specification tiers, contract duration structures, deployment water depth categories, and regional regulatory frameworks. CAGR derivation weighted near-term EPA compliance deadlines against longer-term shale resource exhaustion curves and deepwater project sanctioning timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price collapse scenarios or accelerated electrification mandates. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity between rental and ownership models. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Slickline Services Market
Oil & Gas
Southeast Asia Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Egypt Oil and Gas Market