
 Heat Pump (>100°C) Market | 2026-2036
Heat Pump (>100°C) Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Pump (>100°C) Market Insights
The capital-intensity gap between integrated system builders and component assemblers is collapsing as modular high-temperature heat pump platforms commoditize core compressor and heat exchanger designs. Siemens Energy leverages its turbomachinery heritage to dominate large-scale industrial installations above 150°C. GEA Group Aktiengesellschaft anchors European process heating retrofits with customized ammonia-based systems for food and chemical plants. Panasonic Holdings Corporation competes through compact vapor compression units targeting Asian manufacturing facilities with space-constrained boiler rooms.
Heat pumps exceeding 100°C deliver thermal energy through vapor compression, absorption, or thermoelectric cycles using specialized refrigerants or working fluids rated for elevated temperature lifts, typically achieving coefficient of performance values between two and four depending on source temperature and lift requirements. These systems primarily displace fossil fuel combustion in industrial drying, pasteurization, sterilization, and district heating networks where conventional heat pumps fail to reach required process temperatures. Air source configurations lead current installations due to lower infrastructure requirements, though water source systems represent the fastest-growing category as industrial facilities exploit adjacent wastewater or cooling water streams for improved efficiency. Among end user verticals, manufacturing occupies the deepest margin pools because energy-intensive processes justify premium system pricing through operating cost reductions.
The EU F-Gas Regulation and Ecodesign Directive jointly constrain refrigerant selection and minimum efficiency standards for high-temperature heat pumps sold across member states, while EPA SNAP program rules in the United States restrict high-GWP alternatives in industrial applications. Japan's METI Top Runner program establishes escalating efficiency benchmarks that shape product development priorities for export-oriented manufacturers. Stakeholders must monitor refrigerant phase-down schedules and carbon border adjustment mechanisms to align procurement timelines with compliance windows and avoid stranded equipment investments.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choice windows and forcing simultaneous redesigns of compressor architecture and heat exchanger materials across all system tiers.
Growth Catalysts
- Industrial Decarbonization Mandates:Germany's hydrogen-ready heating infrastructure law requires fossil fuel boiler replacements in process plants, creating immediate demand pull for ammonia-based high-temperature systems.
- Waste Heat Recovery Economics:Food and beverage facilities adjacent to municipal wastewater treatment plants exploit thermal energy from effluent streams, cutting source temperature differentials and improving coefficient of performance.
- REACH Compliance Deadlines:The European Chemicals Agency's phased restrictions on high-GWP synthetic refrigerants accelerate engineering investment in natural working fluid architectures.
Market Restraints
- Copper and Rare Earth Input Volatility:Permanent magnet synchronous motors for high-speed compressors depend on neodymium supply concentrated in Chinese processing facilities.
- Refrigerant Patent Thickets:Honeywell and Chemours hold blocking positions on hydrofluoroolefin formulations suitable for 120°C+ lifts, forcing licensing negotiations or costly workarounds.
- Grid Capacity Constraints:Rural industrial zones in Eastern Europe lack substation headroom for megawatt-scale heat pump electrification, delaying project timelines.
Strategic Opportunities
- Pulp and Paper Integration:Scandinavian mills with on-site biomass boilers seek heat pump topping cycles to reach 150°C drying temperatures without additional combustion.
- Carbon Border Adjustment Mechanism:The EU CBAM's phased implementation creates cost pressure on imported processed goods, incentivizing domestic facility retrofits with electrified process heat.
- Absorption-Compression Hybrids:Pairing thermal-driven absorption stages with electric vapor compression unlocks ultra-high temperature delivery for chemical reactor feed preheating.
Industry Challenges
- Thermofluid Engineering Talent Gap:Fewer than two dozen European universities train specialists in transcritical CO2 and ammonia system design, constraining manufacturer hiring pipelines.
- Legacy Control System Integration:Brownfield chemical plants operate 1980s-era distributed control systems lacking digital interfaces for variable-speed heat pump modulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Pump (>100°C) Market |
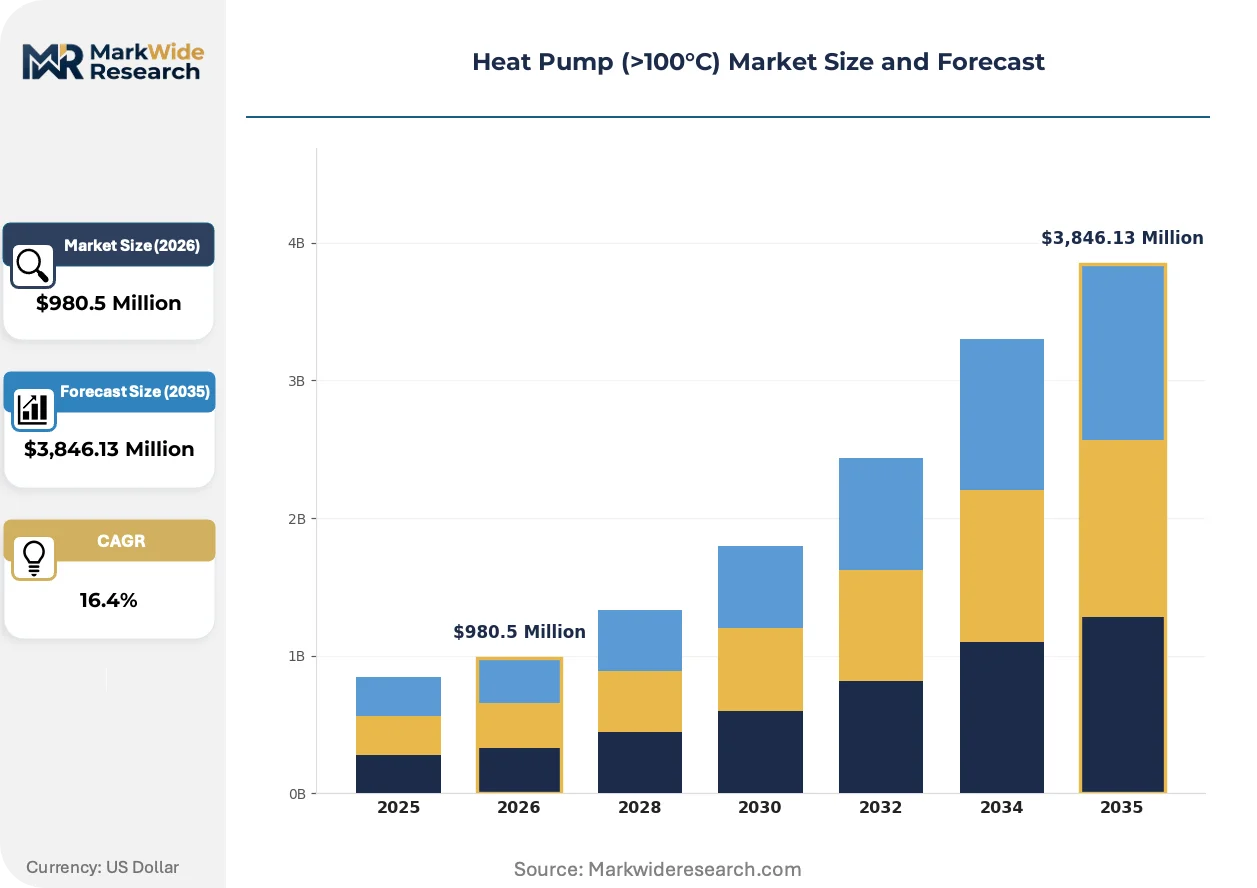
| Market Size in 2026 | $980.5 Million |
| Market Size in 2035 | $3,846.13 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Water Source, Ground Source, Hybrid System Application: Industrial Heating, Residential Heating, Commercial Heating, District Heating Technology: Vapor Compression, Adsorption, Absorption, Thermoelectric End User: Manufacturing, Hospitality, Education, Healthcare |
| Companies Covered | Siemens Energy, GEA Group Aktiengesellschaft, Johnson Controls, Panasonic Holdings Corporation, Mitsubishi Electric Corporation, Danfoss, Denso, Hitachi, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Pump (>100°C) Market Trends and Innovations
Refrigerant chemistry and turbomachinery design are converging to push practical temperature ceilings past 150°C while maintaining viable efficiency metrics.
Transcritical CO2 cycles with custom-designed two-stage centrifugal compressors are supplanting conventional HFC-based systems in European district heating networks. Municipal utilities in Denmark and Germany deploy these units for 90°C supply temperatures with 110°C peak capability. The shift is compressing equipment supplier margins as compressor platforms commoditize.
The EPA SNAP program's latest rulemaking restricts unsaturated HFC blends above specific GWP thresholds in industrial applications. Equipment manufacturers face reformulation deadlines that collide with product certification cycles. Process heating OEMs are responding by accelerating ammonia architecture development for North American food processing corridors.
Energy service companies now bundle heat pump installation with guaranteed thermal output contracts, transferring operational risk from capital-constrained manufacturers. This model disrupts traditional equipment-only sales channels in the Benelux region. Chemical processors in the Port of Rotterdam cluster increasingly specify performance-based procurement for 120°C+ process steam replacement projects.
Heat Pump (>100°C) Market Segmentation
High-temperature heat pump procurement channels diverge sharply by thermal duty and infrastructure constraints. Equipment specification, installation complexity, and refrigerant handling requirements reshape how each segment reaches end-users.
Product Type:
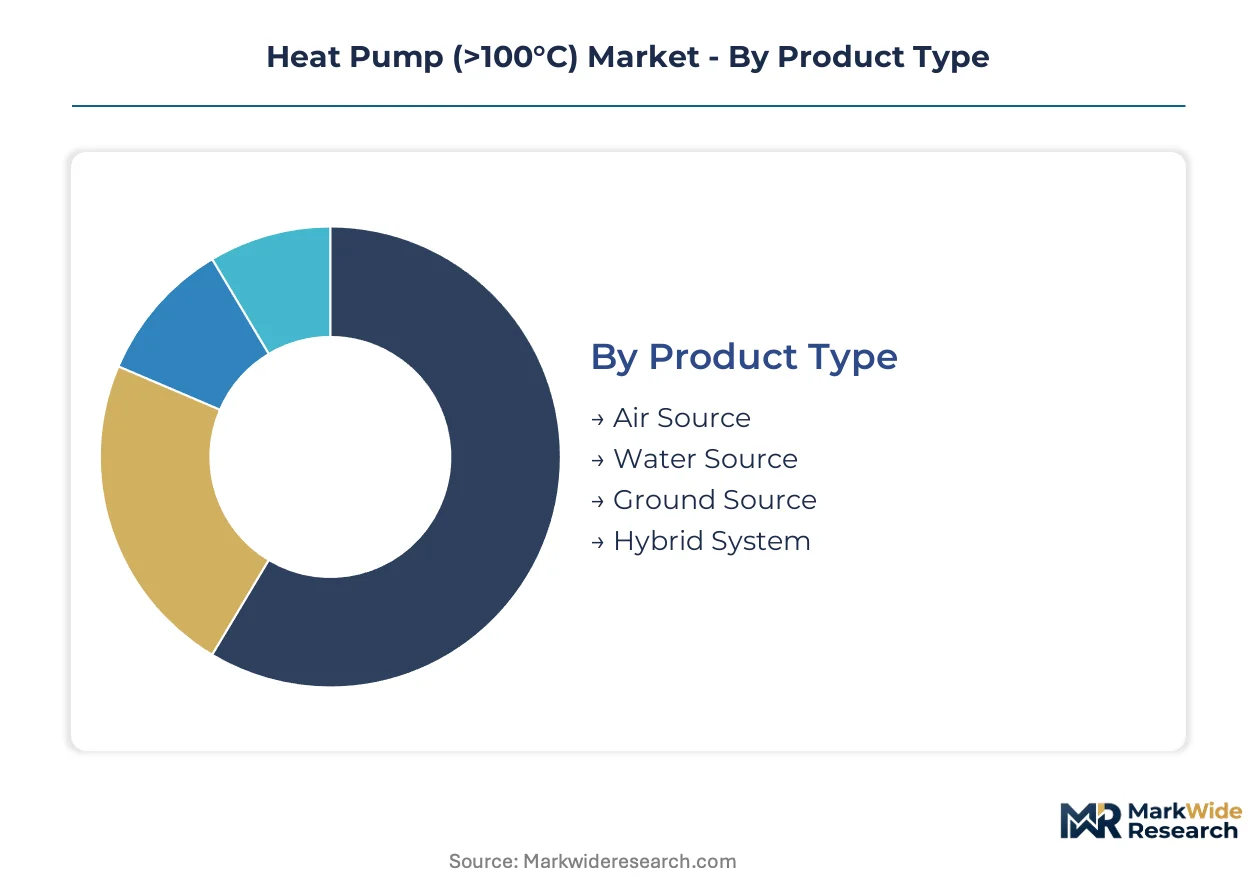
Air source units move through HVAC distributors and mechanical contractors with minimal site engineering. Water source systems require specialized energy service companies capable of hydronic integration and wastewater permitting.
- Air Source:Ambient air harvesters dominate retrofit installations where geothermal drilling or water rights prove impractical. German food processors in Stuttgart and Munich industrial parks specify these for 90-110°C pasteurization loops to satisfy hydrogen-ready heating mandates without civil works.
- Water Source:Adjacent effluent or cooling water exploitation delivers superior coefficient of performance. Danish district heating utilities in Aarhus and Odense deploy these for 115°C supply temperatures, leveraging harbor water thermal mass.
- Ground Source:Borefield-dependent systems suit greenfield chemical campuses with multi-decade operational horizons.
- Hybrid System:Dual-source architectures buffer seasonal efficiency swings for Nordic pulp mills.
By volume, air source leads. By growth pace, water source is ahead.
Application:
Cost tier stratification separates premium industrial process heat from standardized building services. District heating commands system-level pricing with 20-year performance guarantees.
- Industrial Heating:Process steam replacement and drying applications above 120°C demand custom ammonia architectures. Rotterdam chemical corridor facilities specify these for reactor feed preheating under EU ETS compliance pressure.
- District Heating:Municipal utility procurement bundles compressor platforms with thermal storage. Copenhagen and Hamburg networks integrate transcritical CO2 units for 90°C baseload with 110°C peaking capability.
- Commercial Heating:Hotels and office complexes favor packaged units below 500kW thermal output.
- Residential Heating:Single-family and small multi-family buildings rarely exceed 100°C requirements.
Industrial heating captures margin concentration. District heating shows steepest expansion trajectory.
Technology:
Maturity curves separate proven vapor compression from emerging thermoelectric alternatives. Patent thickets around HFO refrigerants accelerate natural working fluid development.
- Vapor Compression:Centrifugal and screw compressor architectures deliver 150°C+ with two-stage staging. Siemens Energy turbomachinery dominates large-scale deployments across German automotive paint shops.
- Absorption:Thermal-driven cycles pair with waste heat or biomass boilers for topping duty. Finnish pulp mills combine these with existing bark-fired boilers to reach 160°C drying temperatures without additional combustion.
- Adsorption:Silica gel and zeolite systems suit low-grade heat recovery below 80°C source temperature.
- Thermoelectric:Solid-state heat pumping remains laboratory-scale for elevated temperature lifts.
Vapor compression holds installed base dominance. Absorption gains share fastest in biomass-integrated applications.
End User:
Customer type dictates specification intensity and service contract structures. Manufacturing verticals justify dedicated engineering support; institutional buyers prioritize standardized maintenance agreements.
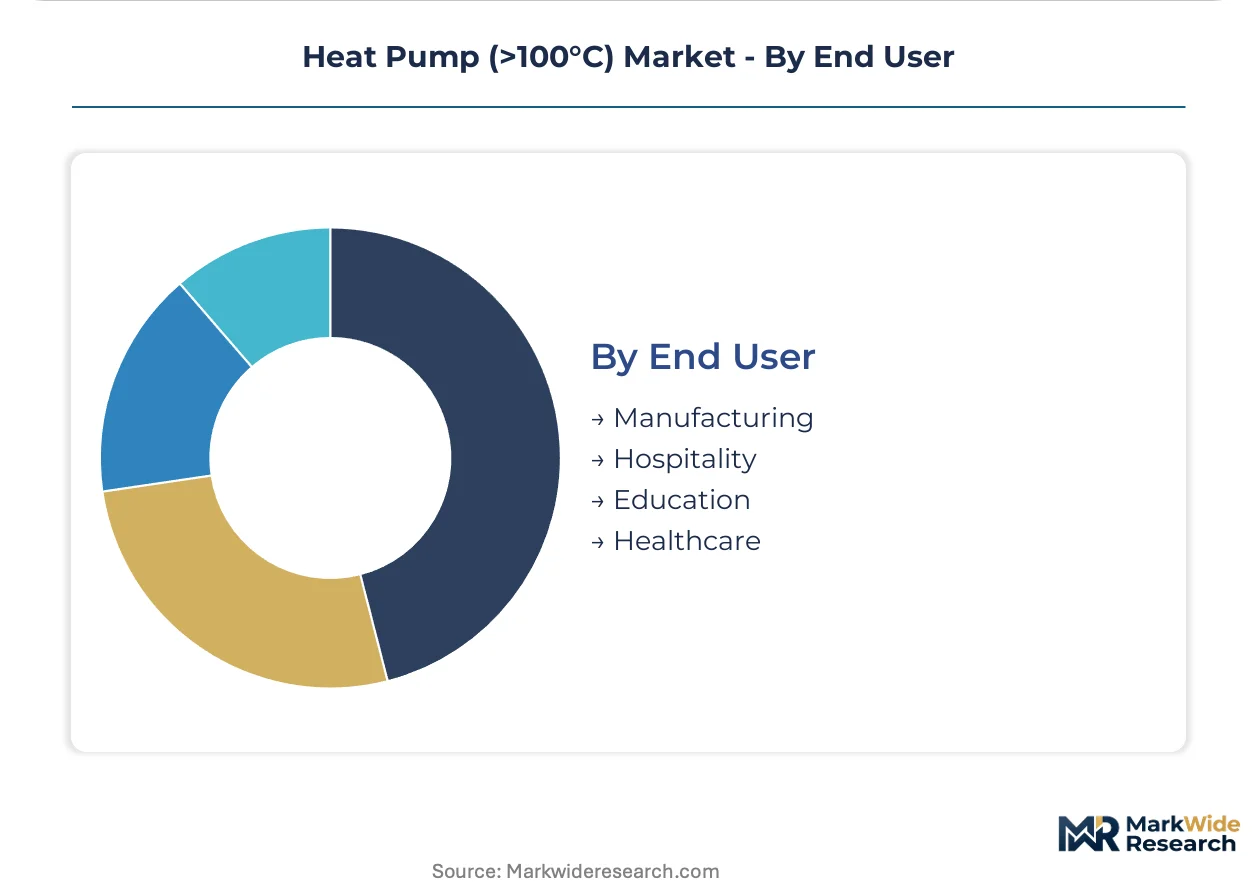
- Manufacturing:Energy-intensive processes with continuous thermal demand justify premium system pricing through operating cost reductions. Dutch food processors in the Port of Rotterdam cluster specify ammonia-based 120°C+ systems for sterilization and evaporation duties.
- Hospitality:Hotels and resorts require compact footprints for laundry and kitchen steam replacement.
- Healthcare:Hospital sterilization departments demand redundant capacity and pharmaceutical-grade control documentation.
- Education:University campuses favor hybrid geothermal-electric systems with visible sustainability credentials.
Manufacturing leads procurement volume. Healthcare shows tightest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Denmark absorb premium pricing for ammonia-based systems with minimal price elasticity, while facilities in Eastern Europe and parts of Asia demonstrate acute sensitivity to capital expenditure thresholds. This demand-elasticity contrast shapes regional deployment patterns and supplier market entry strategies.
Germany
Automotive paint shops and food processing plants in Stuttgart and Munich drive concentrated demand for 150°C+ vapor compression systems. The national hydrogen-ready heating infrastructure law mandates fossil fuel boiler replacements, accelerating procurement timelines. Siemens Energy leverages its turbomachinery heritage to dominate large-scale industrial installations across the Baden-Württemberg manufacturing corridor.
Denmark
Municipal district heating utilities in Copenhagen, Aarhus, and Odense exploit harbor water thermal mass for transcritical CO2 systems reaching 115°C supply temperatures. The Danish Energy Agency's efficiency benchmarking programs exceed EU Ecodesign minima, compressing equipment supplier margins. Copenhagen's district heating network integrates thermal storage with compressor platforms for 90°C baseload and 110°C peaking capability.
Netherlands
Chemical processors in the Port of Rotterdam cluster specify ammonia-based 120°C+ systems for reactor feed preheating under EU ETS compliance pressure. REACH phased restrictions on high-GWP synthetic refrigerants accelerate engineering investment in natural working fluid architectures. Rotterdam facilities increasingly specify performance-based procurement for process steam replacement projects.
Japan
Compact vapor compression units target space-constrained boiler rooms in Osaka and Nagoya manufacturing facilities. METI's Top Runner program establishes escalating efficiency benchmarks that shape product development priorities for export-oriented manufacturers. Panasonic Holdings Corporation competes through standardized platforms optimized for Asian facility footprints.
United States
Food processing corridors in California and the Midwest face EPA SNAP program restrictions on unsaturated HFC blends above specific GWP thresholds. Equipment manufacturers navigate reformulation deadlines that collide with product certification cycles. Process heating OEMs accelerate ammonia architecture development for North American installations.
Heat Pump (>100°C) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with turbomachinery specialists commanding premium pricing for 150°C+ industrial applications while Asian manufacturers compete on compact footprints and standardized platforms. The vendor base separates into three tiers: integrated system builders with compressor manufacturing heritage, component assemblers sourcing from commoditized platforms, and energy service companies bundling installation with performance guarantees. Dominant competitive moves include strategic partnerships between equipment OEMs and municipal utilities for district heating concessions, plus technology licensing arrangements that circumvent refrigerant patent thickets.
Among European integrated specialists, Siemens Energy and GEA Group Aktiengesellschaft exemplify the technology-leadership archetype through turbomachinery and customized ammonia system capabilities. Panasonic Holdings Corporation occupies a position within the compact-platform tier, targeting space-constrained Asian manufacturing facilities. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across the temperature-lift spectrum.
| Leading Market Players |
|---|
| Siemens Energy |
| GEA Group Aktiengesellschaft |
| Johnson Controls |
| Panasonic Holdings Corporation |
| Mitsubishi Electric Corporation |
| Danfoss |
| Denso |
| Hitachi |
| Bosch |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance gates both supplier qualification and price differentiation simultaneously, forcing equipment OEMs to absorb certification costs for natural refrigerant architectures while commanding premiums for ammonia-based systems rated above 120°C. Buyers in Germany and Denmark absorb these premiums with minimal elasticity, while Eastern European facilities demonstrate acute capital expenditure sensitivity that compresses margins for standardized platforms.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers drive lifetime value capture for installed base monetization. Three-tier pricing structure across premium, standard, and economy levels separates ammonia-based custom systems from packaged HFO units and compact Asian platforms. Price differentiation hinges on certification grade for EU Ecodesign compliance and geographic delivery cost for remote industrial zones. Cost compression in mid-tier vapor compression is intensifying because transcritical CO2 compressor platforms are commoditizing. Manufacturing verticals show least price sensitivity; hospitality and education segments demonstrate highest.
Supply Chain Analysis
China and Japan anchor permanent magnet synchronous motor production for high-speed compressors, while Germany concentrates precision heat exchanger manufacturing. Neodymium supply draws from Chinese processing facilities; specialized aluminum alloys for transcritical CO2 systems rest on European smelter capacity. Single-source vulnerability in rare earth magnet supply creates exposure to export restriction risk. Distribution runs through energy service companies bundling installation with performance guarantees in the Benelux region, HVAC distributors for standardized air source units, and direct OEM engagement for large industrial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial decarbonization mandates are disrupting fossil fuel boiler incumbents, with the EU ETS carbon price mechanism creating irreversible substitution economics for electrified process heat above 100°C.
For Market Incumbents: Secure ammonia architecture patent positions before REACH phase-down deadlines eliminate HFO alternatives. Defend installed base through captive service contracts and backward integration into compressor manufacturing. Siemens Energy's turbomachinery dominance in German automotive paint shops exemplifies channel control leverage against emerging Asian competitors. For New Entrants and Emerging Players: CE marking fast-track for transcritical CO2 systems below 500kW opens white-space in Nordic district heating retrofits. Target water source configurations for Dutch food processors adjacent to municipal wastewater plants. Pursue performance-based procurement contracts that transfer operational risk from capital-constrained buyers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular high-temperature heat pump platforms as compressor designs commoditize. Five-to-ten year viability favors energy service companies with guaranteed thermal output contract books over pure-play equipment manufacturers. Watch EU CBAM implementation pace as signal for accelerated domestic facility retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Architecture Development | REACH compliance deadlines force natural refrigerant engineering investment ahead of HFO phase-down. |
| Performance-Based Procurement | Rotterdam chemical processors increasingly specify guaranteed thermal output contracts for 120°C+ steam replacement. |
| Backward Integration into Compressors | Siemens Energy leverages turbomachinery heritage to capture margin pools in 150°C+ industrial applications. |
| District Heating Concession Partnerships | Copenhagen and Hamburg municipal utilities bundle thermal storage with compressor platforms for baseload-peaking configurations. |
| Water Source System Deployment | Danish utilities in Aarhus exploit harbor water thermal mass for superior coefficient of performance at 115°C supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, energy service company project developers, OEM procurement teams, and aftermarket service heads. Secondary validation drew from SEC filings of listed industrial equipment manufacturers, ECHA REACH restriction timelines, EU ETS carbon price data, and FERC interconnection queue records for industrial electrification projects. Bottom-up installation tracking across German federal states and Danish municipalities triangulated against top-down equipment production estimates from compressor and heat exchanger suppliers.
Across the analysis window, the forecasting framework modeled vapor compression, absorption, and hybrid technology penetration by application temperature tier, source configuration type, and end-user vertical. CAGRs were derived from segment-level build-ups reflecting industrial decarbonization policy intensity, refrigerant transition timelines, and grid capacity expansion rates. Key inputs included EU F-Gas Regulation phase-down schedules, hydrogen-ready heating infrastructure mandate compliance deadlines, and carbon border adjustment mechanism implementation stages.
Underlying assumptions cover sustained EU ETS price elevation and rare earth magnet supply continuity, with deviation risk concentrated in grid interconnection delays for rural industrial zones and refrigerant patent litigation outcomes. Recalibration cycles align with material shifts in EU regulatory enforcement, neodymium export policy, and municipal utility procurement award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Air-Cooled Gas Coolers Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Cold Trap Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
United States Heat Pump Market