
 Temporary Power and Cooling Solutions Market | 2026-2036
Temporary Power and Cooling Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Temporary Power and Cooling Solutions Market Insights
Multi-source equipment procurement is rebalancing toward hybrid rental-own models as capital discipline tightens across energy-intensive sectors. Aggreko leverages its distributed fleet network to anchor emergency response contracts across utility and industrial accounts. United Rentals competes through scale advantages in construction-adjacent cooling deployments. Caterpillar sustains manufacturing depth in mobile generator sets, giving it channel control over dealer-serviced rental programs.
Temporary power and cooling solutions encompass mobile diesel and natural gas generator sets, trailer-mounted chillers, and modular air handling units rated from 20 kW to 2,000-plus kW for power and 10 to 1,500-plus tons for cooling, designed for rapid deployment without permanent infrastructure. These systems serve critical functions during planned maintenance, grid instability, and thermal emergencies where fixed plant capacity proves inadequate or unavailable. Generator rental services dominate value capture given asset intensity and fuel logistics complexity, while data center end users represent the fastest-expanding demand pool as hyperscalers add redundant cooling for peak-load events. Installation services across temporary sites retain thinner margins but lock in recurring maintenance revenue streams.
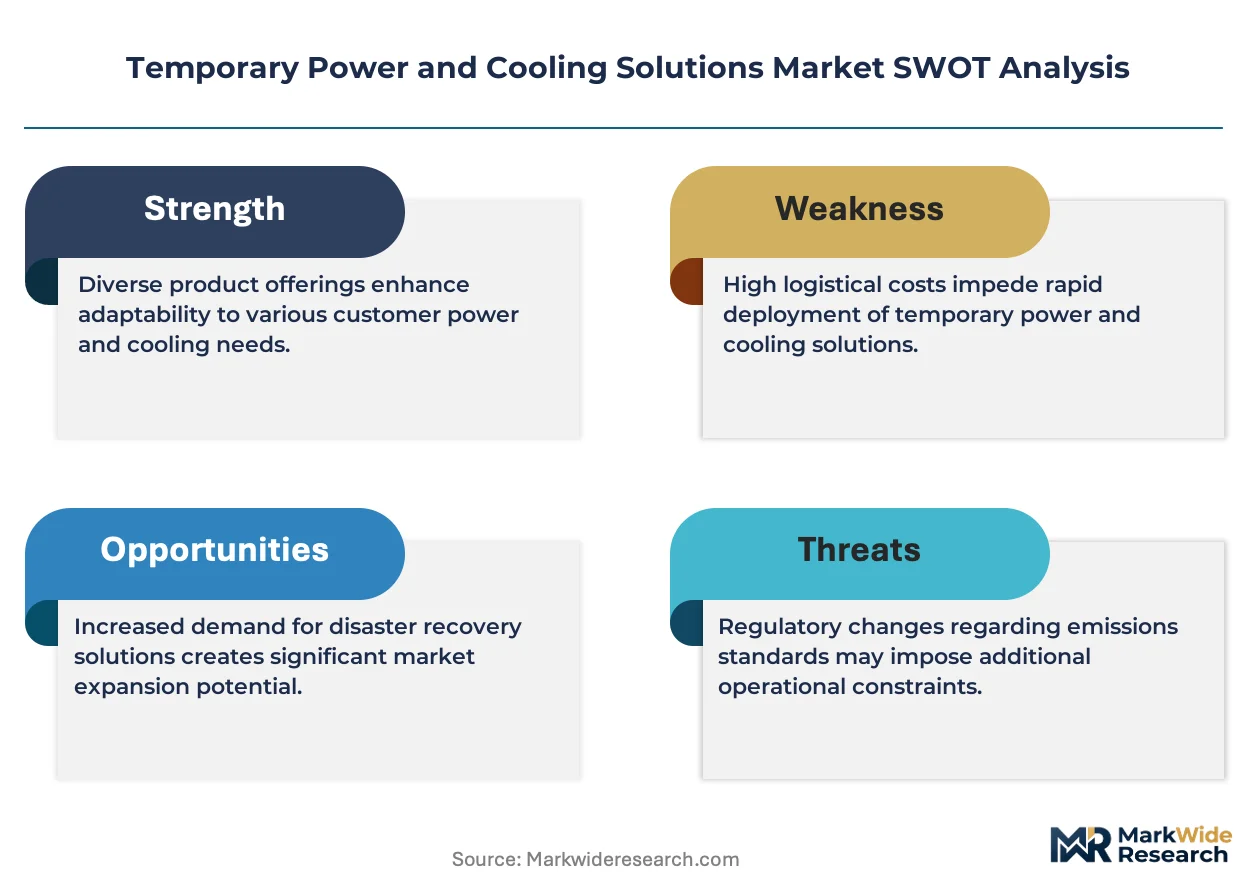
EPA Tier 4 Final standards and OSHA workplace noise regulations constrain diesel generator specifications, elevating compliance costs for rental fleet operators and filtering smaller service providers from utility-scale tenders. The EU F-Gas Regulation and REACH chemical protocols similarly reshape chiller refrigerant choices and thermal fluid handling practices across European deployments. Stakeholders must monitor evolving carbon border mechanisms and grid interconnection queues to calibrate fleet composition between fossil-fueled and battery-hybrid temporary power architectures.
Market Dynamics
Hybrid rental-own procurement models are rebalancing fleet economics as capital discipline tightens across energy-intensive sectors, forcing operators to optimize asset utilization against EPA Tier 4 Final compliance costs.
Growth Catalysts
- Data center thermal redundancy:Hyperscalers deploy trailer-mounted chillers during peak-load events and facility upgrades, creating recurring demand for modular cooling infrastructure.
- EPA Tier 4 Final standards:Fleet operators replace legacy diesel generator sets with compliant units, accelerating replacement cycles and rental demand during transition periods.
- Grid instability patterns:Hurricane-season volatility in the United States sustains emergency response contracts across utility and industrial accounts.
Market Restraints
- Input cost volatility:Steel and copper price swings compress rental fleet margins and complicate long-term contract pricing.
- Supply concentration risk:Mobile generator engine manufacturing clusters in Germany and Japan expose operators to single-source dependencies.
- Technical limitation:Battery-hybrid temporary power architectures face energy density constraints above 500 kW continuous output.
Strategic Opportunities
- Underpenetrated geography:Southeast Asian manufacturing corridors lack established rental cooling infrastructure for semiconductor fabrication expansion.
- Regulatory tailwind:The EU F-Gas Regulation drives refrigerant transition services and chiller fleet modernization across European deployments.
- Technology convergence:Integration of predictive thermal analytics with mobile cooling units enables proactive deployment before thermal emergencies.
Industry Challenges
- Talent gap:Certified technicians for Tier 4 Final engine diagnostics and refrigerant handling remain scarce relative to fleet expansion needs.
- Certification timeline:OSHA noise compliance testing and EPA emissions certification extend equipment commissioning cycles.
- Legacy integration:Synchronizing temporary power with existing building management systems requires custom electrical engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temporary Power and Cooling Solutions Market |
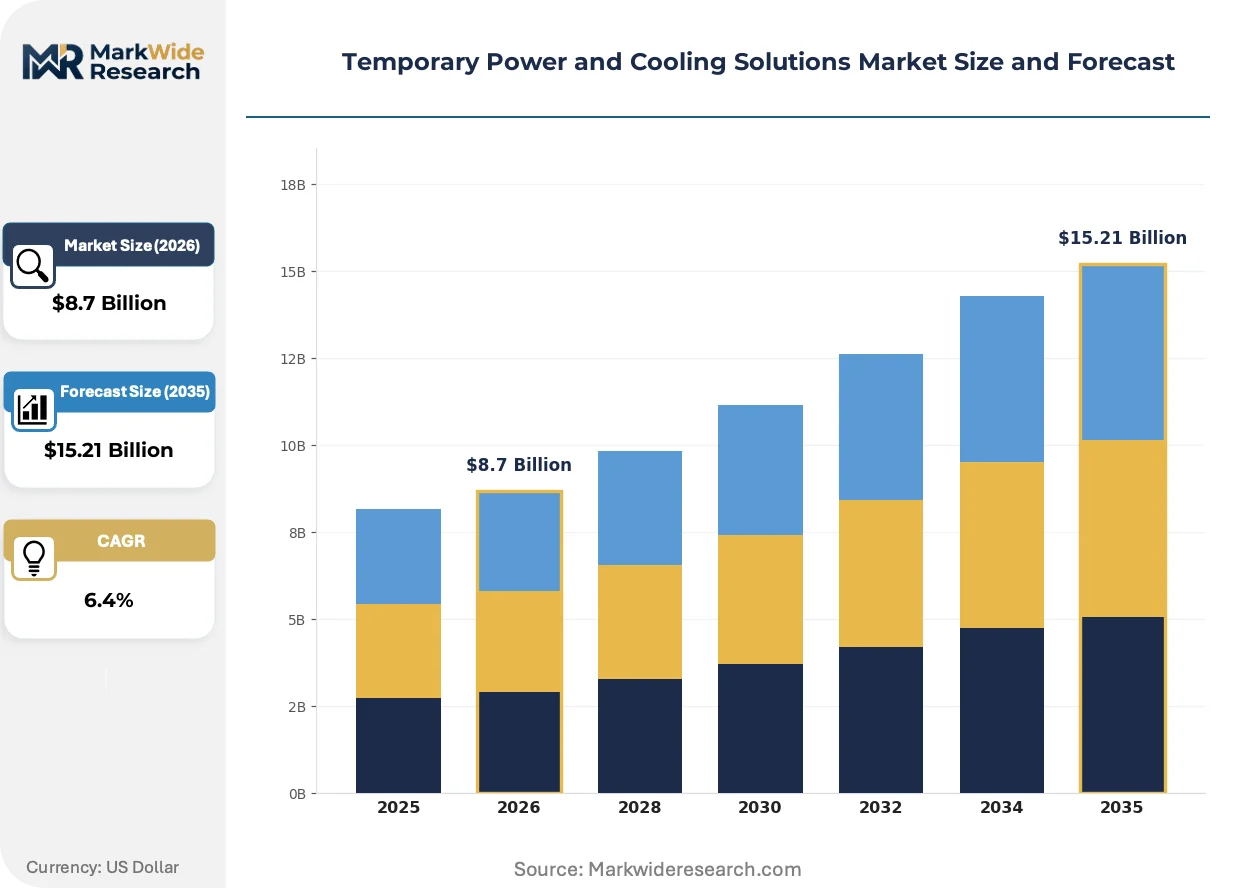
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, Chillers, Air Conditioners, Thermal Storage Installation: Temporary Sites, Events, Construction Projects, Emergency Services End User: Industrial Facilities, Data Centers, Commercial Buildings, Residential Areas Service Type: Rental Services, Maintenance Services, Installation Services, Consulting Services |
| Companies Covered | Aggreko, United Rentals, Sunbelt Rentals, Trane Technologies, Herc Rentals, Caterpillar, Atlas Copco, Cummins, Carrier Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temporary Power and Cooling Solutions Market Trends and Innovations
Equipment intelligence and emissions compliance are converging to reshape competitive positioning, with sensor-enabled fleet management and alternative fuel architectures displacing conventional diesel-centric operations.
Natural gas generator sets are absorbing market share in urban deployments where EPA Tier 4 Final diesel compliance costs prove prohibitive. Data center operators and healthcare facilities adopt these units for planned maintenance coverage. The technology is absorbing demand that previously defaulted to diesel, compressing the addressable market for conventional mobile generator rentals in noise-sensitive and emissions-restricted zones.
REACH chemical protocols and the EU F-Gas Regulation are forcing refrigerant transitions across European chiller fleets. Rental operators must retrofit or replace thermal fluid handling systems to maintain deployment eligibility. Industrial process cooling and pharmaceutical manufacturing segments face the steepest compliance burdens, accelerating capital deployment toward low-GWP refrigerant architectures.
Equipment-as-a-service contracting is displacing traditional spot rental arrangements among large industrial accounts. Fixed monthly fees covering deployment, fuel logistics, and maintenance lock in multi-year relationships and reduce procurement friction. This model concentrates most visibly in United States utility-scale construction and petrochemical turnaround projects where budget predictability outweighs spot-rate flexibility.
Temporary Power and Cooling Solutions Market Segmentation
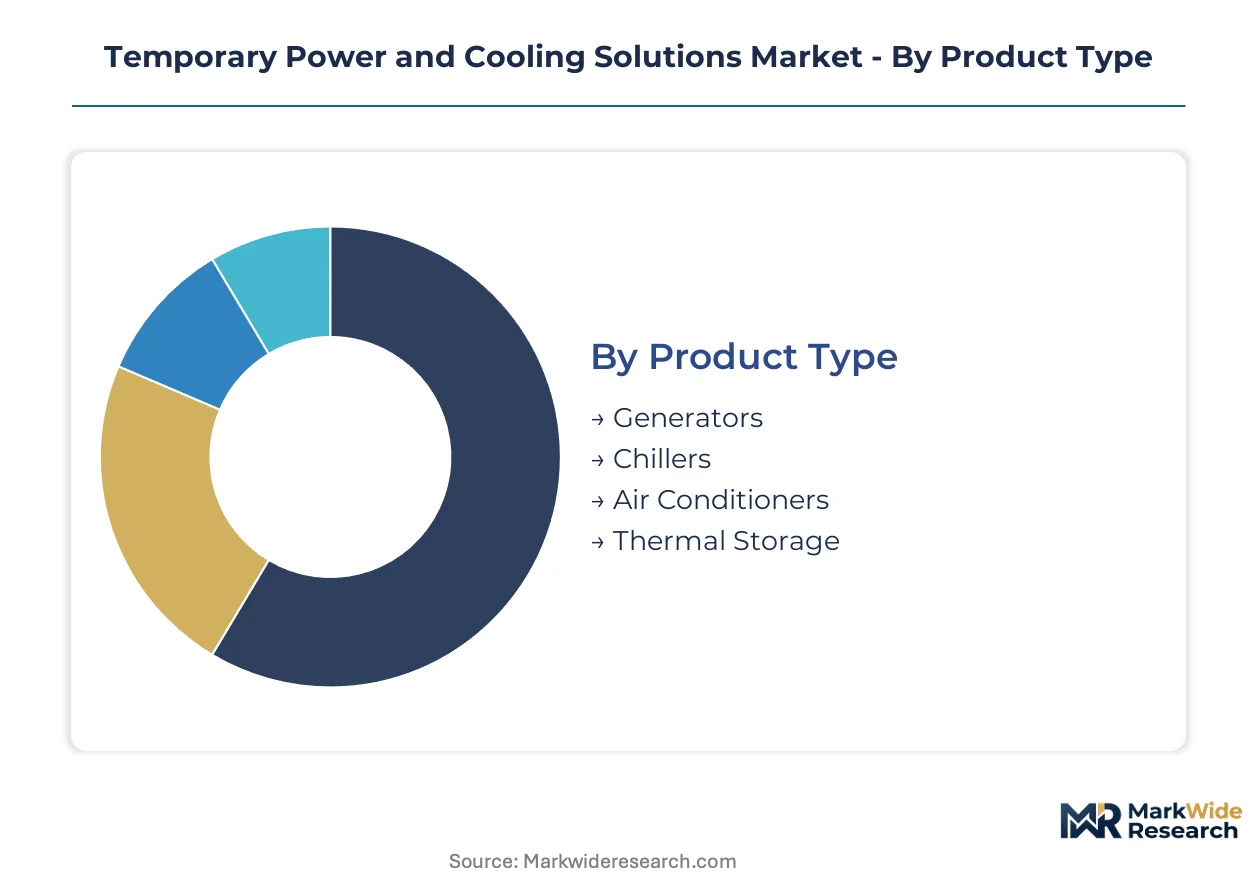
Segmentation in temporary power and cooling solutions reveals how asset intensity, deployment velocity, and regulatory exposure concentrate value capture across distinct procurement patterns. Equipment specifications and service bundling separate utility-scale contracts from spot-market rentals.
Product Type:
Mobile generator sets anchor fleet economics through fuel logistics complexity and EPA Tier 4 Final compliance costs that filter smaller operators from large tenders.
- Generators:Diesel and natural gas mobile units rated from 20 kW to 2,000-plus kW dominate rental revenue given asset intensity and synchronized paralleling requirements for utility-scale deployments. Data center operators in hurricane-prone US states absorb the highest deployment volumes during grid instability events.
- Chillers:Trailer-mounted units from 10 to 1,500-plus tons serve thermal redundancy needs during facility upgrades and peak-load events. Hyperscalers in Northern Virginia and Dallas-Fort Worth metro areas drive fastest adoption as they expand redundant cooling for planned maintenance windows.
- Air Conditioners:Modular air handling units deploy for rapid climate control without permanent infrastructure.
- Thermal Storage:Ice-based and chilled water systems provide load-shifting capacity for demand response programs.
Generators lead on scale; chillers lead on momentum.
Installation:
Deployment context determines contract duration, fuel logistics complexity, and integration requirements with existing building management systems.
- Temporary Sites:Industrial turnarounds and planned maintenance events require synchronized paralleling with permanent plant infrastructure. Petrochemical facilities along the US Gulf Coast sustain longest average contract durations given multi-week turnaround schedules.
- Events:Sports stadiums and concert venues demand rapid deployment and noise-compliant specifications for urban deployments. Tier 4 Final diesel and natural gas units absorb demand in emissions-restricted zones where conventional diesel faces prohibitive compliance costs.
- Construction Projects:Utility-scale builds require continuous power for crane operations and welding during grid interconnection queues.
- Emergency Services:Hurricane response and grid restoration contracts prioritize mobilization speed over fuel efficiency.
Temporary Sites command the longest contracts; Events are climbing the fastest.
End User:
Capital discipline and thermal load predictability separate multi-year equipment-as-a-service contracts from spot rental arrangements.
- Industrial Facilities:Petrochemical, mining, and manufacturing operations require continuous power during planned maintenance and grid instability. Louisiana and Texas refineries sustain highest generator utilization rates given hurricane-season volatility and process safety requirements.
- Data Centers:Hyperscalers deploy trailer-mounted chillers for peak-load events and facility upgrades. Northern Virginia's concentration of cloud computing infrastructure creates densest demand for modular cooling redundancy.
- Commercial Buildings:Healthcare facilities and office complexes adopt natural gas units for planned maintenance coverage in noise-sensitive zones.
- Residential Areas:Post-disaster grid restoration drives emergency generator deployment for critical infrastructure.
Industrial Facilities anchor revenue concentration; Data Centers show steepest expansion trajectory.
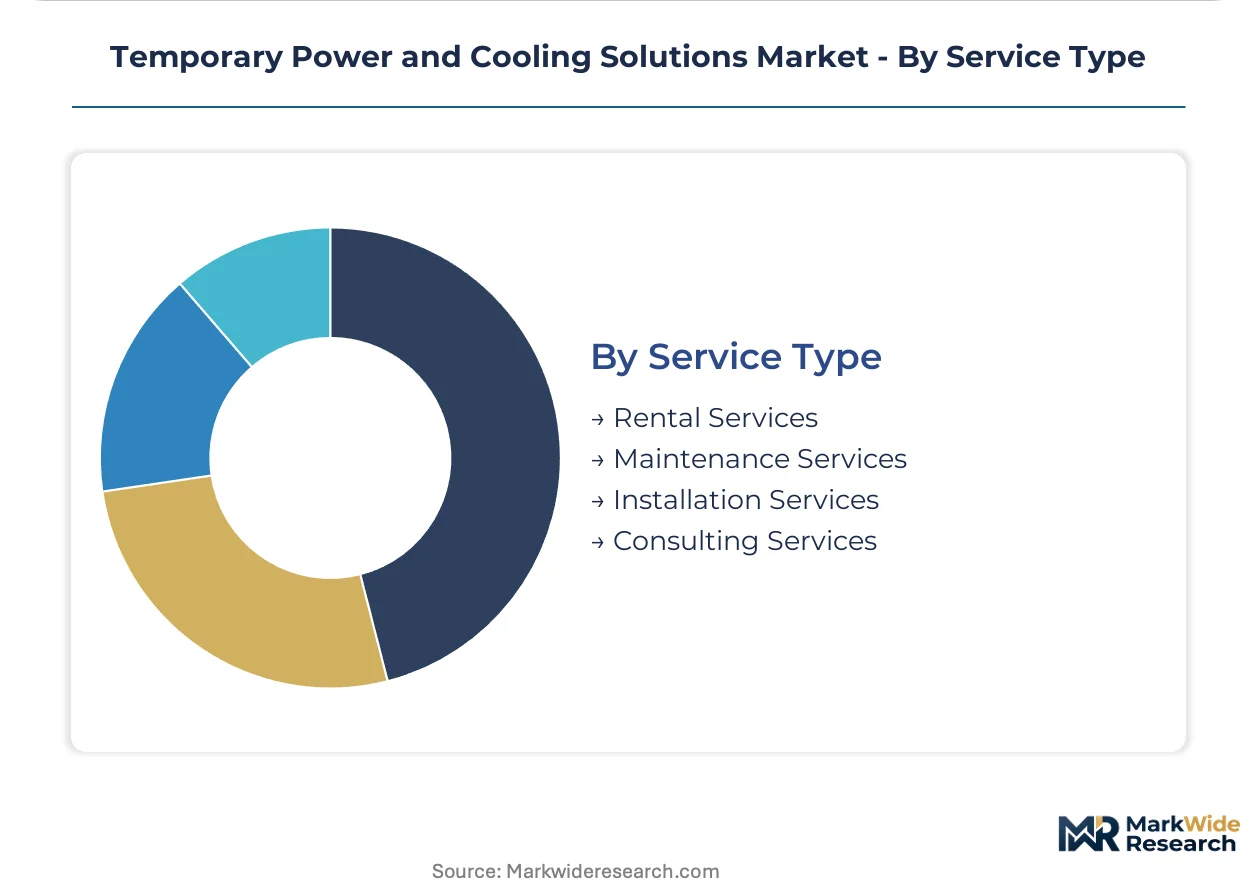
Service Type:
Revenue model selection reflects customer scale, technical capability gaps, and preference for budget predictability over spot-rate flexibility.
- Rental Services:Equipment leasing with bundled fuel logistics and maintenance commands highest margins given asset intensity and EPA compliance costs. Large industrial accounts in US utility-scale construction increasingly prefer fixed monthly fees over spot arrangements.
- Maintenance Services:Preventive and corrective service contracts lock in recurring revenue streams. Tier 4 Final engine diagnostics and refrigerant handling certifications create scarcity premiums for qualified technician networks.
- Installation Services:Site preparation, electrical integration, and commissioning retain thinner margins but enable ongoing maintenance relationships.
- Consulting Services:Load analysis, regulatory compliance planning, and hybrid architecture design support complex deployments.
Rental Services capture dominant value share; Maintenance Services gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northern Virginia data center corridor concentrates global demand for modular cooling redundancy as hyperscalers expand thermal infrastructure during facility upgrades.
United States
Hurricane-season grid instability and utility-scale construction activity sustain emergency generator utilization across Gulf Coast refineries and Texas petrochemical complexes. EPA Tier 4 Final standards accelerate replacement cycles for non-road diesel engines in rental fleets. Dallas-Fort Worth metro data centers deploy trailer-mounted chillers during peak-load events.
Germany
Industrial manufacturing clusters in North Rhine-Westphalia require continuous power during planned maintenance and grid balancing events. REACH chemical protocols and EU F-Gas Regulation reshape refrigerant choices for chiller fleet operators. Bavarian automotive plants adopt natural gas generator sets for emissions-restricted production coverage.
China
Semiconductor fabrication expansion in the Yangtze River Delta and Pearl River Delta drives demand for precision cooling during facility construction phases. MEE emissions standards and dual carbon goals push temporary power toward cleaner fuel architectures. Shanghai metro data centers rent modular air handling units during thermal infrastructure upgrades.
India
Grid intermittency in Maharashtra and Gujarat manufacturing corridors sustains diesel generator rental demand for continuous process operations. CEA grid codes and state-level renewable purchase obligations complicate temporary power synchronization with evolving grid infrastructure. Bengaluru data centers deploy rental cooling during hyperscaler facility expansions.
United Arab Emirates
Desert climate extremes and construction mega-projects in Dubai and Abu Dhabi sustain year-round demand for mobile cooling and power infrastructure. MOHAP facility standards and federal emissions frameworks guide generator specifications for healthcare and critical infrastructure deployments. NEOM construction sites absorb large-scale rental power for off-grid development phases.
Temporary Power and Cooling Solutions Market Competitive Landscape
Global majors compete with regional champions across fleet scale and emergency response velocity, producing a tiered structure where asset intensity and technician certification networks separate utility-scale contract winners from spot-market operators. Equipment rental specialists, integrated manufacturers with captive dealer networks, and energy service providers constitute three dominant archetypes. Consolidation through fleet acquisitions and geographic expansion into underpenetrated manufacturing corridors represent the primary competitive vectors reshaping market share distribution.
Among the integrated manufacturer tier, Caterpillar and Cummins occupy positions defined by engine manufacturing depth and channel control over dealer-serviced rental programs. Aggreko exemplifies the pure-play rental specialist archetype, anchoring emergency response contracts through distributed fleet networks. These three companies represent contrasting strategic positions: manufacturing-backed rental access versus asset-light service scaling versus hybrid energy solutions integration.
| Leading Market Players |
|---|
| Aggreko |
| United Rentals |
| Sunbelt Rentals |
| Trane Technologies |
| Herc Rentals |
| Caterpillar |
| Atlas Copco |
| Cummins |
| Carrier Corporation |
| Others |
Pricing and Supply Chain Analysis
Certified Tier 4 Final engine technicians concentrated in Texas and Louisiana command wage premiums that widen pricing spreads between premium rental fleets and spot-market operators lacking qualified diagnostic networks.
Pricing Analysis
Input-cost pass-through from steel and copper volatility compresses margins for standard-tier rental operators while premium fleets absorb fluctuations through longer-term equipment-as-a-service contracts. Price differentiation separates EPA-certified Tier 4 Final units from legacy diesel alternatives, with certification grade and bundled fuel logistics driving tier separation. Pricing pressure intensifies in the spot rental segment as construction-adjacent demand softens and smaller operators discount to maintain utilization. Industrial facilities with multi-year maintenance windows show lowest price sensitivity; event-driven spot rentals face highest sensitivity to rate competition.
Supply Chain Analysis
EPA and EU F-Gas qualification requirements gate access to utility-scale tenders, filtering suppliers without certified refrigerant handling and emissions-compliant engine networks. Mobile generator engine manufacturing clusters in Germany and Japan create geographic concentration, while trailer-mounted chiller production draws from China and the United States. Raw material dependencies span steel for enclosures, copper for windings, and aluminum for heat exchangers. Single-source vulnerability in specialized engine components from Japanese suppliers poses structural risk. Distribution runs through manufacturer-authorized dealer networks and pure-play rental specialists with regional depot infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Tier 4 Final enforcement and EU F-Gas phase-down mandates perpetuate replacement demand and certification barriers.
For Market Incumbents: Anchor emergency response velocity through distributed fleet positioning in hurricane-prone Gulf Coast corridors and Northern Virginia data center clusters. Deepen technician certification networks to defend against emerging battery-hybrid entrants lacking EPA engine diagnostics capability. Prioritize equipment-as-a-service contract structures that lock in industrial accounts before spot-market competitors undercut on rate. For New Entrants and Emerging Players: Digital equipment brokerage platforms offer the lowest-capital route to wedge into fragmented Southeast Asian manufacturing corridors lacking established rental cooling infrastructure. Target semiconductor fabrication buildouts in Vietnam and Malaysia where precision cooling demand outpaces local supply. Pursue predictive thermal analytics integration as a differentiated service layer atop commoditized equipment rental. For Investors and Strategic Acquirers: Energy service companies with captive power generation assets are the most active acquirer in this space, seeking rental fleet capabilities to bundle with distributed energy contracts. Acquisition targets should display dense technician networks in high-utilization geographies and EPA certification depth that would require years to replicate organically. Monitor battery-hybrid architecture cost curves as the inflection signal for fossil-fueled fleet obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Tier 4 Final Fleet Modernization | EPA compliance deadlines force replacement cycles that concentrate market share among certified operators. |
| Equipment-as-a-Service Contracting | Fixed-fee structures lock in multi-year industrial relationships and reduce procurement friction. |
| Predictive Thermal Analytics Integration | Sensor-enabled deployment timing captures demand before thermal emergencies materialize. |
| Natural Gas Generator Expansion | Urban emissions restrictions shift demand from diesel toward cleaner-burning alternatives. |
| Southeast Asian Depot Network Buildout | Semiconductor fabrication corridors lack established rental infrastructure for precision cooling. |
Research Methodology
Bottom-up data center and industrial facility modeling reconciled against top-down rental fleet capacity tracking forms the analytical core of this study. Primary interviews with fleet operations directors, EPA compliance officers, data center facilities managers, and petrochemical maintenance planners combined with secondary validation from EIA power outage databases, EPA engine certification registries, and hyperscaler capex disclosures. Triangulation across these sources anchors volume estimates.
Historical utilization trendline analysis by equipment type and geography informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, installation context, end-user industry, and service bundling structure. CAGRs derive from equipment replacement cycle timing, regulatory phase-in schedules, and thermal load growth patterns at hyperscale facilities. Forecast inputs incorporate grid instability frequency indices and construction project pipeline data.
The model assumes a particular technology adoption path; alternative pathways for battery-hybrid temporary power architectures above 500 kW would alter the outlook. Forecasts reflect assumptions about EPA enforcement continuity and EU F-Gas refrigerant availability. A model refresh is warranted upon material change in battery energy density cost curves or carbon border mechanism implementation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Thawing System Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Air to Air Heat Pumps Sales Market