
 Automotive Refinish Coatings Market | 2026-2036
Automotive Refinish Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Refinish Coatings Market Analysis
The capital-intensity divergence between integrated resin producers and formulation specialists is unwinding competitive stability in automotive refinish coatings. PPG Industries leverages captive acrylic resin production to sustain margin control across base coat and clear coat lines. Axalta Coating Systems anchors its position through dedicated refinish distribution networks spanning independent body shops and commercial fleet operators. BASF SE differentiates via polyurethane technology leadership in premium clear coat segments.
Automotive refinish coatings constitute pigmented and clear film-forming systems applied to repaired or restored vehicle substrates, typically comprising acrylic-urethane or polyester-urethane chemistries cured through ambient or forced-dry processes at film builds of 40–150 microns. These formulations restore aesthetic and protective functions to collision-damaged, weathered, or customized vehicle surfaces across passenger and commercial transport categories. Water-based technology now leads regulatory-compliant growth in Europe and North America while solvent-based systems still dominate volume in cost-sensitive repair channels. Clear coats capture premium margin pools due to gloss retention and durability specifications demanded by OEM certification programs. Independent body shops represent the largest end-user channel, though commercial fleets are consolidating procurement toward direct supplier relationships.
EPA VOC rules and REACH restrictions on isocyanate-containing formulations are reshaping product development priorities across formulation labs. FDA oversight of workplace chemical exposure in repair facilities intersects with OSHA permissible exposure limits to accelerate spray booth investment cycles. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to maintain dual solvent-water portfolios or commit capital to single-technology platforms before compliance deadlines harden.
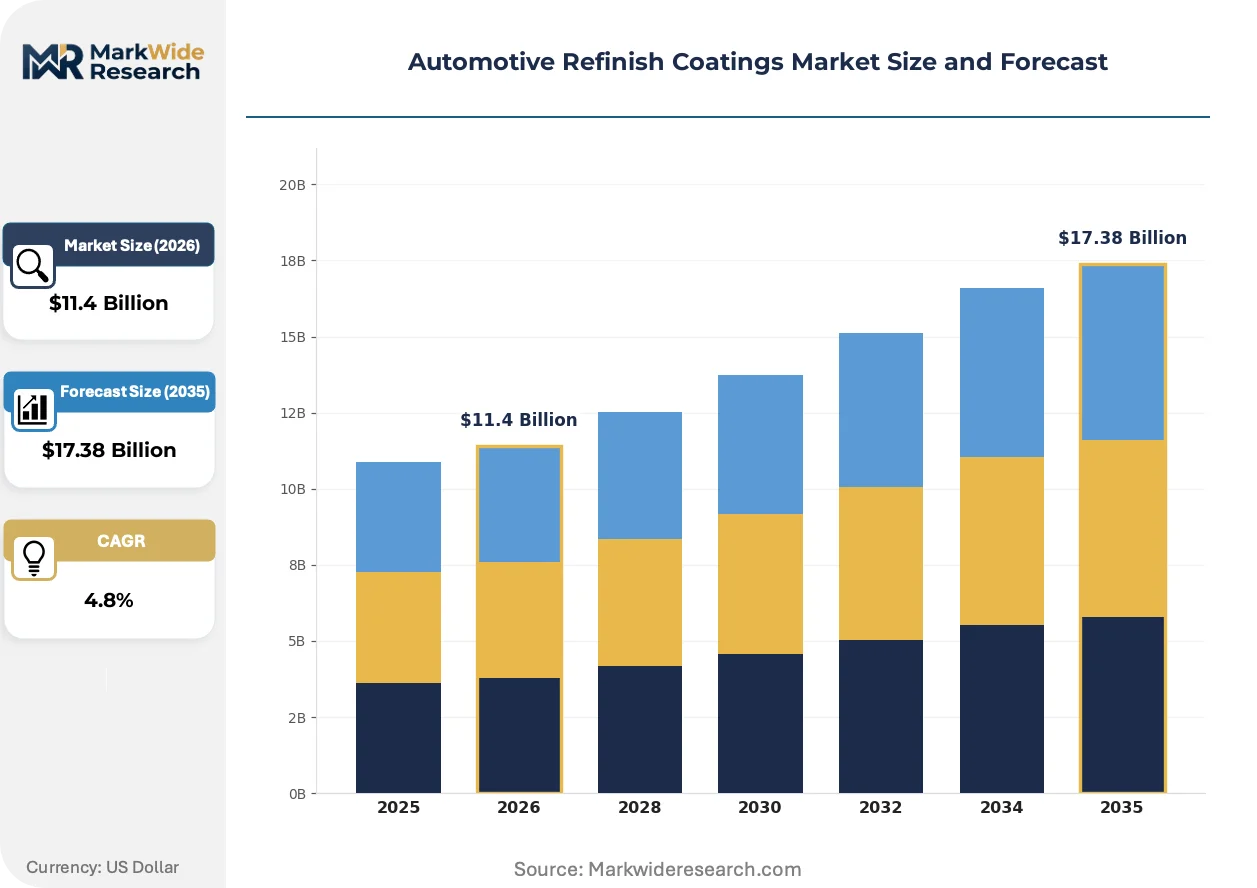
Market Dynamics
Water-based formulation technology is compressing the competitive moat between integrated resin producers and regional blenders as EPA VOC limits and REACH restrictions harden compliance deadlines across collision repair networks.
Growth Catalysts
- EPA VOC Phase-Down Rules:The US Environmental Protection Agency's progressively tightening volatile organic compound limits for automotive refinish coatings are forcing solvent-to-water technology conversions across independent body shop networks, expanding addressable market for compliant formulation suppliers.
- Collision Repair Volume Concentration:Rising vehicle fleet age in developed markets is extending repairable life cycles and increasing per-vehicle coating consumption as substrates require more extensive surface preparation and multi-layer restoration.
- Polyurethane Clear Coat Performance Premium:OEM certification programs demanding gloss retention above 90% at five-year intervals are locking in premium pricing tiers for polyurethane-based clear coat technologies across certified repair channels.
Market Restraints
- Titanium Dioxide Feedstock Volatility:Pigment cost fluctuations concentrated in Chinese sulfate-process production are compressing formulation margins and forcing quarterly price adjustments across base coat product lines.
- Isocyanate Exposure Liability:REACH restrictions on hexamethylene diisocyanate-containing hardeners are triggering reformulation costs and workplace exposure monitoring investments that disproportionately burden small independent body shop operators.
- Spray Booth Capital Intensity:Forced-dry water-based curing systems require booth upgrades exceeding $80,000 per bay, creating adoption friction in cost-sensitive repair markets and extending payback periods.
Strategic Opportunities
- India Collision Repair Network Expansion:Emerging organized multi-shop chains in Mumbai, Delhi, and Bangalore are consolidating procurement and creating direct supplier relationships bypassing traditional distributor markups.
- Commercial Fleet Direct Contracting:Logistics and rental fleet operators with centralized maintenance operations are negotiating volume-based coating supply agreements with formulation specialists, disintermediating independent distributor networks.
- UV-Curable Technology Convergence:Integration of ultraviolet curing with water-based resin platforms is enabling energy consumption reductions and throughput gains for high-volume repair facilities seeking operational differentiation.
Industry Challenges
- Spray Technician Certification Compression:OEM paint certification programs requiring 40-hour training modules and annual recertification are constraining labor supply and inflating wage costs across certified repair networks.
- Dual-Technology Inventory Complexity:Body shops serving mixed vehicle fleets must maintain parallel solvent-based and water-based coating inventories, doubling working capital requirements and complicating color-matching accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Refinish Coatings Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Coats, Clear Coats, Primer Coats, Activators Technology: Solvent-Based, Water-Based, UV-Curable, Electrostatic End User: Independent Body Shops, OEMs, Commercial Fleets, Insurance Companies Application: Repair, Restoration, Customization, Maintenance |
| Companies Covered | PPG Industries, Axalta Coating Systems, BASF SE, AkzoNobel N.V., Nippon Paint Holdings, The Sherwin-Williams Company, Kansai Paint Co., Ltd., 3M Company, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Refinish Coatings Market Emerging Trajectories
Digital color-matching systems and automated dispensing equipment are restructuring how collision repair facilities manage substrate variability and reduce material waste across multi-layer coating applications.
Nano-particle additive technology is miniaturizing film-build requirements while maintaining chip resistance and UV durability specifications. High-volume independent body shops in Germany and the Netherlands are adopting nano-enhanced clear coats to reduce material consumption per repair job by 15-20%. This compression of film thickness is miniaturizing the traditional base-coat-clear-coat stack architecture and enabling faster throughput in constrained booth capacity environments.
REACH authorization requirements for chromium trioxide in corrosion-inhibiting primers are accelerating substitution toward zirconium-based and silicon-based pretreatment chemistries. Formulation labs across Belgium, France, and Italy are requalifying adhesion performance under salt-spray testing protocols. The commercial vehicle refinish segment faces the steepest compliance timeline, with fleet operators in Poland and Spain accelerating procurement of pre-approved alternative systems.
Consolidated procurement platforms operated by national insurance networks are displacing traditional distributor relationships in the United Kingdom and Australia. These platforms aggregate volume across affiliated repair facilities and negotiate direct supply agreements with coating manufacturers, extracting price concessions in exchange for exclusive product specifications. The behavioral shift is most visible in total-loss avoidance programs where insurers mandate certified coating systems to preserve vehicle residual values.
Automotive Refinish Coatings Market Segmentation
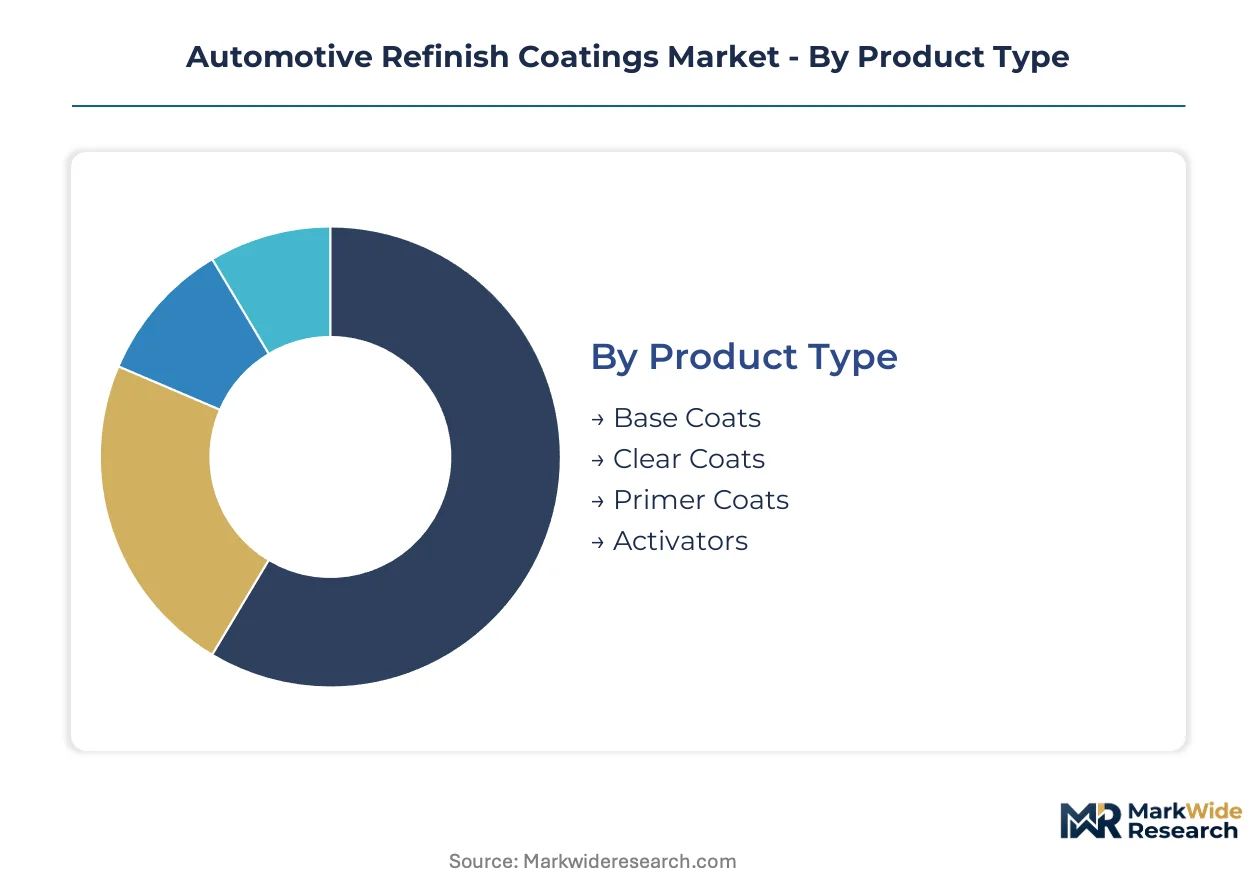
Automotive refinish coatings segment along four critical dimensions that determine formulation specifications, regulatory compliance pathways, and distribution channel economics. Product type and technology choices dictate capital requirements and margin profiles, while end-user concentration shapes procurement patterns across collision repair networks.
Product Type:
Domestic consumption concentrates in base coats and clear coats across North American and European repair networks, while primer exports flow toward emerging collision infrastructure in Asia. Activator demand tracks regional formulation preferences.
- Base Coats:Pigmented acrylic-urethane systems providing color and opacity at 15–25 micron film builds. Demand concentrates in independent body shops across Germany, the United States, and Japan as EPA and REACH VOC enforcement tightens solvent-based inventory. Color-matching complexity drives premium pricing for factory-packaged formulations.
- Clear Coats:Transparent polyurethane or acrylic-urethane top layers delivering gloss retention and UV protection at 40–60 microns. OEM certification programs in Italy, France, and the United Kingdom mandate specific clear coat performance tiers, locking in supplier relationships and sustaining margin premiums through durability specifications.
- Primer Coats:Corrosion-inhibiting adhesion promoters applied to bare metal or filler substrates. REACH chromium trioxide restrictions are accelerating zirconium-based substitution in Belgian and Spanish commercial vehicle applications.
- Activators:Isocyanate-containing hardeners catalyzing polyurethane cure reactions. Workplace exposure monitoring requirements under OSHA and REACH disproportionately burden small operators in cost-sensitive repair markets.
Clear coats command the established base. The steepest expansion runs through base coats as water-based conversions accelerate.
Technology:
Cost tier stratification separates premium water-based systems from economy solvent formulations, with UV-curable and electrostatic technologies occupying specialized throughput niches.
- Solvent-Based:Traditional alkyd and acrylic systems delivering fast ambient drying and broad substrate compatibility. Volume concentrates in India, Brazil, and Mexico where collision repair networks prioritize equipment minimization and technician familiarity over regulatory compliance timelines.
- Water-Based:Acrylic-urethane dispersions requiring forced-air drying infrastructure. EPA VOC phase-down rules and REACH restrictions are mandating adoption across certified repair networks in California, Michigan, and Ontario, with booth upgrade subsidies accelerating penetration.
- UV-Curable:Acrylate oligomer systems cured through ultraviolet radiation exposure. High-volume facilities in the Netherlands and South Korea deploy this technology for spot repair applications demanding sub-30-minute turnaround.
- Electrostatic:Charged particle application systems maximizing transfer efficiency. Commercial fleet operators in Australia and Canada adopt electrostatic spray for wheel and bumper refinishing to reduce material waste.
Solvent-based technology retains volume leadership. Water-based platforms are climbing the fastest as compliance deadlines harden.
End User:
Customer type determines procurement scale and specification authority, from fragmented independent operators to consolidated fleet purchasing.
- Independent Body Shops:Small and mid-sized collision repair facilities representing the largest channel by transaction volume. Insurance network consolidation in the United Kingdom and Australia is displacing traditional distributor relationships through mandated procurement platforms.
- OEMs:Vehicle manufacturers operating certified repair networks with strict coating specifications. German and Japanese OEM certification programs require 40-hour technician training and annual recertification, constraining labor supply.
- Commercial Fleets:Logistics, rental, and municipal operators with centralized maintenance operations. Direct contracting trends in Poland and Texas are bypassing distributor markups through volume-based supply agreements.
- Insurance Companies:Underwriters mandating coating specifications through total-loss avoidance programs. Residual value preservation requirements in France and Spain drive certified system procurement.
Independent body shops anchor volume. Commercial fleets are gaining share fastest through procurement centralization.
Application:
Application purpose segments by vehicle lifecycle stage and substrate condition, from damage remediation to aesthetic modification.
- Repair:Collision damage restoration comprising the dominant application by revenue. Rising fleet age in the United States and Germany extends repairable life cycles and increases per-vehicle coating consumption.
- Restoration:Classic and vintage vehicle refinishing requiring period-correct color matching. Specialty shops in California and England command premium pricing for concours-quality finishes.
- Customization:Aesthetic modification including color changes and graphic applications. Aftermarket specialists in Florida and Dubai serve consumer preference for personalized vehicle appearance.
- Maintenance:Protective refinishing of weathered or degraded surfaces. Commercial vehicle operators in Ohio and Pennsylvania schedule preventive coating renewal to maximize asset resale values.
Repair commands the established base. Customization shows the steepest expansion trajectory as consumer personalization preferences intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese OEM-certified repair networks while cost-sensitive volume flows through Indian and Brazilian solvent-based channels. Regulatory divergence between EPA-VOC jurisdictions and REACH enforcement zones is fragmenting technology adoption timelines. Collision repair density maps directly to vehicle fleet age and insurance market maturity.
United States
Collision repair volume concentrates in California, Texas, and Florida where aging vehicle fleets extend repairable life cycles. EPA VOC phase-down rules mandate water-based conversions across certified body shops in Michigan and Ohio. The Detroit-Windsor corridor anchors North American formulation demand through dense commercial fleet operations and OEM-certified repair networks.
Germany
Premium clear coat specifications from BMW, Mercedes-Benz, and Volkswagen certification programs sustain margin premiums. REACH restrictions on hexamethylene diisocyanate hardeners trigger reformulation investments across Bavarian and Baden-Württemberg formulation labs. The Stuttgart-Munich industrial corridor concentrates Europe's highest collision repair labor rates and OEM compliance density.
China
Organized multi-shop chains in Shanghai, Beijing, and Guangzhou consolidate procurement toward direct supplier relationships. MEE enforcement of VOC limits in Yangtze River Delta provinces accelerates water-based infrastructure investment. The Pearl River Delta collision repair market still favors solvent-based speed for high-volume commercial vehicle turnaround.
India
Emerging organized chains in Mumbai, Delhi, and Bangalore bypass traditional distributor markups through centralized procurement. BIS standards for automotive coatings remain less stringent than REACH or EPA equivalents, preserving solvent-based cost advantages. The Pune-Nashik corridor anchors western India's fastest collision repair network expansion.
Japan
OEM certification programs from Toyota, Honda, and Nissan require 40-hour technician training and annual recertification. METI guidelines on workplace chemical exposure accelerate spray booth investment cycles in Osaka and Nagoya repair clusters. The Kanto region's dense insurance network mandates certified coating systems for total-loss avoidance programs.
Automotive Refinish Coatings Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated resin producers commanding premium pricing through captive raw material control while regional blenders compete on formulation flexibility and distributor relationships. The market structure consolidates around three tiers: multinational integrated producers, regional formulation specialists, and captive OEM supply operations. Dominant competitive moves include backward integration into acrylic and polyurethane resin production and strategic partnerships with national insurance procurement platforms.
Among integrated multinational producers, PPG Industries and Axalta Coating Systems exemplify the technology-and-distribution archetype through dedicated refinish networks spanning independent body shops and commercial fleet operators. BASF SE occupies a position representing polyurethane technology specialization in premium clear coat segments. These three anchors demonstrate how captive resin production, distribution infrastructure ownership, and OEM certification alignment separate sustainable margin pools from commodity formulation competition.
| Leading Market Players |
|---|
| PPG Industries |
| Axalta Coating Systems |
| BASF SE |
| AkzoNobel N.V. |
| Nippon Paint Holdings |
| The Sherwin-Williams Company |
| Kansai Paint Co., Ltd. |
| 3M Company |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
Resin production scale economies at integrated producers like PPG and BASF establish price floors that regional blenders cannot match without captive acrylic or polyurethane feedstock. This concentration of upstream capacity in Germany, the United States, and Japan compresses margin flexibility for formulation specialists while amplifying pricing power for backward-integrated players across OEM-certified repair networks.
Pricing Analysis
The customization-premium spread separates factory-packaged color-matched base coats from bulk tinting systems. Three-tier pricing structure across premium, standard, and economy levels tracks OEM certification grade and volume scale. Price differentiation hinges on gloss retention specifications and insurance network exclusivity. Cost-sensitive independent body shops in India and Brazil resist premium tiers, while German and Japanese OEM channels absorb markups for durability guarantees. Pricing pressure stems from titanium dioxide feedstock volatility concentrated in Chinese sulfate-process production.
Supply Chain Analysis
Just-in-time inventory strategies dominate water-based formulation distribution to minimize shelf-life degradation, while strategic stockpiling persists for solvent-based activators with longer stability windows. Raw material supply concentrates in Germany, China, and the United States for acrylic resins, isocyanate hardeners, and nano-particle additives. Formulation draws from titanium dioxide pigment networks anchored in Chinese sulfate-process capacity and zirconium-based pretreatment chemistries emerging from Belgian and Spanish labs. Single-source vulnerability runs through hexamethylene diisocyanate supply chains facing REACH authorization pressures. Distribution runs through dedicated refinish networks spanning independent body shops and commercial fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive refinish coatings operate as a substitution defense market where UV-curable and powder coating technologies threaten traditional liquid formulations. Incumbents must navigate this substitute threat while consolidating procurement platforms disintermediate traditional distributor relationships.
For Market Incumbents: Compound technology leadership in polyurethane clear coats through captive resin production and OEM certification alignment. Deepen backward integration into acrylic feedstock to defend margin pools against titanium dioxide volatility. Prioritize spray booth financing partnerships to accelerate water-based conversions ahead of EPA VOC deadlines.
For New Entrants and Emerging Players: Anchor in India's emerging organized collision repair chains in Mumbai, Delhi, and Bangalore where centralized procurement bypasses legacy distributor markups. Target commercial fleet direct contracting in Poland and Texas with volume-based supply agreements. Pursue nano-enhanced clear coat formulations as a performance-differentiated entry wedge.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with established insurance procurement platform relationships over commodity blenders. Long-term viability hinges on regulatory compliance trajectory across REACH and EPA jurisdictions. Acquisition target archetype: regional players with captive distribution in water-based growth corridors. Watch for UV-curable technology cost parity as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | Captive feedstock supply insulates margin pools from titanium dioxide volatility. |
| OEM Certification Program Alignment | BMW and Toyota certification requirements lock in premium pricing tiers. |
| Insurance Procurement Platform Partnership | Direct supply agreements with UK and Australian networks disintermediate distributors. |
| Spray Booth Financing Programs | Equipment subsidies accelerate water-based adoption ahead of EPA VOC deadlines. |
| UV-Curable Technology Convergence | Energy reduction and throughput gains attract high-volume Dutch and Korean facilities. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across collision repair networks, formulation laboratories, and commercial fleet maintenance divisions. Primary interviews with body shop owners, coating procurement managers, OEM certification program administrators, and spray equipment distributors were validated against secondary sources including EPA regulatory filings, ECHA REACH authorization databases, customs trade data on titanium dioxide imports, and SEC 10-K disclosures from integrated coating producers. Bottom-up volume estimates from independent body shop transaction data were triangulated with top-down value projections from formulation manufacturer revenue segmentation.
Across the analysis window, forecasts were derived from modeled interactions between technology adoption curves, regulatory compliance timelines, and collision repair volume concentration. Segmentation dimensions included product type, formulation technology, end-user channel, and application purpose. CAGRs were computed from annualized growth paths adjusted for spray booth capital intensity and technician certification constraints. Industry-specific inputs incorporated fleet age trajectories in the United States and Germany alongside MEE enforcement patterns in China's Yangtze River Delta.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA VOC phase-down and REACH authorization timelines; material deviation would warrant model refresh. Revision becomes warranted when UV-curable technology cost curves cross solvent-based parity thresholds or when insurance procurement platform consolidation accelerates beyond modeled penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Water Based Enamel Market
Coatings
Japan Marine Coatings Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
2K Protective Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Global Low Friction Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Global Sputter Coater Market
Coatings
Bio-Based Coatings Market
Coatings
PU Coatings Market
Coatings
Conductive Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Industrial Coatings Market
Coatings
Marine Nanocoating Market