
 Global Solar Panel Coatings Market | 2026-2036
Global Solar Panel Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Panel Coatings Market Foresight
REACH compliance is decoupling European market access from legacy solvent-based formulations. PPG Industries leverages its fluoropolymer expertise to sustain premium positioning in anti-soiling solutions. BASF SE anchors supply relationships across utility-scale project pipelines through polymer-based coating platforms.
Solar panel coatings are thin-film surface treatments, typically 100–500 nanometers in thickness, applied to photovoltaic glass to enhance light transmission, reduce soiling accumulation, and extend module service life. Their primary purpose is to maximize energy yield per installed watt by minimizing reflection losses and maintenance downtime. Anti-reflective coatings dominate volume demand due to universal integration into crystalline silicon modules, while nanocoatings represent the fastest-expanding technology tier as manufacturers pursue dual-function hydrophobic-anti-reflective layers. Hydrophobic formulations command margin premiums in desert and coastal installations where dust and salt deposition degrade performance.
The EPA enforces VOC emission thresholds that constrain coating formulation chemistry in the United States, while China's MEE implements dual carbon goals that mandate cleaner manufacturing processes for domestic suppliers. India's BIS certification requirements for solar components create compliance barriers for imported coating systems. Stakeholders must monitor evolving perfluorinated substance restrictions across jurisdictions, as these chemistries underpin current hydrophobic performance leadership but face phasedown pressures from regulators in Europe and North America.
Market Dynamics
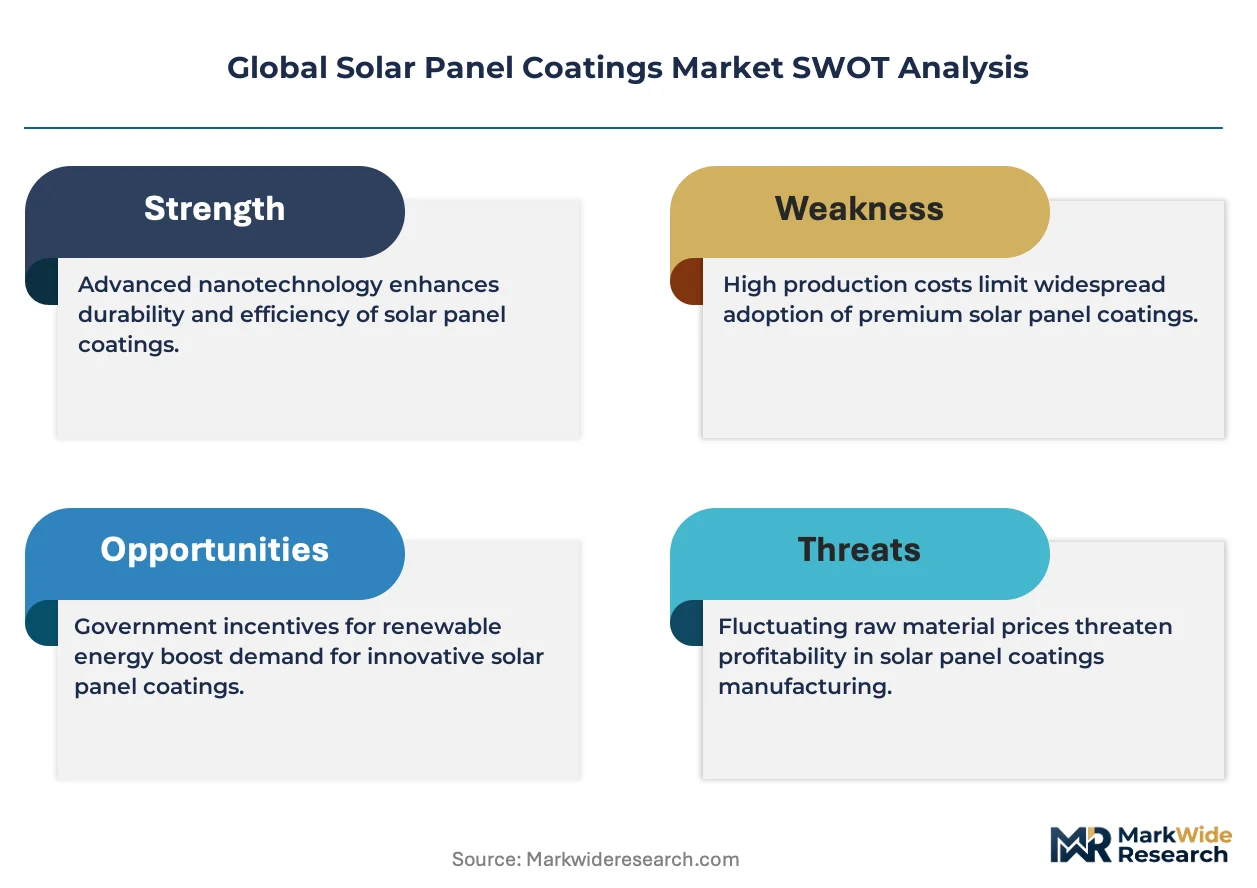
The solar panel coatings sector faces a decisive inflection as REACH compliance forces solvent-based formulation obsolescence across European supply chains, compressing margins for incumbents while opening premium positioning for fluoropolymer innovators.
Growth Catalysts
- EU Green Deal mandates:Binding clean energy targets accelerate utility-scale deployment across Germany, Spain, and Poland, creating sustained demand for high-transmission coating systems.
- Dual carbon goals in China:MEE enforcement of cleaner manufacturing processes drives domestic suppliers toward water-based coating chemistries, expanding addressable market for compliant foreign technologies.
- Anti-soiling nanocoatings:Hydrophobic formulations with dual-function anti-reflective properties capture margin premiums in desert and coastal installations where dust and salt degradation concentrate.
Market Restraints
- Perfluorinated substance restrictions:ECHA phasedown timelines for PFAS chemistries threaten hydrophobic performance leadership, forcing reformulation investments without guaranteed efficacy parity.
- Raw material concentration:Fluoropolymer resin supply concentrates among Japanese and Chinese petrochemical complexes, exposing coating formulators to input cost volatility and allocation risk.
- Technical degradation limits:Current nanocoating durability caps at 15-20 years under UV exposure, falling short of 25-year module warranties and creating performance liability exposure.
Strategic Opportunities
- India manufacturing expansion:PLI scheme subsidies for domestic photovoltaic production create captive demand for coating systems, with BIS certification requirements favoring localized technical partnerships.
- Bifacial module penetration:Rear-side glass coatings for double-sided cells represent an underaddressed application layer with distinct optical requirements from front-side formulations.
- Agrivoltaic convergence:Agricultural solar installations require coatings resistant to ammonia, pollen, and pesticide drift, opening formulation specialization beyond standard anti-soiling specifications.
Industry Challenges
- Formulation chemist scarcity:Expertise in fluoropolymer-silane hybrid systems concentrates among aging specialists in Germany and Japan, constraining R&D velocity for next-generation products.
- Multi-jurisdiction certification lag:Coating systems require sequential EPA VOC validation, REACH SVHC screening, and BIS mechanical testing, extending commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Panel Coatings Market |
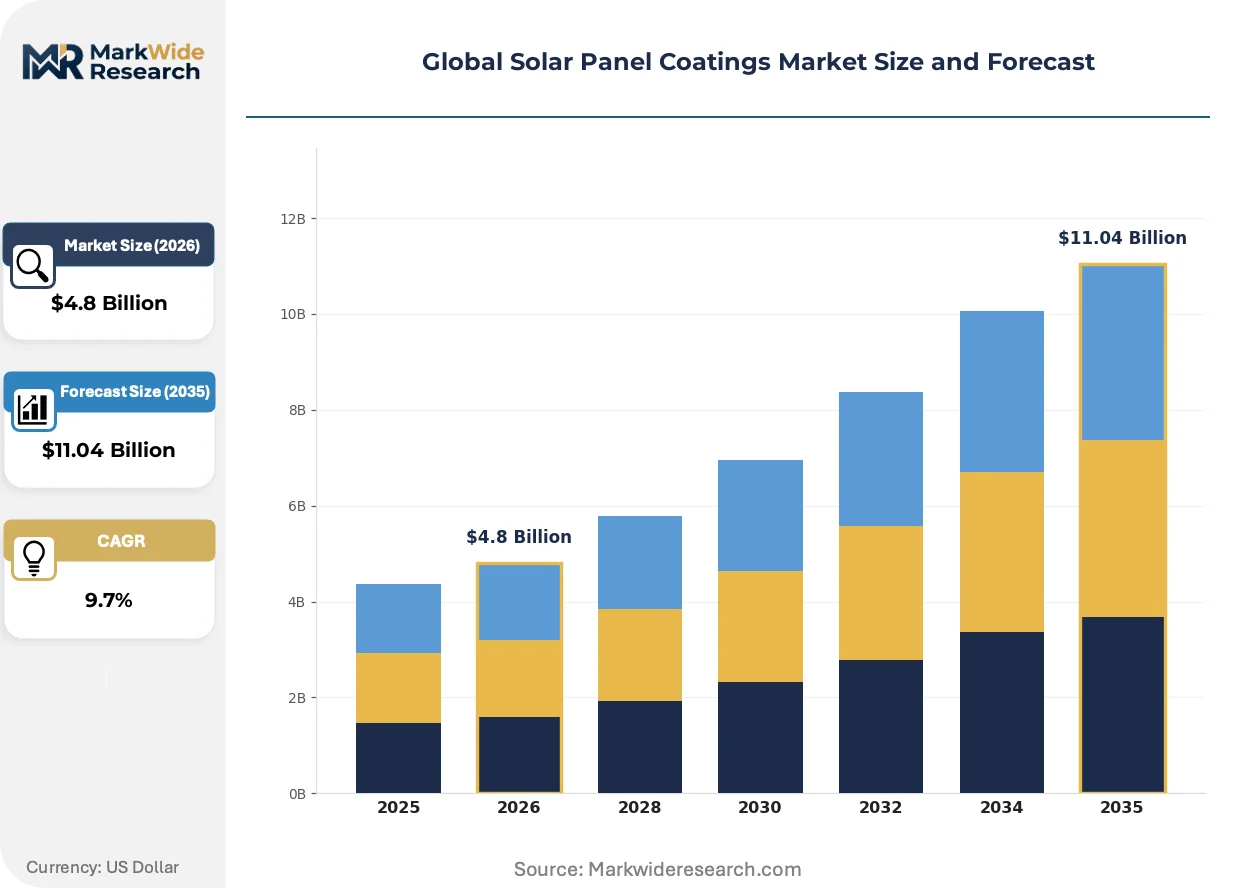
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
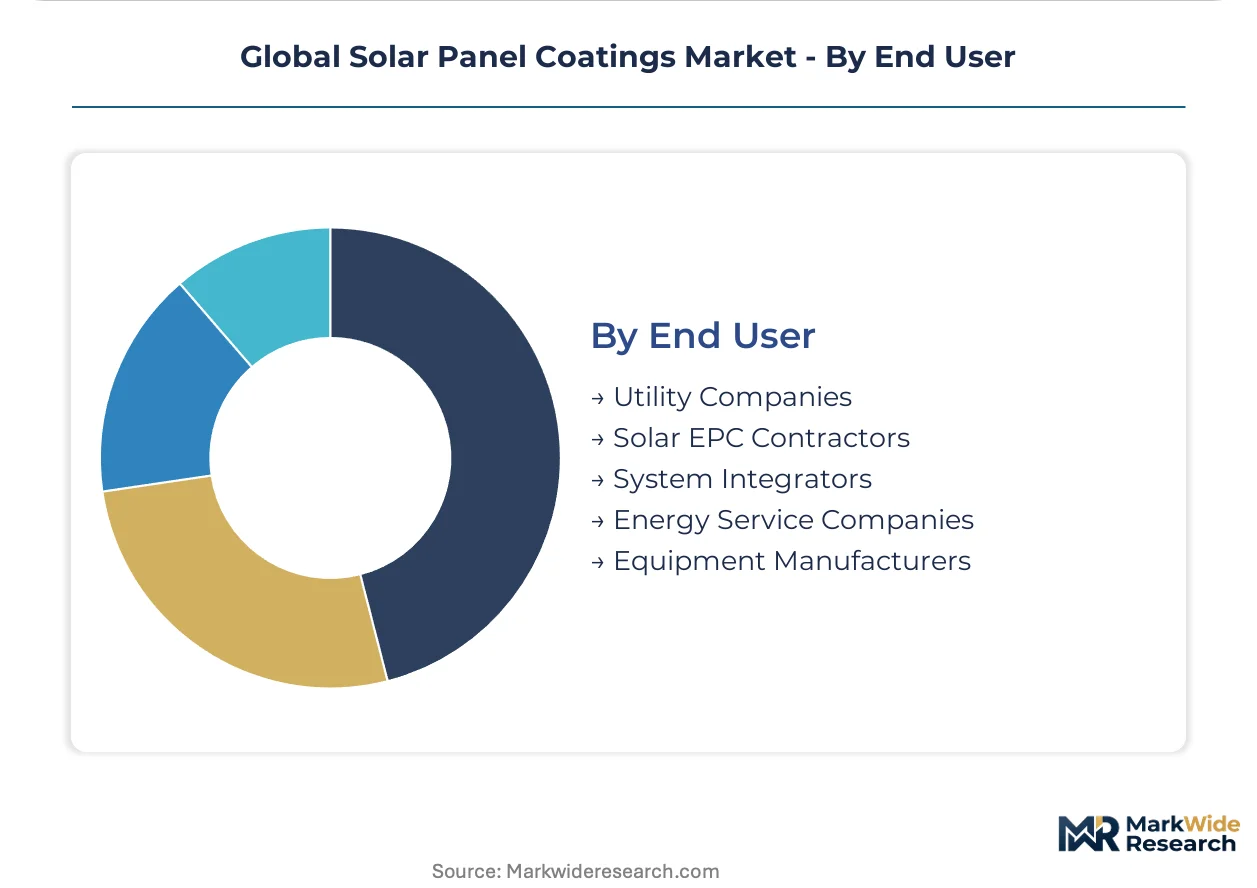
| Segmentation | Product Type: Anti-Reflective, Hydrophobic, Self-Cleaning, Anti-Soiling, Scratch Resistant Technology: Nanocoatings, Polymer-Based, Ceramic-Based, Metal Oxide, Fluoropolymer Application: Residential Systems, Commercial Arrays, Utility-Scale Farms, Building Integrated Photovoltaics, Portable Devices End User: Utility Companies, Solar EPC Contractors, System Integrators, Energy Service Companies, Equipment Manufacturers |
| Companies Covered | PPG Industries, 3M Company, Arkema Group, BASF SE, Evonik Industries AG, AkzoNobel, DuPont, Saint-Gobain, Unelko Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Panel Coatings Market Shifts & Advancements
Active materials science breakthroughs are compressing the traditional trade-off between optical performance and mechanical durability, while regulatory chemistry constraints force simultaneous process reinvention.
Atomic layer deposition of titanium dioxide-silica nanolaminates is electrifying module efficiency roadmaps. Tier-1 crystalline silicon manufacturers in South Korea and Malaysia are integrating these sub-100 nanometer stacks into mass production lines. The technology is electrifying competitive differentiation by enabling sub-2% reflection losses previously achievable only with fragile sol-gel coatings.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing hydrophobic coating reformulation across European supply chains. Formulators are pivoting toward silicone resin and hybrid inorganic-organic platforms that sacrifice some contact angle performance for regulatory survivability. German and Dutch project developers now require PFAS-free certification in procurement specifications, compressing addressable market for legacy fluoropolymer suppliers.
Utility-scale asset operators are unbundling coating warranties from module supply agreements, creating direct procurement relationships with specialized applicators. This disintermediation shifts technical specification authority from cell manufacturers to O&M service providers in the United States and Australia. Direct coating procurement enables customized performance guarantees tied to soiling rate metrics rather than generic material specifications.
Global Solar Panel Coatings Market Segmentation
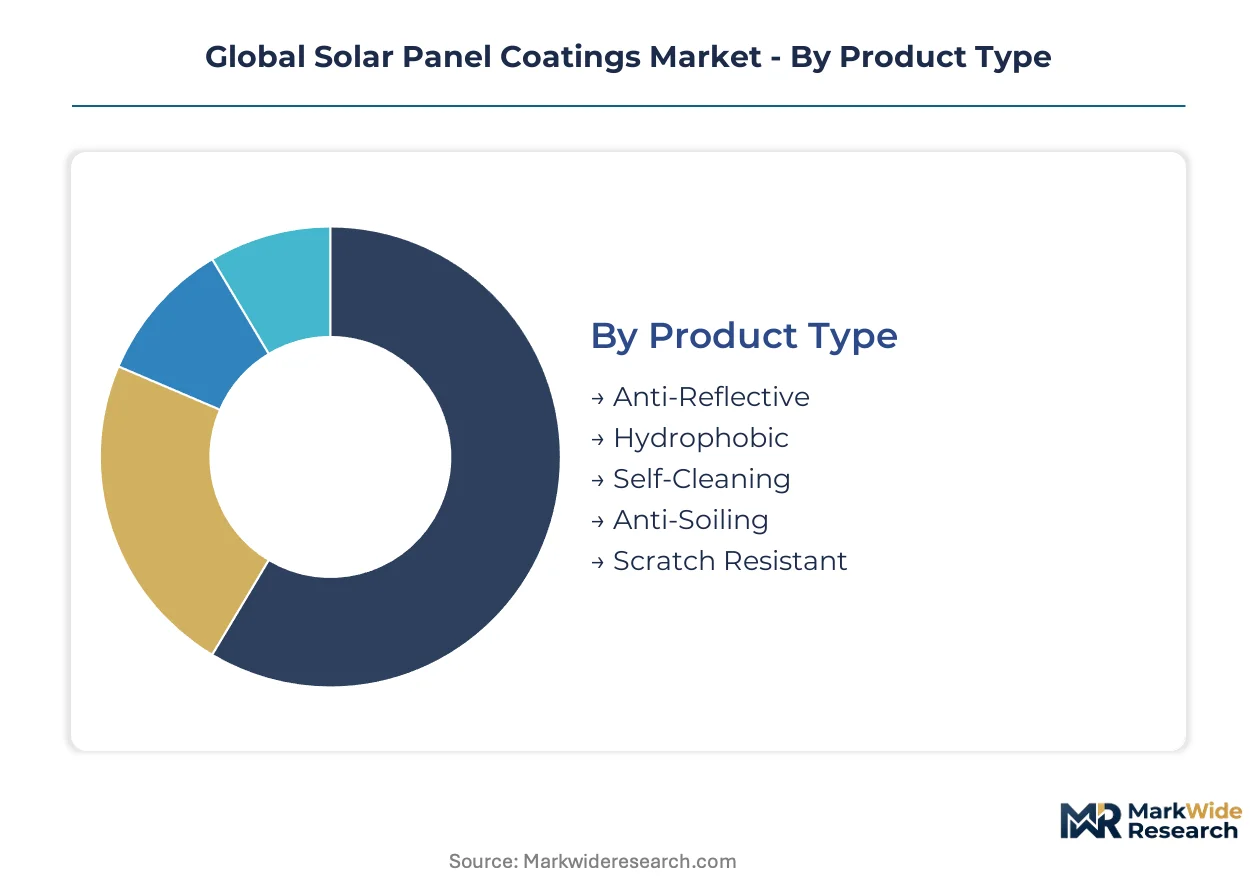
Coating specification authority fragments across module manufacturers, project developers, and O&M service providers. Each stakeholder tier prioritizes different performance vectors—optical efficiency, field durability, or lifecycle cost—creating distinct demand profiles that reshape formulation requirements and pricing architecture.
Product Type:
Anti-reflective coatings integrate universally into crystalline silicon manufacturing lines, while hydrophobic and self-cleaning formulations serve specialized deployment environments as aftermarket or premium OEM specifications.
- Anti-Reflective:Titanium dioxide-silica nanolaminates achieve sub-2% reflection losses through atomic layer deposition. Demand concentrates in South Korean and Malaysian tier-1 manufacturing lines where efficiency roadmaps mandate maximum photon capture.
- Hydrophobic:Fluoropolymer and silicone resin formulations create water-repellent surfaces with contact angles exceeding 110 degrees. Installations in Saudi Arabia and the UAE prioritize these coatings for dust mitigation in desert climates where soiling degrades yield.
- Self-Cleaning:Photocatalytic titanium dioxide layers decompose organic contaminants under UV exposure. German project developers specify these for agrivoltaic arrays facing pollen and pesticide drift accumulation.
- Anti-Soiling:Surface energy modification reduces particulate adhesion without full hydrophobicity. Coastal installations in Spain and Italy favor these formulations for salt spray resistance at lower cost than fluoropolymer alternatives.
- Scratch Resistant:Silica-based hardcoats protect glass surfaces during transportation and installation handling. Equipment manufacturers in China integrate these into bifacial module rear-side glass to prevent performance degradation from field abrasion.
Anti-Reflective coatings lead volumes today; Hydrophobic formulations are gaining share fastest.
Technology:
Process chemistry determines whether coatings deposit as standalone surface layers or embed within glass manufacturing, with profound implications for supply chain positioning and margin capture.
- Nanocoatings:Sub-100 nanometer films applied through sol-gel or vapor deposition processes. South Korean manufacturers drive adoption for dual-function anti-reflective-hydrophobic layers that compress coating steps.
- Polymer-Based:Acrylic and polyurethane formulations deliver cost-efficient barrier protection. BASF SE anchors supply relationships across German and Spanish utility-scale pipelines through scalable polymer platforms.
- Ceramic-Based:Silicon dioxide and aluminum oxide layers provide extreme hardness and thermal stability. Japanese suppliers concentrate production for high-temperature deployment environments.
- Metal Oxide:Zinc oxide and tin oxide variants enable transparent conductive functionality alongside optical management. Building-integrated photovoltaic applications in the Netherlands specify these for aesthetic and electrical integration.
- Fluoropolymer:Perfluorinated chemistries deliver unmatched hydrophobic performance and chemical resistance. REACH Annex XVII phasedown timelines force reformulation investments across European supply chains.
Polymer-Based systems dominate installed base; Nanocoatings show the steepest expansion trajectory.
Application:
Scale of installation dictates coating procurement modality—captive integration for residential modules, specification-driven selection for commercial arrays, and direct O&M contracting for utility-scale assets.
- Residential Systems:Standardized anti-reflective coatings embedded during module manufacturing. Indian rooftop deployment programs create volume concentration through domestic production incentives.
- Commercial Arrays:Performance guarantees drive specification of premium hydrophobic formulations. Australian commercial developers unbundle coating warranties from module supply to capture O&M cost reductions.
- Utility-Scale Farms:Direct procurement relationships with specialized applicators shift technical authority from manufacturers to asset operators. US and Middle Eastern operators now specify soiling rate metrics rather than material properties.
- Building Integrated Photovoltaics:Aesthetic and structural requirements demand customized optical properties. German architectural integration projects prioritize neutral color rendering alongside efficiency.
- Portable Devices:Flexible substrate coatings for off-grid and mobile applications. Chinese manufacturers serve camping and marine segments with lightweight, abrasion-resistant formulations.
Utility-Scale Farms anchor revenue concentration today; Building Integrated Photovoltaics are climbing the fastest.
End User:
Technical specification authority varies dramatically—equipment manufacturers control front-side glass coating integration, while energy service companies and EPC contractors increasingly dictate aftermarket and rear-side applications.
- Utility Companies:Direct coating procurement for O&M optimization unbundles warranties from module supply. US independent power producers lead this disintermediation trend.
- Solar EPC Contractors:Procurement specifications for project completion drive coating selection during construction phase. Indian PLI scheme beneficiaries favor domestic BIS-certified systems.
- System Integrators:Turnkey solution design incorporates coating performance into overall energy yield models. German integrators specify PFAS-free certification to preempt regulatory liability.
- Energy Service Companies:Performance contracting structures align coating investment with measured output gains. Spanish ESCOs pioneer soiling-rate-based guarantee structures.
- Equipment Manufacturers:Captive coating integration into module production lines. Chinese and South Korean tier-1 manufacturers internalize anti-reflective deposition through vertical manufacturing control.
Equipment Manufacturers capture the largest addressable market today; Energy Service Companies are expanding their specification influence most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists in Germany and Japan anchor global coating innovation, while manufacturing scale concentrates in Chinese and South Korean photovoltaic clusters.
China
Domestic module production exceeding 80% of global output drives captive coating demand across Jiangsu and Zhejiang provinces. The Ministry of Ecology and Environment enforces dual carbon goals that mandate water-based chemistry transitions for domestic suppliers. Changzhou hosts concentrated fluoropolymer resin production serving tier-1 manufacturers integrating anti-reflective deposition lines.
United States
Utility-scale deployment in Texas and California creates aftermarket coating procurement by independent power producers. The EPA maintains VOC emission thresholds that constrain solvent-based formulation chemistry for domestic applicators. Arizona's desert installations prioritize hydrophobic specifications for dust mitigation in utility-scale arrays.
Germany
Agrivoltaic project expansion in Bavaria and Baden-Württemberg drives specialized coating demand for ammonia and pesticide resistance. REACH Annex XVII phasedown timelines for PFAS chemistries force reformulation investments across European supply chains. Dresden's materials science cluster advances atomic layer deposition for sub-100 nanometer nanolaminates.
India
Production-linked incentive scheme subsidies for domestic photovoltaic manufacturing create captive coating system demand. The Bureau of Indian Standards certification requirements for solar components create compliance barriers favoring localized technical partnerships. Gujarat's Mundra and Dahej industrial corridors concentrate new module fabrication capacity with integrated coating lines.
Saudi Arabia
Desert utility-scale installations in Al-Qassim and Tabuk regions prioritize hydrophobic formulations for dust accumulation mitigation. The Saudi Standards, Metrology and Quality Organization implements technical regulations for solar component imports. NEOM's renewable energy megaproject specifies premium anti-soiling coatings for sustained performance in extreme aridity.
Global Solar Panel Coatings Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with fluoropolymer expertise. Five to eight major suppliers capture the majority of formulation supply relationships, with tier-2 specialists serving regional aftermarket applicators. Strategic archetypes include integrated resin-to-coating manufacturers, licensed technology platforms, and O&M service partnerships. Capacity expansion in Asian manufacturing hubs and technology licensing for PFAS-free alternatives represent dominant competitive moves.
Among diversified coating specialists, PPG Industries and BASF SE occupy positions reflecting distinct strategic emphases. PPG Industries exemplifies fluoropolymer innovation leadership in premium anti-soiling applications. BASF SE anchors supply relationships through scalable polymer-based platforms across European utility-scale pipelines. Arkema Group represents French chemical conglomerate participation in advanced materials for photovoltaic applications.
| Leading Market Players |
|---|
| PPG Industries |
| 3M Company |
| Arkema Group |
| BASF SE |
| Evonik Industries AG |
| AkzoNobel |
| DuPont |
| Saint-Gobain |
| Unelko Corporation |
| Others |
Supply & Pricing Matrix
Fluoropolymer resin indices from Changzhou and Osaka petrochemical complexes cascade through three distinct pricing tiers, compressing margins for solvent-based formulators while elevating premiums for REACH-compliant hydrophobic systems in European procurement.
Pricing Analysis
Bundled OEM coating integration competes against unbundled direct procurement by utility-scale operators, with pricing stratifying across premium fluoropolymer, standard polymer-based, and economy water-based acrylic tiers. Price differentiation hinges on ECHA PFAS certification status and volume scale commitments from tier-1 module manufacturers. Cost compression in standard-tier formulations is intensifying because MEE-mandated water-based chemistry transitions raise production overheads for Chinese domestic suppliers. Residential system integrators exhibit highest price sensitivity, while Middle Eastern IPPs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Container freight rates from Shanghai to Hamburg directly impact landed costs for Japanese fluoropolymer resins, reshaping procurement calendars for European formulators. Raw material supply concentrates in China, Japan, and South Korea, with coating formulators drawing from concentrated petrochemical complexes in Jiangsu and Osaka. Fluoropolymer resin allocation risk represents the dominant structural vulnerability, as tier-1 module manufacturers secure multi-year offtake agreements. Distribution runs through module OEM captive integration for anti-reflective coatings, while hydrophobic and self-cleaning formulations reach end-users via specialized applicator networks and O&M service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar panel coatings market functions as a regulatory compounder, with EU Green Deal binding targets and REACH Annex XVII phasedowns creating sustained demand displacement toward compliant formulation platforms.
For Market Incumbents: Lock in fluoropolymer-silane hybrid R&D capacity through technical partnerships with Dresden and Osaka materials science clusters, preempting formulation chemist scarcity. Deepen backward integration into titanium dioxide-silica nanolaminate deposition equipment to capture atomic layer deposition adoption curves. Defend against PFAS-free silicone resin substitutes by accelerating REACH-compliant hydrophobic certification pipelines. For New Entrants and Emerging Players: Atomic layer deposition equipment leasing models offer a technology-first wedge into South Korean and Malaysian tier-1 manufacturing lines seeking sub-2% reflection losses without capital-intensive in-house buildout. White-space concentration appears in bifacial rear-side glass coatings and agrivoltaic ammonia-resistant formulations, with Indian PLI scheme beneficiaries representing the most penetrable customer segment. A certification-first go-to-market strategy targeting BIS compliance for Gujarat manufacturing corridors accelerates commercial traction. For Investors and Strategic Acquirers: Asymmetric upside sits with PFAS-free formulation specialists holding validated silicone-hybrid intellectual property ahead of ECHA enforcement timelines. Long-term viability across the analysis window favors acquisition targets with demonstrated atomic layer deposition process integration and established utility-scale O&M service relationships. Watch for Saudi NEOM and Indian National Solar Mission procurement specifications as inflection signals for premium anti-soiling coating demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Certification | ECHA Annex XVII compliance unlocks German and Dutch utility-scale procurement specifications ahead of phasedown deadlines. |
| Atomic Layer Deposition Partnership | Sub-100 nanometer nanolaminate integration with South Korean tier-1 manufacturers captures sub-2% reflection loss roadmaps. |
| Backward Integration into Resin Production | Captive fluoropolymer supply from Changzhou or Osaka complexes mitigates allocation risk and input cost volatility. |
| BIS Certification Localization | Indian PLI scheme compliance creates preferential access to Gujarat and Tamil Nadu module fabrication capacity expansion. |
| Agrivoltaic Formulation Development | Ammonia and pesticide-resistant coatings address Bavarian and Baden-Württemberg agricultural solar installation specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating formulators, module OEM procurement leads, EPC contractors, and utility-scale O&M directors with secondary validation from ECHA REACH filings, MEE dual carbon enforcement notices, BIS certification registries, and customs trade data for fluoropolymer resin flows. Bottom-up coating volume estimates from individual manufacturing facilities triangulated against top-down module production forecasts across the analysis window.
Segment-weighting approaches distributed value and volume projections across product type, technology platform, application scale, and end-user specification authority dimensions. CAGRs derived from regression analysis of historical coating adoption rates against module efficiency roadmaps and regulatory milestone timelines. Industry-specific forecast inputs incorporated atomic layer deposition equipment deployment schedules and PFAS phasedown enforcement probability assessments.
The model holds under sustained EU Green Deal implementation and MEE dual carbon enforcement; deviation in ECHA PFAS restriction acceleration or fluoropolymer resin supply disruption would shift volume trajectories. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Vietnam Architectural Coatings Market
Coatings
Silicone Coating Market
Coatings
Pure Epoxy Powder Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
Global Waterborne Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Corrosion Protection Coating Market
Coatings
Mexico Floor Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
Gelcoat Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Electrically Conductive Coating Market
Coatings
Conductive Coatings Market
Coatings
Waterborne Wood Coatings Market
Coatings
E-Coat Market