
 Industrial Liquid Coating Market | 2026-2036
Industrial Liquid Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Liquid Coating Market Analysis
Modular coating service packages is expanding as a procurement pattern, allowing automotive and heavy machinery buyers to bundle application technology with resin supply. PPG Industries leverages its captive spray-application equipment division to anchor multi-year supply contracts. Sherwin-Williams differentiates through controlled distribution networks spanning North American manufacturing corridors. Akzo Nobel N.V. competes on R&D intensity in low-VOC acrylic platforms.
Industrial liquid coating denotes a fluid-applied protective or decorative layer, typically 25–150 microns dry-film thickness, comprising binders, pigments, solvents or water carriers, and functional additives cured through ambient oxidation or thermal crosslinking. Its primary purpose is to confer corrosion resistance, chemical protection, and aesthetic finish to metal, composite, or concrete substrates in factory and field settings. Epoxy formulations dominate marine and heavy machinery maintenance cycles due to superior adhesion and chemical resistance. Polyurethane segments capture premium automotive and aerospace refinishing demand where gloss retention and weatherability command price premiums. Spray application technology leads volume throughput in manufacturing settings, though dip coating sustains share in standardized small-part processing.
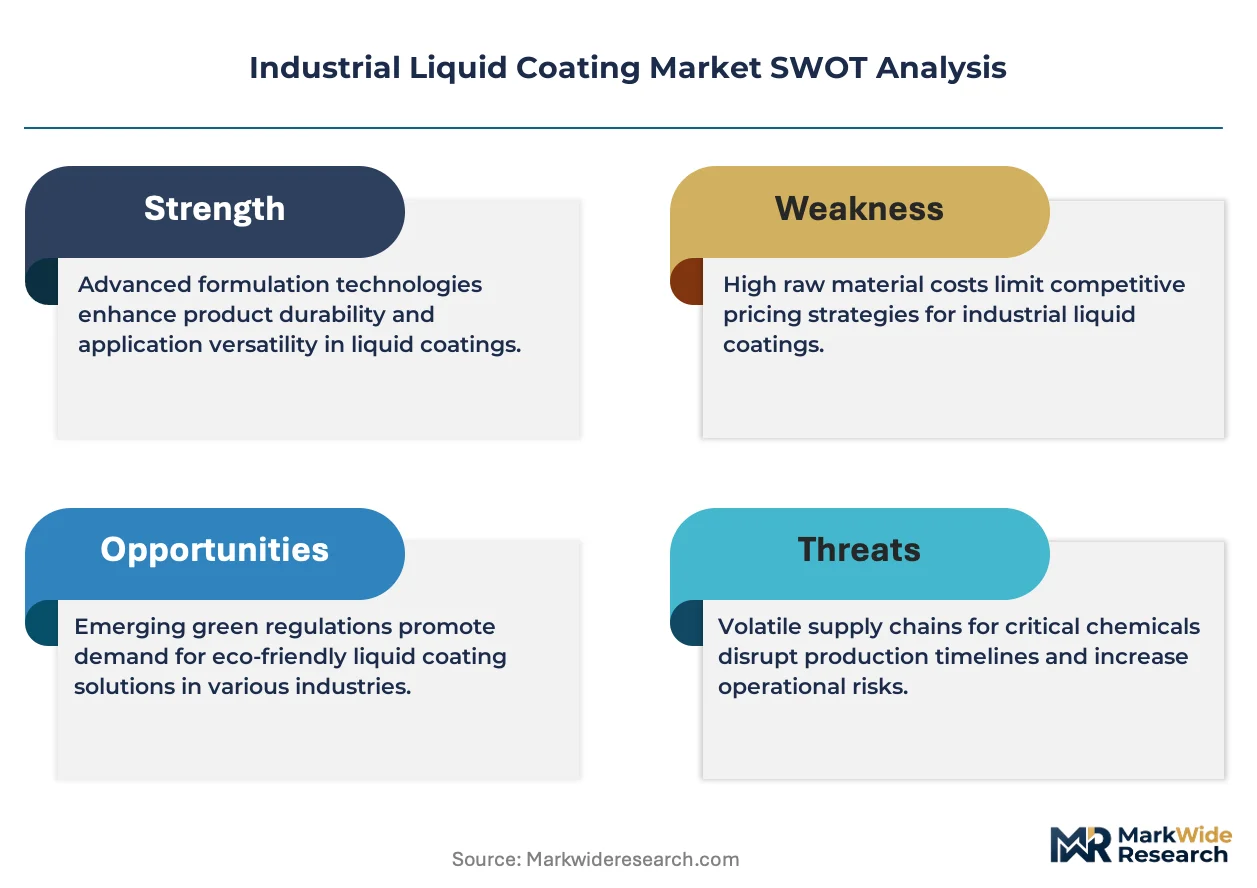
EPA VOC rules under the National Emission Standards for Hazardous Air Pollutants constrain solvent-borne formulation choices in US manufacturing facilities, while REACH registration requirements in Europe elevate compliance costs for imported resin systems. China's MEE enforces progressively stricter emission limits on coating operations in the Yangtze and Pearl River manufacturing belts. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate product portfolios and capital allocation across regional production networks.
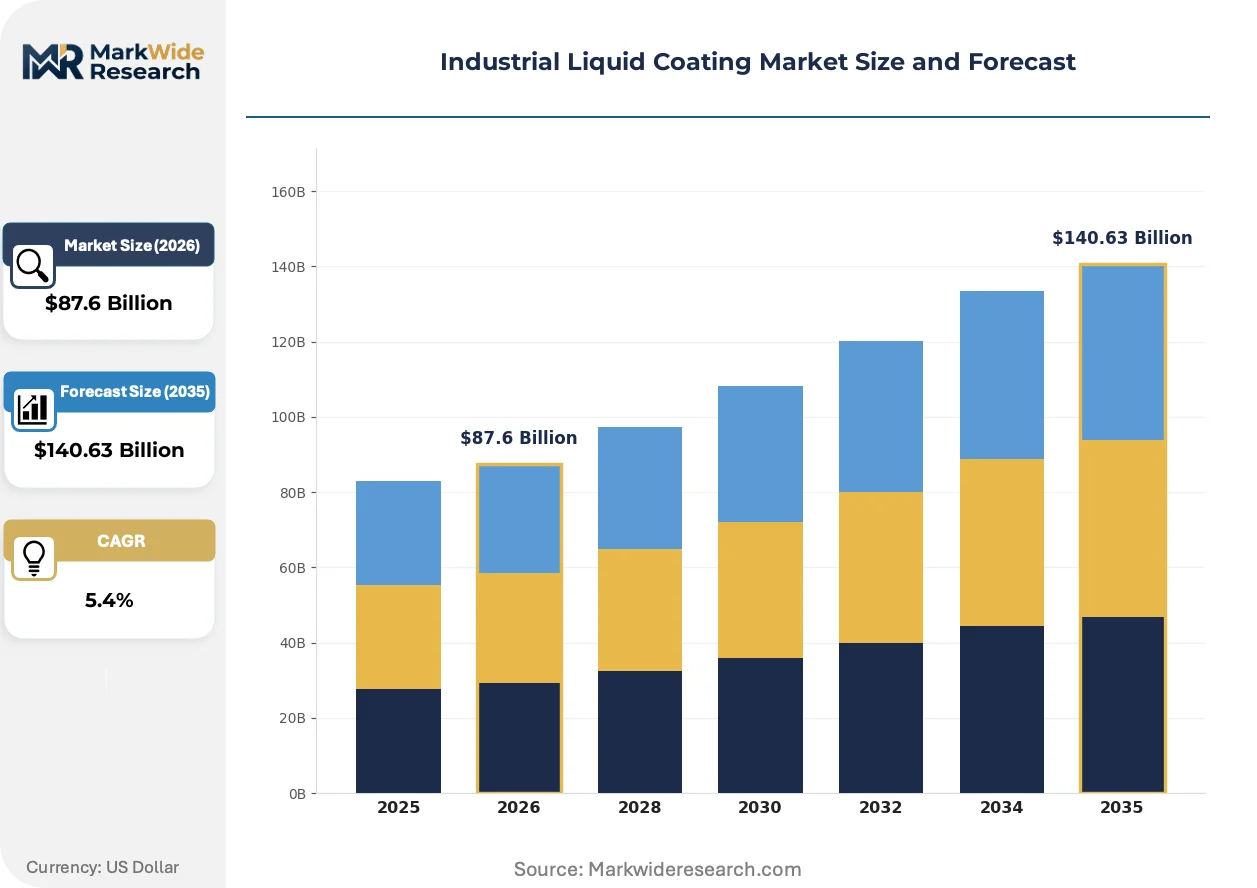
Market Dynamics
REACH and EPA VOC emission limits are redirecting R&D budgets toward compliant resin systems, compressing solvent-borne formulation margins while elevating water-borne and high-solids platforms.
Growth Catalysts
- Automotive OEM specification shifts:Premium vehicle manufacturers are mandating low-VOC polyurethane clearcoats for exterior refinishing, pulling formulation upgrades across supplier tiers.
- China MEE enforcement waves:Progressive emission limits across Yangtze and Pearl River manufacturing belts are accelerating capital replacement in coating operations.
- Epoxy marine maintenance cycles:Extended dry-docking intervals for commercial shipping fleets are expanding high-performance anti-corrosive coating consumption.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and isocyanate precursor costs fluctuate with crude oil and propylene markets, compressing blended margin stability.
- Specialty additive supply concentration:Wetting agents and UV stabilizers concentrate among German and Japanese chemical suppliers, creating single-source vulnerability.
- Solvent-borne technical ceiling:REACH registration thresholds block incremental reformulation pathways for legacy high-VOC systems in European facilities.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for domestic manufacturing are pulling coating demand into Gujarat and Tamil Nadu automotive clusters.
- Wind turbine blade protection:Offshore wind installations require specialized polyurethane topcoats with extended weatherability guarantees.
- Digital color-matching platforms:Cloud-based spectrophotometry services enable remote specification approval, compressing project timelines for architectural metal finishing.
Industry Challenges
- Formulation chemist scarcity:Expertise in hybrid water-borne polyurethane-acrylic systems remains concentrated among senior practitioners nearing retirement.
- Application equipment retrofit costs:Electrostatic spray lines require capital overhaul to handle higher-solids materials without orange-peel defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Liquid Coating Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $140.63 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Polyester Application: Automotive, Aerospace, Marine, Heavy Machinery End User: Construction, Manufacturing, Electronics, Healthcare Technology: Spray Application, Brush Application, Roller Application, Dip Coating |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Sherwin-Williams, Axalta Coating Systems, Nippon Paint, Kansai Paint Co., Ltd., RPM International, Hempel, Jotun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Liquid Coating Market Emerging Trajectories
Formulation chemistry and application technology are converging around compliance-driven performance thresholds, compressing the viable solution set while elevating premium positioning for certified systems.
High-solids 2K polyurethane technology is consolidating its position in automotive refinishing by delivering gloss retention equivalent to solvent-borne predecessors at sub-250 g/L VOC content. Tier-one collision repair networks in Germany and the US are standardizing these platforms for warranty compliance. This consolidation is compressing mid-tier solvent-borne suppliers into commodity marine and industrial maintenance segments.
REACH authorization requirements for chromium trioxide in anti-corrosive primers are forcing marine and aerospace applicators toward trivalent chrome and thin-film silane alternatives. The industrial consequence is extended qualification timelines for new pretreatment systems. European shipyards and German automotive component suppliers are most affected, accelerating in-house testing laboratory investments.
Integrated coating-service procurement is displacing discrete resin and application equipment purchasing across North American heavy machinery manufacturers. Bundled contracts anchor multi-year supply relationships with captive spray-booth technology provision. This pattern is most visible in Illinois and Ohio manufacturing corridors where capital equipment financing constraints favor operational expenditure models.
Industrial Liquid Coating Market Segmentation
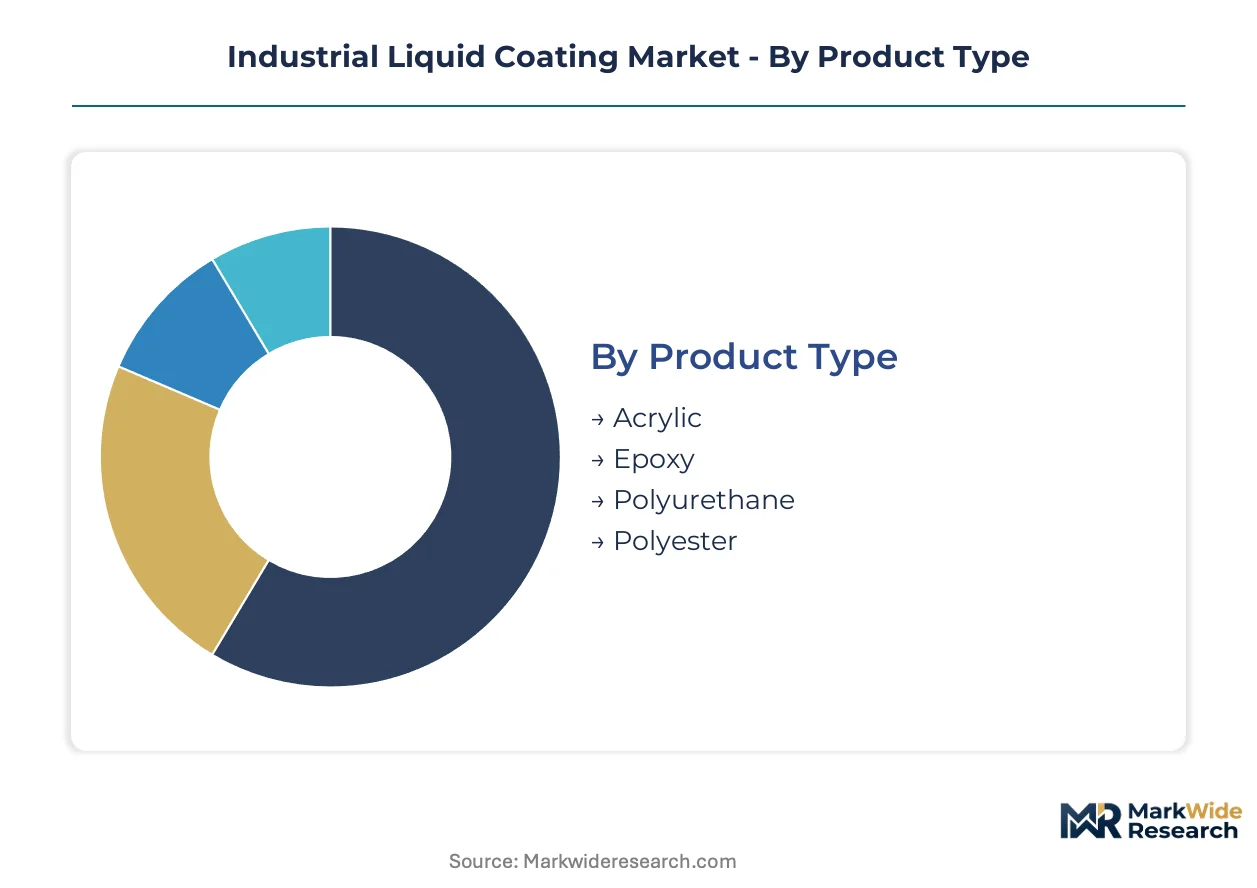
Segmentation in industrial liquid coatings reveals how formulation chemistry, application method, and end-use requirements create distinct commercial battlegrounds. Each dimension carries different margin profiles, regulatory exposure, and customer concentration that shape supplier strategy.
Product Type:
Customization intensity varies sharply across resin platforms, from standardized commodity polyesters to specification-locked aerospace polyurethanes.
- Acrylic:Water-borne acrylic emulsions dominate architectural metal finishing and light industrial applications where low-VOC compliance meets cost sensitivity. Demand concentrates in German automotive component supply chains, where REACH registration costs favor established resin producers with in-house toxicology capabilities.
- Epoxy:Two-component amine-cured systems deliver superior chemical resistance and substrate adhesion for marine maintenance and heavy equipment refurbishment. Shipyards in China's Yangtze River manufacturing belt anchor volume consumption, though MEE emission enforcement is accelerating shifts toward high-solids variants.
- Polyurethane:Aliphatic isocyanate-based topcoats command premium positioning in automotive refinishing and wind turbine blade protection.
- Polyester:Saturated polyester resins serve powder coating liquid analogs in appliance and general industrial finishing.
Leading the category by volume: Epoxy. Growing fastest: Polyurethane.
Application:
Application segments separate by qualification burden and coating performance guarantees, from crash-test-validated automotive systems to field-applied marine maintenance.
- Automotive:OEM clearcoat specifications mandate polyurethane platforms with 10-year gloss retention warranties, locking supplier relationships through multi-year qualification cycles. Tier-one collision repair networks in the US Midwest standardize water-borne basecoat systems to meet EPA NESHAP compliance.
- Aerospace:MIL-SPEC-qualified epoxy primers and polyurethane topcoats require extensive flame-resistance and fluid-resistance testing. Qualification timelines stretch 18-24 months, concentrating procurement among incumbent suppliers with established OEM maintenance manuals.
- Marine:Anti-corrosive epoxy systems for commercial shipping face extended dry-docking intervals, expanding high-build coating consumption per vessel.
- Heavy Machinery:Field-applied maintenance coatings prioritize application speed and substrate tolerance over cosmetic finish.
Automotive generates the highest revenue per liter. Aerospace shows the steepest expansion trajectory.
End User:
End-user concentration determines contract structure, from project-based construction procurement to integrated manufacturing supply agreements.
- Construction:Architectural metal finishing for commercial facades and infrastructure projects drives specification-grade fluoropolymer and silicone-modified polyester demand. Digital color-matching platforms are compressing approval timelines for custom metallic effects.
- Manufacturing:Captive coating operations in automotive and heavy machinery plants favor bundled resin-plus-application-equipment contracts. Illinois and Ohio manufacturing corridors show the strongest integrated procurement adoption.
- Electronics:Conformal coating applications for circuit board protection require ultra-low-VOC precision spray systems.
- Healthcare:Medical device finishing demands biocompatible epoxy and polyurethane systems with extensive extractables testing.
Manufacturing dominates absolute volume. Healthcare offers the highest margin expansion potential.
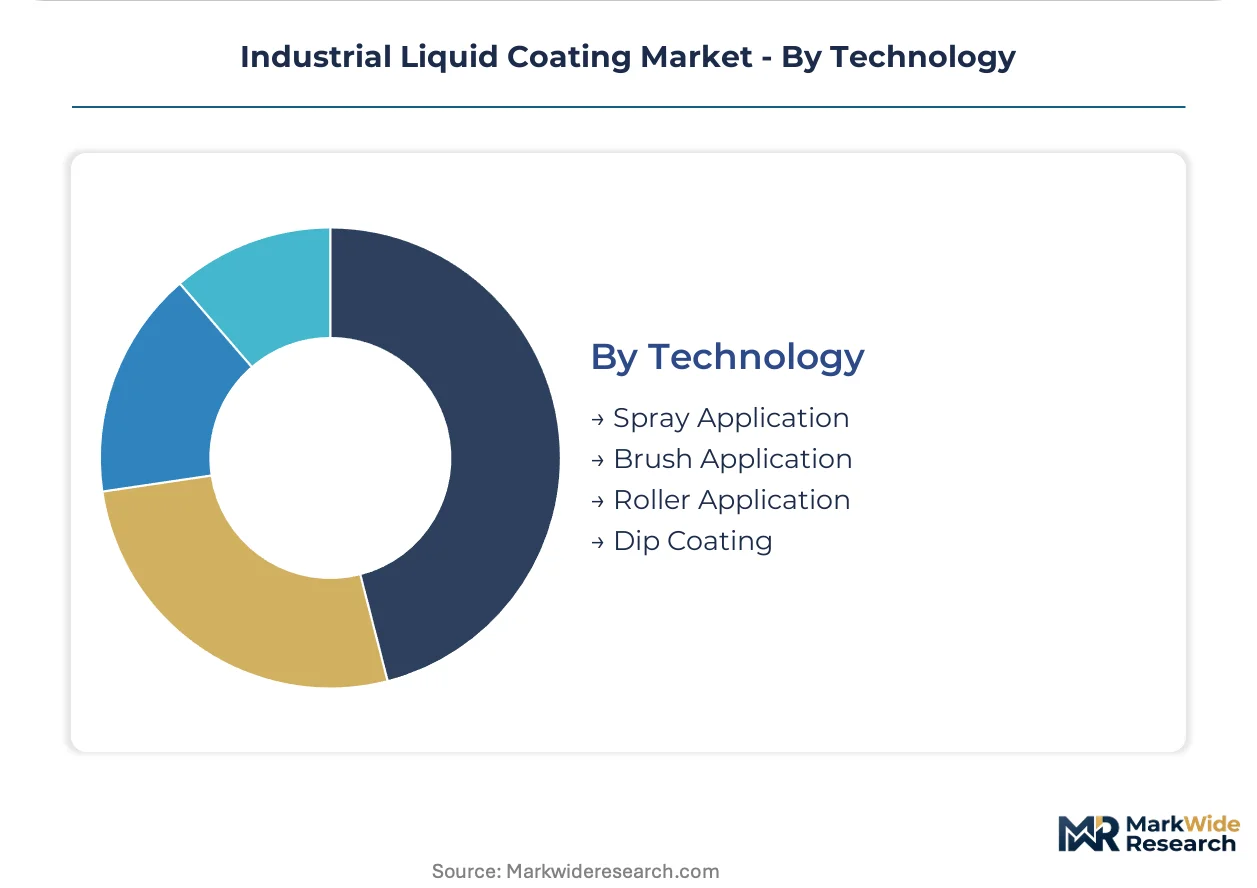
Technology:
Technology segments align with production scale and part geometry complexity, from high-throughput automated lines to precision manual touch-up.
- Spray Application:Electrostatic and airless spray systems dominate automotive OEM and tier supplier operations, with robotic integration enabling consistent film builds on complex geometries. Capital equipment retrofit requirements for higher-solids materials are constraining mid-tier manufacturer upgrades.
- Dip Coating:Immersion systems sustain share in standardized small-part processing for fasteners, brackets, and stampings. Gujarat and Tamil Nadu automotive clusters in India are installing new dip lines under PLI scheme incentives.
- Brush Application:Manual touch-up and field repair operations in marine and heavy machinery maintenance favor brush and roller methods.
- Roller Application:Large flat surfaces in construction and tank lining applications use roller methods for controlled film build.
Spray application leads by installed base. Dip coating is gaining share fastest in emerging manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in China, Germany, and India while consumption growth accelerates across automotive clusters in these same markets. The regulatory divergence between EPA, REACH, and MEE enforcement is fragmenting formulation strategies by geography.
United States
Automotive OEM clearcoat specifications and heavy machinery refurbishment drive formulation demand across Michigan and Ohio manufacturing corridors. EPA NESHAP rules constrain solvent-borne systems in Tier 1 supplier facilities. Illinois-based collision repair networks standardize water-borne basecoat platforms to meet compliance timelines.
Germany
Premium vehicle manufacturers mandate low-VOC polyurethane systems with decade-long gloss retention warranties. REACH authorization requirements for chromium trioxide force marine and aerospace applicators toward trivalent chrome alternatives. Bavarian automotive component suppliers accelerate in-house testing laboratory investments to compress qualification cycles.
China
Commercial shipping fleet maintenance and wind turbine blade protection expand epoxy and polyurethane consumption along coastal provinces. MEE emission enforcement waves across Yangtze and Pearl River manufacturing belts accelerate capital replacement in coating operations. Shanghai and Guangzhou automotive clusters anchor volume demand for compliant resin systems.
India
PLI scheme incentives pull coating demand into Gujarat and Tamil Nadu automotive manufacturing corridors. BIS standards for industrial finishing create compliance thresholds for imported resin formulations. Ahmedabad and Chennai industrial zones install new dip coating lines to serve standardized small-part processing for domestic OEM supply chains.
Industrial Liquid Coating Market Vendor Landscape
The competitive structure tilts toward integrated coating-service bundling over discrete resin supply. Three tiers populate the vendor map: multinational chemical conglomerates with captive application technology divisions, regional specialists with controlled distribution networks, and formulation-focused innovators concentrating R&D intensity in compliant resin platforms. Capacity expansion and strategic partnerships dominate competitive moves, with players securing multi-year supply contracts through equipment financing arrangements.
Within the multinational tier, Akzo Nobel N.V., PPG Industries, and Sherwin-Williams occupy distinct positioning vectors. Akzo Nobel N.V. exemplifies R&D-intensive specialization in low-VOC acrylic platforms. PPG Industries anchors integrated procurement patterns through its captive spray-application equipment division. Sherwin-Williams represents controlled distribution network dominance across North American manufacturing corridors. These three entities collectively illustrate how formulation chemistry, application technology, and channel control separate competitive positions in this market.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries |
| Sherwin-Williams |
| Axalta Coating Systems |
| Nippon Paint |
| Kansai Paint Co., Ltd. |
| RPM International |
| Hempel |
| Jotun |
| Others |
Supply Flow & Price Mechanics
EPA NESHAP emission mandates gate qualified supply for Tier 1 automotive suppliers while propping premium-tier pricing access for compliant water-borne and high-solids formulations. REACH registration costs in Europe and MEE enforcement in China fragment regional pricing power, concentrating margin capture among resin producers with captive toxicology and application technology capabilities.
Pricing Analysis
Margin tightening in solvent-borne formulations reflects feedstock volatility in epoxy resin and isocyanate precursors tied to propylene markets. The market operates on a contract-based long-term offtake structure with three-tier pricing stratification across certified low-VOC systems, standard high-solids platforms, and legacy solvent-borne commodities. Price differentiation rests on certification grade—REACH-registered and EPA-compliant formulations command 15-30% premiums—and volume scale through multi-year automotive OEM contracts. Cost-down pressure on mid-tier suppliers accelerates as Chinese MEE enforcement waves compress demand for non-compliant systems. Tier 1 automotive buyers show lowest price sensitivity due to warranty liability exposure, while general industrial maintenance buyers prioritize unit cost over compliance certification.
Supply Chain Analysis
Formulation chemist scarcity in Germany and the US Midwest constrains batch consistency for hybrid water-borne polyurethane-acrylic systems. Supply concentrates in China, Germany, and India, with epoxy resin production anchored in the Yangtze River manufacturing belt and specialty aliphatic isocyanates drawing from German and Japanese chemical suppliers. Raw material dependencies include petrochemical-derived epoxy precursors, trivalent chrome alternatives for anti-corrosive primers, and UV stabilizers concentrated among Japanese additive specialists. Single-source vulnerability in wetting agents and UV stabilizers creates qualification risk for marine and aerospace applicators. Distribution runs through controlled networks spanning North American manufacturing corridors and direct technical service relationships with automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemist availability acts as the binding capacity constraint, propping pricing for qualified water-borne and high-solids systems across automotive and marine segments.
For Market Incumbents: Deploy backward integration into specialty additive supply to mitigate single-source vulnerability in German and Japanese wetting agent channels. Anchor multi-year contracts through captive spray-application equipment financing, locking Tier 1 automotive relationships against emerging water-borne specialists. Accelerate in-house toxicology laboratory investments to compress REACH qualification timelines for trivalent chrome primer alternatives. For New Entrants and Emerging Players: Begin with Gujarat and Tamil Nadu automotive clusters under India's PLI scheme incentives, where dip coating standardization creates lower qualification barriers than spray-application OEM supply. Target field-applied heavy machinery maintenance segments where substrate tolerance requirements exceed cosmetic finish standards, reducing R&D intensity versus automotive clearcoat specifications. Pursue digital color-matching platform partnerships to compress architectural metal finishing approval timelines without legacy spectrophotometry infrastructure. For Investors and Strategic Acquirers: Bavarian automotive component suppliers accelerating in-house testing laboratory investments is the leading indicator that REACH authorization timelines are compressing competitive windows for chromium trioxide alternatives. Frame long-term viability around formulation chemistry capabilities in hybrid water-borne systems, where practitioner scarcity concentrates value in acquired technical teams. Monitor China MEE enforcement wave announcements as the signal for capital replacement cycles in Yangtze and Pearl River coating operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Additives | Mitigates single-source vulnerability in Japanese UV stabilizer channels for marine applicators. |
| Green Manufacturing Transition | Accelerates water-borne polyurethane platform adoption for EPA NESHAP compliance in Midwest collision repair networks. |
| Long-term Supply Agreement | Locks multi-year resin-plus-equipment bundles with Illinois and Ohio heavy machinery manufacturers. |
| Joint Venture | Combines German R&D intensity with India PLI scheme access for Gujarat automotive cluster penetration. |
| Capacity Expansion | Adds high-solids epoxy batch capacity to serve extended dry-docking intervals in China's commercial shipping fleet. |
Methodological Framework
Multi-period observation of EPA NESHAP compliance timelines, REACH authorization waves, and China MEE enforcement announcements anchored the trend analysis, supplemented by interviews with formulation R&D directors, automotive OEM procurement leads, marine coating applicators, and specialty chemical distribution channel managers. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed coating producers, and regulatory filing databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices modeled demand drivers across resin chemistry platforms, application technology segments, and end-use industry concentrations. Segmentation dimensions included formulation type, application method, end-user industry, and regional regulatory cluster. CAGRs derived from regression analysis of historical consumption patterns against automotive production forecasts, shipyard dry-docking schedules, and wind turbine installation projections. Industry-specific inputs captured VOC regulatory phase-in schedules and formulation qualification timeline distributions.
Underlying measurement precision varies by segment; automotive OEM specifications carry tighter precision than fragmented marine maintenance demand. Forecasts incorporate assumptions around regulatory enforcement consistency, feedstock price stability, and chemist workforce availability. Material deviation in EPA, REACH, or MEE rulemaking timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Trim Coatings Market
Coatings
Global Fluorinated Ethylene Propylene (FEP) Coatings Market
Coatings
Urethane Surface Coatings Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
2K Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Polysiloxane Coatings Market
Coatings
Carbon Fiber Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Gelcoat Market
Coatings
South Korea Protective Coatings Market
Coatings
Global Flat Glass Coatings Market
Coatings
Paper Coating Binders Market