
 Canada Protective Coatings Market | 2026-2036
Canada Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Protective Coatings Market Outlook
Asset-light leasing models for coating application equipment are reshaping competitive entry in the Canada Protective Coatings Market. PPG Industries Inc. leverages its broad distribution network to serve remote oil and gas installations across Alberta and Saskatchewan. AkzoNobel NV anchors its position through specialized marine and industrial formulations tailored to Canadian climatic extremes. RPM International Inc. competes via targeted product lines for infrastructure maintenance contractors in Ontario and Quebec.
Canada protective coatings are multi-layer formulations—typically incorporating epoxy primers, polyurethane topcoats, or acrylic barriers—engineered to prevent substrate corrosion, chemical degradation, and UV-induced weathering in temperatures ranging from -40°C to humid summer conditions. Their primary purpose is extending asset life for steel and concrete structures exposed to aggressive Canadian environmental cycles. Epoxy coatings dominate heavy industrial applications where chemical resistance and substrate adhesion prove critical, while water-based technologies are gaining fastest conversion as PMRA and provincial environmental agencies tighten solvent emission thresholds. Powder coating occupies a narrower but high-margin niche in manufacturing and automotive parts finishing, where zero-VOC compliance and durable factory-applied films justify capital-intensive electrostatic lines.
Health Canada's PMRA regulates biocidal and antimicrobial additives in coating formulations, while provincial environmental ministries enforce VOC content limits aligned with Canadian Environmental Protection Act schedules. The Canadian Standards Association certifies performance benchmarks for fire-resistant and intumescent systems used in commercial construction. CSA S16 and National Building Code provisions further shape product qualification for structural steel protection. Stakeholders must monitor evolving federal carbon pricing mechanisms and provincial clean-fuel regulations that could alter raw material sourcing economics for resin and solvent suppliers serving Canadian formulators.
Market Dynamics
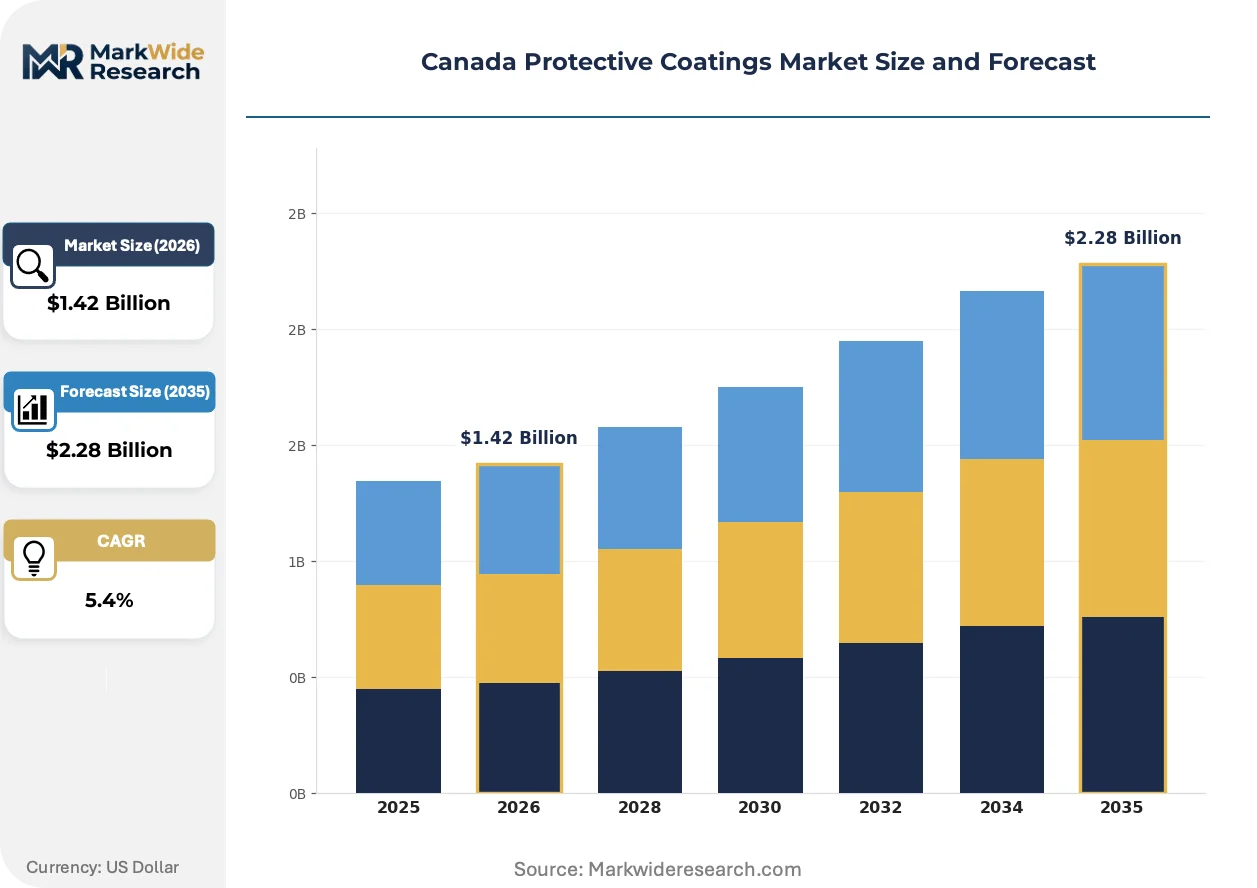
Health Canada's PMRA is tightening VOC emission thresholds under the Canadian Environmental Protection Act, forcing formulators to abandon solvent-borne systems and rebuild supply chains around water-based and powder technologies.
Growth Catalysts
- Infrastructure renewal mandates:Ontario's bridge rehabilitation program and Alberta's pipeline integrity regulations are accelerating specification of high-performance epoxy and polyurethane systems for steel protection.
- PMRA regulatory pressure:Federal biocide registration requirements are filtering out low-investment competitors and consolidating procurement around certified suppliers with compliant antimicrobial additives.
- Oil sands maintenance cycles:Suncor and Canadian Natural Resources facilities in Fort McMurray are driving recurring demand for corrosion-resistant coatings in extreme temperature cycling environments.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and isocyanate prices fluctuate with Alberta crude differentials, compressing margin predictability for Ontario-based formulators.
- Specialized applicator scarcity:NACE-certified coating inspectors and industrial painters are concentrated in Edmonton and Sarnia, creating bottlenecked project timelines.
- Powder coating capital barriers:Electrostatic spray line investments exceed CAD 2 million for mid-sized fabricators, limiting conversion from liquid systems.
Strategic Opportunities
- Quebec marine expansion:Davie Shipbuilding and Chantier Maritime de Matane are specifying ice-class coating systems for Arctic vessel construction.
- Federal green procurement:Environment and Climate Change Canada's sustainable products mandate is creating preferential purchasing channels for bio-based and low-carbon coating technologies.
- Digital coating monitoring:IoT-enabled corrosion sensors are converging with predictive maintenance platforms to create subscription-based asset protection services.
Industry Challenges
- CSA S16 certification timelines:Fire-resistant intumescent coating approvals require 18-24 month testing cycles, delaying commercialization of reformulated products.
- Cross-provincial regulatory misalignment:British Columbia's stricter VOC limits than federal schedules force dual inventory management for national distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Protective Coatings Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Vinyl Application: Aerospace, Marine, Industrial, Construction Technology: Water-Based, Solvent-Based, Powder Coating, UV-Cured End User: Manufacturing, Automotive, Oil & Gas, Utilities |
| Companies Covered | Axalta Coatings Systems, Jotun, The Sherwin-Williams Company, Nippon Paint Holdings Co., Ltd., Henkel AG & Co. KGaA, AkzoNobel NV, RPM International Inc., Kansai Paint Co., Ltd., PPG Industries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Protective Coatings Market Strategic Shifts
Water-borne technology platforms are collapsing the traditional solvent-borne dominance in Canadian industrial maintenance, while digital specification tools and green procurement mandates rewrite how buyers evaluate coating performance.
Water-borne epoxy and polyurethane systems are collapsing the installed base of solvent-borne coatings in Ontario manufacturing and Alberta oil sands maintenance. Facility managers at Imperial Oil and Syncrude are specifying these technologies for 60% of new maintenance contracts despite 15-20% upfront cost premiums. The shift is collapsing the addressable market for conventional alkyds and forcing distributors to liquidate legacy inventory.
Health Canada's PMRA is accelerating re-registration timelines for biocidal additives under the Pest Control Products Act, eliminating legacy chemistries from marine and industrial formulations. Coatings containing now-restricted isothiazolinones must reformulate or exit the market by scheduled compliance deadlines. Ontario-based marine applicators in Hamilton and Thunder Bay are switching to PMRA-registered alternatives ahead of enforcement phases.
Asset owners are unbundling coating specification from general contractor procurement, hiring independent corrosion engineers to write performance-based tenders. Suncor and TC Energy are leading this separation in Alberta, contracting directly with coating manufacturers for technical support while contractors bid labor-only. This pattern concentrates in oil sands and pipeline sectors where failure costs exceed coating material expenditures by orders of magnitude.
Canada Protective Coatings Market Segmentation
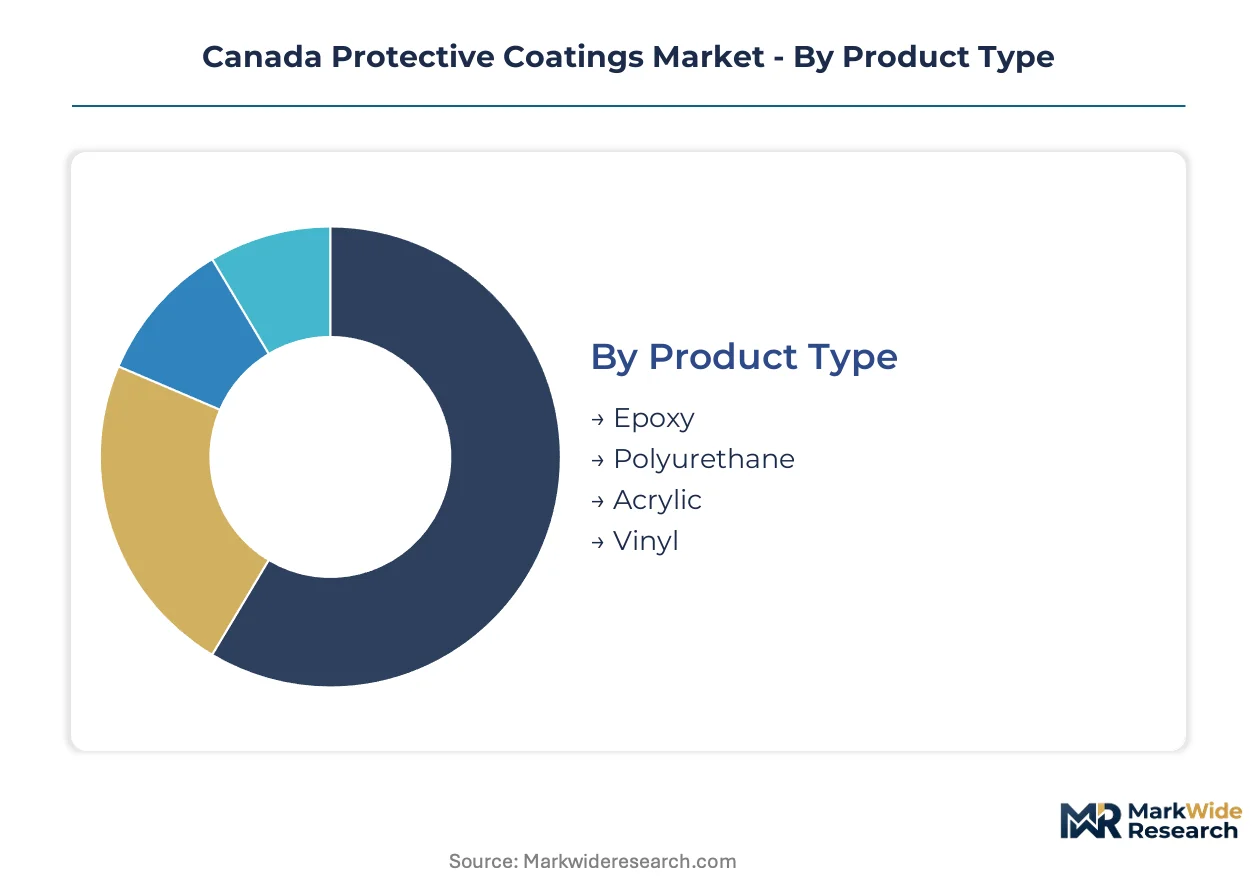
Canada's protective coatings market fragments across four critical dimensions that determine specification behavior and procurement cycles. Product chemistry governs performance in Alberta's freeze-thaw extremes and Ontario's humid industrial corridors. Application context, technology platform, and end-user industry each impose distinct compliance burdens and re-coating frequencies that reshape supplier economics.
Product Type:
Epoxy systems turn over slowest with 10-15 year lifecycles in buried pipeline service, while vinyl maintenance coatings refresh fastest at 3-5 year intervals on marine superstructures.
- Epoxy:Two-component thermoset formulations built from bisphenol-A or novolac resins deliver chemical resistance and substrate adhesion for steel protection. Demand concentrates in Alberta's oil sands infrastructure—Suncor's Fort McMurray facilities specify these for tank linings and structural steel—where PMRA-registered biocide additives now replace legacy isothiazolinones under tightened re-registration timelines.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems provide UV stability and abrasion resistance as topcoats over epoxy primers. Ontario's bridge rehabilitation program drives specification growth, with MTO contracts requiring these for steel girder protection where gloss retention and color stability matter across freeze-thaw cycling.
- Acrylic:Water-dispersed or solvent-borne thermoplastic resins offer breathable barriers for concrete and masonry substrates. Health Canada's VOC limits are pushing formulators toward high-solids acrylics in Ontario manufacturing facilities.
- Vinyl:Chlorinated polyvinyl chloride solutions deliver chemical resistance in immersion service. Marine applicators in Hamilton specify these for Great Lakes vessel hull protection where ice abrasion demands frequent re-coating.
Epoxy dominates installed base across heavy industrial assets. Polyurethane is where expansion concentrates as infrastructure maintenance contracts multiply.
Application:
Cost tier separation is pronounced—marine and aerospace command 3-4x material premiums over construction volume applications.
- Aerospace:Chromate-free epoxy primers and polyurethane topcoats meeting Transport Canada airworthiness standards. Demand clusters at Bombardier facilities in Montreal and Toronto where MRO cycles drive predictable re-coating schedules.
- Marine:Ice-class epoxy and silicone-alkyd systems for Arctic vessel construction. Davie Shipbuilding in Lévis and Chantier Maritime de Matane are specifying these for Coast Guard icebreaker fleet renewal, where CSA certification for fire-resistant deck coatings adds procurement complexity.
- Industrial:Chemical-resistant tank linings and floor coatings for Ontario's manufacturing corridor. Imperial Oil's Sarnia refinery and petrochemical clusters drive specification of novolac epoxies for sulfuric acid exposure.
- Construction:Intumescent fireproofing and architectural coatings for commercial steel framing. Toronto and Vancouver high-rise construction is accelerating uptake of water-borne acrylics as general contractors face green procurement mandates.
Industrial applications anchor volume throughput. Marine is climbing the fastest as federal shipbuilding strategy contracts ramp up.
Technology:
Volume concentration sits with solvent-borne legacy systems, though margin expansion favors powder and UV platforms in automated manufacturing.
- Water-Based:Acrylic and epoxy dispersions with sub-100 g/L VOC content meeting federal and British Columbia emission schedules. Syncrude and Canadian Natural Resources are converting maintenance contracts to these systems despite 15-20% upfront cost premiums.
- Solvent-Based:High-solids alkyds and epoxies retaining share in remote field application where water-borne cure fails in sub-zero conditions. Alberta pipeline maintenance contractors still specify these for winter construction windows.
- Powder Coating:Zero-VOC thermoset formulations applied via electrostatic spray lines. Automotive parts suppliers in Ontario's Windsor corridor and manufacturing fabricators justify CAD 2 million+ capital investments for factory-applied durable films.
- UV-Cured:Acrylate oligomer systems instant-cured via ultraviolet lamps. Narrow but high-margin niche in furniture and flooring manufacturing where line speed economics dominate.
Solvent-based technology retains largest installed base. Water-based platforms are gaining share fastest as provincial VOC limits tighten beyond federal minimums.
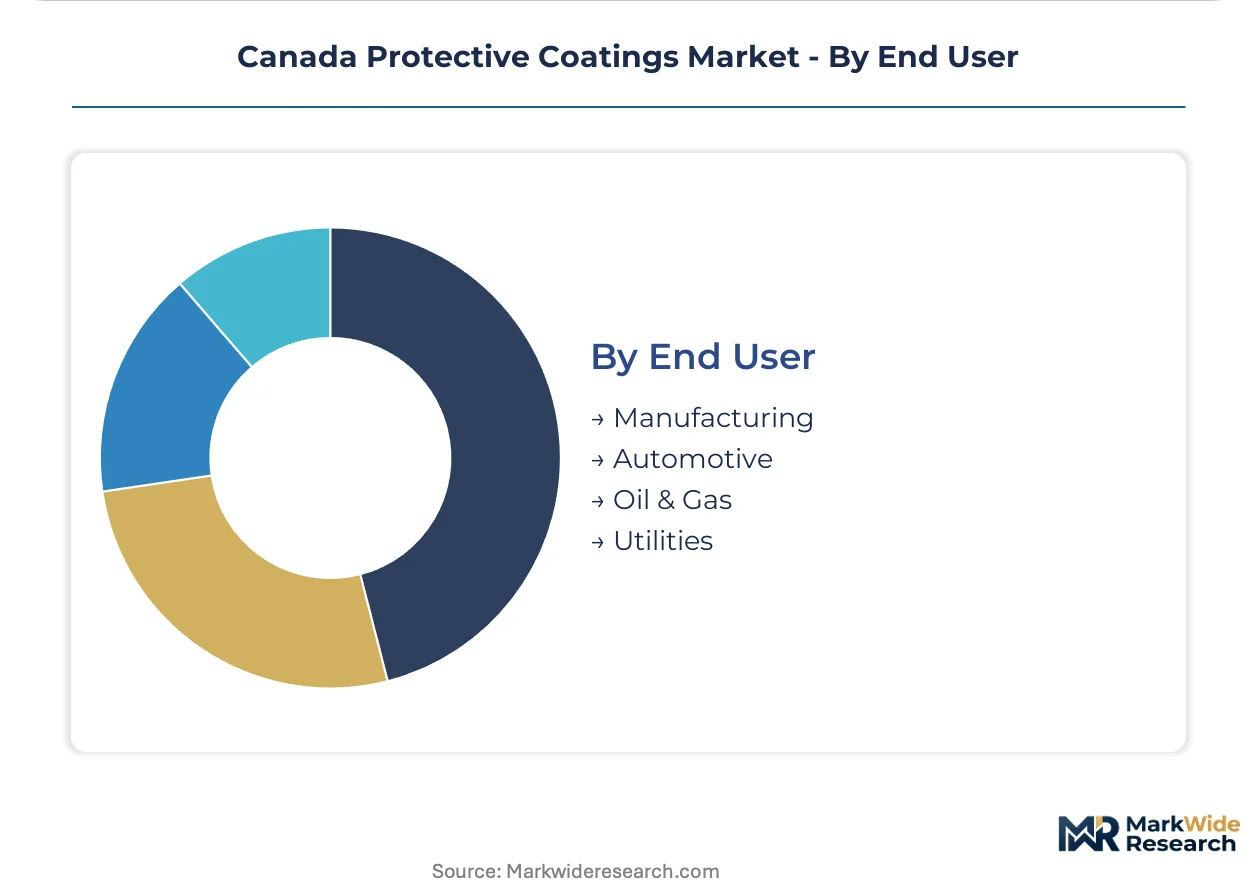
End User:
Customer procurement maturity varies—oil and gas operators unbundle coating specification from general contractors, while automotive buyers consolidate through OEM-approved supplier lists.
- Manufacturing:Food processing and general industrial facilities requiring USDA-accepted and chemical-resistant floor coatings. Quebec and Ontario plants are specifying antimicrobial epoxy systems as PMRA tightens biocide registration requirements.
- Automotive:OEM production lines and supplier tier paint operations. Stellantis Windsor Assembly and Toyota Cambridge drive powder coating specification for chassis and component protection.
- Oil & Gas:Upstream production, midstream pipelines, and downstream refining. TC Energy's pipeline integrity programs and oil sands operators in Fort McMurray demand NACE-certified inspection protocols and performance-based coating specifications.
- Utilities:Hydroelectric, nuclear, and transmission infrastructure. Ontario Power Generation and Hydro-Québec specify epoxy and polyurethane systems for dam structures and transmission towers exposed to ice loading and UV degradation.
Oil and gas commands highest performance specification intensity. Manufacturing offers steepest expansion trajectory as food safety and antimicrobial requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's protective coatings trade flows reflect regional specialization in resource extraction and manufacturing. Domestic production concentrates in Ontario and Alberta, while coastal provinces rely on imports for marine-grade formulations.
Ontario
Toronto's high-rise construction and Hamilton's steel manufacturing drive demand for intumescent fireproofing and industrial epoxy systems. The province's Ministry of Transportation mandates polyurethane topcoats for bridge rehabilitation contracts. Sarnia's petrochemical corridor specifies novolac epoxies for sulfuric acid exposure at Imperial Oil and downstream facilities.
Quebec
Davie Shipbuilding in Lévis and Chantier Maritime de Matane anchor demand for ice-class coating systems in Arctic vessel construction. Transport Canada airworthiness standards govern aerospace coatings at Bombardier's Montreal facilities. The province's stricter VOC schedules than federal minimums accelerate water-borne technology conversion in Quebec City manufacturing plants.
Alberta
Suncor and Canadian Natural Resources facilities in Fort McMurray generate recurring demand for corrosion-resistant coatings in extreme temperature cycling. The Alberta Energy Regulator's pipeline integrity mandates specify high-performance epoxies for TC Energy's midstream infrastructure. Edmonton concentrates NACE-certified coating inspectors and industrial painters, creating application bottlenecks during maintenance windows.
British Columbia
Vancouver's commercial construction sector faces green procurement mandates from Environment and Climate Change Canada. The province's VOC limits exceed federal schedules, forcing distributors to manage dual inventory for water-based systems. Coastal marine applicators specify vinyl solutions for Great Lakes vessel hull protection against ice abrasion.
Canada Protective Coatings Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin and additive supply. The Canada protective coatings market structures around three tiers: multinational formulators with PMRA-registered portfolios, regional distributors with application service capabilities, and specialty importers serving marine and aerospace niches. Consolidation pressures intensify as Health Canada's biocide re-registration timelines filter low-investment competitors. Dominant competitive moves include strategic partnerships with NACE-certified inspection firms and geographic expansion into Quebec's shipbuilding corridor.
Among North American formulators, PPG Industries Inc. and RPM International Inc. occupy positions serving Alberta's oil sands maintenance sector and Ontario's infrastructure rehabilitation programs. AkzoNobel NV exemplifies the European specialist archetype with formulations tailored to Canadian climatic extremes. These three anchors represent distinct strategic postures: continental scale with distribution density, targeted product lines for regional maintenance contractors, and climate-specialized formulation expertise.
| Leading Market Players |
|---|
| Axalta Coatings Systems |
| Jotun |
| The Sherwin-Williams Company |
| Nippon Paint Holdings Co., Ltd. |
| Henkel AG & Co. KGaA |
| AkzoNobel NV |
| RPM International Inc. |
| Kansai Paint Co., Ltd. |
| PPG Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility from Alberta crude differentials determines both margin compression patterns across epoxy resin tiers and the geographic clustering of formulator capacity around Edmonton and Sarnia. Buyers face widening price spreads between solvent-borne legacy systems and water-based alternatives as PMRA compliance costs layer onto raw material fluctuations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Canada Protective Coatings Market. Premium tiers command spreads based on NACE-certified inspection protocols and CSA S16 fire-resistant certification, while economy tiers compete on volume scale for construction maintenance contracts. Pricing pressure stems from isocyanate and bisphenol-A resin cost volatility tied to western Canadian crude benchmarks. Price-sensitive construction contractors dominate volume procurement, whereas oil sands operators exhibit lowest sensitivity due to failure-cost exposure exceeding material expenditures.
Supply Chain Analysis
Contract manufacturing concentration rests with PPG Industries, AkzoNobel, and RPM International facilities in Ontario and Alberta. Raw material sourcing draws from US Gulf Coast epoxy resin producers, Asian isocyanate suppliers, and domestic Alberta petrochemical feedstocks. Single-source vulnerability concentrates in specialty biocide additives facing PMRA re-registration timelines. Distribution runs through regional distributors with NACE-certified application service capabilities serving remote oil sands installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada Protective Coatings Market functions as a service-attach opportunity where predictive maintenance platforms and IoT-enabled corrosion monitoring expand faster than standalone coating sales. Asset owners increasingly unbundle technical specification from labor procurement, creating recurring revenue layers for suppliers with inspection and digital monitoring capabilities.
For Market Incumbents: Harden PMRA-registered biocide portfolios ahead of scheduled compliance deadlines to filter low-investment competitors. Deepen backward integration into water-based resin production in Ontario manufacturing corridors to capture margin from solvent-borne displacement. Channel control through NACE-certified inspection firm partnerships defends against emerging asset-light equipment leasing entrants. For New Entrants and Emerging Players: Build out Quebec marine coating capabilities targeting Davie Shipbuilding and Chantier Maritime de Matane ice-class specifications as the most penetrable segment. Digital coating monitoring platforms offer white-space entry through subscription-based asset protection services. Go-to-market positioning should emphasize Transport Canada and CSA certification support bundled with predictive analytics. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors vertically integrated formulators with PMRA-registered additive portfolios. Long-term viability across the projection horizon hinges on water-based technology conversion capabilities and marine sector exposure. Watch for inflection through quarterly tracking of provincial VOC limit adoption beyond federal schedules and federal green procurement mandate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Water-Based Resin Production | Ontario formulators capture margin compression from PMRA-driven solvent-borne displacement. |
| NACE-Certified Inspection Firm Partnership | Suppliers anchor channel control through bundled technical specification services for oil sands operators. |
| Quebec Marine Coating Capacity Expansion | Ice-class formulation capabilities access federal shipbuilding strategy contracts at Davie Shipbuilding. |
| Predictive Maintenance Platform Development | IoT-enabled corrosion sensors create subscription revenue layers beyond commodity coating sales. |
| PMRA Biocide Registration Investment | Compliant antimicrobial portfolios filter competitors ahead of scheduled re-registration deadlines. |
Study Parameters
A standing panel of plant engineers at Suncor and Canadian Natural Resources, NACE-certified coating inspectors in Edmonton, procurement leads at Ontario Ministry of Transportation, and technical R&D directors at multinational formulators provided ongoing calibration. Primary interview findings triangulated against Health Canada PMRA registration databases, Canadian Standards Association certification records, provincial environmental ministry VOC schedules, and customs trade data for resin and solvent imports. Bottom-up project pipeline analysis and top-down sectoral expenditure models converged on volume estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon using differential assumptions for provincial regulatory adoption timing and oil sands maintenance cycle intensity. Segmentation dimensions modeled include product chemistry tier, application context, technology platform, and end-user industry procurement maturity. CAGRs derived from fitted growth curves applied to disclosed maintenance expenditure patterns and infrastructure renewal program allocations. Forecast inputs incorporated Alberta crude differential volatility assumptions and PMRA compliance timeline scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian specialty chemical producers or accelerated federal carbon pricing implementation would shift outcomes. Quarterly review of provincial VOC limit adoption rates, oil sands operator maintenance budget disclosures, and PMRA biocide registration approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Electrocoat Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Global Sputter Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Global Nanocoatings Market
Coatings
FBE Coatings Market
Coatings
Rail Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
Carbon Fiber Coatings Market
Coatings
Russia Protective Coatings Market
Coatings
Morocco Automotive OEM Coatings Market
Coatings
US Antifouling Yacht Coatings Market