
 Single-Ply Membranes Market | 2026-2036
Single-Ply Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Ply Membranes Market Outlook
Preventive maintenance contracts and membrane lifecycle service agreements are repositioning how single-ply systems get specified and sold. Carlisle Companies leverages its installed base to sustain recurring revenue through inspection and repair programs. GAF anchors its competitive stance with contractor certification networks that control specification channels. Firestone Building Products differentiates through extended warranty structures tied to approved installer performance.
Single-ply membranes are synthetic polymer sheets, typically 0.030 to 0.060 inches thick, manufactured through calendering or extrusion processes and designed to provide weatherproof barriers for low-slope roofing and building envelope applications. TPO formulations lead specification volumes in North American commercial construction due to heat-weldable seams and reflective surface properties, while EPDM retains dominance in ballasted systems where puncture resistance and long-term UV stability command premium positioning. Installation method selection increasingly tracks labor availability and wind uplift requirements, with mechanically attached systems occupying the fastest-growing share in hurricane-prone zones.
FM Global wind uplift standards and ASTM D6878 specifications govern product qualification in the United States, while REACH compliance and CE marking under the Construction Products Regulation shape market access across European Union member states. The EU Green Deal's building performance standards are forcing reformulation timelines for PVC alternatives with lower embodied carbon profiles. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer recycling infrastructure buildouts to anticipate raw material cost trajectories and specification eligibility shifts.
Market Dynamics
The Single-Ply Membranes Market is experiencing structural pressure from EU Green Deal building renovation mandates, which are compressing specification timelines for lower-carbon formulations and forcing reformulation investments ahead of recyclability requirements.
Growth Catalysts
- Deep retrofit mandates:Germany's building energy efficiency regulations are accelerating membrane replacement cycles in commercial warehouse stock. Contractors face binding performance targets that favor complete system overhauls.
- TPO heat-weldable seam technology:Thermoplastic polyolefin formulations enable faster installation with fewer skilled labor hours, expanding contractor capacity in tight labor markets. Reflective surface properties align with cooling energy codes.
- FM Global wind uplift standards:Stricter hurricane-zone certification requirements in the United States are driving specification of mechanically attached systems with higher fastener density and membrane tensile grades.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene monomer prices fluctuate with crude oil and natural gas liquid markets, compressing margin predictability for membrane producers without captive polymer supply.
- EPDM supply concentration:Carbon black-reinforced sheet production clusters in specific manufacturing corridors, creating geographic vulnerability to logistics disruptions and regional environmental enforcement actions.
- PVC substitution pressure:REACH restrictions on plasticizer chemistries and embodied carbon scoring are displacing traditional polyvinyl chloride membranes in public procurement frameworks across EU member states.
Strategic Opportunities
- Extended producer responsibility buildout:EU member states are piloting membrane take-back programs that reward producers with established recycling infrastructure. Early movers capture specification preference in public tenders.
- Building-integrated photovoltaics convergence:TPO and EPDM substrates serve as mounting platforms for solar membrane systems, opening rooftop energy generation contracts to roofing contractors.
- Preventive maintenance service contracts:Lifecycle agreements reposition membrane vendors as facility managers, locking out competitors through inspection protocols and repair authorization networks.
Industry Challenges
- Heat-welding technician certification gaps:Automated welding equipment requires specialized training that outpaces vocational program output, constraining installation quality and warranty eligibility in high-growth regions.
- ASTM D6878 compliance timeline compression:Accelerated aging test protocols and revised seam strength thresholds demand reformulation cycles that conflict with just-in-time manufacturing schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Ply Membranes Market |
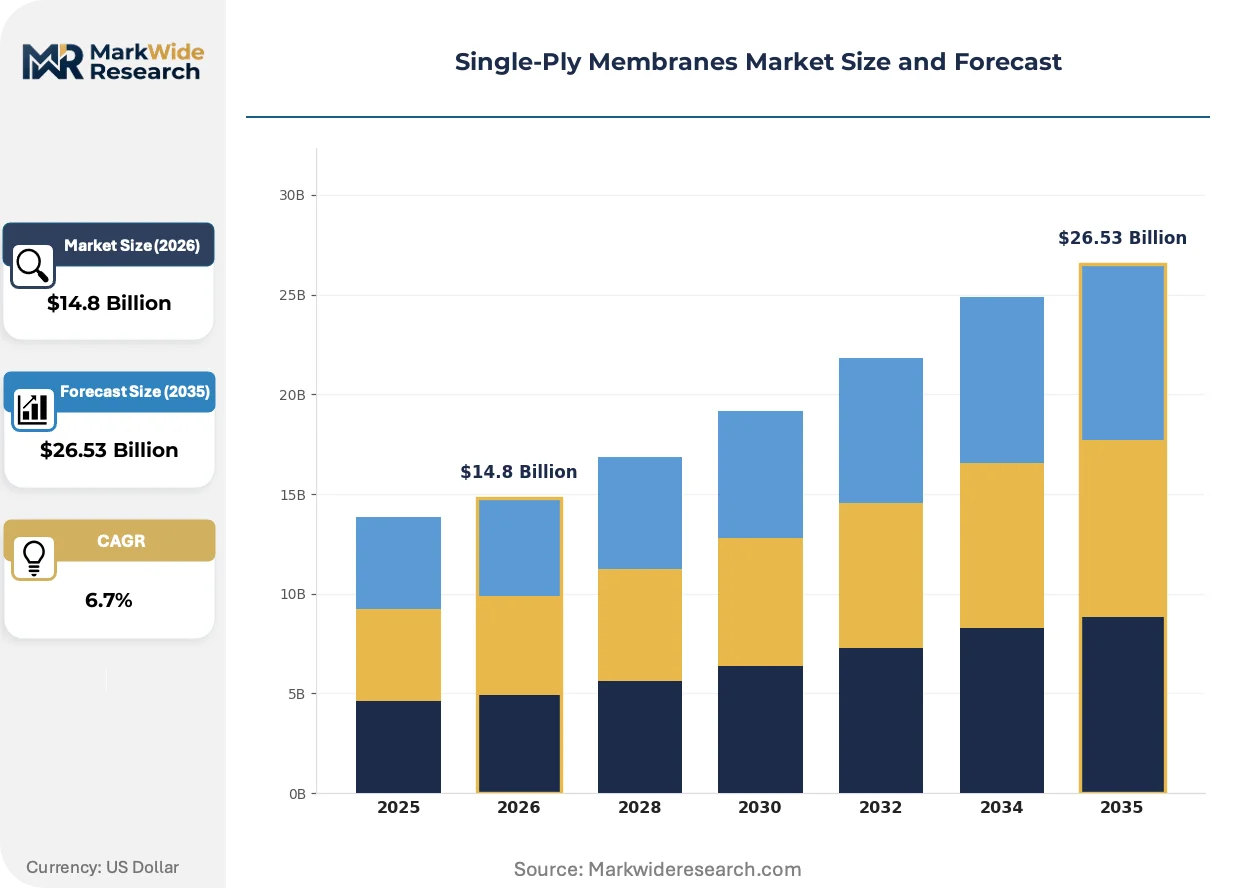
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TPO, PVC, EPDM, Bitumen Installation Method: Fully Adhered, Mechanically Attached, Ballasted, Self-Adhered End User: Commercial, Industrial, Residential, Institutional System Type: Roofing, Waterproofing, Building Envelope, Others |
| Companies Covered | GAF, Carlisle Companies, Sika AG, Firestone Building Products, Johns Manville, Duro-Last, Dow, Owens Corning, Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Ply Membranes Market Strategic Shifts
Material science advances and procurement model evolution are compressing product lifecycles while extending vendor-customer relationships through service-layer monetization. Specification authority is migrating from architects to certified contractor networks.
Self-adhering membrane technology is consolidating installation workflows by eliminating mechanical fasteners and heat-welding equipment from low-slope commercial applications. Facility managers in retail and logistics verticals specify these systems to minimize business disruption during roof replacement. The technology is consolidating market share among contractors facing skilled labor shortages and insurance-driven safety protocols.
REACH compliance deadlines for phthalate-free plasticizers are forcing PVC membrane producers to validate alternative chemistries ahead of 2025 restriction phases. ECHA substance evaluation timelines compress reformulation windows, favoring producers with in-house polymer compounding capabilities. German and French specification bodies are embedding these restrictions into public procurement technical clauses ahead of full regulatory enforcement.
Building owners now unbundle membrane procurement from installation and maintenance, creating three distinct contract vehicles that specialist contractors aggregate into single-source accountability. General contractors and facility management firms in the United States are consolidating vendor relationships to reduce qualification overhead. This pattern concentrates specification influence with national contractor certification networks that control project pipeline visibility.
Single-Ply Membranes Market Segmentation
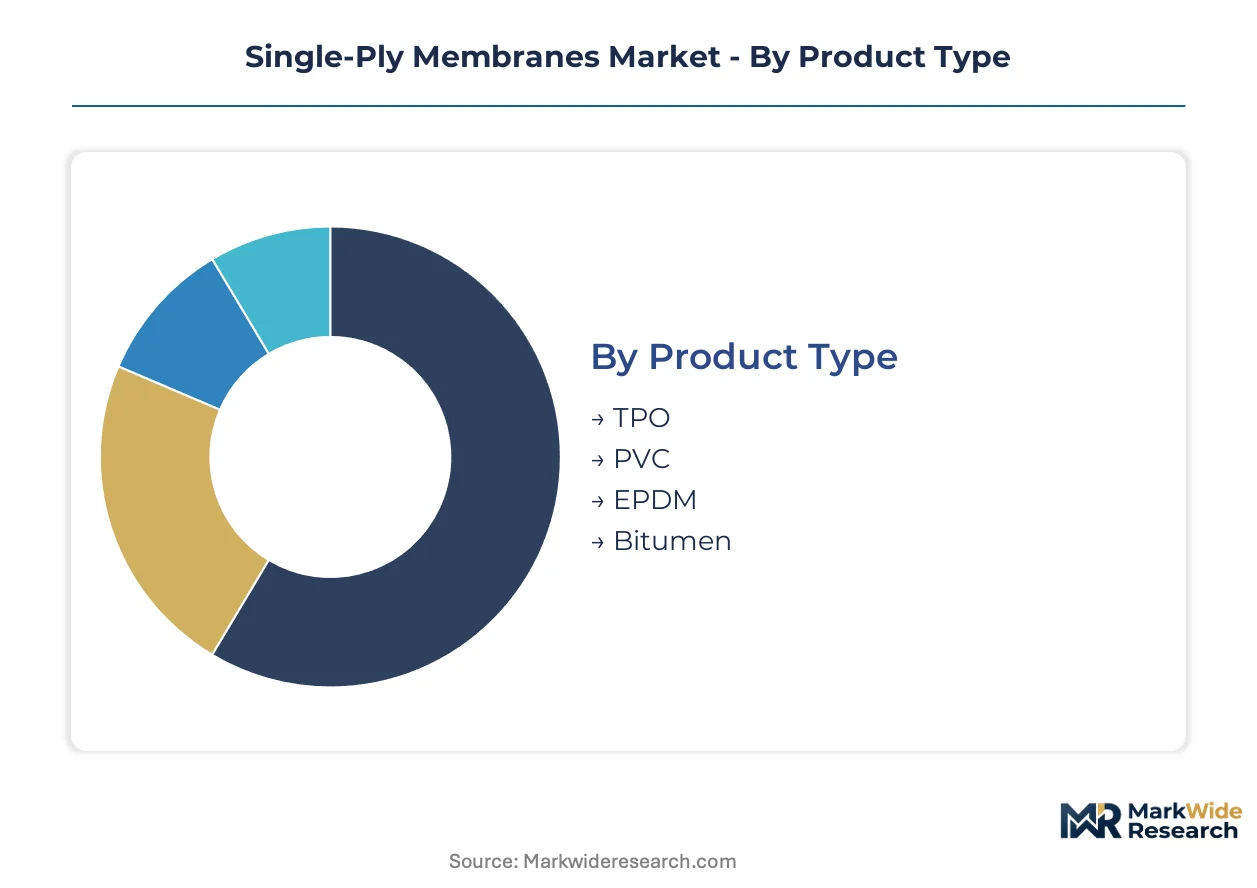
Membrane specification authority fragments across product chemistry, attachment physics, and building typology. Contractors and facility managers weight segments differently based on labor availability, code jurisdiction, and warranty eligibility requirements.
Product Type:
TPO and EPDM dominate as standalone membrane systems specified directly by roofing contractors, while PVC and bitumen increasingly embed into multi-layer assemblies controlled by general contractors.
- TPO:Thermoplastic polyolefin sheets formulated with polypropylene and ethylene-propylene rubber deliver heat-weldable seams and solar reflectance above 0.70. Demand concentrates in Texas and Florida warehouse construction where cooling load reduction drives specification. FM Global wind uplift certification for mechanically attached TPO systems accelerates adoption in hurricane corridors.
- EPDM:Ethylene-propylene-diene terpolymer membranes provide exceptional UV stability and puncture resistance through carbon black reinforcement. Ballasted EPDM systems retain dominance in Minnesota and Michigan commercial retrofits where stone ballast offers hail protection and installation speed. Labor shortages favor crews familiar with loose-laid rather than welded systems.
- PVC:Polyvinyl chloride membranes with polyester or fiberglass reinforcement achieve chemical resistance and dimensional stability through plasticizer loading. REACH phthalate restrictions compress formulation timelines for EU-bound production.
- Bitumen:Modified bitumen sheets combine SBS or APP polymers with asphalt binders for multi-ply system compatibility. Self-adhered bitumen variants serve as base layers in hybrid specifications.
TPO leads volumes today; PVC is losing share fastest to thermoplastic alternatives.
Installation Method:
Attachment physics segment the market by labor skill requirements, equipment capital intensity, and wind uplift performance tiers.
- Mechanically Attached:Fastener plates and bar systems secure membrane to structural decks at calculated densities. Hurricane-zone building codes in Miami-Dade County and Broward County mandate this method for projects above 60-foot mean roof height. Fastener manufacturers sponsor contractor certification programs that control specification pipelines.
- Fully Adhered:Water-based or solvent-based adhesives bond membrane to substrate without penetration. Urban infill projects in Chicago and Boston specify adhered systems to eliminate interior noise from foot traffic on fastener plates. Adhesive VOC regulations in California and New York constrain product availability.
- Ballasted:Loose-laid membrane covered with stone or concrete pavers provides installation speed without specialized welding equipment. Distribution centers in Ohio and Pennsylvania favor ballasted EPDM for 24-hour installation windows.
- Self-Adhered:Factory-applied adhesive backing eliminates field mixing and curing time. Retail chain rollouts in suburban Atlanta and Dallas specify self-adhered TPO to minimize business disruption.
Mechanically attached systems dominate new construction; self-adhered methods are expanding most quickly in reroofing.
End User:
Building typology determines performance specification, maintenance contract structures, and procurement centralization.
- Commercial:Office buildings, retail centers, and hospitality properties specify reflective membranes for energy code compliance. National retail chains centralize procurement through approved contractor networks.
- Industrial:Manufacturing facilities and warehouses prioritize puncture resistance and chemical compatibility over reflectance. Food processing plants in Wisconsin and California specify heat-weldable seams for washdown durability.
- Residential:Multi-family housing and estate properties represent a niche segment with shorter warranty expectations and price-sensitive procurement.
- Institutional:Schools, hospitals, and government buildings embed membrane selection into multi-year capital planning cycles. Public procurement frameworks in Germany and France privilege recyclability scoring.
Commercial applications anchor volume; industrial verticals show the steepest expansion trajectory.
System Type:
Functional scope segments the market between weatherproofing specialization and building envelope integration.
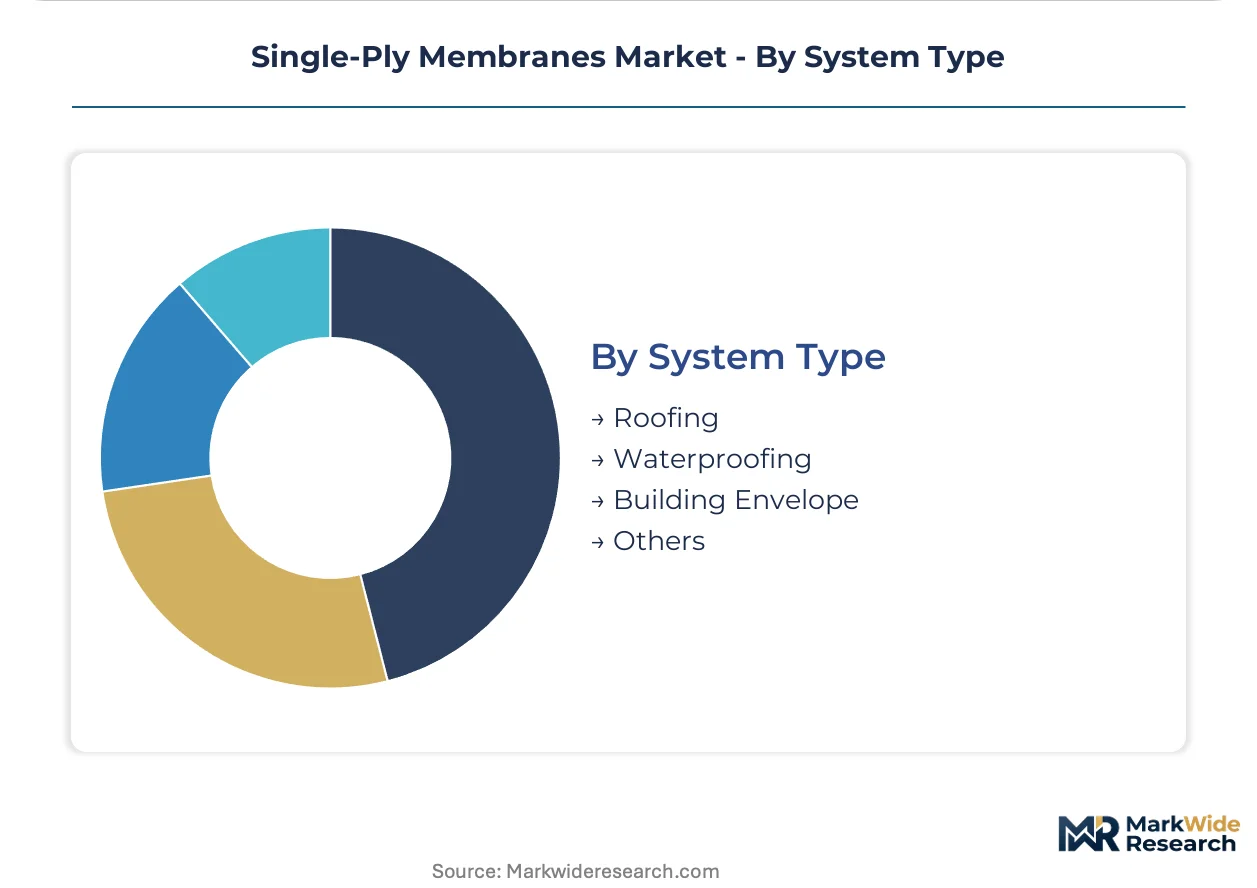
- Roofing:Low-slope weatherproofing represents the core application with established ASTM and FM Global qualification protocols. Single-ply roofing systems specified for slopes below 2:12 dominate contractor training and distribution inventory.
- Waterproofing:Below-grade and plaza deck applications demand puncture resistance and hydrostatic pressure performance. Green roof assemblies in Seattle and Portland integrate waterproofing membranes with drainage composites.
- Building Envelope:Wall and soffit applications extend membrane specification beyond traditional roofing boundaries. Air barrier integration with TPO wall systems gains traction in Passive House construction.
- Others:Tunnel lining and containment applications represent specialized industrial demand with custom fabrication requirements.
Roofing systems command the revenue base; building envelope applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's deep retrofit mandates accelerate replacement cycles faster than US hurricane-zone construction drives mechanically attached system specification, creating divergent demand profiles across the two largest national markets.
United States
Texas and Florida warehouse construction concentrates TPO specification volumes where cooling load reduction meets FM Global wind uplift certification for mechanically attached systems. The EPA's energy efficiency standards for commercial buildings tighten membrane reflectance requirements. Miami-Dade County building codes mandate enhanced fastening densities for projects above 60-foot mean roof height.
Germany
Commercial warehouse stock in North Rhine-Westphalia and Bavaria faces binding building energy efficiency regulations that favor complete roofing system overhauls. The EU Green Deal's building performance standards compress timelines for lower-carbon membrane formulations. Frankfurt and Stuttgart industrial zones drive specification volumes for recyclable thermoplastic alternatives.
France
Public procurement frameworks in Île-de-France embed REACH phthalate restrictions into technical clauses ahead of full 2025 enforcement. The country's national building regulator accelerates embodied carbon scoring for roofing materials in institutional projects. Lyon and Marseille logistics hubs specify heat-weldable membranes for food processing facility durability.
China
Yangtze River Delta manufacturing facilities prioritize puncture-resistant EPDM for chemical compatibility in industrial roofing applications. The Ministry of Ecology and Environment's dual carbon goals pressure reformulation toward lower-emission polymer production. Shanghai and Suzhou construction clusters integrate single-ply substrates with building-integrated photovoltaic mounting platforms.
Canada
Ontario and Quebec commercial retrofits specify ballasted EPDM systems where stone ballast delivers hail protection and installation speed advantages. Health Canada's environmental assessment protocols review plasticizer chemistries for below-grade waterproofing applications. Toronto and Montreal facility managers unbundle membrane procurement from maintenance contracts to reduce vendor qualification overhead.
Single-Ply Membranes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with membrane producers controlling specification through certified installer networks while regional fabricators compete on price for undifferentiated volumes. The vendor base concentrates around three strategic archetypes: integrated polymer producers with captive raw material supply, roofing system specialists leveraging inspection and repair programs for recurring revenue, and building materials conglomerates cross-selling membrane into envelope portfolios. Consolidation pressures favor acquisition of regional installers over manufacturing capacity expansion, while technology licensing agreements accelerate heat-welding equipment standardization.
Among North American building materials specialists, GAF and Carlisle Companies exemplify the certified-network archetype, each anchoring competitive positioning through contractor qualification programs that filter project pipeline visibility. Sika AG represents the European integrated chemicals model, with Swiss-based polymer compounding capabilities supporting REACH-compliant formulation timelines. Firestone Building Products occupies a position within the extended-warranty tier, where installer performance metrics determine coverage eligibility and lock out non-approved competitors.
| Leading Market Players |
|---|
| GAF |
| Carlisle Companies |
| Sika AG |
| Firestone Building Products |
| Johns Manville |
| Duro-Last |
| Dow |
| Owens Corning |
| Kingspan Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FM Global-approved mechanically attached systems and commodity-grade ballasted membranes manifests in pricing premiums of 15-25% for hurricane-zone qualified products, while supply chain configurations split between captive polymer compounding operations serving premium tiers and toll-manufacturing arrangements feeding price-sensitive specifications. This divergence concentrates margin capture with integrated producers possessing in-house formulation capabilities, while contract manufacturers compete on ethylene-propylene feedstock arbitrage across regional petrochemical corridors.
Pricing Analysis
Capacity additions in the US Gulf Coast are reshaping price floors for TPO resin, compressing margins for non-integrated membrane producers dependent on spot polymer markets. Three-tier pricing structure across premium, standard, and economy levels tracks FM Global certification status, installer network exclusivity, and warranty term length. Pricing pressure stems from ethylene monomer volatility linked to natural gas liquid pricing. Institutional buyers in German public procurement frameworks exhibit lowest price sensitivity due to lifecycle cost scoring mandates, while US retail chain facility managers drive hardest bargain on per-square-foot installed cost.
Supply Chain Analysis
Single-source vulnerability sits with carbon black-reinforced EPDM sheet production concentrated in Ohio, Kentucky, and southeastern US manufacturing corridors. Geographic supply concentration centers on the United States, Germany, and China for membrane fabrication, with South Korea and Japan anchoring specialty polymer additive production. Raw material dependencies rest on ethylene and propylene monomers, carbon black reinforcement grades, and heat-stabilizer chemistries. Tariff exposure on Chinese-manufactured roofing accessories creates inventory positioning risk. Distribution runs through national contractor certification networks that control specification pipeline visibility and project bidding access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Specification authority migration toward certified installer networks and EU Green Deal durability mandates favor membrane producers with established inspection and repair service infrastructure over commodity suppliers.
For Market Incumbents: Lock in specification channel control through accelerated contractor certification program expansion, particularly in Florida and Texas hurricane corridors where FM Global wind uplift requirements tighten eligibility. Deepen backward integration into polymer compounding to defend margin position against ethylene feedstock volatility. Prioritize recyclability infrastructure investment ahead of EU extended producer responsibility framework rollout. For New Entrants and Emerging Players: Regional roofing contractors underserved by national certification networks represent the most penetrable entry point. White-space targets include self-adhered membrane segments in retail chain reroofing programs and building-integrated photovoltaic substrate applications in Yangtze River Delta manufacturing zones. Go-to-market angle should emphasize 24-hour installation capability and minimal business disruption protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where regional installers possess certified technician pools but lack membrane manufacturing scale. Long-term viability favors integrated producers with captive polymer supply and established take-back recycling programs. Acquisition target archetype: mid-scale membrane fabricators with FM Global approvals and underutilized calendering capacity. Signal to watch: EU member state pilot program announcements for membrane take-back infrastructure subsidies.| Strategic Initiative | Industry Significance |
|---|---|
| Recyclability Infrastructure Buildout | Early movers capture specification preference in EU public tenders ahead of extended producer responsibility mandates. |
| Contractor Certification Network Expansion | GAF and Carlisle Companies demonstrate how installer qualification programs filter project pipeline visibility and lock out competitors. |
| Backward Integration into Polymer Compounding | Sika AG's Swiss-based compounding capabilities compress REACH-compliant formulation timelines versus toll-manufacturing dependent rivals. |
| Preventive Maintenance Service Contract Launch | Lifecycle agreements reposition membrane vendors as facility managers, creating recurring revenue streams and repair authorization lock-in. |
| Building-Integrated Photovoltaic Substrate Development | TPO and EPDM mounting platforms open rooftop energy generation contracts to roofing contractors in Shanghai and Suzhou industrial zones. |
Study Parameters
Bottom-up commercial roofing contractor modeling reconciled against top-down polymer feedstock tracking forms the analytical core of this study. Primary interviews with roofing contractors, facility managers at national retail chains, membrane product managers, and EPC contractors specializing in warehouse construction were validated against secondary sources including FM Global loss prevention data, ASTM D6878 certification records, EU Construction Products Regulation filings, and customs trade statistics for ethylene-propylene rubber imports. Triangulation across these data streams isolates specification volume trends from inventory cycle noise.
Input-output matrices map membrane demand across installation method, building typology, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from weighted average of contractor capacity expansion plans, building permit flow analysis, and energy code adoption timelines. Industry-specific forecast inputs include FM Global wind uplift certification velocity and EU Green Deal building renovation mandate implementation schedules across member states.
Underlying measurement precision varies by segment; mechanically attached TPO systems in US hurricane corridors carry tighter precision than ballasted EPDM retrofits in Midwest distribution centers due to certification documentation requirements. Forecasts reflect assumptions on labor availability, polymer feedstock cost trajectories, and regulatory enforcement intensity that could shift with macroeconomic or policy developments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Asia-Pacific, Middle East and Africa Macrofiltration Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market