
 Telemetric Devices Market | 2026-2036
Telemetric Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Telemetric Devices Market Outlook
Medical-grade telemetry specification is collapsing the gap between hospital and home monitoring environments. Siemens AG leverages its diagnostic imaging heritage to anchor cardiac telemetry platforms across European clinical networks. Medtronic Plc competes through implantable device leadership, while Philips Healthcare sustains bedside-to-cloud integration for remote patient surveillance.
Telemetric devices encompass sensor-integrated hardware that captures physiological, geospatial, or mechanical parameters and transmits data via radio frequency protocols to centralized analysis platforms. These systems typically operate on sub-gigahertz or licensed cellular bands with power budgets under 500 milliwatts for wearable form factors, serving industrial automation and connected health applications. Cellular-enabled remote monitors command premium positioning due to real-time alerting capabilities in critical care workflows. Bluetooth-based wearable devices occupy high-volume consumer health segments where battery life and cost sensitivity dominate procurement criteria. GPS trackers within fleet management applications concentrate margin pools through subscription-based software layering.
The FDA governs patient-facing telemetry through Class II medical device pathways, while the FCC manages spectrum allocation for unlicensed and licensed transmission bands. EMA harmonization under the EU Medical Device Regulation is forcing cross-border compliance investments for wearable cardiac monitors. Stakeholders must monitor spectrum reallocation proceedings and cybersecurity framework updates as telemetry networks expand beyond controlled clinical settings into unregulated consumer environments.
Market Dynamics
FCC spectrum reallocation mandates are compressing device certification timelines while cellular module suppliers consolidate manufacturing footprints across East Asian foundries. Fleet operators now demand real-time geospatial telemetry as a baseline procurement specification rather than a premium upgrade.
Growth Catalysts
- Cellular Module Cost Compression:5G RedCap chipsets from Qualcomm and MediaTek are reducing bill-of-materials overhead for mid-tier remote monitors. Transportation fleets in Germany and Japan are absorbing these modules at volume scale.
- FDA Class II Pathway Streamlining:The FDA's Digital Health Center of Excellence is accelerating pre-submission reviews for wearable cardiac telemetry. Home health agencies are expanding remote patient monitoring contracts accordingly.
- Fleet Telematics Mandates:Japan's METI has enacted compulsory electronic logging device installation for commercial vehicles exceeding 3.5 tonnes. Logistics providers are retrofitting existing fleets with cellular-enabled GPS trackers.
Market Restraints
- Lithium-Polymer Supply Concentration:Battery cell production for wearable form factors concentrates in Chinese and South Korean manufacturing corridors. Geopolitical friction is injecting procurement uncertainty for European device assemblers.
- Sub-Gigahertz Spectrum Fragmentation:Regional allocation inconsistencies for 868 MHz and 915 MHz bands force hardware variants that inflate inventory carrying costs.
- Silicon Shortage in RF Front-Ends:Gallium arsenide and silicon germanium wafer supply for radio frequency components remains constrained. Lead times for power amplifier modules now extend 26-32 weeks.
Strategic Opportunities
- India Connected Health Infrastructure:The Ayushman Bharat Digital Mission is subsidizing remote diagnostic device deployment across rural primary health centers. Cellular telemetry vendors can anchor public procurement frameworks.
- EMA MDR Harmonization:The EU Medical Device Regulation's unified conformity assessment is reducing cross-border certification redundancy for wearable monitors. Manufacturers can consolidate European distribution nodes.
- Bluetooth-Cellular Convergence:Hybrid protocol stacks are enabling seamless handoff between short-range bedside monitoring and wide-area cellular alerting. Hospital-at-home programs in the United States are piloting these architectures.
Industry Challenges
- Embedded Firmware Security Certification:IEC 62304 medical software lifecycle compliance demands specialized engineering talent that remains scarce in Eastern European and Latin American development centers.
- Legacy Fleet Management Integration:Transportation operators maintain heterogeneous telematics installations spanning three cellular generations. API standardization gaps complicate unified data lake construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telemetric Devices Market |
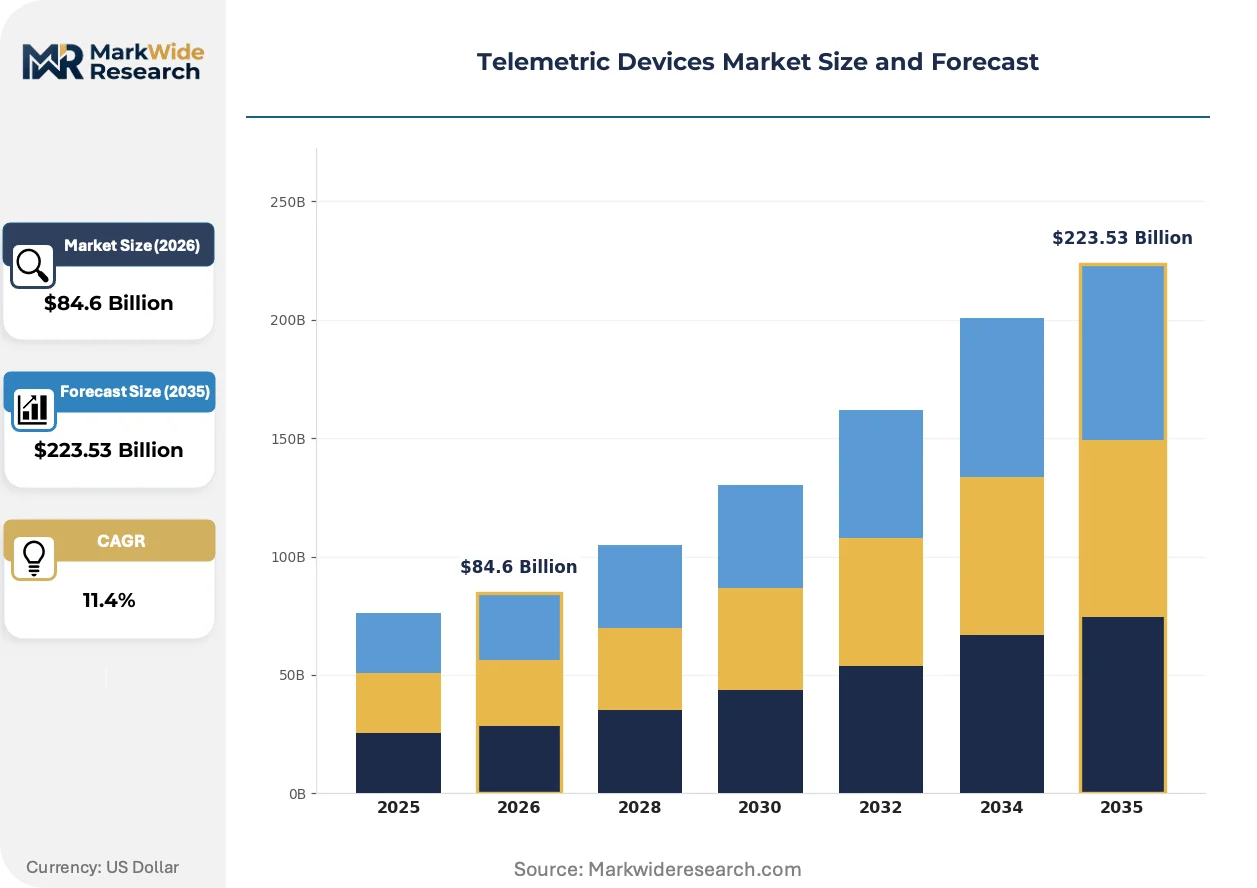
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $223.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitors, GPS Trackers, Data Loggers Technology: Bluetooth, Wi-Fi, Cellular, RFID End User: Healthcare Providers, Sports Organizations, Transportation Companies, Industrial Manufacturers Application: Patient Monitoring, Asset Tracking, Fleet Management, Environmental Monitoring |
| Companies Covered | Siemens AG, GE Healthcare, Philips Healthcare, Schlumberger Limited, Schneider Electric, Honeywell International Inc., Cobham Plc, Sierra Wireless, Inc., Medtronic Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telemetric Devices Market Strategic Shifts
Multi-protocol sensor fusion is collapsing the boundary between clinical-grade precision and consumer-scale deployment. Device architectures now prioritize software-defined radio flexibility over fixed-function hardware.
Ultra-wideband positioning chips from Apple and Samsung semiconductor divisions are miniaturizing into sub-100-milliwatt form factors for asset tracking applications. Third-party logistics providers in Germany are embedding these modules into refrigerated container seals. The technology is miniaturizing geofencing accuracy from meter-scale to decimeter-scale, compressing insurance premium differentials for high-value cargo shipments.
The EU AI Act's risk classification framework is mandating algorithmic transparency for diagnostic inference engines embedded in remote patient monitors. Manufacturers must document training data provenance and model drift detection protocols. Cardiac telemetry platforms with embedded arrhythmia detection are most affected, with Siemens AG and Philips Healthcare restructuring quality management systems to satisfy conformity assessment body requirements.
Hospital procurement committees are unbundling hardware acquisition from recurring software subscription commitments. Health systems in the United States now negotiate telemetry device purchases through group purchasing organizations while selecting analytics platforms through separate RFP processes. This bifurcation is compressing vendor lock-in duration and accelerating switching cycles for cloud-based surveillance dashboards.
Telemetric Devices Market Segmentation
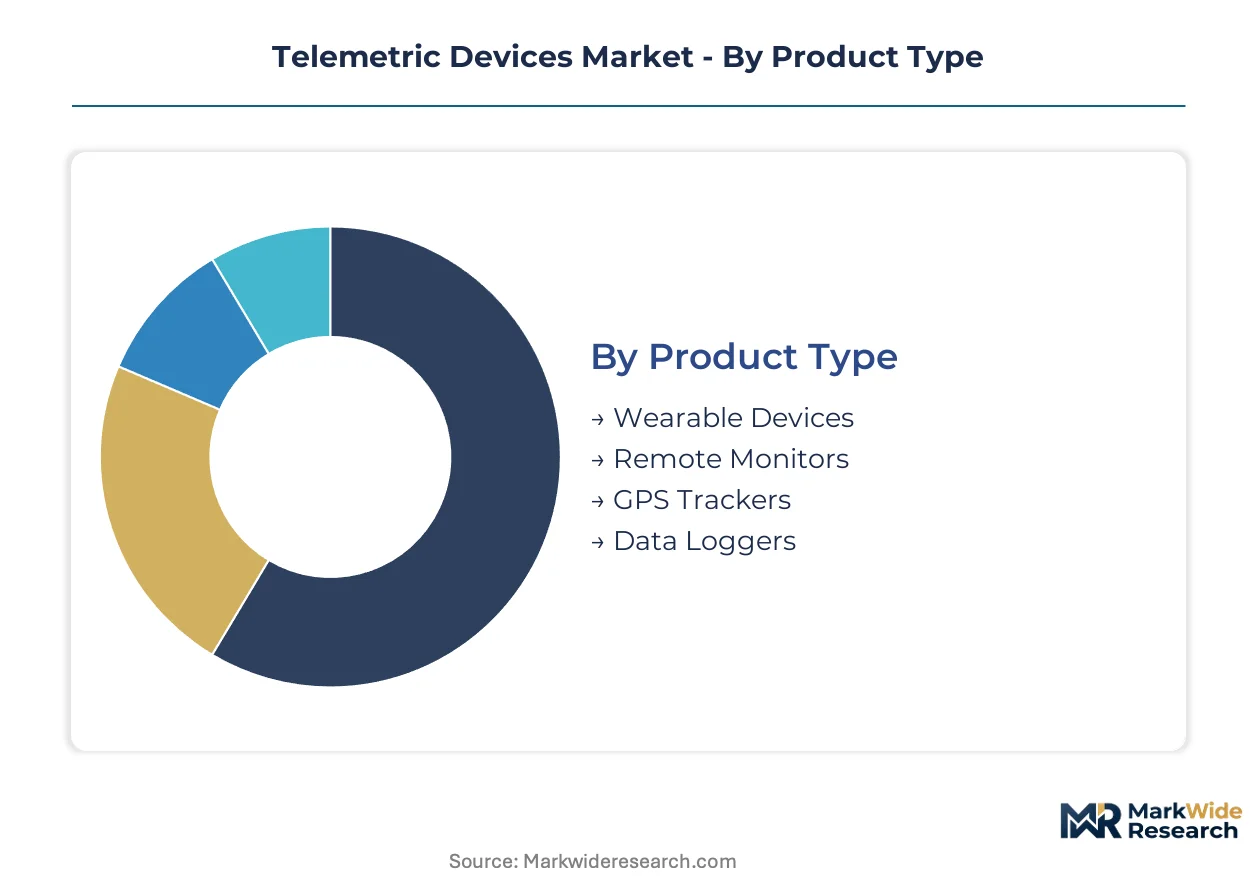
Telemetric devices fragment across four intersecting dimensions that determine procurement channels and margin architecture. Product type dictates power budgets and form factor constraints. Technology selection governs certification pathways and recurring revenue potential through connectivity subscriptions.
Product Type:
Wearable devices and remote monitors flow through clinical procurement committees and direct-to-consumer channels, while GPS trackers and data loggers concentrate in fleet operator and industrial distributor networks.
- Wearable Devices:Sensor-integrated wristbands and patches operating under 500 milliwatts capture continuous physiological streams for cardiac and metabolic surveillance. Demand concentrates in United States hospital-at-home programs where Philips Healthcare and Medtronic Plc anchor procurement frameworks through FDA Class II certifications.
- Remote Monitors:Bedside-to-cloud telemetry platforms with embedded cellular modules enable real-time alerting across European clinical networks. Siemens AG leverages diagnostic imaging heritage to secure multi-year service contracts with German hospital systems prioritizing EMA MDR harmonization.
- GPS Trackers:Fleet telematics hardware with subscription-based software layering commands premium positioning in Japanese logistics corridors under METI electronic logging mandates.
- Data Loggers:Environmental and mechanical parameter recorders serve industrial automation applications with extended battery life requirements.
Wearable devices dominate installed base through consumer health volume. Remote monitors are where expansion concentrates as clinical networks extend surveillance beyond facility walls.
Technology:
Cost tier stratification separates premium cellular modules from economy Bluetooth implementations, with Wi-Fi and RFID occupying mid-tier positioning for specific application constraints.
- Cellular:Licensed-band modules with real-time alerting capabilities command highest bill-of-materials overhead. 5G RedCap chipsets from Qualcomm and MediaTek are compressing costs for mid-tier remote monitors in German and Japanese transportation fleets.
- Bluetooth:Short-range protocols dominate high-volume consumer health segments where battery life and unit economics override connectivity range requirements. Philips Healthcare sustains bedside-to-cloud integration through hybrid Bluetooth-cellular architectures.
- Wi-Fi:Hospital and industrial campus deployments leverage existing infrastructure for localized telemetry aggregation without recurring cellular subscription burdens.
- RFID:Passive and active radio-frequency identification supports asset tracking applications with minimal power budgets and simplified regulatory pathways.
Cellular modules dominate revenue per unit through subscription layering. Bluetooth volumes are climbing fastest as consumer health applications proliferate.
End User:
Customer type determines procurement sophistication, with healthcare providers demanding FDA and EMA certifications while industrial manufacturers prioritize total cost of ownership and integration flexibility.
- Healthcare Providers:Hospital systems and home health agencies procure through group purchasing organizations with separate RFP processes for hardware and analytics platforms. FDA Digital Health Center of Excellence pre-submission reviews are accelerating wearable cardiac telemetry adoption.
- Transportation Companies:Fleet operators now mandate real-time geospatial telemetry as baseline procurement specification. Japanese commercial vehicle regulations above 3.5 tonnes are retrofitting cellular-enabled GPS trackers at volume scale.
- Sports Organizations:Performance monitoring applications drive demand for lightweight wearable form factors with simplified regulatory pathways.
- Industrial Manufacturers:Automation and predictive maintenance applications prioritize ruggedized data loggers with extended operational temperature ranges.
Healthcare providers dominate certification complexity and margin per unit. Transportation companies are where volume expansion concentrates through regulatory mandate absorption.
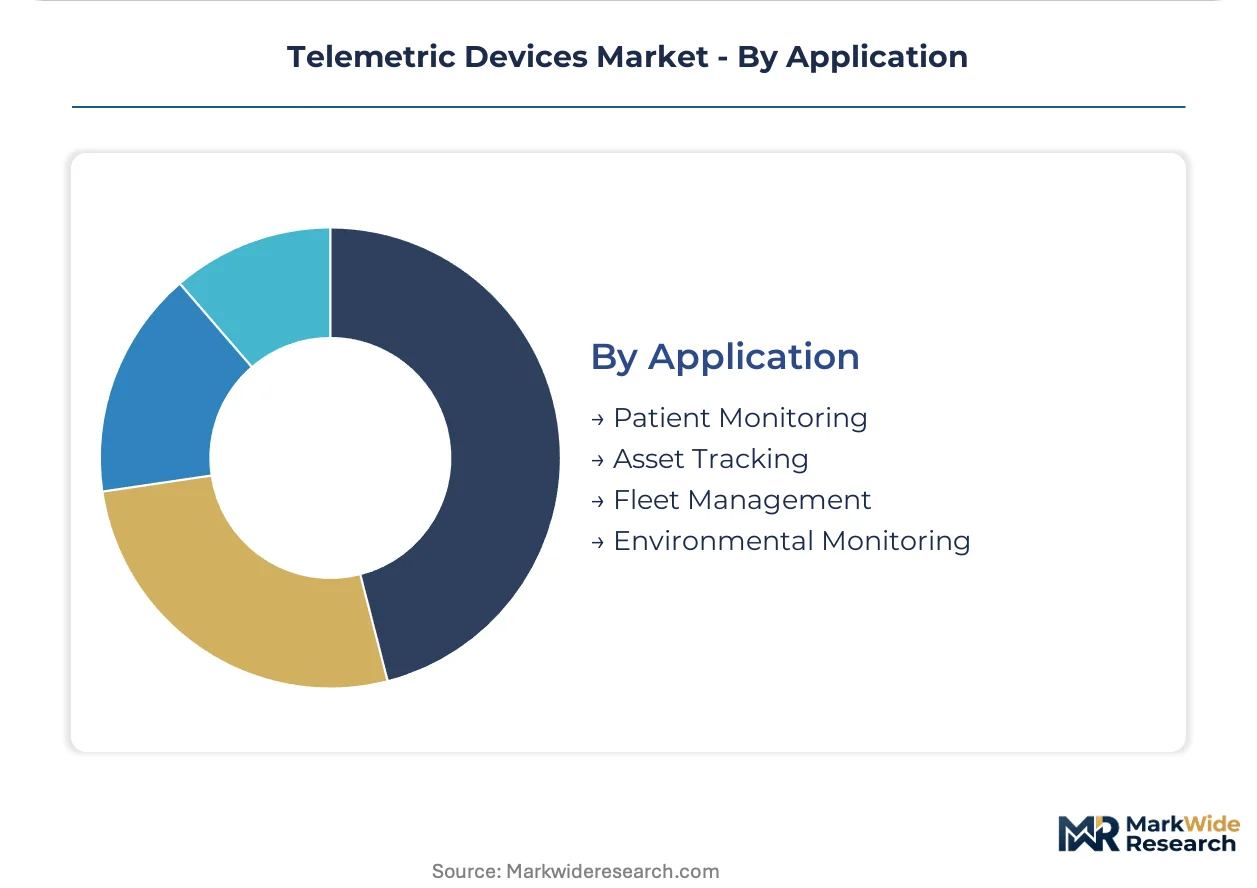
Application:
Maturity differentiation separates established patient monitoring workflows from emerging environmental monitoring deployments, with asset tracking and fleet management occupying intermediate growth trajectories.
- Patient Monitoring:Cardiac telemetry with embedded arrhythmia detection faces EU AI Act algorithmic transparency mandates. Siemens AG and Philips Healthcare are restructuring quality management systems for conformity assessment body requirements.
- Fleet Management:Real-time geospatial telemetry with electronic logging integration commands subscription-based revenue pools. German third-party logistics providers are embedding ultra-wideband positioning chips for decimeter-scale geofencing accuracy.
- Asset Tracking:Refrigerated container seals and high-value cargo monitoring leverage multi-protocol sensor fusion for insurance premium compression.
- Environmental Monitoring:Industrial and agricultural telemetry applications are expanding as regulatory frameworks mandate emissions and condition reporting.
Patient monitoring dominates clinical revenue concentration. Fleet management is where expansion accelerates through mandatory installation timelines and software subscription layering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telemetric device trade flows favor net-importing healthcare systems over manufacturing-heavy export corridors. The United States, Germany, and Japan absorb the majority of cellular-enabled remote monitor shipments. Regulatory harmonization pressures are compressing certification timelines across these demand centers.
United States
Hospital-at-home programs and remote patient monitoring contracts drive procurement volume. The FDA Digital Health Center of Excellence accelerates pre-submission reviews for wearable cardiac telemetry. Greater Boston anchors clinical trial networks where Philips Healthcare and Medtronic Plc validate bedside-to-cloud integration architectures.
Germany
Transportation fleets and third-party logistics providers mandate real-time geospatial telemetry as baseline specification. The EU Medical Device Regulation harmonizes conformity assessment for wearable monitors across member states. Bavaria's medical technology cluster hosts Siemens AG diagnostic imaging operations serving European clinical networks.
Japan
Commercial vehicle operators retrofit cellular-enabled GPS trackers under METI electronic logging mandates. The PMDA governs patient-facing telemetry through streamlined Class II pathways for home health applications. The Kanto region concentrates semiconductor packaging capacity for 5G RedCap chipset integration.
India
The Ayushman Bharat Digital Mission subsidizes remote diagnostic device deployment across rural primary health centers. CDSCO and BIS frameworks govern medical device import and local manufacturing standards. Karnataka's Bengaluru-Tumkur corridor attracts cellular module assembly investments serving South Asian demand.
South Korea
Industrial automation and predictive maintenance applications expand telemetry adoption in manufacturing supply chains. The MFDS regulates patient-facing devices while the central bank monitors cross-border data flows for connected health platforms. The Seoul Capital Area hosts RF front-end foundries supplying power amplifier modules.
Telemetric Devices Market Competitive Environment
Listed leaders compete with private specialists across certification complexity and subscription revenue layering. The vendor base stratifies into three tiers: diversified conglomerates with diagnostic imaging heritage, implantable device pure-plays, and cellular connectivity module suppliers. Strategic archetypes include hospital system integrators, fleet telematics bundlers, and industrial automation enablers. Consolidation concentrates through M&A targeting software-defined radio capabilities and geographic expansion into subsidized public health frameworks.
Among diversified healthcare conglomerates, Siemens AG and Philips Healthcare exemplify the hospital-system integrator archetype through European clinical network anchoring. Medtronic Plc occupies the implantable device specialist tier with FDA Class II pathway leadership. Sierra Wireless, Inc. represents the cellular connectivity pure-play model serving transportation and industrial telemetry applications.
| Leading Market Players |
|---|
| Siemens AG |
| GE Healthcare |
| Philips Healthcare |
| Schlumberger Limited |
| Schneider Electric |
| Honeywell International Inc. |
| Cobham Plc |
| Sierra Wireless, Inc. |
| Medtronic Plc |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with East Asian foundries lock in semiconductor module access while capping price volatility for cellular-enabled device assemblers. These contracts tether procurement visibility to 5G RedCap chipset allocation pools serving German transportation fleets and Japanese logistics operators.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in telemetric device procurement. Premium tiers command positioning through FDA Class II certification and embedded cellular subscription bundling, while economy Bluetooth wearables compete on unit cost and battery endurance. Cost compression in mid-tier remote monitors intensifies because Qualcomm and MediaTek 5G RedCap chipsets expand supplier choice. Healthcare providers demonstrate lowest price sensitivity due to reimbursement-backed procurement, whereas consumer health segments prioritize unit economics over feature depth.
Supply Chain Analysis
Inventory carrying costs inflate when regional spectrum fragmentation forces hardware variants for 868 MHz and 915 MHz band compliance across European and North American deployments. Component sourcing centers on Taiwan and South Korea for RF front-end foundries, China for lithium-polymer cell production, and Japan for precision sensor packaging. Gallium arsenide wafer supply for power amplifier modules rests on concentrated East Asian refining capacity. Tariff exposure on Chinese battery cells complicates European device assembler procurement strategies. Distribution runs through industrial distributors for GPS trackers and fleet telematics, while remote monitors flow through GPO-negotiated hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded firmware engineering talent for IEC 62304 medical software lifecycle compliance remains scarcer than hardware manufacturing capacity, compressing vendor differentiation around regulatory submission velocity rather than sensor specification alone.
For Market Incumbents: Shield service contract renewals by embedding software-defined radio flexibility into hardware refresh cycles before Bluetooth-cellular hybrid architectures commoditize connectivity modules. Deepen backward integration into RF front-end semiconductor sourcing to offset gallium arsenide wafer lead time volatility. Prioritize FDA Digital Health Center of Excellence pre-submission pathway investments to accelerate wearable cardiac telemetry approvals ahead of EMA MDR harmonization deadlines. For New Entrants and Emerging Players: Anchor in India's Ayushman Bharat Digital Mission subsidized procurement frameworks where incumbent presence remains thin across rural primary health centers. Target refrigerated container seal applications for third-party logistics providers in Germany seeking decimeter-scale geofencing accuracy through ultra-wideband positioning integration. Pursue fleet telematics retrofit opportunities under Japan's METI electronic logging mandates as the most penetrable regulatory-driven volume window. For Investors and Strategic Acquirers: Cellular connectivity pure-plays with software subscription layering capabilities represent the most defensible acquisition archetype as hardware margins compress. Long-term viability hinges on recurring revenue attachment rates rather than device shipment volumes alone. Monitor FCC spectrum reallocation proceeding outcomes as the critical inflection signal for unlicensed band device certification cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| 5G RedCap Module Integration | Qualcomm and MediaTek chipset adoption compresses bill-of-materials overhead for mid-tier remote monitors. |
| FDA Pre-Submission Pathway Investment | Digital Health Center of Excellence engagement accelerates wearable cardiac telemetry review timelines for home health expansion. |
| Bluetooth-Cellular Hybrid Architecture | Seamless protocol handoff enables hospital-at-home programs to extend surveillance beyond facility walls. |
| EMA MDR Harmonization Compliance | Unified conformity assessment reduces cross-border certification redundancy for European wearable monitor distribution. |
| Ultra-Wideband Positioning Embedding | Apple and Samsung semiconductor miniaturization enables decimeter-scale geofencing for high-value cargo insurance premium compression. |
Study Parameters
A standing panel of biomedical engineers, hospital GPO contracts managers, fleet operations directors, and cellular module procurement leads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, FCC equipment authorization databases, EMA MDR conformity assessment body records, and METI regulatory implementation notices. Bottom-up device shipment modeling triangulated against top-down connectivity subscription revenue estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, technology protocol, end-user segment, and application dimensions. CAGRs derived from segment-level growth trajectory blending over the projection horizon. Industry-specific forecast inputs incorporated electronic logging mandate compliance timelines and spectrum reallocation proceeding schedules.
Decision-makers should treat outputs as directional under assumptions of stable FCC and EMA regulatory frameworks; material deviation in certification timeline compression or chipset supply concentration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Consumer 3D Sensing Products Market
Sensors
Personal Navigation Devices Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Indoor Air Quality Monitor Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Weigh-In-Motion System Market
Sensors
Global Equipment Monitoring Market
Sensors
Alcohol Sensor Market
Sensors
Temperature Data Loggers Market
Sensors
Transportation Sensors Market
Sensors
Asia Pacific RFID Market
Sensors
Residential Water Leak Detection System Market
Sensors
Vibration Monitoring Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Safety Motion Control System Market
Sensors
Conveyor Monitoring Market