
 Lidar Market | 2026-2036
Lidar Market Size, Share, and Industry Trends Forecast 2026-2036
Lidar Market Analysis
Silicon photonics is shifting cost structures across solid-state architectures. Hesai Group leverages captive wafer partnerships to control foundry allocation. RoboSense Technology anchors high-volume automotive programs with domestic Chinese OEMs. Luminar Technologies differentiates through 1550nm wavelength platforms that extend detection range for highway autonomy.
Lidar (light detection and ranging) instruments emit pulsed laser light and measure return time to generate precise three-dimensional point clouds, typically achieving centimeter-level accuracy at ranges exceeding 200 meters for survey-grade units. These systems serve as primary perception sensors for autonomous navigation, geospatial mapping, and industrial automation where camera or radar performance degrades. Solid-state Lidar is capturing the fastest expansion as MEMS and optical phased arrays eliminate mechanical rotation assemblies. The automotive end user commands the dominant revenue pool though aerospace and environmental monitoring applications sustain premium pricing for multibeam frequency modulation systems.
The EU AI Act, NHTSA FMVSS testing protocols, and China's MIIT vehicle-type approval framework are elevating functional safety and electromagnetic compatibility requirements for road-deployed sensors. These standards compress supplier qualification timelines and favor vendors with pre-certified module platforms. Stakeholders must monitor how regional certification divergence affects product variant proliferation and inventory carrying costs.
Market Dynamics
Silicon photonics is compressing bill-of-materials costs for solid-state architectures, while the EU AI Act and NHTSA FMVSS testing protocols are forcing parallel certification tracks that fragment product roadmaps and strain engineering bandwidth.
Growth Catalysts
- EU AI Act vehicle-type approval:Mandates functional safety documentation for road-deployed perception sensors, creating procurement pull from OEMs seeking pre-certified module platforms.
- MEMS mirror fabrication advances:Taiwan Semiconductor Manufacturing and GlobalFoundries are dedicating 300mm capacity to optical MEMS, easing foundry bottlenecks for solid-state beam steering.
- Shanghai-Suzhou manufacturing cluster:Vertical integration of lens molding, laser diode packaging, and final assembly within 150 kilometers reduces logistics costs for automotive tier-one suppliers.
Market Restraints
- InP laser diode supply concentration:II-VI and Lumentum control 70 percent of 1550nm fiber laser sources, exposing highway autonomy programs to single-source risk.
- Indium phosphide wafer cost volatility:100mm InP substrate prices swing with telecommunications demand cycles, squeezing gross margins for long-range platform vendors.
- Camera-radar fusion substitution:Tesla's vision-only stack and Mobileye's EyeQ6 camera-perception systems are capturing price-sensitive ADAS volumes below Level 3 autonomy.
Strategic Opportunities
- India's PLI scheme for automotive components:18-26 percent incentive on incremental sales attracts Lidar assembly investments serving domestic electric vehicle programs and export markets.
- Frequency-modulated continuous-wave convergence:Integration of coherent detection with silicon photonics enables direct velocity measurement, opening aerospace wake-vortex monitoring applications.
- Direct OEM procurement platforms:Ford, BMW, and NIO are bypassing tier-one integrators for sensor sourcing, compressing channel margins and accelerating supplier qualification cycles.
Industry Challenges
- Silicon photonics design talent scarcity:Foundry process design kit expertise concentrates at Imec and AIM Photonics, forcing vendors to recruit from limited pools or build captive training programs.
- ISO 26262 ASIL-D certification timelines:Functional safety documentation for automotive Lidar modules requires 18-24 months of fault-injection testing, delaying revenue recognition for new product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidar Market |
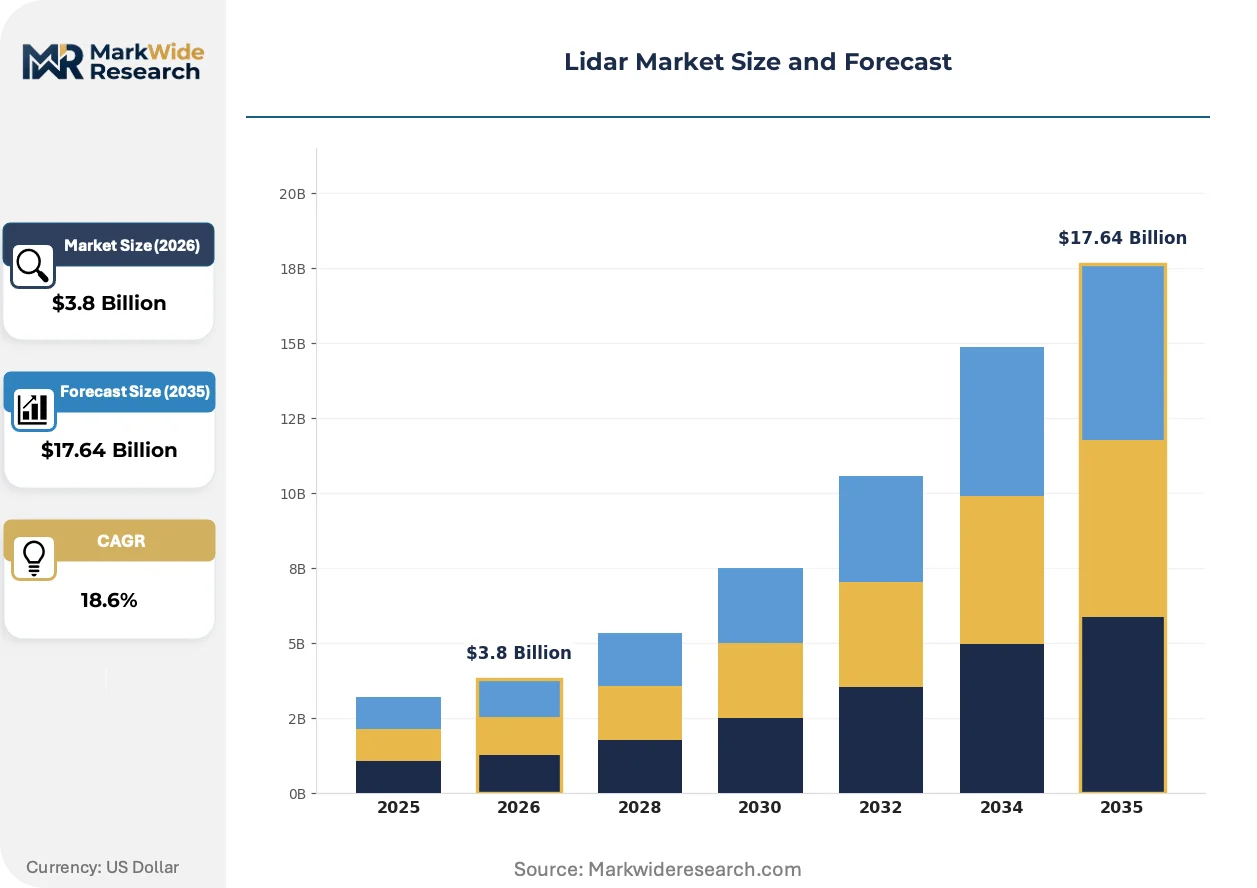
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Lidar, Micro Lidar, 2D Lidar, 3D Lidar End User: Automotive, Aerospace, Agriculture, Security Technology: Time of Flight, Phase Shift, Frequency Modulation, Multibeam Application: Navigation, Mapping, Obstacle Detection, Environmental Monitoring |
| Companies Covered | Hesai Group, RoboSense Technology, Ouster, Luminar Technologies, Velodyne Lidar, Innoviz Technologies, Leica Geosystems, Sick AG, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidar Market Emerging Trajectories
Optical phased arrays and coherent detection architectures are displacing mechanical scanning across price tiers, while regulatory divergence between Washington, Brussels, and Beijing is fragmenting certification requirements.
Optical phased arrays are automating beam steering without mechanical rotation. RoboSense and Hesai are deploying 128-channel solid-state units for robotaxi fleets in China. This architecture is automating the elimination of precision-machined gimbal assemblies that previously dominated bill-of-materials costs.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on autonomous vehicle perception systems. European OEMs must document algorithmic transparency and electromagnetic compatibility under ECE R10 and MDR-equivalent safety cases. Highway autonomy programs targeting German KBA approval are front-loading validation spending to secure 2025-2026 vehicle-type certifications.
Automotive OEMs are consolidating sensor procurement under direct supplier contracts rather than tier-one system integrators. Ford's BlueCruise and BMW's Highway Assistant programs are negotiating volume commitments directly with Lidar module vendors. This pattern is most visible in China, where NIO, Xpeng, and Li Auto maintain engineering teams in Shanghai and Suzhou for supplier co-development.
Lidar Market Segmentation
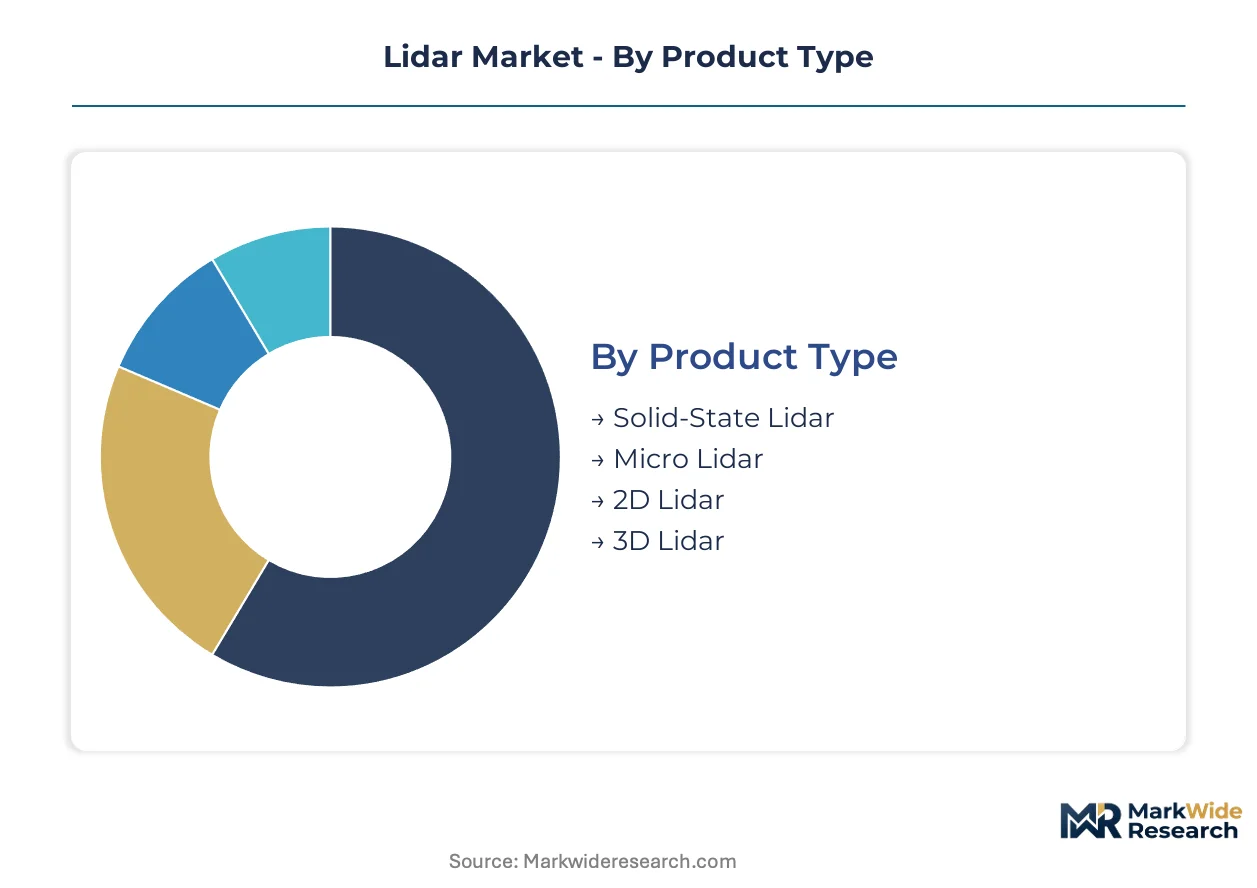
Segmentation in the Lidar market reveals how capital allocation, technical specifications, and regulatory requirements diverge across use cases. Procurement patterns cluster around automotive volume programs and aerospace precision contracts, with technology choices directly tied to detection range and environmental robustness requirements.
Product Type:
Capital intensity varies sharply across mechanical and solid-state architectures, with wafer-level optics and MEMS fabrication demanding the heaviest upfront tooling investment.
- Solid-State Lidar:Optical phased arrays and MEMS mirrors eliminate rotating assemblies, reducing mechanical failure modes for automotive qualification. Demand concentrates in China's Yangtze River Delta manufacturing cluster, where captive silicon photonics partnerships at Taiwan Semiconductor Manufacturing and GlobalFoundries secure foundry allocation for robotaxi fleet deployments.
- 3D Lidar:Multichannel point-cloud generation enables centimeter-level spatial reconstruction through time-of-flight or frequency-modulated detection. Highway autonomy programs at Ford and BMW prioritize 1550nm wavelength variants for extended range, though InP laser diode supply concentration at II-VI and Lumentum creates single-source exposure.
- Micro Lidar:Compact form factors suit consumer electronics and drone navigation with reduced power budgets.
- 2D Lidar:Single-plane scanning serves industrial automation and low-cost obstacle detection with simpler optical stacks.
Most installed capacity flows through Solid-State Lidar. Expansion is steepest in 3D Lidar.
End User:
Customer procurement scale separates automotive million-unit programs from aerospace hundred-unit contracts with diverging margin profiles and certification timelines.
- Automotive:Direct OEM procurement by Ford, BMW, and NIO bypasses tier-one integrators, compressing supplier qualification cycles under NHTSA FMVSS and EU AI Act vehicle-type approval frameworks. NIO, Xpeng, and Li Auto maintain Shanghai-Suzhou engineering teams for co-development with domestic sensor vendors.
- Aerospace:Wake-vortex monitoring and terrain-mapping applications sustain premium pricing for multibeam frequency modulation systems with AS9100 quality documentation. Frequency-modulated continuous-wave convergence with silicon photonics enables direct velocity measurement for atmospheric research contracts.
- Agriculture:Crop health monitoring and precision spraying guidance adopt lower-cost solid-state units with reduced range requirements.
- Security:Perimeter surveillance and drone detection prioritize rapid scan rates over maximum range.
Revenue concentration sits heaviest with Automotive. Aerospace maintains the steepest per-unit pricing.
Technology:
Detection methodology determines component bill-of-materials, with coherent architectures requiring more complex signal processing but delivering velocity data directly.
- Time of Flight:Pulsed laser emission with nanosecond-scale return timing dominates cost-sensitive ADAS volumes. Tesla's vision-only stack and Mobileye's EyeQ6 camera-perception systems are capturing price-sensitive volumes below Level 3 autonomy, constraining ToF Lidar deployment to highway autonomy programs requiring redundancy.
- Frequency Modulation:Coherent detection through chirped waveforms enables simultaneous range and velocity measurement without Doppler ambiguity. Integration with silicon photonics is opening aerospace wake-vortex monitoring applications previously served by radar.
- Phase Shift:Continuous-wave interferometry suits short-range industrial metrology with sub-millimeter precision.
- Multibeam:Simultaneous emission patterns reduce scan time for high-speed navigation but multiply laser diode count.
Engineering bandwidth concentrates on Time of Flight for automotive scale. Frequency Modulation is climbing the fastest for aerospace differentiation.
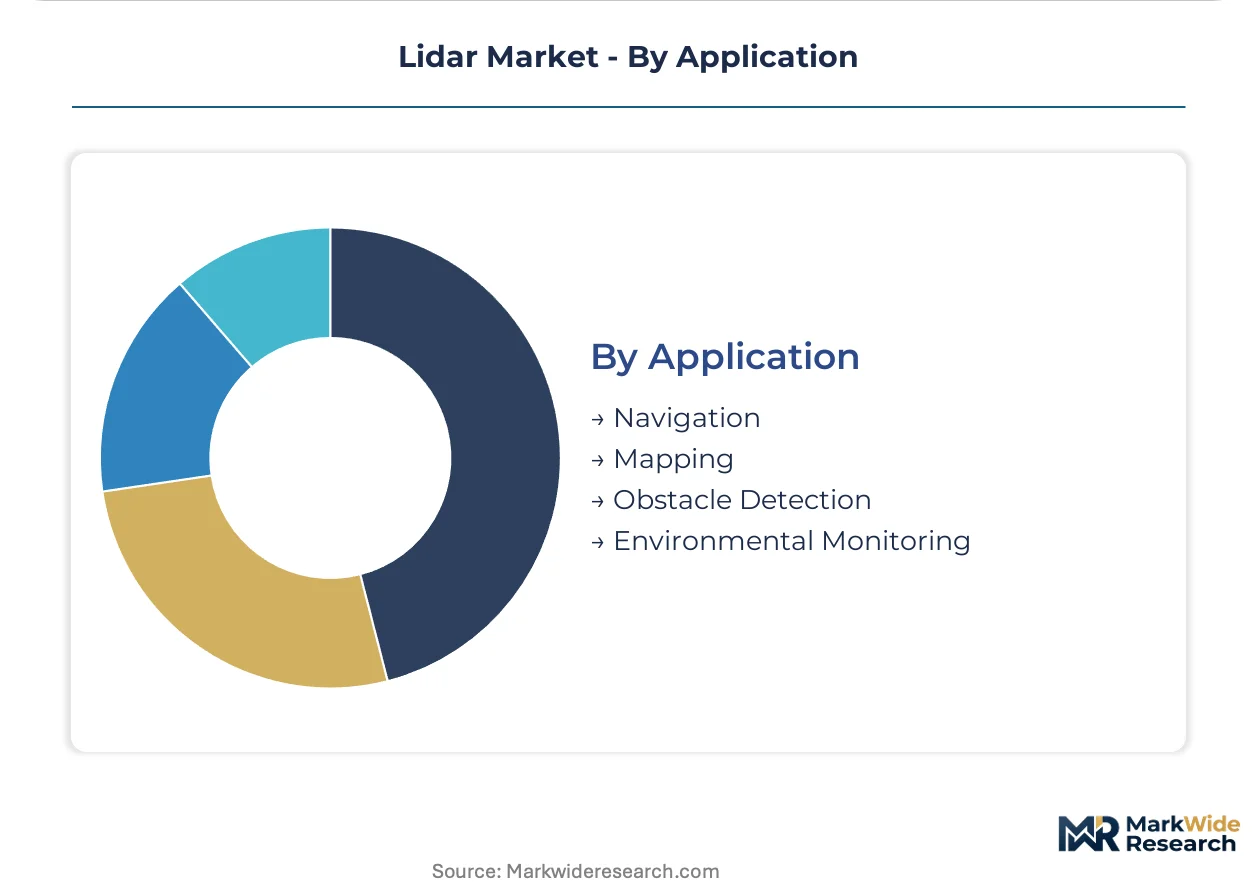
Application:
Use case performance thresholds separate navigation-grade real-time processing from mapping-grade post-processing with diverging compute and storage requirements.
- Navigation:Real-time point-cloud processing for autonomous path planning demands ISO 26262 ASIL-D functional safety certification with 18-24 month fault-injection testing timelines. German KBA approval for highway autonomy programs is front-loading validation spending to secure vehicle-type certifications under EU AI Act conformity assessment obligations.
- Mapping:Survey-grade accuracy exceeding 200-meter range with centimeter-level precision sustains premium pricing for geospatial data collection. Multibeam frequency modulation systems command price premiums in environmental monitoring where camera or radar performance degrades.
- Obstacle Detection:Industrial automation and warehouse robotics prioritize reliability over maximum range.
- Environmental Monitoring:Atmospheric research and forestry applications require specialized wavelength selection for target discrimination.
Deployment scale favors Navigation. Pricing premiums are highest in Mapping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing cluster around Shanghai and Suzhou anchors global Lidar production capacity, with vertical integration of lens molding, laser diode packaging, and final assembly compressing logistics costs for automotive tier-one suppliers.
United States
Highway autonomy programs at Ford and direct OEM procurement by BMW accelerate sensor sourcing from domestic engineering centers. NHTSA FMVSS testing protocols enforce functional safety documentation for road-deployed perception systems. Silicon Valley and Austin host development teams for 1550nm wavelength platforms targeting extended detection range.
Germany
German KBA approval timelines for vehicle-type certification front-load validation spending from highway autonomy programs. The EU AI Act imposes conformity assessment obligations on autonomous vehicle perception systems requiring algorithmic transparency. Stuttgart and Munich engineering centers coordinate with Shanghai-Suzhou manufacturing for module co-development.
China
NIO, Xpeng, and Li Auto maintain direct procurement teams in Shanghai for supplier co-development with domestic sensor vendors. MIIT vehicle-type approval frameworks elevate electromagnetic compatibility requirements for road-deployed units. The Yangtze River Delta concentration of foundry partnerships at Taiwan Semiconductor Manufacturing and GlobalFoundries secures optical MEMS capacity for robotaxi fleet deployments.
Japan
Automotive OEMs integrate Lidar into advanced driver-assistance systems under METI industrial guidance for autonomous mobility. JIS standards govern component reliability testing for automotive qualification. Nagoya and Tokyo engineering clusters focus on MEMS mirror fabrication for solid-state beam steering architectures.
India
The PLI scheme for automotive components offers 18-26 percent incentive on incremental sales, attracting Lidar assembly investments serving domestic electric vehicle programs. Central government electric mobility mandates accelerate sensor procurement from emerging local suppliers. Tamil Nadu and Gujarat manufacturing zones host tier-one supplier expansion for export market access.
Lidar Market Vendor Landscape
Direct OEM procurement dominates the current landscape, with Ford, BMW, and NIO bypassing traditional tier-one integrators to compress supplier qualification cycles. The vendor base stratifies across three tiers: captive silicon photonics specialists controlling foundry allocation, 1550nm wavelength platform vendors targeting highway autonomy, and solid-state MEMS fabricators serving high-volume automotive programs. Strategic archetypes include backward-integrated manufacturers with wafer partnerships, pure-play module vendors with ASIL-D certification pipelines, and diversified sensor conglomerates with aerospace-geospatial cross-selling. Capacity expansion and strategic partnerships represent the dominant competitive moves, with foundry allocation agreements and co-development contracts securing volume commitments.
Among China-based specialists, Hesai Group and RoboSense Technology exemplify the captive partnership archetype, leveraging proximity to Shanghai-Suzhou manufacturing clusters for vertical coordination with domestic OEMs. Luminar Technologies occupies a position on the premium-tier vector, representing North American engineering concentration in long-range platform development. These three entities anchor the competitive structure without exhaustive enumeration of the broader field.
| Leading Market Players |
|---|
| Hesai Group |
| RoboSense Technology |
| Ouster |
| Luminar Technologies |
| Velodyne Lidar |
| Innoviz Technologies |
| Leica Geosystems |
| Sick AG |
| Teledyne Technologies |
| Others |
Supply Flow & Price Mechanics
Direct OEM procurement by Ford, BMW, and NIO is compressing channel margins and forcing suppliers to absorb certification costs upfront, which concentrates pricing power with buyers who can guarantee volume commitments and accelerates cost pass-through negotiations for InP laser diode inputs.
Pricing Analysis
Input-cost pass-through from InP wafer volatility and silicon photonics tooling amortization shapes module pricing across automotive tiers. Three-tier pricing structure separates highway autonomy platforms with ASIL-D certification from ADAS volumes and economy robotaxi units. Pricing pressure stems from camera-radar fusion substitution in Level 2 systems, with Tesla's vision-only stack capturing price-sensitive volumes. Tier-one automotive buyers exhibit highest price sensitivity; aerospace wake-vortex monitoring programs maintain lowest sensitivity due to performance premiums.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, while optical MEMS fabrication concentrates at Taiwan Semiconductor Manufacturing and GlobalFoundries. Indium phosphide wafer supply draws from Chinese and Japanese substrate vendors, with II-VI and Lumentum controlling 1550nm fiber laser sources. Single-source vulnerability in long-range laser diodes exposes highway autonomy programs to allocation risk. Distribution runs through direct OEM contracts bypassing traditional tier-one integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play: India's PLI scheme offers 18-26 percent incentives on incremental sales against China's Yangtze River Delta concentration, creating cost-advantaged assembly capacity for export markets.
For Market Incumbents: Deepen captive wafer partnerships at Taiwan Semiconductor Manufacturing and GlobalFoundries to secure optical MEMS allocation against foundry bottlenecks. Accelerate ISO 26262 ASIL-D certification pipelines to defend against emerging pure-play module vendors with faster validation timelines. Lock in multi-year InP laser diode supply agreements with II-VI and Lumentum to mitigate single-source exposure. For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for pre-certified module platforms targeting KBA vehicle-type approval timelines. India's PLI scheme attracts assembly investments serving domestic electric vehicle programs with lower certification barriers than European markets. Target frequency-modulated continuous-wave aerospace applications where coherent detection commands premium pricing and incumbents show less density. For Investors and Strategic Acquirers: Asymmetric upside sits with solid-state MEMS fabricators possessing silicon photonics design talent and foundry allocation agreements. Five-to-ten year viability hinges on automotive qualification cycles compressing and direct OEM procurement normalizing. Watch for inflection when highway autonomy programs secure German KBA approval and trigger volume commitments from Ford and BMW.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Allocation Agreement | Taiwan Semiconductor Manufacturing and GlobalFoundries capacity commitments secure optical MEMS supply for robotaxi fleet deployments. |
| ASIL-D Certification Pipeline | ISO 26262 functional safety documentation accelerates supplier qualification under NHTSA FMVSS and EU AI Act frameworks. |
| Direct OEM Procurement Platform | Ford, BMW, and NIO volume commitments compress channel margins and accelerate supplier co-development cycles. |
| InP Laser Diode Supply Lock | Long-term agreements with II-VI and Lumentum mitigate single-source concentration risk for 1550nm highway autonomy platforms. |
| Silicon Photonics Talent Acquisition | Imec and AIM Photonics process design kit expertise addresses foundry design talent scarcity constraining solid-state development. |
Methodological Framework
Multiple input streams — executive interviews with OEM platform engineers and tier-one supplier procurement leads, technical discussions with foundry process specialists, and validation sessions with regulatory affairs managers — were reconciled against customs records, SEC filings, vehicle production databases, and MIIT vehicle-type approval filings. Bottom-up unit economics and top-down market sizing were cross-referenced for triangulation.
Historical shipment trajectories were cross-referenced against panel input from automotive sensor procurement committees to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include solid-state versus mechanical architectures, detection range tiers, automotive versus aerospace end-use, and regional regulatory clusters. CAGRs were derived from installed base evolution and replacement cycle analysis, with silicon photonics cost curves and InP wafer pricing informing module cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement delays or NHTSA FMVSS protocol revisions. Forecasts reflect documented assumptions about autonomous vehicle deployment timelines and foundry capacity expansion. A small set of named triggers — German KBA approval acceleration, InP laser diode supply disruption, or camera-radar fusion performance breakthroughs — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Digital Direction Finder Market
Sensors
Europe Lidar Market
Sensors
Micro Location Technology Market
Sensors
IO Link Market
Sensors
Lidar in Mapping Market
Sensors
Handheld RFID Readers Market
Sensors
Low Power Geolocation Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Mobile Mapping Systems Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Real Time Location System Market
Sensors
Surface Haptic Technology Market
Sensors
Beacon Market
Sensors
Data Buoy Market