
 Vibration Monitoring Market | 2026-2036
Vibration Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Vibration Monitoring Market Intelligence
Market Context
Buyer concentration among energy utilities and aerospace OEMs is expanding as these sectors consolidate vendor relationships around full-service condition monitoring contracts. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor long-term service agreements with downstream refiners. SKF competes through its bearing-integrated sensor architecture, which reduces installation complexity for rotating equipment operators. Baker Hughes Company dominates offshore energy deployments with ruggedized hardware designed for subsea vibration measurement.
Technical Definition and Segment Structure
Vibration monitoring encompasses the systematic measurement, analysis, and interpretation of mechanical oscillations in rotating and reciprocating machinery using piezoelectric accelerometers, eddy-current displacement probes, and laser Doppler vibrometers to detect imbalance, misalignment, bearing degradation, and structural fatigue before catastrophic failure occurs. Accelerometers lead product type revenue due to their versatility across frequency ranges and established calibration traceability to ISO 16063 standards, while wireless technology segments are gaining fastest as battery-harvested sensors eliminate cabling costs in hazardous zones. Predictive maintenance applications command the deepest margin pools because customers pay premium pricing for algorithm-driven failure forecasting that converts unplanned outages into scheduled interventions.
Regulatory Environment and Outlook
OSHA machinery guarding standards and EPA emissions compliance requirements in the United States, coupled with EU Machinery Directive 2006/42/EC and ATEX equipment safety rules in Europe, mandate documented equipment integrity programs that institutionalize vibration analysis as a compliance layer. China's SAMR enforcement of GB/T mechanical safety standards and India's CEA grid code reliability mandates for power generation assets are extending comparable obligations across Asia. Stakeholders must monitor how regulatory convergence on digital audit trails reshapes procurement criteria toward integrated hardware-software platforms with native data sovereignty controls.
Market Dynamics
The transition from wired to wireless sensor architectures is restructuring competitive advantage around battery-harvesting efficiency and mesh-network reliability rather than hardware durability alone. This shift favors vendors with embedded software competency over traditional instrumentation specialists.
Growth Catalysts
- OSHA machinery guarding enforcement:Documented equipment integrity programs in US manufacturing now mandate continuous vibration surveillance, institutionalizing sensor deployment as a compliance layer rather than discretionary maintenance spend.
- Offshore wind capacity expansion:Turbine operators in the North Sea and Baltic regions require ruggedized subsea measurement systems to monitor drivetrain health in corrosive marine environments.
- Edge computing integration:On-device analytics at the sensor node level reduces latency for critical-rotating equipment alerts in petrochemical facilities.
Market Restraints
- Piezoelectric ceramic supply concentration:Sourcing of high-sensitivity sensing elements depends on limited specialty material processors in Japan and Germany, creating input vulnerability.
- ATEX certification timelines:Hazardous-zone equipment approvals in Europe extend deployment cycles by 8-14 months, compressing vendor cash conversion.
- Optical vibrometry cost floor:Laser-based non-contact measurement remains prohibitively expensive for mid-tier manufacturing, capping addressable market expansion.
Strategic Opportunities
- India CEA grid code mandates:Central Electricity Authority reliability requirements for thermal power assets create first-time vibration monitoring obligations across state generation companies.
- Battery-harvesting convergence with LPWAN protocols:LoRaWAN and NB-IoT integration enables decade-long unattended sensor operation in remote mining conveyors.
- Digital audit trail standardization:EU Machinery Directive amendments pushing native data sovereignty controls favor integrated hardware-software platforms over point-sensor vendors.
Industry Challenges
- ISO 16063 calibration expertise scarcity:Qualified metrology technicians for accelerometer traceability are concentrated in aging workforce pools across industrial regions.
- Legacy DCS integration complexity:Brownfield installations require protocol bridging between modern wireless sensors and decades-old distributed control system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vibration Monitoring Market |
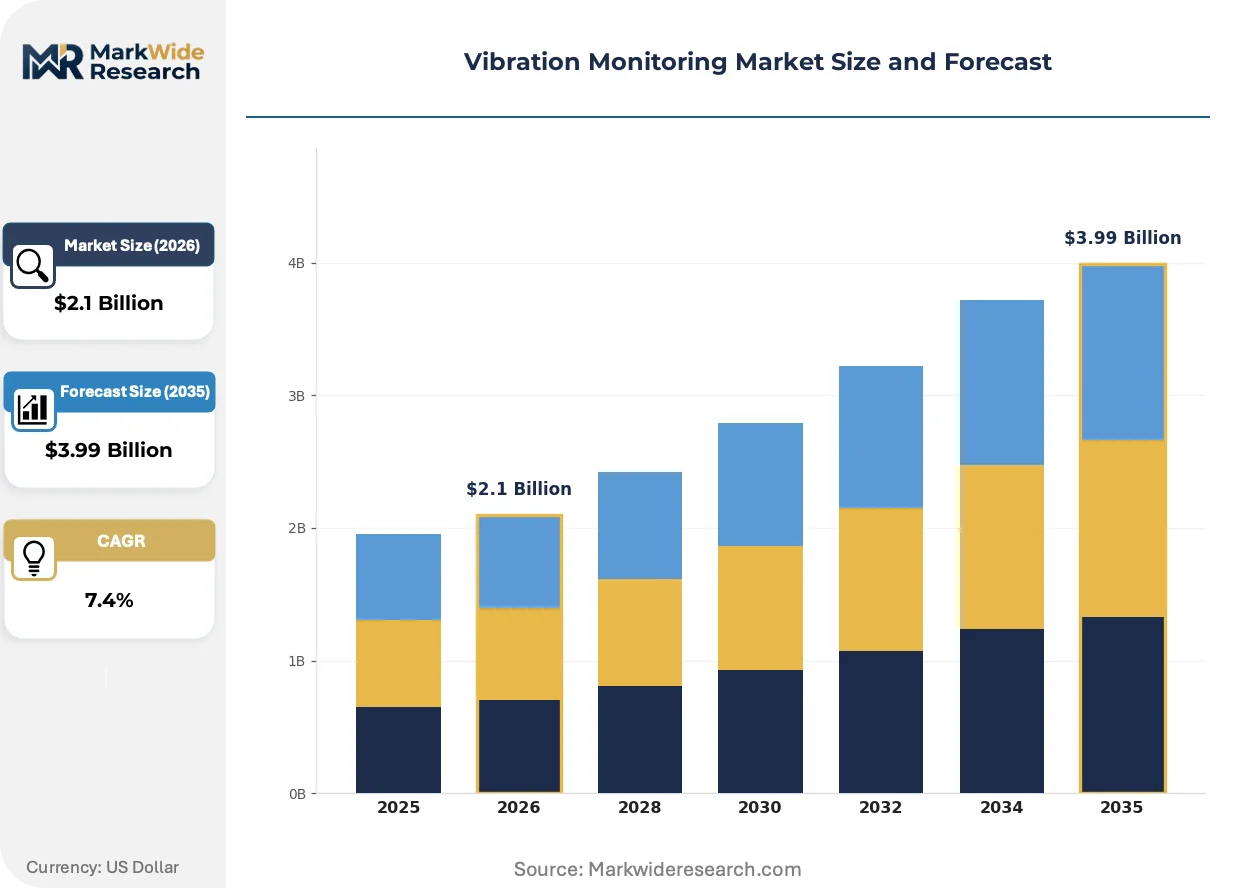
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Displacement Sensors, Velometers, Data Acquisition Systems Technology: Wireless, Wired, IVHM, Handheld End User: Manufacturing, Aerospace, Automotive, Energy Application: Predictive Maintenance, Condition Monitoring, Quality Control, Structural Health |
| Companies Covered | Baker Hughes Company, Emerson Electric Co., SKF, Schaeffler AG, Parker Hannifin Corp, Honeywell International Inc., Rockwell Automation, Analog Devices, Inc., Brüel & Kjær, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vibration Monitoring Market Strategic Shifts & Innovations
Sensor miniaturization and energy-autonomous operation are collapsing the installed cost gap between continuous monitoring and periodic manual inspection, rewiring buyer economics across capital-intensive sectors.
MEMS-based accelerometers are absorbing functions previously requiring macro-scale piezoelectric assemblies, enabling sub-dollar sensor nodes that cement plant operators in chemical processing deploy by the thousand. The technology is absorbing vibration surveillance into standard motor control panels, compressing the addressable market for standalone monitoring systems into high-criticality equipment only.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-leak detection mandates that bundle vibration analysis into integrated compressor health platforms for HVAC-R OEMs. Industrial refrigeration operators in Germany and France now specify combined thermal-acoustic-vibration sensor packages to satisfy consolidated compliance reporting.
Service unbundling is fragmenting long-term condition-monitoring contracts into discrete diagnostic subscriptions, with aerospace MRO facilities in the US Southwest purchasing per-flight-hour analytics rather than capitalizing sensor hardware. This consumption-pattern shift transfers obsolescence risk to vendors while compressing upfront procurement thresholds for fleet operators.
Vibration Monitoring Market Segmentation
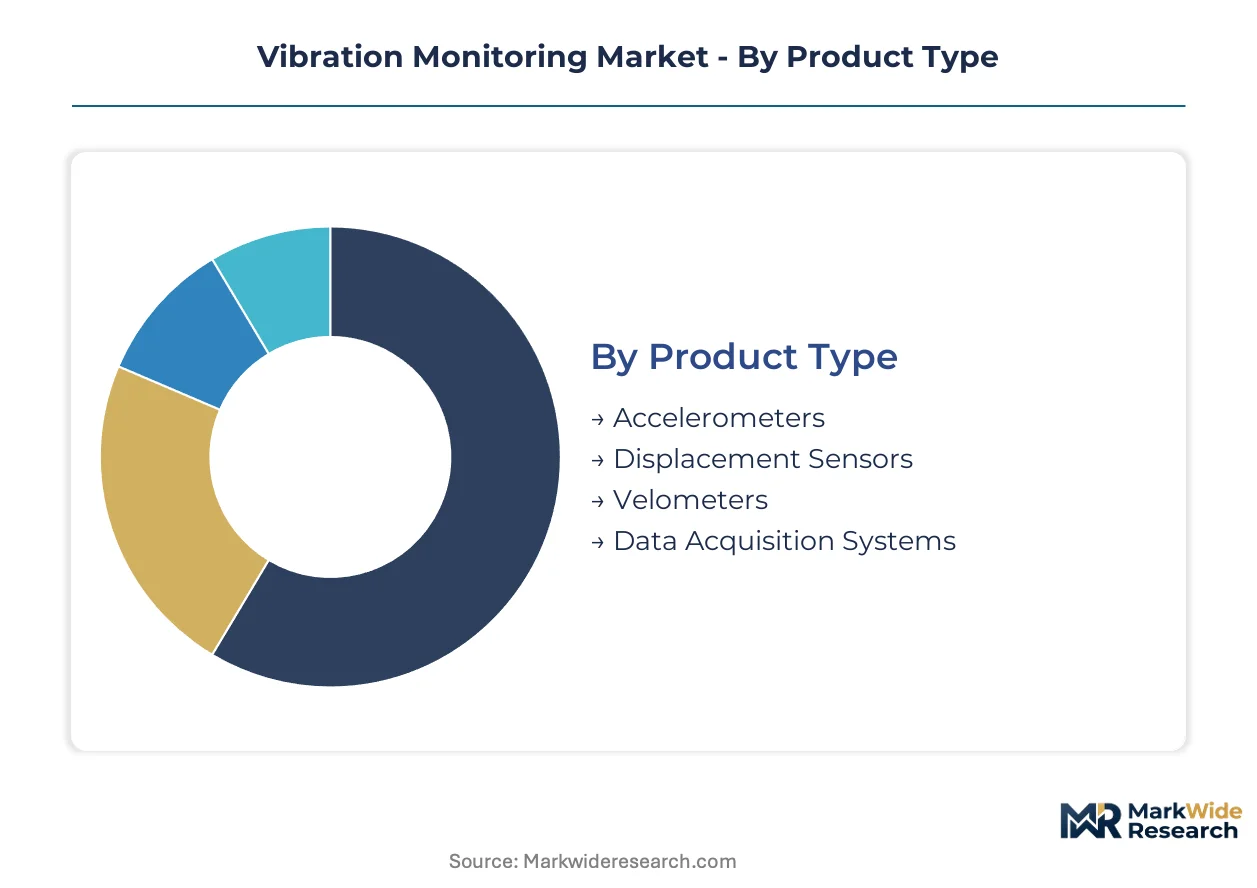
Vibration monitoring procurement splits sharply between standardized commodity sensors for broad plant deployment and engineered solutions for safety-critical rotating equipment. Understanding these segmentation boundaries exposes where margin pools concentrate versus where volume commoditization erodes pricing power.
Product Type:
Customization intensity varies from off-the-shelf MEMS chips to application-specific probe assemblies requiring metrological calibration chains.
- Accelerometers:Piezoelectric and MEMS variants measure vibration acceleration across 0.1 Hz to 30 kHz frequency ranges with ISO 16063 traceability. Demand clusters in chemical processing plants across Germany and Texas where OSHA machinery guarding mandates continuous bearing surveillance on pumps and compressors.
- Displacement Sensors:Eddy-current proximity probes track shaft relative vibration in turbomachinery with sub-micron resolution. Aerospace OEMs in Toulouse and Seattle specify these for jet engine test cell installations where non-contact measurement eliminates mechanical interference.
- Velometers:Velocity transducers integrate acceleration signals for low-frequency machinery health assessment in cooling tower fans and large HVAC systems.
- Data Acquisition Systems:Multi-channel hardware synchronizes sensor inputs with edge analytics for real-time alarm generation in petrochemical refineries.
Leading the category by volume: Accelerometers. Expanding most quickly: Data Acquisition Systems.
Technology:
Architecture choices determine total cost of ownership through installation labor, hazardous-zone cabling, and maintenance access requirements.
- Wireless:Battery-harvested sensors with LoRaWAN or NB-IoT backhaul eliminate conduit runs in explosive atmospheres. Mining operators in Western Australia and Chile deploy these across remote conveyor systems where technician access intervals stretch to quarterly schedules.
- Wired:Shielded coaxial and twisted-pair installations deliver deterministic signal integrity for high-frequency turbomachinery diagnostics in combined-cycle power plants.
- IVHM:Integrated Vehicle Health Management embeds vibration surveillance into platform-level prognostic frameworks for military rotorcraft and commercial aviation fleets.
- Handheld:Portable analyzers support periodic walk-around inspection programs in small and mid-sized machine shops with limited capital budgets.
Fastest-growing trajectory: Wireless. Largest installed base: Wired.
End User:
Industry verticals impose distinct performance specifications based on safety consequence classes and regulatory exposure.
- Manufacturing:Automotive stamping presses and CNC machining centers require spindle vibration surveillance to maintain surface finish tolerances and tool life economics.
- Aerospace:MRO facilities and engine OEMs mandate continuous drivetrain monitoring for airworthiness certification and fleet availability guarantees.
- Automotive:EV powertrain testing laboratories use vibration signature analysis to validate motor mount isolation and gearbox NVH performance.
- Energy:Wind turbine operators in the North Sea and combined-cycle plant owners in India deploy ruggedized systems for drivetrain and generator health management under CEA grid code reliability mandates.
Deepest margin capture: Energy. Broadest unit volume: Manufacturing.
Application:
Use case segmentation separates compliance-driven baseline monitoring from premium-priced predictive analytics delivering operational risk reduction.
- Predictive Maintenance:Machine learning algorithms process vibration trends to forecast bearing failures weeks before functional degradation. Refinery operators in Rotterdam and Houston pay premium subscriptions for algorithm-driven intervention scheduling that converts emergency shutdowns into planned turnarounds.
- Condition Monitoring:Continuous surveillance establishes equipment health baselines and triggers threshold-based alarms for immediate operator response.
- Quality Control:In-process vibration measurement validates machining stability and detects chatter-induced surface defects during precision component fabrication.
- Structural Health:Civil infrastructure deployments track bridge deck and building frame dynamic response under environmental loading for safety certification.
Highest value capture: Predictive Maintenance. Widest deployment base: Condition Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in three manufacturing powerhouses where machinery safety enforcement and infrastructure modernization converge. China, Germany, and the United States collectively anchor procurement volumes as industrial operators replace legacy wired installations with wireless sensor networks.
United States
OSHA machinery guarding standards mandate continuous vibration surveillance in refineries and chemical processing plants across the Gulf Coast. EPA emissions compliance requirements reinforce equipment integrity documentation for rotating machinery. Houston and Port Arthur host the densest deployments as downstream operators consolidate vendor relationships around full-service condition monitoring contracts.
Germany
EU Machinery Directive 2006/42/EC and ATEX equipment safety rules institutionalize vibration analysis as a compliance layer for industrial operators. F-Gas Regulation phase-down schedules accelerate bundled thermal-acoustic-vibration sensor specifications for HVAC-R OEMs. Industrial clusters in Bavaria and Baden-Württemberg drive premium demand for bearing-integrated sensor architectures that reduce installation complexity.
China
SAMR enforcement of GB/T mechanical safety standards extends documented equipment integrity obligations across state-owned manufacturing assets. Dual carbon goals pressure heavy industry to reduce unplanned downtime through predictive maintenance programs. Yangtze River Delta manufacturing plants are expanding wireless sensor deployments to eliminate cabling costs in hazardous production zones.
India
CEA grid code reliability mandates for thermal power assets create first-time vibration monitoring obligations across state generation companies. Central Electricity Authority requirements are forcing modernization of aging coal and gas turbine fleets. Maharashtra and Gujarat power corridors are absorbing the initial wave of sensor installations as public sector utilities comply with new reliability protocols.
Japan
METI industrial efficiency programs incentivize predictive maintenance adoption to sustain manufacturing competitiveness amid labor constraints. JIS standards for machinery safety provide calibration traceability frameworks for high-precision accelerometer deployments. Automotive and precision machinery clusters in Aichi Prefecture and the Kansai region maintain premium demand for eddy-current displacement probes in turbomachinery applications.
Vibration Monitoring Market Key Industry Players
German and Swedish producers anchor the precision instrumentation tier; US industrial conglomerates hold the integrated platform tier. The vendor base stratifies between full-service condition monitoring providers and specialized sensor fabricators. Three archetypes dominate: bearing-integrated sensor specialists, ruggedized offshore equipment suppliers, and digital ecosystem orchestrators. Competitive moves concentrate on strategic partnerships for wireless protocol integration and portfolio diversification into edge analytics software.
Within the integrated platform tier, Emerson Electric Co. and Rockwell Automation exemplify vendors anchoring long-term service agreements through digital ecosystem offerings. SKF occupies a position representing the bearing-integrated sensor archetype, reducing installation complexity for rotating equipment operators. Baker Hughes Company anchors the ruggedized offshore specialization, serving subsea vibration measurement requirements in corrosive marine environments.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Emerson Electric Co. |
| SKF |
| Schaeffler AG |
| Parker Hannifin Corp |
| Honeywell International Inc. |
| Rockwell Automation |
| Analog Devices, Inc. |
| Brüel & Kjær |
| Others |
Cost & Logistics Intelligence
Energy utility procurement consolidation around full-service condition monitoring contracts anchors subscription-based pricing models across the vibration monitoring landscape. Refinery operators in Houston and Rotterdam negotiate multi-year algorithm-driven forecasting agreements that bundle hardware, software, and predictive analytics into recurring revenue streams rather than capital expenditure line items.
Pricing Analysis
Volume commoditization concentrates in MEMS accelerometer chips for broad plant deployment, while margin capture clusters in engineered displacement probe assemblies for turbomachinery applications. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified hazardous-zone systems from general industrial sensors and unbranded commodity components. Pricing pressure stems from MEMS cost compression as sub-dollar sensor nodes absorb functions previously requiring macro-scale piezoelectric assemblies. Small and mid-sized machine shops exhibit highest price sensitivity, deferring continuous monitoring in favor of periodic handheld analyzer inspections.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from aerospace engine manufacturers and wind turbine OEMs, while authorized distributors serve fragmented industrial maintenance departments. Piezoelectric ceramic fabrication concentrates in Japan and Germany, with MEMS wafer processing anchored in Taiwan and South Korea. High-sensitivity sensing elements, precision-machined probe housings, and ISO 16063 calibration reference standards constitute critical input dependencies. Single-source vulnerability in specialty material processors creates exposure to geopolitical trade restrictions. Distribution runs through technical instrumentation distributors with field service capabilities for hazardous-zone installation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vibration monitoring sector is becoming a vertical-integration race as vendors pursue captive control over edge analytics software stacks to anchor long-term service agreements and reduce customer churn.
For Market Incumbents: Acquire predictive analytics software platforms to deepen algorithm-driven forecasting capabilities and defend against pure-play AI entrants. Consolidate wireless protocol engineering talent through targeted hiring in LoRaWAN and NB-IoT specializations. Cement bearing-integrated sensor architectures as the default specification for rotating equipment operators, raising switching costs for customers considering standalone sensor vendors. For New Entrants and Emerging Players: Digital-channel routes through industrial IoT marketplaces offer lower customer acquisition costs than field sales organizations for battery-harvested sensor deployments. Target India's state generation companies facing first-time CEA grid code compliance obligations as the most penetrable geography. Pursue white-space in combined thermal-acoustic-vibration sensor packages for EU F-Gas Regulation refrigerant-leak detection mandates. For Investors and Strategic Acquirers: The window for entry favors edge analytics specialists with trained machine learning models on rotating equipment failure modes. Long-term viability hinges on algorithm accuracy in bearing degradation forecasting rather than hardware manufacturing scale. Watch for ISO 16063 calibration expertise scarcity forcing acquisition premiums for metrology-capable targets.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Protocol Integration | LoRaWAN and NB-IoT certification accelerates deployment in explosive atmospheres without conduit infrastructure. |
| Edge Analytics Acquisition | On-device algorithm training reduces latency for critical turbomachinery alerts in petrochemical facilities. |
| Bearing-Integrated Sensor Architecture | SKF and Schaeffler demonstrate reduced installation complexity drives specification preference among maintenance directors. |
| Subsea Ruggedization Investment | Corrosion-resistant probe assemblies capture offshore wind expansion in the North Sea and Baltic regions. |
| Digital Audit Trail Standardization | EU Machinery Directive amendments favor integrated hardware-software platforms with native data sovereignty controls. |
Research Approach
SEC 10-K filings, EU Machinery Directive implementation guidance, and customs trade data on accelerometer imports formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with maintenance directors at Gulf Coast refineries, plant engineers in German automotive clusters, and aftermarket service heads at bearing manufacturers validated demand drivers and procurement criteria. Bottom-up sensor shipment estimates triangulated against top-down predictive maintenance software subscription values.
Bottom-up modeling built sensor unit economics across MEMS and piezoelectric product tiers, while top-down analysis tracked condition monitoring contract values at major energy utilities. Segmentation dimensions included product type, technology architecture, end-use vertical, and application criticality. CAGRs derived from regression analysis of historical installation patterns against regulatory mandate timelines and infrastructure modernization cycles. Forecast inputs incorporated OSHA enforcement intensity scoring and CEA grid code compliance deadlines.
The model holds under stable regulatory enforcement and continued wireless protocol standardization; deviation in trade policy affecting ceramic sensor element sourcing or abrupt shifts in utility capital expenditure cycles would shift trajectory. Forecasts reflect documented assumptions on MEMS cost decline curves and predictive algorithm adoption rates. Periodic stress-testing of base assumptions against actual utility procurement data and ATEX certification queue lengths is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Portable Iris Recognition Scanner Market
Sensors
Temperature Data Loggers Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Industrial Barcode Scanners Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
IO Link Market
Sensors
Lidar Market
Sensors
Fixed RFID Readers Market
Sensors
Lidar in Construction Market
Sensors
Beacon Technology Market
Sensors
Global Positioning Systems Market
Sensors
Smart Mat Market
Sensors
Europe Lidar Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Asia Pacific Container Monitoring Market