
 Russia Data Center Construction Market | 2026-2036
Russia Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Data Center Construction Market Insights
ISO 27001 certification is collapsing as a baseline qualification for contractors bidding on hyperscale projects in Russia. Green MDC leverages its modular prefabrication expertise to compress deployment timelines for cloud operators. LANIT-projects anchors its position through deep relationships with state-owned enterprises requiring sovereign data infrastructure. Arup competes on engineering complexity, particularly in seismic and thermal design for facilities spanning Siberia's extreme climate zones.
Russia data center construction encompasses the civil, mechanical, and electrical engineering of facilities housing IT equipment with power densities exceeding 15 kW per rack and PUE targets below 1.4. These structures integrate redundant substations, liquid cooling loops, and multi-layer physical security to ensure continuous operation for financial clearing, cloud services, and AI training workloads. Capacity segmentation shows hyperscale projects commanding the largest capital allocations, while edge computing deployments within the technology dimension represent the fastest expansion vector as latency-sensitive applications proliferate. Brownfield construction type segments gain traction in St. Petersburg and Yekaterinburg, where Soviet-era industrial buildings undergo conversion to reduce greenfield land acquisition costs.
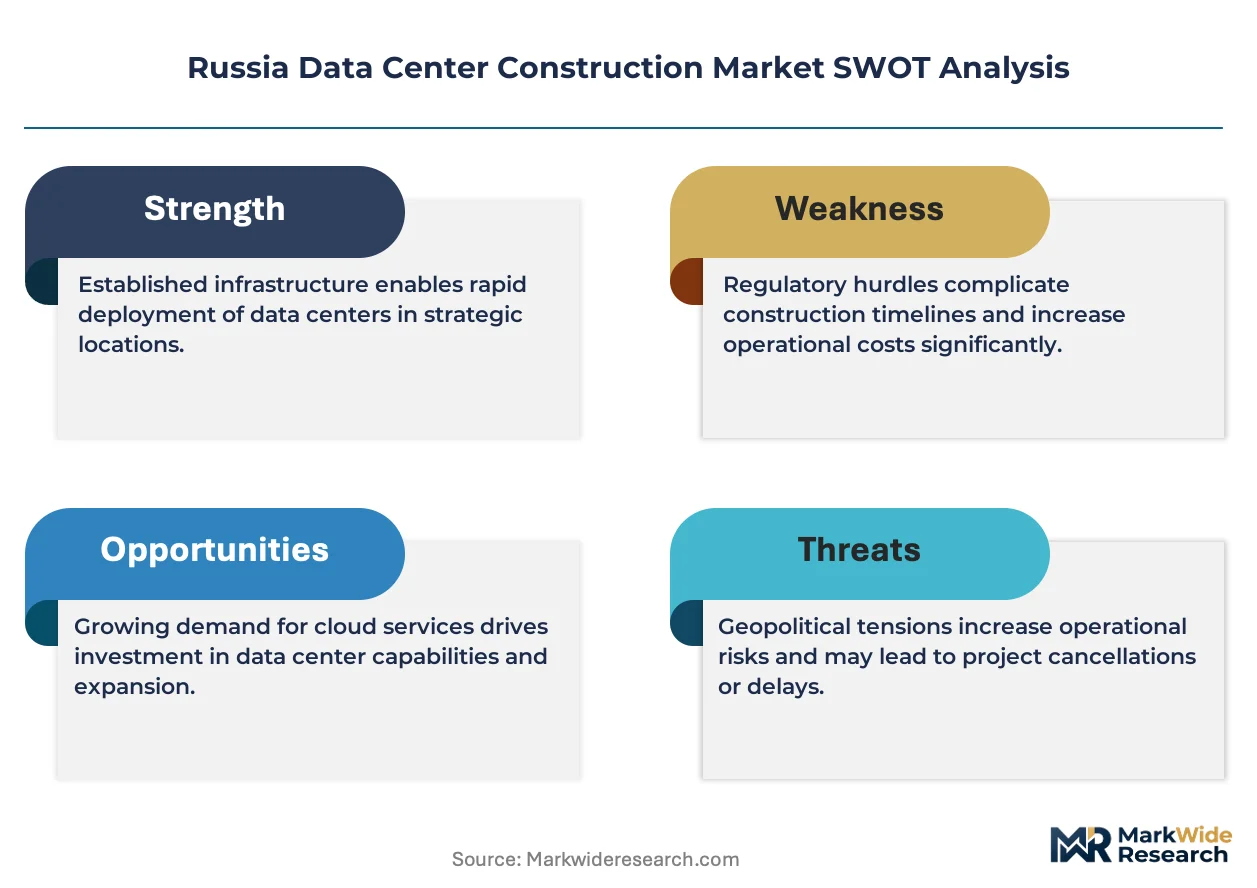
Russia's Federal Service for Technical and Export Control (FSTEC) certifies data processing facilities under security clearance tiers that dictate foreign equipment restrictions and architectural requirements. The national regulator Roskomnadzor enforces data localization compliance through audit mechanisms that directly trigger new construction cycles when violations are identified. Stakeholders must monitor how sanctions regimes affect turbine generator and switchgear supply chains, as import substitution timelines will determine whether domestic manufacturing scales sufficiently to support announced facility pipelines.
Market Dynamics
Federal Law No. 242-FZ mandates domestic storage of Russian citizen data, forcing foreign cloud operators to commission locally built facilities rather than serving the market from abroad. This regulatory pressure compresses procurement timelines and redirects capital flows toward construction firms with FSTEC security clearance credentials.
Growth Catalysts
- Data localization mandates:Roskomnadzor enforces audit mechanisms that trigger new construction cycles when violations surface, creating recurring demand for compliant facilities.
- Hyperscale cloud expansion:International operators require sovereign infrastructure to serve enterprise clients in financial services and e-commerce verticals.
- Liquid cooling adoption:Power densities exceeding 15 kW per rack demand advanced thermal management systems that only specialized contractors can install.
Market Restraints
- Import substitution timelines:Sanctions restrict turbine generator and switchgear supply chains, forcing reliance on domestic manufacturing that has not yet scaled to announced pipeline volumes.
- Seismic engineering complexity:Siberian facilities require specialized structural designs that extend project durations and limit contractor pools.
- Copper and aluminum volatility:Electrical busbar and cabling costs fluctuate with commodity markets, eroding fixed-price contract margins.
Strategic Opportunities
- Edge computing proliferation:Latency-sensitive AI inference and industrial IoT applications drive modular micro-data center deployments in St. Petersburg and Yekaterinburg.
- Brownfield conversion:Soviet-era industrial buildings offer reduced land acquisition costs versus greenfield development in land-constrained Moscow.
- FSTEC certification services:Security clearance tiers create adjacent revenue streams for engineering firms that can navigate foreign equipment restriction protocols.
Industry Challenges
- Seismic and thermal engineering talent scarcity:Few Russian firms possess combined expertise in extreme climate design and high-density cooling integration.
- Multi-layer physical security integration:Biometric access, perimeter hardening, and blast-resistant construction add coordination complexity to already compressed schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Data Center Construction Market |
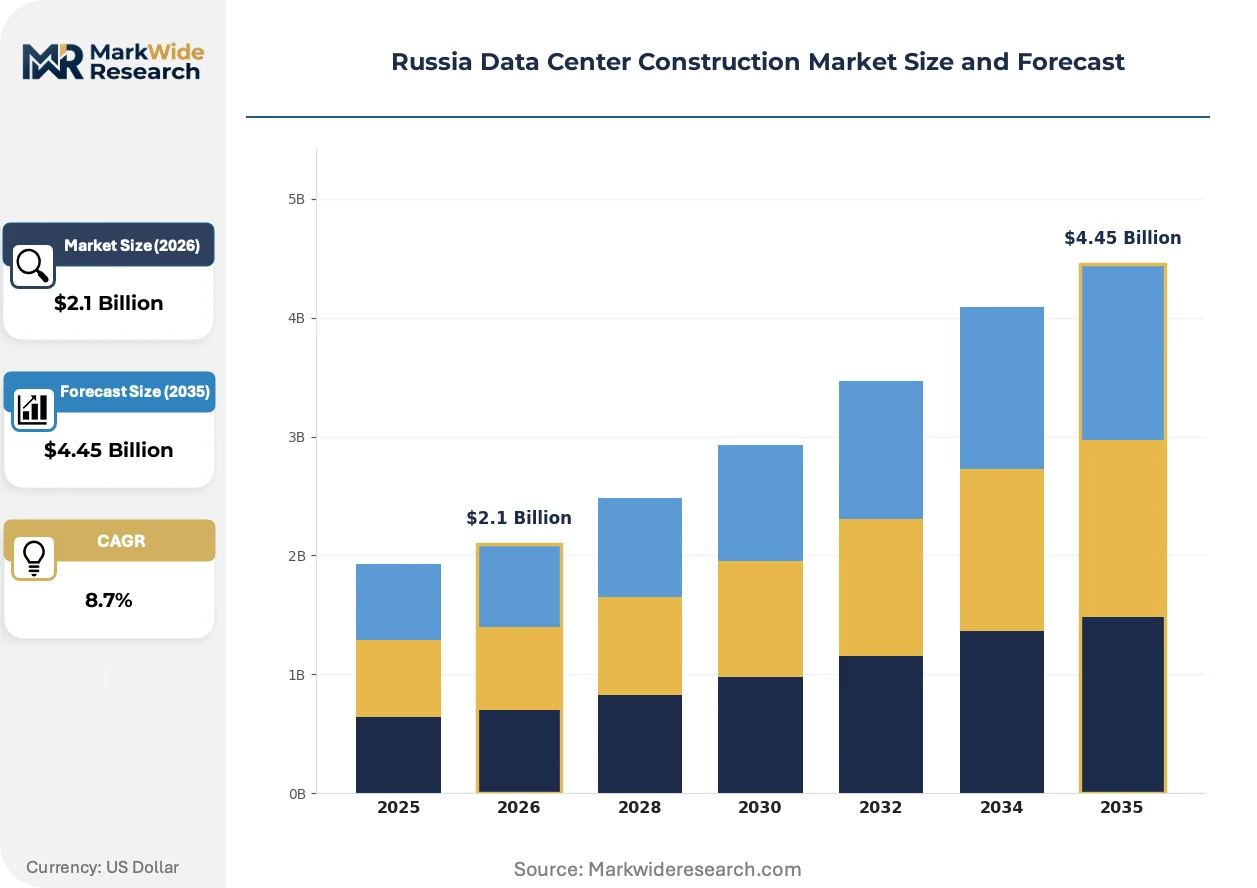
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Greenfield, Brownfield, Modular, Retrofitting Technology: Cloud Computing, Edge Computing, AI Integration, Cooling Solutions Capacity: Small Scale, Medium Scale, Large Scale, Hyper Scale End User: Financial Services, Healthcare Providers, E-Commerce, Telecommunications |
| Companies Covered | Arup, Astron Buildings, Green MDC, HAKA Moscow, Monarch Group, LANIT-projects, Granlund Group, Nefteresurs, Sintec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Data Center Construction Market Trends and Innovations
Liquid cooling architectures and modular prefabrication are compressing deployment timelines while regulatory pressure on energy efficiency intensifies design specifications. These forces reshape contractor selection criteria and capital allocation patterns across the build cycle.
Immersion cooling systems are bifurcating the thermal management market. Hyperscale operators in Moscow deploy single-phase dielectric fluids for AI training clusters, while colocation providers adopt two-phase systems for mixed-density racks. This technology split is compressing vendor consolidation timelines as suppliers must choose specialization paths.
FSTEC certification requirements now mandate specific architectural features for facilities processing sensitive data. Foreign equipment restrictions force redesigns of electrical distribution and fire suppression systems. Tier-3 and Tier-4 projects face the steepest compliance burden, with some operators delaying groundbreaking until clearance pathways clarify.
Build-operate-transfer contracts are displacing traditional design-bid-build arrangements for hyperscale campuses. Cloud operators transfer construction risk to contractors with sovereign infrastructure experience. This shift concentrates most visibly in the Moscow region, where power infrastructure density supports multi-hundred-megawatt commitments.
Russia Data Center Construction Market Segmentation
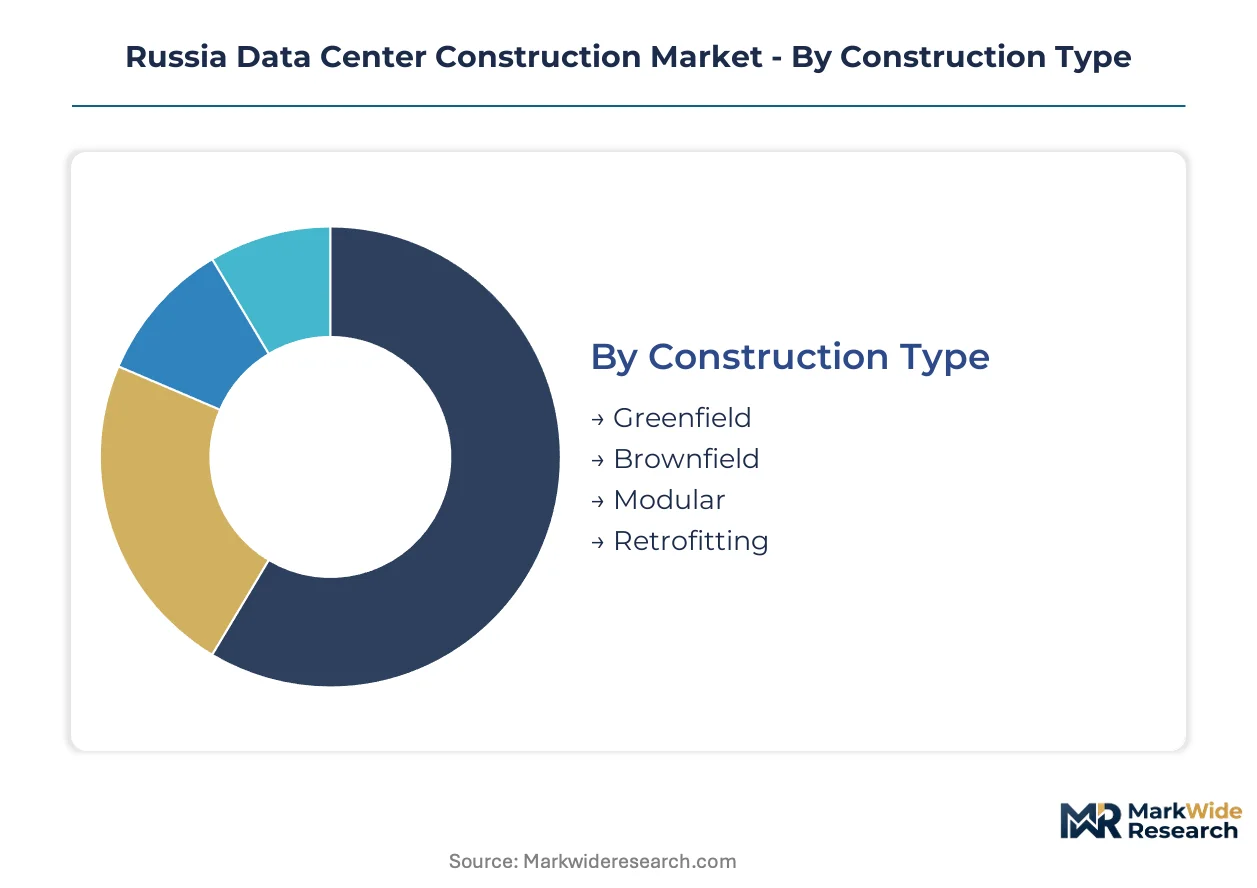
Segmentation reveals how Federal Law No. 242-FZ and FSTEC certification requirements reshape capital allocation across build types and capacity tiers. Contractors with security clearance credentials capture disproportionate share in regulated segments. Moscow's power density advantages concentrate hyperscale investment while regional cities drive brownfield conversion demand.
Construction Type:
Greenfield builds dominate Moscow-region deployments where land availability and transmission infrastructure align. Brownfield conversions accelerate in secondary cities seeking to bypass land acquisition bottlenecks.
- Greenfield:Purpose-built facilities on undeveloped land achieve PUE targets below 1.4 through integrated thermal design from foundation phase. Demand concentrates in the Moscow region where Rosatom and Rosseti transmission corridors support multi-hundred-megawatt commitments. FSTEC Tier-3 and Tier-4 mandates favor greenfield for clean-sheet security architecture.
- Brownfield:Soviet-era industrial buildings undergo structural reinforcement and electrical retrofit to host IT loads exceeding 15 kW per rack. St. Petersburg and Yekaterinburg conversions reduce land costs by 40-60% versus greenfield alternatives. Seismic assessment requirements extend permitting timelines.
- Modular:Prefabricated data hall units compress deployment to 6-9 months for cloud operators facing localization deadlines. Factory-built components bypass on-site construction bottlenecks.
- Retrofitting:Legacy facility upgrades address power density constraints and cooling inefficiencies in Tier-1 and Tier-2 buildings. Operators prioritize locations with existing fiber connectivity.
Greenfield holds the largest share; momentum sits with brownfield as land constraints intensify in primary markets.
Technology:
Cloud infrastructure commands capital allocation supremacy while edge deployments climb fastest on latency requirements.
- Cloud Computing:Hyperscale campuses integrate redundant substations and liquid cooling loops to serve financial clearing and enterprise SaaS workloads. Moscow and Tatarstan host the dominant facility footprints.
- Edge Computing:Micro-data centers positioned within 10 milliseconds of population centers support industrial IoT and autonomous systems. Kazan and Novosibirsk emerge as edge node priorities for manufacturing corridor coverage.
- AI Integration:Training clusters demand 30-50 kW per rack densities requiring single-phase dielectric immersion cooling. GPU-intensive configurations drive specialized electrical distribution designs.
- Cooling Solutions:Two-phase systems gain traction in colocation facilities serving mixed-density client racks. Vendor specialization between single-phase and two-phase architectures accelerates.
Cloud computing anchors investment volume; steepest expansion trajectory belongs to edge computing as latency thresholds tighten.
Capacity:
Scale tier determines contractor pool depth and procurement complexity, with hyperscale projects concentrating among cleared builders.
- Small Scale:Sub-1 MW deployments serve regional healthcare providers and municipal data localization requirements. Standardized designs reduce engineering overhead.
- Medium Scale:1-10 MW facilities dominate telecommunications and mid-market financial services demand. Colocation operators favor this tier for risk distribution.
- Large Scale:10-50 MW builds require multi-layer physical security and biometric access integration. E-commerce platforms commission these for peak-load resilience.
- Hyper Scale:Facilities exceeding 50 MW integrate blast-resistant construction and sovereign cloud architecture for state-affiliated operators. Only three Russian contractors maintain recurring hyperscale credentials.
Large scale captures current procurement volume; hyperscale is gaining share fastest as sovereign cloud mandates deepen.
End User:
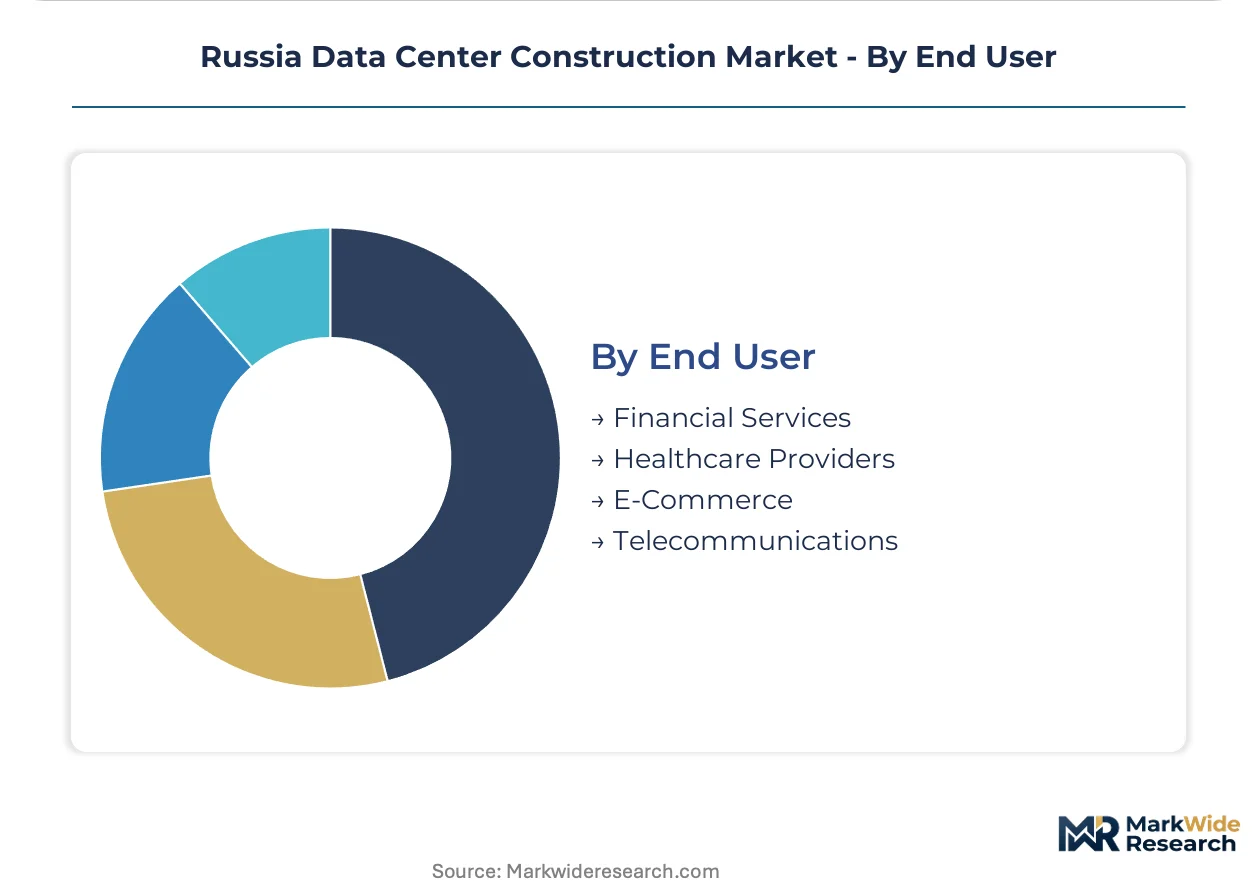
Vertical-specific compliance requirements fragment contractor selection, with financial services imposing the steepest security architecture burdens.
- Financial Services:Central Bank of Russia regulations mandate Tier-3 minimum uptime with seismic isolation for trading infrastructure. Sberbank and VTB commission dedicated facilities exceeding 100 MW in Moscow.
- Healthcare Providers:Mandatory Health Insurance Fund integration requires FSTEC-certified processing for citizen medical records. Regional hospital networks drive small-scale distributed builds.
- E-Commerce:Ozon and Wildberries commission capacity for transaction spike absorption during promotional periods. Peak-load engineering dominates specifications.
- Telecommunications:Rostelecom and MTS expand edge presence to support 5G core network functions. Latency-sensitive radio access network hosting shapes site selection.
Financial services dominates capital deployment; healthcare providers are expanding most quickly as electronic medical record mandates broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators and state-affiliated enterprises concentrate procurement among contractors with FSTEC security clearance, driving geographic concentration in power-dense corridors.
Moscow Region
Sberbank and VTB commission dedicated facilities exceeding 100 MW near Rosatom transmission corridors. Federal Law No. 242-FZ mandates domestic data storage for citizen records, accelerating sovereign cloud buildouts. The Skolkovo Innovation Center hosts multiple Tier-3 campuses serving financial clearing workloads.
Tatarstan
Kazan emerges as an edge computing priority for manufacturing corridor coverage within 10 milliseconds of population centers. The regional government offers infrastructure incentives for data processing facilities meeting FSTEC Tier-2 minimums. Innopolis technology park anchors modular micro-data center deployments for industrial IoT applications.
St. Petersburg
Soviet-era industrial buildings undergo brownfield conversion to reduce land acquisition costs by 40-60% versus greenfield alternatives. Seismic assessment requirements extend permitting timelines for retrofitted facilities. The city hosts colocation operators serving mixed-density client racks with two-phase cooling systems.
Yekaterinburg
Regional hospital networks drive small-scale distributed builds for Mandatory Health Insurance Fund integration. FSTEC-certified processing requirements shape contractor selection for citizen medical record infrastructure. The Ural Federal District serves as a logistics hub for Siberian edge node expansion.
Novosibirsk
AI training clusters demand 30-50 kW per rack densities requiring specialized electrical distribution designs. Akademgorodok research institutes anchor GPU-intensive configurations for scientific computing workloads. Extreme climate zones necessitate seismic and thermal engineering expertise that limits available contractor pools.
Russia Data Center Construction Market Competitive Landscape
Player mix skews toward engineering-led specialists with sovereign infrastructure credentials and modular prefabrication capabilities. The contractor pool concentrates among firms maintaining recurring hyperscale relationships with state-affiliated operators. Two strategic archetypes dominate: security-cleared builders with FSTEC Tier-3/Tier-4 experience, and modular fabricators compressing deployment timelines through factory-built components. Competitive moves center on build-operate-transfer contract capture and brownfield conversion expertise acquisition.
Within the engineering-specialist tier, Arup occupies a position exemplifying complex seismic and thermal design capabilities for extreme climate zones. Green MDC represents the modular prefabrication archetype, anchoring compressed deployment timelines for cloud operators facing localization deadlines. LANIT-projects sits within the state-enterprise relationship tier, exemplifying deep ties with sovereign data infrastructure requirements. These three firms collectively represent the credential concentration shaping hyperscale procurement decisions.
| Leading Market Players |
|---|
| Arup |
| Astron Buildings |
| Green MDC |
| HAKA Moscow |
| Monarch Group |
| LANIT-projects |
| Granlund Group |
| Nefteresurs |
| Sintec |
| Others |
Pricing and Supply Chain Analysis
Ninety-day turbine generator lead times concentrate procurement power among contractors with pre-positioned inventory, compressing margins for competitors while amplifying pricing leverage for cleared builders holding FSTEC Tier-3 credentials. This inventory asymmetry shapes how brownfield conversion premiums trade against greenfield base costs across Moscow and regional markets.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate hyperscale procurement, insulating contractors from busbar volatility while exposing clients to aluminum cabling escalators. Price differentiation rests on FSTEC clearance tier and seismic engineering capability, with Tier-4 certified builders commanding substantial premiums over uncertified rivals. Pricing pressure intensifies in brownfield segments as St. Petersburg conversion capacity expands. State-affiliated operators exhibit lowest price sensitivity; regional hospital networks face acute budget constraints.
Supply Chain Analysis
Inventory concentration for switchgear and diesel generators runs through China, Germany, and domestic Russian manufacturing facilities with uneven substitution readiness. Critical inputs include copper electrical busbar, aluminum cabling, and precision cooling fluids subject to foreign equipment restrictions. Single-source vulnerability in turbine generator supply creates procurement bottlenecks when sanctions disrupt German component flows. Distribution channels center on direct contractor-operator relationships with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against modular prefabrication specialists eroding traditional engineering margins through compressed deployment timelines. Incumbents must navigate cloud operator willingness to transfer construction risk to factory-built component providers.
For Market Incumbents: Consolidate hyperscale relationships through build-operate-transfer contract capture before modular competitors establish recurring credentials. Deepen in-house production of liquid cooling loops to reduce dependency on sanctioned foreign suppliers. Anchor position in FSTEC Tier-4 clearance pipeline as regulatory requirements stiffen for sovereign cloud architecture.
For New Entrants and Emerging Players: FSTEC Tier-2 fast-track certification opens brownfield conversion opportunities in Yekaterinburg and Novosibirsk where cleared contractor scarcity extends project timelines. Target regional healthcare provider segments with standardized small-scale designs for Mandatory Health Insurance Fund integration. Pursue equipment-light modular partnerships to bypass capital-intensive electrical distribution manufacturing.
For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned engineering conglomerates divesting non-core data center construction units as sovereign cloud mandates concentrate procurement among specialized players. Long-term viability hinges on import substitution execution in switchgear manufacturing. Monitor Rosatom transmission corridor expansion announcements as inflection signal for hyperscale pipeline acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FSTEC Tier-3 Certification Investment | Security clearance credentials unlock hyperscale procurement with Sberbank and VTB. |
| Brownfield Conversion Capability Acquisition | Soviet-era industrial retrofit expertise reduces land costs in St. Petersburg by forty to sixty percent. |
| Liquid Cooling Loop Manufacturing Scale-Up | Domestic production of dielectric fluids addresses foreign equipment restriction compliance. |
| Build-Operate-Transfer Contract Structuring | Risk transfer mechanisms align with cloud operator preference for sovereign infrastructure partners. |
| Seismic Engineering Talent Recruitment | Siberian facility demand exceeds available contractor pools with extreme climate design expertise. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, combining insights from data center construction project directors, FSTEC certification officers, Roskomnadzor compliance auditors, and cloud operator procurement leads with secondary validation through customs records, Federal Antimonopoly Service filings, and state procurement databases. Bottom-up project pipeline aggregation triangulated against top-down capital expenditure tracking from announced facility commitments.
Across the analysis window, the forecasting framework modeled capacity deployment by construction type, technology tier, and end-user vertical with regional granularity spanning Moscow, Tatarstan, St. Petersburg, Yekaterinburg, and Novosibirsk. CAGRs were derived from facility announcement pipelines adjusted for import substitution timeline probability. Key inputs included Rosatom transmission corridor expansion schedules and FSTEC clearance processing velocity assumptions.
Decision-makers should treat outputs as directional under sustained sanctions regime assumptions; material deviation in turbine generator domestic manufacturing scale would warrant model refresh. Specific risk factors include copper commodity volatility, seismic engineering talent scarcity, and regulatory clearance pathway delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Low-Cost Energy Data Center Market