
 Wireless RFID Readers Market | 2026-2036
Wireless RFID Readers Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless RFID Readers Market Outlook
Aftermarket service revenue is rewriting profit dynamics across the wireless RFID reader landscape. Impinj, Inc. leverages its RAIN RFID chipset ecosystem to anchor recurring firmware and cloud analytics income. Zebra Technologies Corp. dominates enterprise mobility services through its integrated device management platform. Honeywell International Inc. competes on global repair networks and extended warranty programs that sustain long-term account control.
Wireless RFID readers are radio frequency identification devices that operate without physical cable connections to host systems, typically using Wi-Fi, Bluetooth, or cellular backhaul to transmit EPC Class 1 Gen 2 protocol data at frequencies spanning 860–960 MHz UHF bands; their core purpose is to capture tag identifiers automatically for asset tracking and inventory visibility in distributed environments. Fixed readers command the majority of installed base in automated warehouse gates and retail backrooms where throughput volume justifies capital expenditure. Handheld readers represent the fastest-expanding product category as field service and cycle-counting workflows prioritize worker mobility over stationary infrastructure. Passive RFID technology underpins the largest volume deployment segment due to its minimal tag cost, though active RFID is capturing margin pools in cold-chain and high-value asset monitoring where battery-powered beaconing delivers meter-level location precision.
The Federal Communications Commission governs UHF spectrum allocation for RFID operations in the United States, while the European Telecommunications Standards Institute harmonizes frequency bands across EU member states to prevent cross-border interference. GS1 EPCglobal standards and ISO/IEC 18000-6C certifications shape reader interoperability mandates that determine market access for hardware vendors. Stakeholders must weigh spectrum reallocation risks against software-defined radio architectures that promise multi-protocol flexibility without hardware replacement cycles.
Market Dynamics
The GS1 EPC Gen2 protocol standardization is compressing hardware differentiation and forcing reader vendors toward software-defined architectures that support multi-frequency operation without physical replacement.
Growth Catalysts
- Warehouse automation mandates:United States distribution centers are deploying fixed readers at dock doors and conveyor junctions to eliminate manual scan labor and accelerate throughput velocity.
- REACH compliance pressure:European electronics manufacturers are replacing legacy barcode infrastructure with RAIN RFID to satisfy traceability requirements under circular economy directives.
- Bluetooth 5.3 integration:Handheld reader manufacturers are embedding low-energy mesh capabilities to enable peer-to-peer relay in environments lacking Wi-Fi coverage.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries control 90% of advanced RF front-end fabrication, exposing reader OEMs to geopolitical disruption and allocation rationing.
- UHF spectrum fragmentation:Japan's 952–954 MHz allocation differs from China's 920–925 MHz band, forcing hardware variants that inflate inventory carrying costs.
- Passive tag read-range physics:Liquid and metal environments degrade UHF signal propagation, limiting deployment in food processing and automotive stamping operations without costly tag isolation.
Strategic Opportunities
- India PLI scheme leverage:Domestic electronics manufacturing incentives are attracting reader assembly investments to serve Southeast Asian logistics corridors.
- Healthcare cold-chain convergence:Temperature-logging active tags combined with 5G cellular readers are opening pharmaceutical distribution monitoring contracts.
- Subscription firmware models:Cloud-based reader management platforms are capturing recurring revenue from retail chains seeking over-the-air security patching.
Industry Challenges
- RF engineering talent scarcity:Antenna design and impedance matching expertise concentrates in legacy telecommunications hubs, forcing reader vendors to compete for finite specialist pools.
- ISO/IEC 18000-63 certification timelines:Multi-protocol interoperability testing extends product launch cycles by 8–14 months, compressing competitive windows.
- Legacy WMS integration friction:Enterprise resource planning systems built on barcode data structures require middleware development that delays RFID pilot-to-production transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless RFID Readers Market |
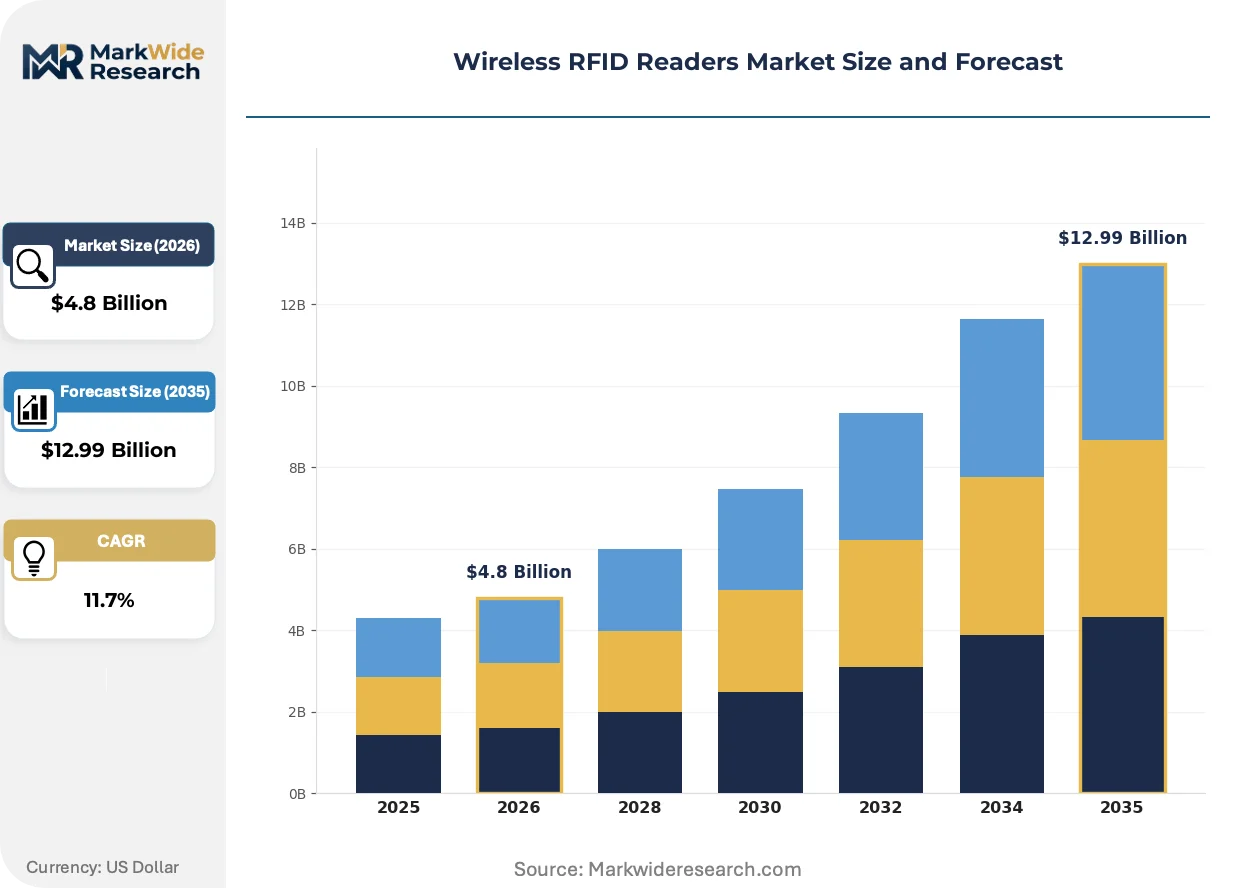
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Readers, Fixed Readers, Embedded Readers, Mobile Readers Technology: Active RFID, Passive RFID, Semi-passive RFID, Near Field Communication End User: Retail, Manufacturing, Logistics, Healthcare Installation: Indoor Installation, Outdoor Installation, Wall-mounted, Tabletop |
| Companies Covered | Impinj, Inc., Honeywell International Inc., Zebra Technologies Corp., Alien Technology, Datalogic S.p.A., Nedap N.V., JADAK, MOJIX, Invengo Technology Pte. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless RFID Readers Market Strategic Shifts
Software-defined radio architectures are dissolving the hardware-software boundary in reader design, enabling firmware-upgradable frequency agility that responds to shifting regulatory allocations without board-level redesign.
Multi-protocol SDR chipsets from Impinj and NXP are rendering obsolete single-frequency fixed readers that dominated warehouse gate deployments through 2020. Third-party logistics operators in the Netherlands and Germany are piloting these platforms to consolidate 865–868 MHz EU and 902–928 MHz US operations onto identical hardware SKUs. The compression of regional hardware variants is collapsing distributor inventory requirements and accelerating cross-border deployment standardization.
The FCC's 2023 UHF spectrum reallocation proceeding is forcing reader manufacturers to embed dynamic frequency selection algorithms that avoid incumbent satellite earth stations. Industrial users in the Gulf Coast petrochemical corridor face immediate retuning obligations that favor software-defined over fixed-tuner hardware purchases. Equipment lessors are responding with trade-in programs that absorb stranded asset risk from pre-2023 reader installations.
Consolidated procurement by Amazon, Walmart, and Target is compressing vendor margins and unbundling installation services from hardware contracts. Reader OEMs are responding with certified integrator networks that shift deployment labor to regional specialists while retaining cloud analytics subscriptions. The unbundling is most advanced in North American retail, where three buyers control 60% of annual reader volume and dictate commercial terms through reverse auctions.
Wireless RFID Readers Market Segmentation
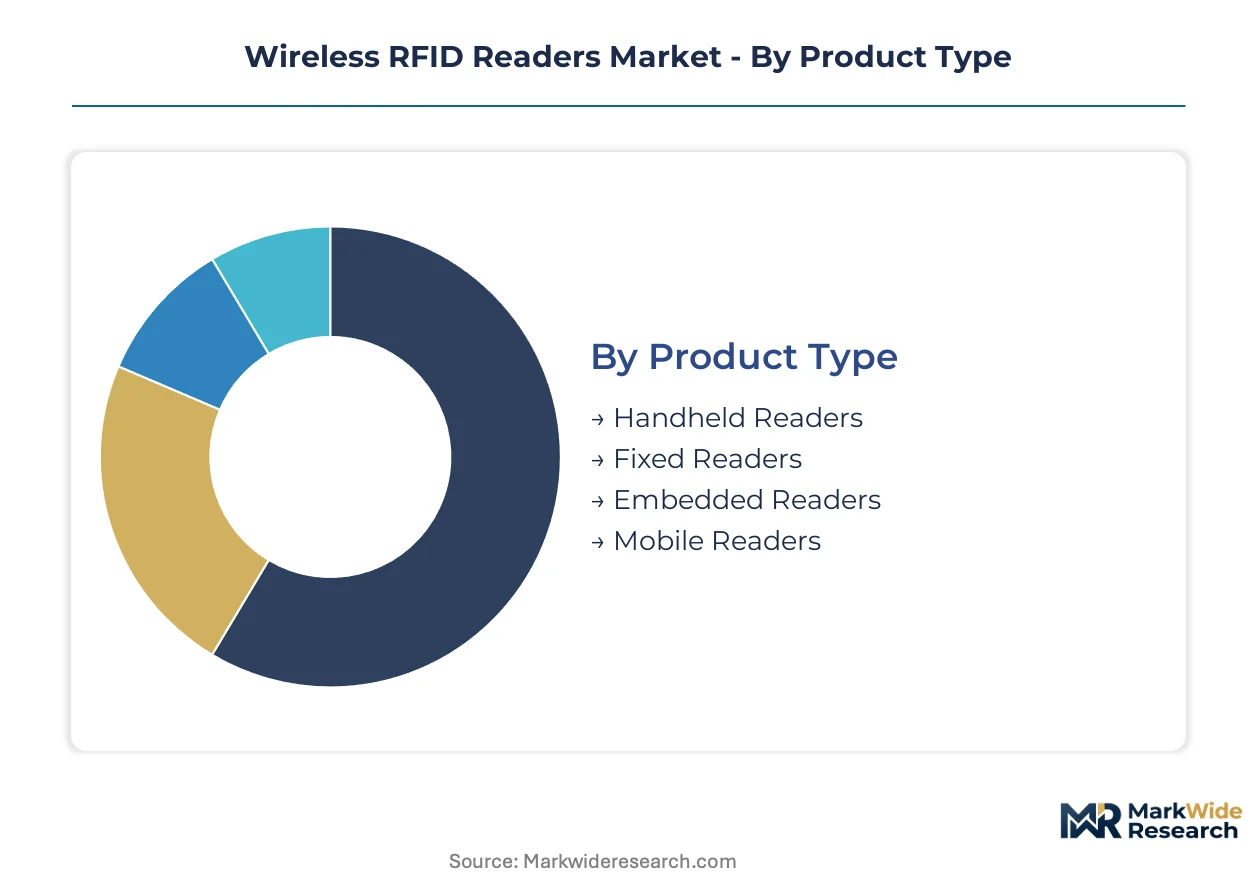
Wireless RFID reader segmentation reveals distinct procurement patterns across mobility requirements, power architectures, and environmental exposure. Hardware vendors configure antenna arrays, ingress protection ratings, and backhaul protocols differently for each segment cluster.
Product Type:
Use-case spectrum spans stationary infrastructure at facility chokepoints to worker-worn devices for field inventory reconciliation.
- Fixed Readers:Stationary UHF interrogators mount at dock doors, conveyor junctions, and portal gates for automated tag capture without human intervention. Amazon fulfillment centers in the United States deploy these at receiving and shipping lanes to eliminate manual scan labor. Established volume favors Fixed Readers; emerging adoption favors Handheld Readers.
- Handheld Readers:Battery-powered pistol-grip or sled-form devices combine barcode imagers with UHF RFID modules for cycle-counting and exception handling. Walmart store associates use these for backroom inventory audits where Wi-Fi coverage supports real-time ERP synchronization. Bluetooth 5.3 mesh capabilities enable peer-to-peer relay in cellular dead zones.
- Embedded Readers:Compact OEM modules integrate into kiosks, smart cabinets, and automated dispensing equipment for closed-loop asset tracking. Medical device manufacturers embed these in surgical instrument sterilization systems.
- Mobile Readers:Vehicle-mounted or cart-based units serve yard management and warehouse aisle traversal where forklift operators require hands-free tag interrogation. Third-party logistics operators deploy these for trailer yard checks.
Procurement patterns diverge by labor substitution calculus: fixed infrastructure amortizes against throughput volume while handheld devices track wage inflation.
Technology:
Power architecture determines tag cost, read range, and environmental resilience across deployment scenarios.
- Passive RFID:Backscatter-powered tags operating without onboard batteries dominate unit economics at scale. RAIN RFID deployments in United States retail apparel tagging leverage this technology for item-level visibility. Established volume favors Passive RFID; emerging adoption favors Active RFID.
- Active RFID:Battery-powered beacons broadcast at programmable intervals for meter-level location precision in cold-chain and high-value asset monitoring. Pharmaceutical distributors track temperature-sensitive biologics with these tags combined with cellular reader backhaul.
- Semi-passive RFID:Battery-assisted backscatter tags extend read range for metal and liquid-adjacent applications where pure passive propagation fails. Automotive parts suppliers use these for engine component tracking.
- Near Field Communication:Short-range 13.56 MHz protocols enable tap-to-pair consumer interactions and access control credentialing. Hospitality and corporate campus deployments favor this form factor.
Tag cost curves and read-range physics segment procurement: passive tags undercut at volume while active architectures capture margin in precision tracking.
End User:
Vertical-specific compliance mandates and throughput requirements reshape reader specification priorities.
- Retail:Omnichannel fulfillment pressures drive item-level tagging for inventory accuracy and buy-online-pickup-in-store execution. United States apparel retailers mandate EPC Gen2 compliance from suppliers.
- Manufacturing:Work-in-process tracking and tool crib automation demand ruggedized readers with ISO/IEC 18000-63 interoperability. Automotive stamping operations require liquid-resistant tag configurations.
- Logistics:Cross-dock velocity and yard management prioritize fixed portal coverage and mobile vehicle-mounted units. European third-party logistics operators consolidate multi-frequency operations through software-defined radio platforms.
- Healthcare:FDA UDI compliance and pharmaceutical cold-chain integrity command active RFID with temperature logging. Hospital asset tracking for infusion pumps and wheelchairs drives embedded reader cabinet deployments.
Regulatory tailwinds segment fastest: REACH traceability accelerates European manufacturing conversion while FDA mandates propel healthcare adoption.
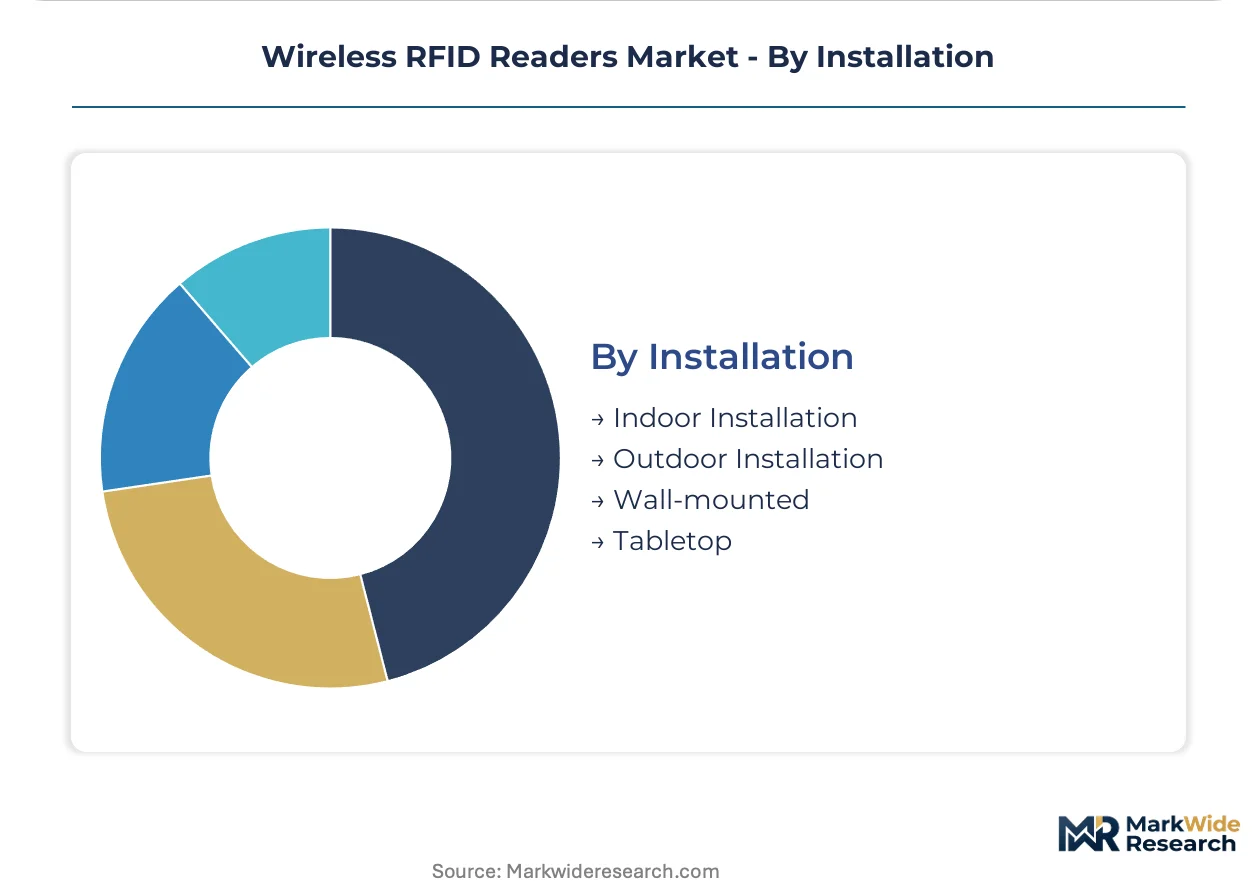
Installation:
Environmental exposure and spatial constraints determine enclosure ratings and mounting hardware specifications.
- Indoor Installation:Climate-controlled warehouse and retail backroom deployments specify IP54-rated enclosures with PoE+ power delivery. Ceiling-mounted overhead readers dominate this configuration.
- Outdoor Installation:IP67-rated units with extended temperature ranges serve trailer yards, construction sites, and agricultural operations. Gulf Coast petrochemical corridors require FCC-compliant dynamic frequency selection.
- Wall-mounted:Compact form factors with integrated antennas suit space-constrained retail floor and cleanroom environments. Point-of-sale integrated readers favor this mounting approach.
- Tabletop:Desktop interrogators support laboratory specimen tracking and small-format asset verification where portability exceeds throughput requirements.
Facility modernization cycles favor Indoor Installation retrofits; greenfield logistics construction favors Outdoor Installation specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize warehouse automation throughput while European procurement emphasizes regulatory compliance traceability. Asian demand clusters around export logistics corridors and domestic retail modernization.
United States
Amazon, Walmart, and Target drive fixed reader deployment at fulfillment center dock doors and conveyor junctions. The FCC governs UHF spectrum allocation with dynamic frequency selection mandates affecting Gulf Coast petrochemical installations. Industrial demand concentrates in the Chicago-Midwest logistics corridor where third-party operators consolidate multi-tenant distribution.
Germany
Automotive stamping operations and pharmaceutical cold-chain logistics anchor reader demand for work-in-process tracking. REACH compliance pressure and EU circular economy directives accelerate RAIN RFID conversion from legacy barcode infrastructure. The Rhine-Ruhr manufacturing belt hosts dense clusters of tier-one automotive suppliers deploying embedded readers for tool crib automation.
China
Domestic e-commerce fulfillment and cross-border export logistics propel handheld and fixed reader adoption. MIIT regulates 920–925 MHz UHF allocation with distinct band plans from neighboring Japan. The Yangtze River Delta manufacturing zone around Shanghai drives embedded reader integration into smart cabinet and kiosk OEM supply chains.
India
Retail inventory modernization and pharmaceutical distribution cold-chain expansion create dual demand vectors. The PLI scheme for domestic electronics manufacturing attracts reader assembly investments targeting Southeast Asian logistics corridors. Maharashtra and Gujarat host emerging production clusters serving regional third-party logistics operators.
Netherlands
Rotterdam-European port logistics and agritech export operations prioritize mobile vehicle-mounted readers for yard management. ETSI harmonizes 865–868 MHz frequency bands across EU member states to prevent cross-border interference. Third-party logistics operators in the Randstad region pilot software-defined radio platforms consolidating multi-frequency EU operations.
Wireless RFID Readers Market Competitive Environment
Capability concentration sits with chipset and firmware specialists; scale advantage sits with integrated device management platforms. The vendor base organizes around three archetypes: RAIN RFID ecosystem architects, enterprise mobility consolidators, and regional hardware fabricators. Dominant competitive moves include certified integrator network expansion to unbundle installation services, and subscription firmware models capturing recurring cloud analytics revenue.
Within the RAIN RFID ecosystem tier, Impinj, Inc. and Nedap N.V. represent the firmware-upgradable platform approach. Zebra Technologies Corp. anchors the enterprise mobility consolidator position. Honeywell International Inc. sits within the global service network archetype. These three companies exemplify divergent paths to account control: chipset ecosystem lock-in, integrated device management platforms, and extended warranty program retention.
| Leading Market Players |
|---|
| Impinj, Inc. |
| Honeywell International Inc. |
| Zebra Technologies Corp. |
| Alien Technology |
| Datalogic S.p.A. |
| Nedap N.V. |
| JADAK |
| MOJIX |
| Invengo Technology Pte. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Taiwan-based foundry concentration for advanced RF front-end fabrication determines both pricing tier spreads and supply chain shape in the wireless RFID reader market. Semiconductor allocation rationing and geopolitical disruption risk compress margins on economy-tier hardware while amplifying premiums for firmware-upgradable software-defined platforms.
Pricing Analysis
Long-term offtake agreements dominate enterprise procurement as Amazon, Walmart, and Target consolidate annual volume through reverse auctions that unbundle installation services from hardware contracts. Pricing stratifies across premium, standard, and economy tiers based on ISO/IEC 18000-63 certification level and after-sales cloud analytics bundling. Cost compression in standard-tier fixed readers is intensifying because consolidated buyer leverage extracts concessions on per-unit pricing. Third-party logistics operators show highest price sensitivity due to thin margin structures, while healthcare cold-chain deployments demonstrate lowest sensitivity given FDA UDI compliance mandates.
Supply Chain Analysis
Export-control regimes restricting RF semiconductor flows to Chinese OEMs fragment component sourcing strategies across Taiwan, South Korea, and Japan. Advanced RF front-end fabrication draws from Taiwan-based foundries, while antenna substrate materials and power management ICs rest on Japanese and South Korean suppliers. Single-source vulnerability in Taiwan-based foundry capacity exposes reader OEMs to allocation rationing during demand surges. Distribution runs through certified integrator networks that shift deployment labor to regional specialists while retaining cloud analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless RFID reader market sits in early-cycle expansion as warehouse automation mandates accelerate fixed reader deployment at dock doors and conveyor junctions. EPC Gen2 protocol standardization by GS1 compresses hardware differentiation and opens white-space for software-defined architectures.
For Market Incumbents: Insulate chipset ecosystem lock-in through firmware-upgradable RAIN RFID platforms that anchor recurring cloud analytics revenue. Defend against emerging SDR entrants by deepening backward integration into antenna design capabilities and embedding dynamic frequency selection algorithms that respond to FCC spectrum reallocations without hardware replacement.
For New Entrants and Emerging Players: Build out certified integrator networks in India's PLI-subsidized manufacturing corridors to capture Southeast Asian logistics demand. Target pharmaceutical cold-chain convergence where temperature-logging active tags combined with 5G cellular readers command premium pricing. Lead with subscription firmware models that capture recurring revenue from retail chains seeking over-the-air security patching.
For Investors and Strategic Acquirers: The market sits at a protocol-consolidation phase that favors RAIN RFID ecosystem architects with captive chipset supply. Long-term viability hinges on software-defined radio architectures that dissolve hardware-software boundaries across the 5-10 year technology refresh cycle. Acquire targets with ISO/IEC 18000-63 certification pipelines and embedded reader module OEM relationships. Watch for inflection when FCC completes UHF spectrum reallocation proceedings affecting Gulf Coast petrochemical installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Upgradable SDR Platform Launch | Enables multi-frequency EU-US operations on identical hardware SKUs for third-party logistics consolidation. |
| Certified Integrator Network Expansion | Shifts deployment labor to regional specialists while retaining cloud analytics subscriptions from retail chains. |
| Backward Integration into Antenna Design | Captures RF engineering expertise concentrated in legacy telecommunications hubs to reduce specialist competition. |
| Healthcare Cold-Chain Partnership | Opens pharmaceutical distribution monitoring contracts through FDA UDI-compliant active RFID with temperature logging. |
| India PLI Manufacturing Investment | Positions assembly capacity to serve Southeast Asian logistics corridors under domestic electronics incentives. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with warehouse automation directors, retail inventory managers, RFID systems integrators, and semiconductor procurement leads at reader OEMs. Secondary validation drew from FCC spectrum allocation proceedings, GS1 EPCglobal standards documentation, ETSI frequency harmonization directives, and SEC filings from publicly traded hardware vendors. Bottom-up shipment estimates triangulated against top-down enterprise IT spending patterns across the analysis window.
Calibration anchored volume projections to installed base replacement cycles and greenfield warehouse automation capex disclosures. Segmentation dimensions modeled include product mobility class, power architecture, end-use vertical, and regional regulatory cluster. CAGRs derived from logistic curve penetration assumptions tied to EPC Gen2 compliance mandates and REACH traceability deadlines. Industry-specific inputs incorporated semiconductor foundry capacity utilization and ISO/IEC 18000-63 certification timeline data.
Sensitivities concentrate around Taiwan foundry allocation disruptions, FCC spectrum reallocation outcomes, and GS1 protocol evolution timelines. Forecasts reflect documented assumptions on warehouse automation adoption velocity and passive tag cost curves. Material shifts in semiconductor supply geography or UHF spectrum fragmentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Global Load Monitoring System (LMS) Market
Sensors
Lidar in Construction Market
Sensors
Weigh-In-Motion System Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Yield Monitoring Systems Market
Sensors
Safety Motion Control System Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Smart Barcode Readers Market
Sensors
Underground Service Locator Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Global Equipment Monitoring Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Traffic Sensor Market
Sensors
Eye Tracking Market
Sensors
Underground Utility Mapping Market