
 Indonesia Study of Data Center Water Consumption Market | 2026-2036
Indonesia Study of Data Center Water Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Study of Data Center Water Consumption Market Insights
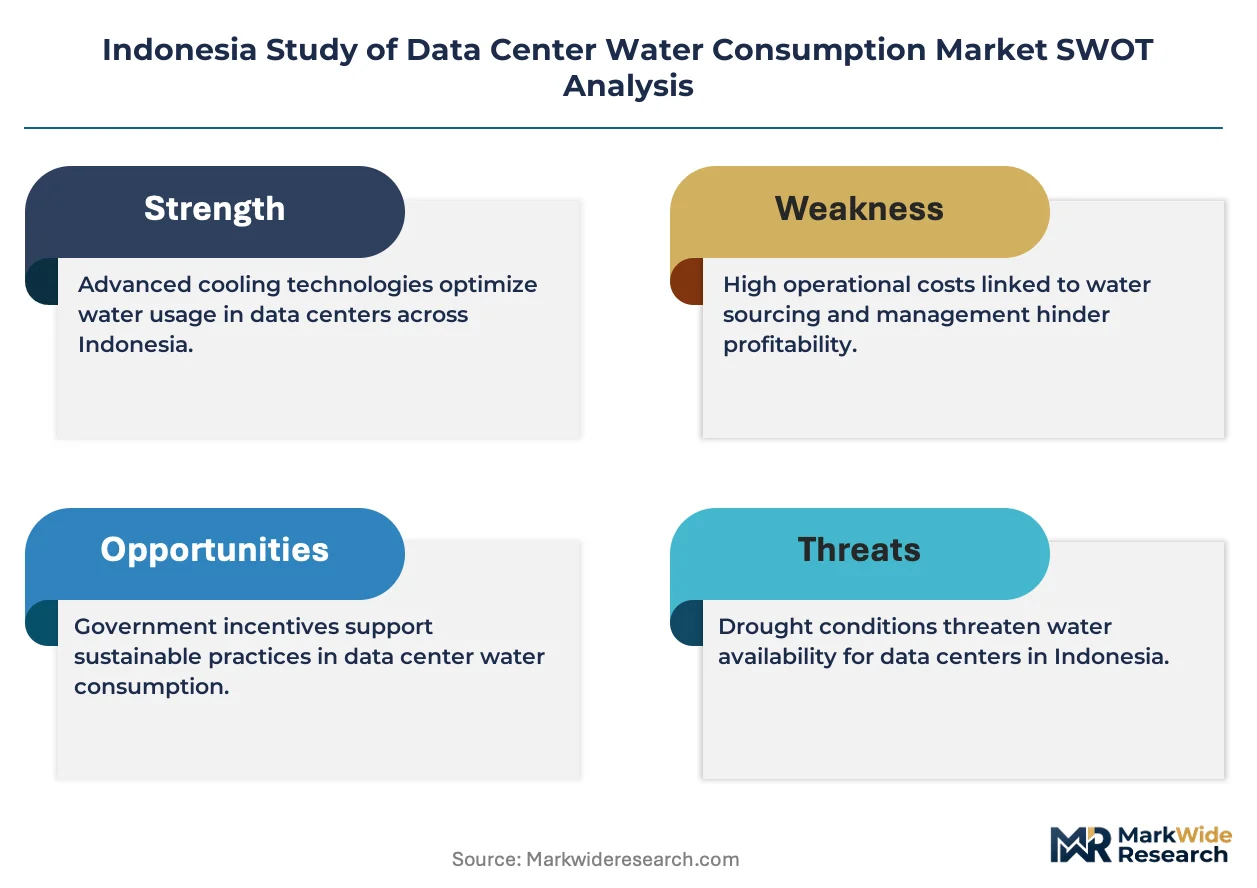
The capital-intensity divergence between hyperscale operators and local colocation providers is rotating competitive dynamics across Indonesia's data center water infrastructure landscape. Equinix leverages its global design playbook to standardize water-efficient cooling architectures across its Jakarta deployments. STT GDC anchors its expansion strategy in captive water treatment investments that reduce municipal dependency in Batam. NeutraDC-Nxera differentiates through direct liquid cooling specialization that cuts freshwater intensity per megawatt against conventional evaporative systems.
Data center water consumption encompasses the full volume of freshwater abstracted, treated, circulated, and discharged to support thermal management and auxiliary operations in mission-critical computing facilities, typically measured in liters per kilowatt-hour or liters per megawatt-day across cooling loops, humidification, and fire suppression systems. The primary industrial purpose centers on dissipating heat generated by server racks, storage arrays, and power conditioning equipment to maintain uptime within ASHRAE thermal envelopes. Chilled water systems dominate installed capacity in Indonesia's tropical climate, though hybrid cooling architectures are capturing expansion projects as operators seek to hedge against municipal supply volatility. Among end users, cloud service providers command the fastest-growing share of water infrastructure investment as AWS, Microsoft, and Google Cloud commit to multi-hundred-megawatt campuses with on-site water recycling mandates.
Indonesia's Ministry of Environment and Forestry sets effluent discharge thresholds that directly shape cooling technology selection and treatment capex for new facilities. BIS-aligned water quality standards for industrial users, coupled with Jakarta Provincial Government groundwater extraction restrictions, are forcing operators toward closed-loop designs and rainwater harvesting integration. Stakeholders must monitor regulatory alignment between national industrial water policies and emerging green building certifications as permitting timelines become a critical path variable for capacity expansion decisions.
Market Dynamics
Indonesia's data center water infrastructure is pivoting around tightening effluent discharge mandates from the Ministry of Environment and Forestry, which are compressing cooling technology selection timelines and elevating captive water treatment from operational preference to permitting prerequisite.
Growth Catalysts
- Cloud Campus Expansion:AWS, Microsoft, and Google Cloud are committing multi-hundred-megawatt facilities with on-site water recycling mandates, pulling advanced cooling infrastructure demand across Greater Jakarta and Batam.
- Groundwater Extraction Restrictions:Jakarta Provincial Government limits on aquifer withdrawal are forcing operators toward closed-loop designs and rainwater harvesting integration, accelerating hybrid cooling adoption.
- BIS-Aligned Industrial Standards:Water quality benchmarks for industrial users are standardizing treatment capex calculations, reducing permitting uncertainty for new facility approvals.
Market Restraints
- Municipal Supply Volatility:Java's concentrated data center load is straining local water utility capacity, creating supply interruption risk during dry season peaks.
- Chilled Water System Lock-In:Legacy infrastructure across existing facilities constrains rapid retrofit to liquid-cooled architectures, extending depreciation cycles.
- Specialized Component Concentration:Precision cooling equipment and membrane filtration systems rely on concentrated import channels through Singapore, exposing operators to logistics friction.
Strategic Opportunities
- Batam Free Trade Zone Positioning:The island's proximity to Singapore submarine cable landing points and lower land costs is attracting hyperscale pre-commitments with integrated water-positive designs.
- Direct Liquid Cooling Convergence:Immersion and cold-plate technologies are converging with high-density GPU deployments, opening freshwater intensity reduction pathways against evaporative alternatives.
- Green Building Certification Tailwinds:Emerging LEED and local green data center standards are creating preferential permitting lanes for operators with documented water reuse metrics.
Industry Challenges
- Thermal Engineering Talent Scarcity:The intersection of mechanical systems design and tropical climate optimization requires specialized expertise that outpaces local vocational pipeline output.
- Legacy Facility Retrofit Complexity:Existing raised-floor environments with perimeter cooling demand phased infrastructure swaps that risk operational continuity during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Study of Data Center Water Consumption Market |
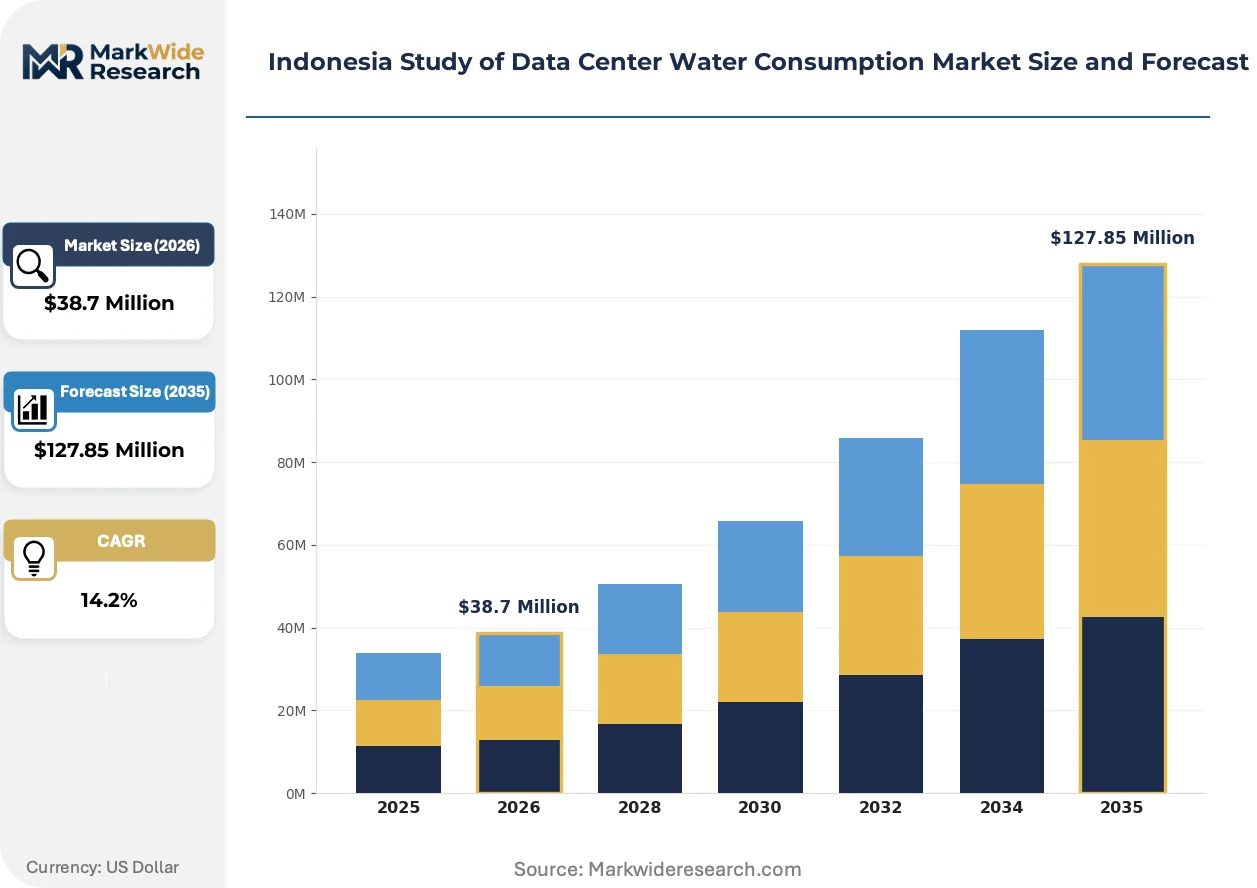
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $127.85 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cooling, Wastewater Management, Process Water, Landscaping Technology: Chilled Water System, Evaporative Cooling, Dry Cooling, Hybrid Cooling End User: Telecommunications, Cloud Service Providers, Colocation Facilities, Enterprises Usage Type: Continuous Use, Peak Load, Emergency Backup, Seasonal |
| Companies Covered | Equinix, Digital Realty, STT GDC, NTT Data, GDS Services, NeutraDC-Nxera, AWS, Microsoft, Google Cloud, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Study of Data Center Water Consumption Market Trends and Innovations
Cooling architecture decisions are migrating from facilities engineering to C-suite risk management as water stress intersects with uptime guarantees and regulatory compliance timelines in tropical deployment contexts.
Direct liquid cooling is miniaturizing heat exchange infrastructure by eliminating the intermediate chilled water loop between server and ambient rejection. Hyperscale operators in Cikarang and Tangerang are piloting cold-plate and immersion systems at 50-100kW rack densities. This compression is miniaturizing the mechanical footprint per megawatt deployed, freeing floor space for revenue-generating compute while reducing absolute freshwater draw.
Indonesia's Ministry of Environment and Forestry is tightening effluent discharge thresholds for total dissolved solids and thermal load, directly shaping cooling technology selection for new permits. Operators must now size on-site treatment capacity to meet stricter outflow standards before municipal connection approval. Colocation providers in Greater Jakarta are responding by bundling water-positive design into customer SLAs as a competitive differentiator.
Water stewardship metrics are migrating into procurement evaluation criteria as enterprise cloud buyers embed sustainability scoring into vendor selection. Traditional capex-focused RFPs are yielding to contracts with documented liters-per-megawatt-day performance clauses. This behavioral pivot is most visible among financial services and e-commerce platforms headquartered in Jakarta with net-zero commitments driving supply chain pressure downward.
Indonesia Study of Data Center Water Consumption Market Segmentation
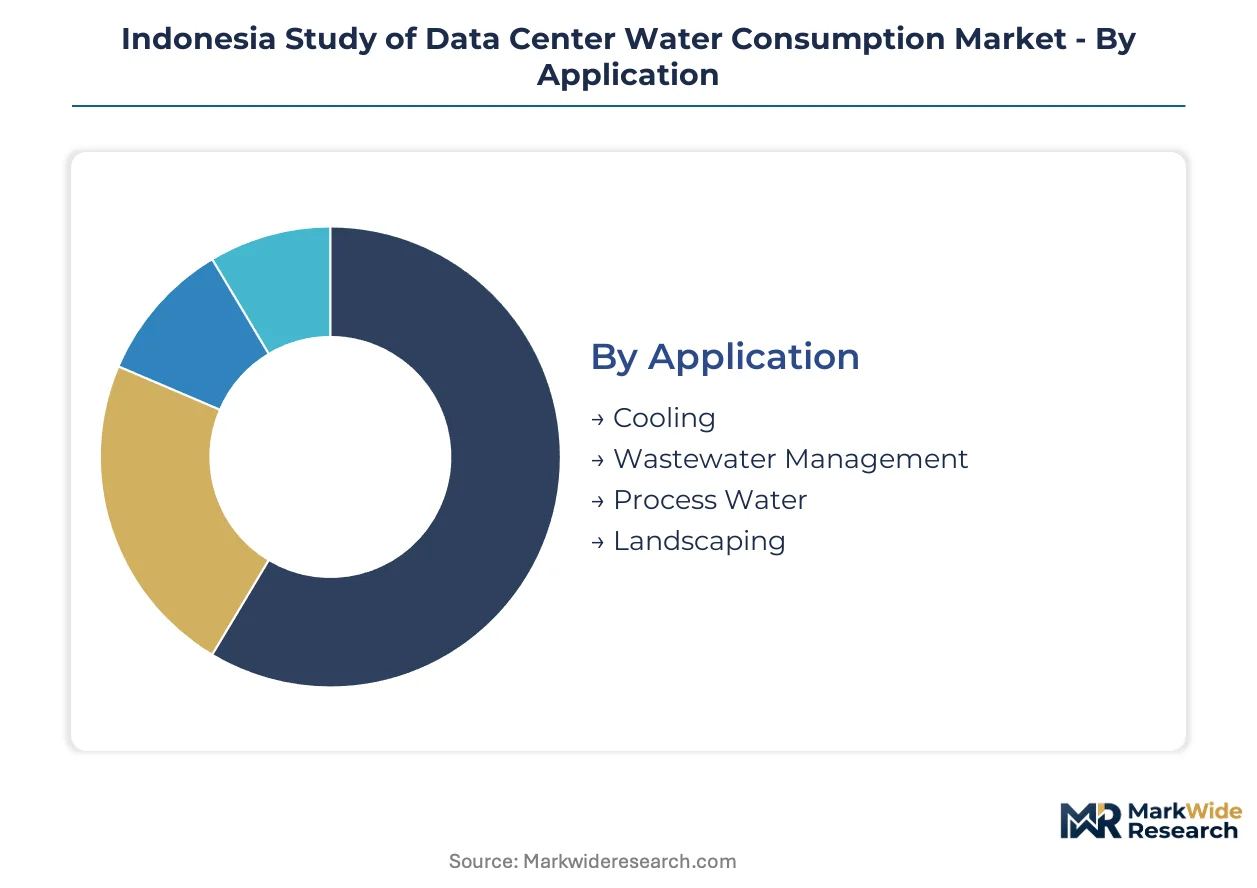
Water infrastructure investment patterns in Indonesian data centers diverge sharply across operational applications and cooling architectures. Regulatory pressure from the Ministry of Environment and Forestry compresses technology selection timelines differently for hyperscale campuses versus legacy colocation retrofits.
Application:
Effluent discharge thresholds from Indonesia's Ministry of Environment and Forestry treat cooling and wastewater streams as distinct permitting categories with separate treatment capex requirements.
- Cooling:Thermal management systems account for the largest freshwater abstraction volume, with chilled water loops and evaporative towers drawing directly from municipal supplies or captive groundwater wells. Demand concentrates in Greater Jakarta hyperscale campuses where ASHRAE thermal envelope compliance drives continuous circulation requirements.
- Wastewater Management:On-site treatment systems neutralize thermal load and total dissolved solids before discharge to municipal sewers or surface water bodies. Batam free trade zone operators are bundling advanced membrane filtration into greenfield designs to preempt regulatory delays.
- Process Water:Humidification and auxiliary mechanical systems require demineralized supply for precision equipment protection.
- Landscaping:Non-potable reuse from treated effluent supports site irrigation with lower regulatory scrutiny than industrial discharge.
Cooling handles the majority of throughput; wastewater management is expanding most quickly on share as effluent standards tighten.
Technology:
Capital intensity per megawatt deployed varies by a factor of three across cooling architectures, with hybrid systems commanding premium positioning in groundwater-restricted zones.
- Chilled Water System:Conventional mechanical refrigeration dominates installed base across Java's existing facilities, utilizing compressor-driven chillers and cooling towers with high freshwater intensity per kilowatt-hour rejected.
- Evaporative Cooling:Direct and indirect evaporative systems reduce energy consumption but amplify water dependency, creating vulnerability during Jakarta's dry season peaks when municipal supply volatility spikes.
- Dry Cooling:Air-cooled condensers eliminate evaporative losses entirely, trading higher fan energy for water independence in locations with aquifer extraction restrictions.
- Hybrid Cooling:Integrated architectures switch between evaporative and dry modes based on ambient wet-bulb temperature and water availability, optimizing operating expense across seasonal variation.
Chilled water systems retain the largest installed footprint; hybrid cooling is gaining share fastest as operators hedge municipal supply risk.
End User:
Procurement authority over water infrastructure capex sits at different organizational levels across customer types, shaping vendor engagement strategies and contract structures.
- Cloud Service Providers:AWS, Microsoft, and Google Cloud mandate on-site water recycling and documented liters-per-megawatt-day performance in multi-hundred-megawatt campus developments.
- Telecommunications:Telkom and Indosat Ooredoo Hutchison operate legacy facilities with perimeter cooling infrastructure that constrains rapid retrofit to liquid-cooled architectures.
- Colocation Facilities:Equinix and STT GDC compete on water-positive design bundling as enterprise customers embed sustainability scoring into vendor selection.
- Enterprises:Financial services and e-commerce platforms headquartered in Jakarta with net-zero commitments drive supply chain pressure downward through documented water stewardship metrics.
Cloud service providers command the steepest expansion trajectory; telecommunications holds the deepest legacy lock-in.
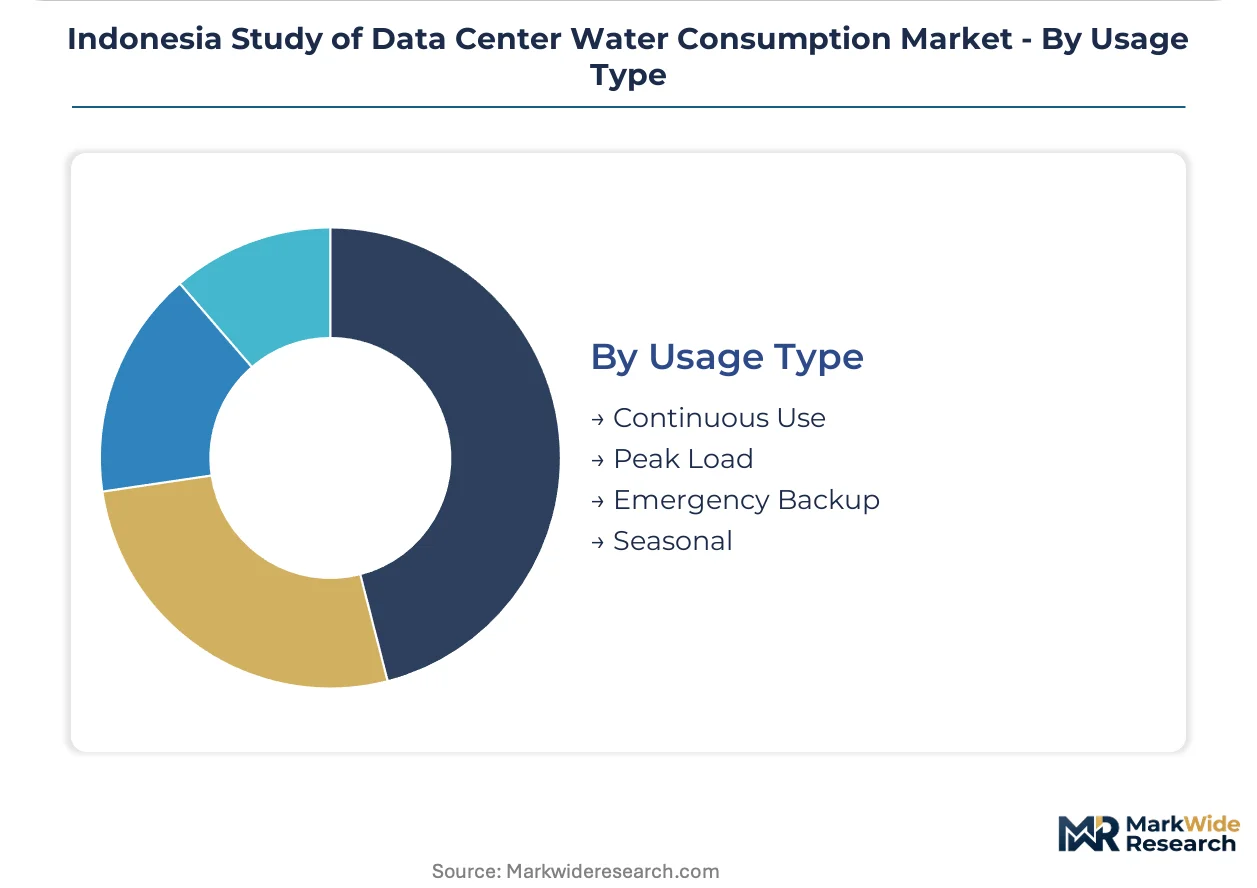
Usage Type:
Load profile shapes storage and treatment infrastructure sizing, with continuous circulation demanding baseline capacity and peak events requiring surge handling.
- Continuous Use:Baseline thermal load from always-on server racks determines chiller plant and cooling tower capacity ratings.
- Peak Load:Training workload bursts on GPU clusters create transient thermal spikes that strain evaporative cooling reserves during high ambient conditions.
- Emergency Backup:Redundant water storage and treatment capacity ensures ASHRAE compliance during municipal supply interruptions or equipment maintenance windows.
- Seasonal:Wet-bulb temperature variation across Jakarta's monsoon and dry seasons shifts optimal operating mode for hybrid cooling architectures.
Continuous use anchors infrastructure sizing; peak load is climbing fastest as AI training densities rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-elasticity varies sharply across Indonesian sub-regions, with hyperscale buyers in Greater Jakarta accepting premium water infrastructure pricing while provincial colocation operators in secondary cities prioritize lowest-cost cooling configurations.
Greater Jakarta
Hyperscale cloud campuses from AWS and Microsoft are driving advanced cooling adoption across Cikarang and Tangerang corridors. Jakarta Provincial Government groundwater extraction restrictions are forcing closed-loop designs and rainwater harvesting integration. Cikarang industrial zones host the densest concentration of liquid-cooled pilot deployments at 50-100kW rack densities.
Batam
Proximity to Singapore submarine cable landing points is attracting multi-hundred-megawatt pre-commitments with integrated water-positive designs. Batam Free Trade Zone incentives reduce municipal dependency through captive water treatment investments. Nongsa Digital Park anchors the island's emerging hyperscale cluster with membrane filtration bundled into greenfield permits.
Surabaya
Eastern Java's telecommunications infrastructure expansion is sustaining chilled water system demand for legacy Indosat Ooredoo Hutchison facilities. East Java Provincial Government industrial water regulations lag Jakarta's stringency, extending depreciation cycles for evaporative cooling. Rungkut industrial estate retains perimeter-cooled environments that constrain rapid retrofit economics.
Bandung
West Java's educational and research computing demand supports mid-scale colocation development with hybrid cooling hedging. Bandung City Government building codes are beginning to reference BIS-aligned water quality standards for new industrial permits. Cimahi manufacturing corridors attract edge computing deployments with lower freshwater intensity requirements than hyperscale baselines.
Medan
Sumatra's northern gateway is capturing disaster recovery and latency-sensitive workloads seeking geographic diversity from Java concentration. North Sumatra provincial water utility capacity limits are accelerating dry cooling evaluation for data center developers. Marelan industrial zones host emerging enterprise facilities with air-cooled condensers eliminating evaporative losses entirely.
Indonesia Study of Data Center Water Consumption Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Indonesia's data center water infrastructure landscape. Global operators with standardized design playbooks command premium positioning through documented water efficiency metrics, while regional specialists compete on capital-light deployment speed. Three archetypes dominate: hyperscale cloud providers with captive sustainability mandates, international colocation platforms with global replication models, and local developers with government relationship advantages. M&A activity concentrates on treatment technology tuck-ins, while capacity expansion focuses on Batam free trade zone positioning ahead of Singapore land constraints.
Within the global colocation tier, Equinix and Digital Realty exemplify standardized water-efficient architecture deployment across multiple Jakarta sites. STT GDC anchors the regional specialist position with captive infrastructure investments reducing municipal dependency. Among cloud-native operators, AWS and Microsoft represent the sustainability-mandated archetype with on-site recycling requirements in multi-hundred-megawatt campus developments.
| Leading Market Players |
|---|
| Equinix |
| Digital Realty |
| STT GDC |
| NTT Data |
| GDS Services |
| NeutraDC-Nxera |
| AWS |
| Microsoft |
| Google Cloud |
| Others |
Pricing and Supply Chain Analysis
Direct liquid cooling substitution for conventional chilled water architectures redraws procurement geography toward Singapore-based precision equipment distributors while compressing lifecycle cost premiums that previously favored legacy evaporative systems. This equipment shift elevates membrane filtration and cold-plate component sourcing above domestic chilled water tower fabrication, restructuring vendor negotiation leverage across Indonesian data center developments.
Pricing Analysis
After-sales service contracts and membrane replacement schedules anchor lifetime value capture for water treatment system vendors. Project-based equipment procurement dominates initial deployment, with pricing stratifying across premium, standard, and economy tiers based on treatment capacity certification and automation integration depth. Cost compression in standard-tier chilled water packages is intensifying as Chinese manufacturers expand Southeast Asian distribution networks. Cloud service providers exhibit lowest price sensitivity given sustainability mandate compliance requirements, while provincial telecommunications operators prioritize capital-light configurations with minimal automation.
Supply Chain Analysis
Singapore-Jakarta shipping lane congestion underwrites logistics vulnerability for precision cooling equipment and advanced membrane filtration systems. Manufacturing concentrates in China, South Korea, and Germany for chiller compressors, heat exchangers, and control systems. Raw material dependencies span copper tubing, specialized polymers, and rare-earth magnets for high-efficiency motors. Single-source vulnerability concentrates in precision temperature control valves and ceramic membrane substrates. Distribution runs through Singapore-based regional hubs with Batam free trade zone emerging as secondary staging point for Indonesian customs clearance optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around Ministry of Environment and Forestry discharge permits creates durable incumbent positioning against unlicensed new capacity.
For Market Incumbents: Shield permit-backed capacity positions through preemptive captive water treatment investments that exceed current effluent thresholds, locking in compliance headroom against anticipated regulatory tightening. Accelerate hybrid cooling retrofits in legacy Cikarang facilities before Jakarta Provincial Government groundwater restrictions expand geographic coverage. Vertical integration into on-site membrane filtration maintenance capabilities captures aftermarket revenue streams that emerging competitors cannot replicate without established service infrastructure. For New Entrants and Emerging Players: Anchor in Batam Free Trade Zone greenfield developments where Nongsa Digital Park infrastructure and streamlined permitting create lower barriers to water-positive design implementation than saturated Greater Jakarta corridors. Target disaster recovery and latency-sensitive workload segments seeking geographic diversity from Java concentration, where buyers prioritize operational resilience over lowest capital cost. Differentiate through modular containerized treatment systems that accelerate commissioning timelines against incumbent project-based construction cycles. For Investors and Strategic Acquirers: Ministry of Environment and Forestry effluent threshold revisions reshape the acquisition landscape toward operators with documented compliance infrastructure and expandable treatment permits. Five-to-ten year viability favors platforms with integrated water stewardship metrics embedded in enterprise customer SLAs. Prioritize targets with captive rainwater harvesting and closed-loop cooling architectures. Monitor Jakarta Provincial Government aquifer extraction restriction expansion announcements as signal for accelerated hybrid cooling retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Water Treatment Investment | STT GDC's Batam membrane filtration bundling reduces municipal dependency and accelerates permit approval timelines. |
| Direct Liquid Cooling Pilot Deployment | Hyperscale cold-plate installations at 50-100kW densities in Cikarang compress mechanical footprint per megawatt deployed. |
| Green Building Certification Alignment | LEED and local green data center standards create preferential permitting lanes for documented water reuse metrics. |
| Hybrid Cooling Architecture Adoption | Integrated evaporative-dry mode switching hedges against Jakarta dry season municipal supply volatility spikes. |
| Rainwater Harvesting Integration | Closed-loop designs with captive collection reduce groundwater extraction exposure under provincial aquifer restrictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Ministry of Environment and Forestry regulatory filings, Jakarta Provincial Government groundwater extraction permits, and BIS-aligned industrial water quality standards. Primary interviews engaged data center facility engineers, cooling system procurement leads at cloud service providers, membrane filtration equipment distributors, and thermal design consultants active across Greater Jakarta and Batam. Secondary validation drew from Indonesia Investment Coordinating Board facility registration databases, Singapore Trade Development Board export records for precision cooling equipment, and hyperscaler sustainability disclosure reports. Bottom-up capacity installation tracking triangulates against top-down water infrastructure investment flow analysis.
Segmentation dimensions modeled span cooling application type, technology architecture, end user procurement authority, and usage load profile across the projection horizon. Cooling segment splits capture thermal management versus wastewater management versus process water abstraction patterns. Technology segmentation tracks chilled water, evaporative, dry, and hybrid system share evolution. End user categories distinguish cloud service provider captive mandates from telecommunications legacy constraints and enterprise sustainability-driven procurement. CAGRs derive from facility-level water intensity benchmarking against projected megawatt capacity expansion schedules. Forecast inputs incorporate seasonal wet-bulb temperature variation patterns and regulatory compliance timeline assumptions.
Decision-makers should treat outputs as directional under base assumptions of continued Ministry of Environment and Forestry effluent threshold tightening and stable Singapore-Jakarta logistics corridor performance; material deviation in regulatory enforcement intensity or shipping lane disruption would warrant model refresh. Practitioners should keep alternative scenarios live as Jakarta Provincial Government groundwater restriction geography and Batam free trade zone incentive durability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Chile Data Center Cooling Market