
 Middle East and Africa E-Commerce Apparel Market | 2026-2036
Middle East and Africa E-Commerce Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa E-Commerce Apparel Market Insights
Asset-light marketplace models and third-party logistics leasing is rewriting competitive entry costs across the Middle East and Africa E-Commerce Apparel Market. Noon.com leverages its captive fulfillment network to sustain next-day delivery promises in the UAE and Saudi Arabia. Landmark Group anchors regional inventory depth through its sprawling brick-and-click infrastructure. Namshi differentiates via curated brand assortments and localized payment integrations that dominate Gulf consumer preferences.
E-commerce apparel denotes clothing and accessories sold through digital interfaces, encompassing web-native inventory management, size-standardization algorithms, and last-mile distribution orchestrated from fulfillment nodes to individual residences. The category serves consumers seeking convenience, assortment breadth, and price transparency without physical store visitation. Activewear claims the fastest expansion trajectory among product type segments as Gulf fitness participation and modest athletic wear innovation accelerate. Mobile applications capture disproportionate transaction flow within distribution channel architecture, reflecting smartphone-first internet access patterns across Kenya, Nigeria, and the UAE. Luxury price tier positioning concentrates margin pools in Dubai and Riyadh, though value tier volume dominates aggregate unit economics through discount marketplace proliferation.
Saudi Arabia's Zakat, Tax and Customs Authority and the UAE's Federal Tax Authority shape cross-border duty structures that determine landed cost competitiveness for international platforms. South Africa's National Credit Regulator and Consumer Protection Act govern installment payment schemes and return policies that influence conversion funnel design. Egypt's customs modernization initiatives and Ethiopia's industrial park frameworks alter manufacturing-origin sourcing calculus for regional e-tailers. Stakeholders must monitor how Gulf data localization mandates and evolving African Union digital trade protocols reshape platform architecture and supplier eligibility requirements.
Market Dynamics
Mobile-first purchasing patterns among young urban professionals in Lagos and Nairobi are compressing traditional retail intermediation, while Saudi Arabia's Zakat and VAT framework rewrites cross-border fulfillment economics for regional platforms.
Growth Catalysts
- Digital Payment Penetration:Smartphone-based transaction infrastructure in Kenya and Nigeria bypasses legacy banking constraints, unlocking apparel purchasing power among previously unbanked demographics.
- Gulf Logistics Modernization:The UAE's Federal Tax Authority streamlined customs protocols accelerate last-mile velocity for fashion inventory flowing through Dubai's free zones.
- Modest Activewear Innovation:Technical fabric development for fitness-compliant modest dress codes expands addressable demand within Saudi Arabia's female consumer segment.
Market Restraints
- Cross-Border Duty Complexity:Saudi Arabia's Zakat, Tax and Customs Authority imposes layered compliance costs that erode margin competitiveness for international marketplace entrants.
- Sub-Saharan Infrastructure Gaps:Fragmented cold-chain and last-mile networks outside the Gulf Cooperation Council corridor inflate fulfillment costs and delivery failure rates.
- Cash-on-Delivery Persistence:High rates of payment-on-delivery in Egypt and Nigeria strain working capital cycles and elevate return processing overhead for apparel merchants.
Strategic Opportunities
- Ethiopian Industrial Park Sourcing:Manufacturing-origin relocation to Ethiopia's specialized textile zones offers tariff-advantaged inventory for regional e-tailers serving Gulf markets.
- Installment Payment Schemes:South Africa's National Credit Regulator frameworks enable structured credit products that lift average order values in price-sensitive apparel segments.
- AI-Driven Size Standardization:Machine learning algorithms addressing fit uncertainty are reducing return rates and unlocking consumer willingness to purchase non-returnable sale inventory.
Industry Challenges
- Data Localization Mandates:Gulf state requirements for domestic server infrastructure force platform architecture rewrites that delay product roadmap execution.
- Skill Scarcity in Fulfillment Engineering:Shortage of supply chain optimization talent familiar with both Sharia-compliant financing structures and modern warehouse automation constrains operational scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa E-Commerce Apparel Market |
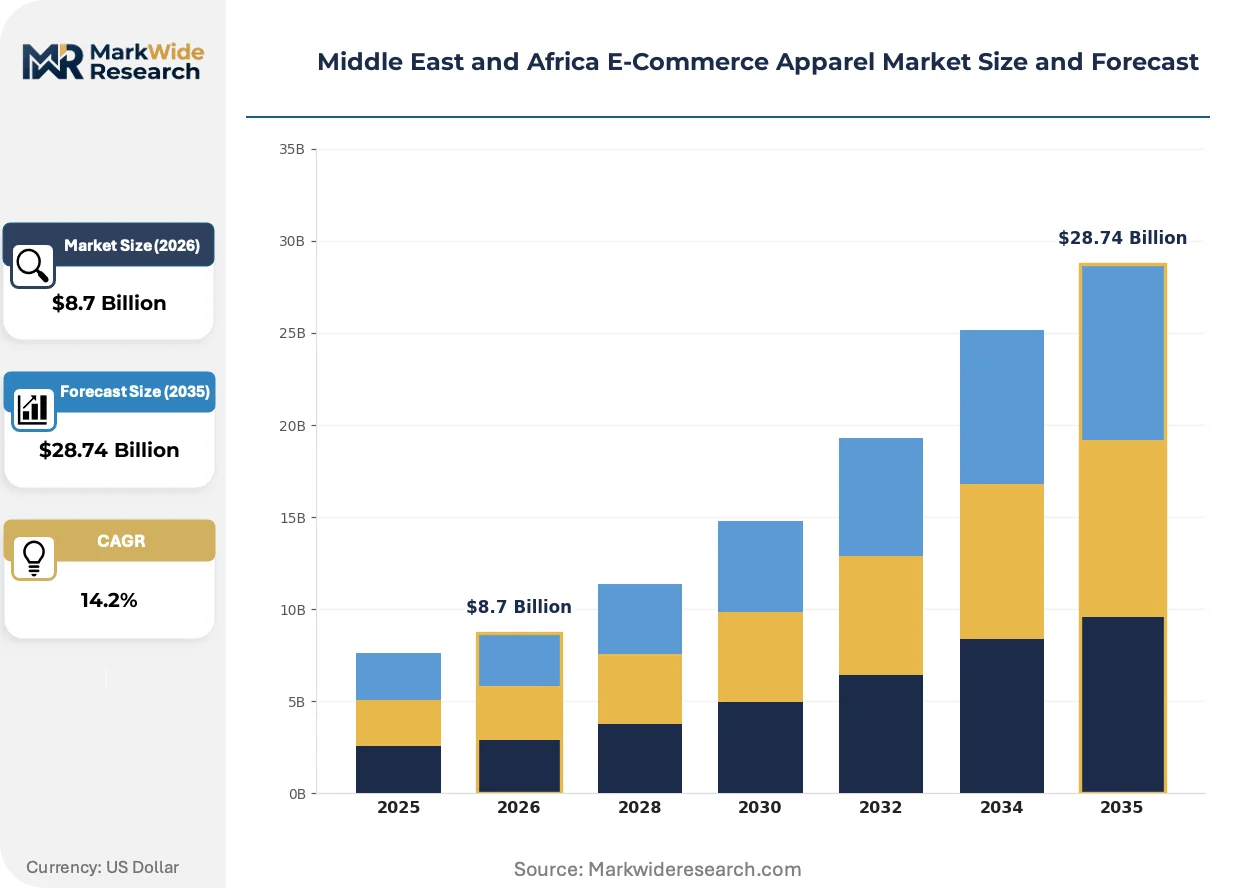
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-shirts, Dresses, Jeans, Activewear Customer Type: Retail Shoppers, Bulk Buyers, Resellers, Direct-to-Consumer Distribution Channel: Online Marketplaces, Brand Websites, Social Media, Mobile Applications Price Tier: Luxury, Mid-range, Discount, Value |
| Companies Covered | Landmark Group, LVMH Moët Hennessy Louis Vuitton, Industria de Diseño Textil, S.A. (INDITEX), Namshi, Noon.com, H & M Hennes & Mauritz, Kering, Ounass, Adidas, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa E-Commerce Apparel Market Trends and Innovations
Three interconnected shifts are compressing traditional apparel retail cycles across the Middle East and Africa: algorithmic inventory matching, regulatory recalibration of cross-border flows, and the unbundling of discovery from transaction in consumer behavior.
Visual search technology trained on modest fashion aesthetics is rendering obsolete text-based query interfaces that previously dominated Arabic-language apparel discovery. Young female consumers in Riyadh and Jeddah are adopting image-upload functionality at three times the rate of conventional search bars. This compression of the consideration phase is collapsing the traditional funnel architecture that legacy e-commerce platforms built around keyword optimization.
Saudi Arabia's Zakat, Tax and Customs Authority has implemented real-time duty calculation APIs that eliminate the post-purchase price shock previously eroding Gulf consumer trust in cross-border apparel orders. International platforms are now pre-integrating landed cost transparency into product display pages. The luxury price tier segment in Dubai and Riyadh has responded fastest, with premium marketplace entrants restructuring supplier contracts to absorb duty visibility as a competitive differentiator.
Social commerce discovery on short-form video platforms is displacing traditional search-engine-initiated purchasing for trend-driven apparel categories. Influencer-curated collections on TikTok and Instagram Reels are capturing first-touch attribution that previously flowed to Google Shopping campaigns. This behavioral rotation is most pronounced in Nigeria's urban centers, where data-light video formats outperform image-heavy catalog browsing on congested mobile networks.
Middle East and Africa E-Commerce Apparel Market Segmentation
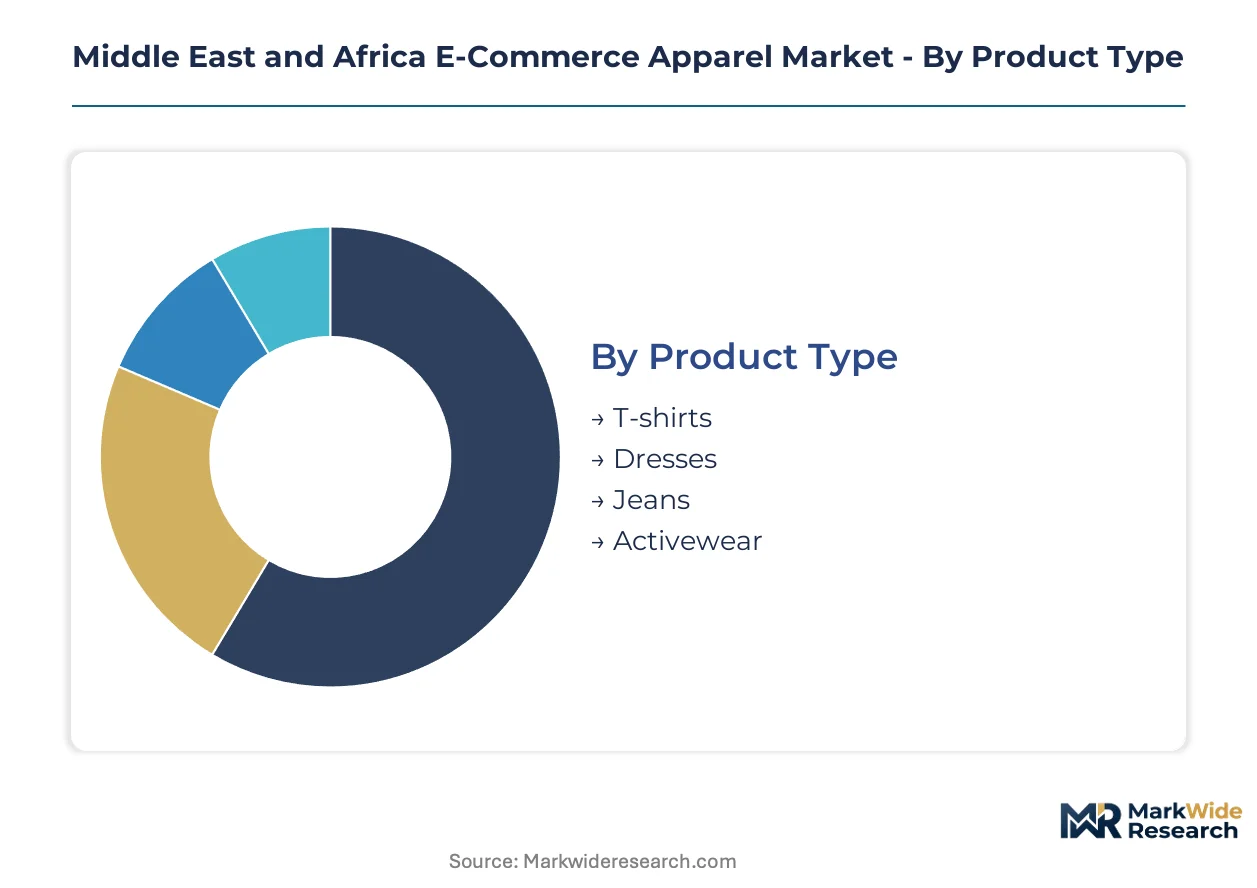
Segmentation in the Middle East and Africa E-Commerce Apparel Market exposes divergent service requirements across product categories and customer profiles. Mobile-first purchasing patterns and cross-border fulfillment complexity create distinct operational demands that reward specialized platform architecture.
Product Type:
After-sales service intensity varies dramatically across apparel categories, with fit-related returns driving disproportionate support costs for certain segments while others operate on near-zero-touch fulfillment models.
- Activewear:Technical fabric compositions with moisture-wicking and compression specifications dominate manufacturing specifications. Demand concentrates in Riyadh and Dubai where female fitness participation and modest athletic wear innovation accelerate category expansion.
- Dresses:Varied silhouettes spanning casual daywear to formal occasion pieces create complex size-standardization challenges. Lagos and Nairobi shoppers drive volume through mobile-first discovery, though return rates exceed other categories due to fit uncertainty.
- Jeans:Denim weight classifications and stretch-cotton blends define quality tiers across Gulf and sub-Saharan markets.
- T-shirts:Basic cotton and blended knits serve as entry-price acquisition tools for platform customer acquisition strategies.
By volume, T-shirts lead. By growth pace, Activewear is ahead.
Customer Type:
Cost tier stratification separates individual purchasers from institutional buyers, with working capital requirements and payment term negotiations creating distinct platform onboarding friction.
- Retail Shoppers:Individual consumers purchasing single or small-basket quantities dominate transaction counts. Nigerian and Kenyan urban professionals compress purchase cycles through smartphone-based checkout, bypassing traditional retail intermediation entirely.
- Direct-to-Consumer:Brand-owned channel strategies bypass marketplace commission structures. Saudi Arabia's Zakat and VAT framework shapes landed cost calculations for international DTC entrants targeting Gulf consumers.
- Bulk Buyers:Corporate procurement and event-based purchasing clusters in UAE and South African metropolitan centers.
- Resellers:Informal distribution networks leverage price arbitrage across Egypt and Morocco's fragmented retail landscapes.
Retail Shoppers generate the highest transaction frequency. Direct-to-Consumer channels are climbing the fastest.
Distribution Channel:
Application-specific interface requirements fragment technical investment, with video-optimized discovery layers demanding entirely separate engineering stacks from traditional catalog architectures.
- Mobile Applications:Native iOS and Android interfaces optimized for 3G network constraints and offline browsing functionality. Nigerian and Kenyan markets exhibit near-total smartphone dependency, with app-based checkout ratios exceeding desktop by factors of ten.
- Social Media:TikTok and Instagram Reels integration enables influencer-curated collection drops. Lagos and Nairobi consumers demonstrate highest engagement with short-form video discovery, displacing traditional search-initiated purchasing.
- Online Marketplaces:Aggregated inventory platforms with third-party seller infrastructure dominate UAE and Saudi transaction volume.
- Brand Websites:Direct proprietary channels concentrate among luxury tier positioning in Dubai and Riyadh.
Online Marketplaces capture the largest share of current volume. Social Media is gaining share fastest.
Price Tier:
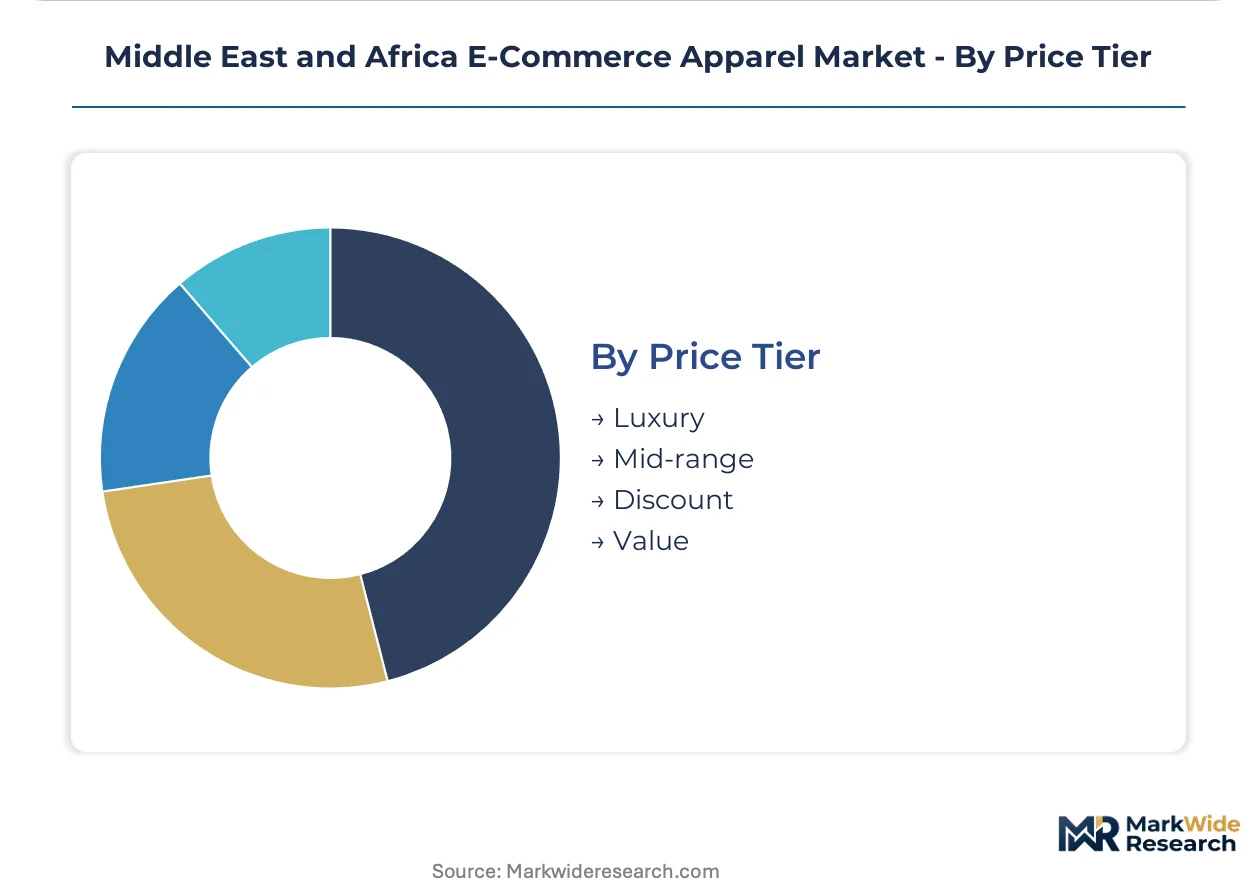
Margin concentration patterns separate inventory-heavy value positioning from asset-light premium curation, with working capital intensity determining viable competitive entry points.
- Luxury:Designer and premium brand positioning with authenticated provenance guarantees. Dubai and Riyadh concentrate regional demand, where Federal Tax Authority streamlined customs protocols support cross-border luxury fulfillment.
- Discount:Flash sale and promotional inventory liquidation through time-limited event structures. Egyptian and Nigerian price-sensitive segments respond to aggressive markdown messaging on congested mobile networks.
- Mid-range:Bridge brands and private label positioning across South African and Moroccan urban centers.
- Value:Basic commodity apparel with minimal brand premium and maximum unit velocity.
Discount tier leads by transaction volume. Luxury is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Zakat, Tax and Customs Authority has streamlined cross-border duty calculation protocols, accelerating regional e-commerce apparel fulfillment velocity. The UAE's Federal Tax Authority and South Africa's National Credit Regulator create divergent compliance environments that shape platform architecture decisions. Nigeria's central bank digital currency pilots and Ethiopia's industrial park frameworks add further complexity to multi-country operating models.
Saudi Arabia
Female fitness participation and modest activewear innovation drive demand acceleration in Riyadh and Jeddah. The Zakat, Tax and Customs Authority mandates real-time duty calculation APIs that eliminate post-purchase price shock for cross-border orders. Jeddah's logistics free zones concentrate fulfillment infrastructure for platforms serving the Western Region consumer base.
United Arab Emirates
Dubai's luxury consumer segment concentrates regional margin pools for premium marketplace positioning. The Federal Tax Authority streamlined customs protocols accelerate last-mile velocity for fashion inventory flowing through Dubai's free zones. Abu Dhabi's sovereign wealth-backed digital infrastructure investments anchor captive fulfillment network expansion across the Gulf Cooperation Council corridor.
South Africa
Structured credit products and installment payment schemes lift average order values in price-sensitive apparel segments. The National Credit Regulator and Consumer Protection Act govern return policies and payment term negotiations that influence conversion funnel design. Cape Town's design and manufacturing clusters support regional private-label development for mid-range positioning.
Nigeria
Young urban professionals in Lagos compress purchase cycles through smartphone-based checkout, bypassing traditional retail intermediation entirely. The central bank's digital currency pilots and mobile money interoperability frameworks reshape payment infrastructure for previously unbanked demographics. Lagos anchors West African demand concentration, with congested mobile networks favoring data-light video discovery formats.
Ethiopia
Manufacturing-origin relocation to specialized textile zones offers tariff-advantaged inventory for regional e-tailers serving Gulf markets. Industrial park frameworks alter sourcing calculus through preferential trade access and duty-free export status. Addis Ababa's Hawassa Industrial Park concentrates apparel manufacturing capacity for platforms seeking origin diversification beyond Asian supply bases.
Middle East and Africa E-Commerce Apparel Market Competitive Landscape
Channel-controlling players compete with product-specialist players for consumer attention and fulfillment velocity across the Middle East and Africa E-Commerce Apparel Market. The competitive structure fragments across three strategic tiers: marketplace aggregators with captive logistics, brick-and-click retailers with regional inventory depth, and brand-owned direct channels with authenticated provenance. Consolidation pressure concentrates among Gulf-based platforms seeking scale economies in last-mile delivery, while specialist players defend positioning through curated assortments and localized payment integrations. Dominant competitive moves include strategic partnerships with third-party logistics providers and portfolio diversification into private-label manufacturing.
Within the Gulf-based marketplace tier, Noon.com and Namshi exemplify divergent strategic archetypes. Noon.com anchors the scale-driven vector through captive fulfillment infrastructure sustaining next-day delivery promises across the UAE and Saudi Arabia. Namshi occupies a position emphasizing curated brand assortments and localized payment integrations that dominate Gulf consumer preferences. Landmark Group represents the brick-and-click hybrid model, leveraging sprawling physical infrastructure to anchor regional inventory depth against pure-play digital entrants. These three players collectively illustrate the competitive tension between asset-heavy operational control and asset-light curation specialization reshaping regional market structure.
| Leading Market Players |
|---|
| Landmark Group |
| LVMH Moët Hennessy Louis Vuitton |
| Industria de Diseño Textil, S.A. (INDITEX) |
| Namshi |
| Noon.com |
| H & M Hennes & Mauritz |
| Kering |
| Ounass |
| Adidas |
| Others |
Pricing and Supply Chain Analysis
Dubai's Jebel Ali Free Zone freight corridors concentrate apparel inventory flows and impose cost structures that stratify final consumer pricing across Gulf and sub-Saharan markets. Saudi Arabia's Zakat and VAT framework layers compliance expenditures onto landed costs, forcing platforms to absorb duty transparency as a competitive wedge or pass through to price-sensitive segments.
Pricing Analysis
Brand premium and certification tier create the primary spread between luxury and value positioning in Middle East and Africa e-commerce apparel. Three-tier pricing structure across premium, standard, and economy levels dominates marketplace architecture, with Dubai and Riyadh luxury consumers absorbing authenticated provenance markups while Nigerian and Egyptian segments gravitate toward promotional flash pricing. Cost compression in the value tier is intensifying because discount marketplace proliferation erodes margin buffers. Retail shoppers in Lagos and Nairobi exhibit highest price sensitivity, whereas Gulf-based bulk buyers and corporate procurement clusters demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between Ethiopia's Hawassa Industrial Park and Gulf Cooperation Council consumer markets dominates supply chain risk calculus for regional e-tailers. Manufacturing-origin concentration in Ethiopia, Bangladesh, and Vietnam feeds raw cotton, technical synthetics, and finished garment dependencies. Single-source vulnerability in Ethiopian textile zones threatens inventory continuity for platforms seeking tariff-advantaged sourcing. Distribution runs through Dubai's free zone consolidation hubs before fragmenting into last-mile networks spanning Saudi Arabia, UAE, and South Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa e-commerce apparel market sits at a platform-economics inflection where social commerce discovery layers and mobile wallet interoperability are collapsing traditional search-to-purchase funnels. Stakeholders must recalibrate around captive fulfillment velocity and algorithmic inventory matching as the new competitive moats.
For Market Incumbents: Build captive logistics moats through third-party logistics leasing and warehouse automation in Jeddah and Dubai free zones. Noon.com's next-day delivery promises demonstrate how fulfillment velocity defends against curated-brand specialists. Absorb Saudi Arabia's Zakat and VAT compliance costs into landed price transparency to neutralize cross-border duty complexity as an entrant wedge. Channel control through proprietary mobile applications retains transaction flow against TikTok and Instagram Reels disintermediation. For New Entrants and Emerging Players: Build out modest activewear private-label manufacturing partnerships with Ethiopian industrial park operators to capture tariff-advantaged inventory positioning. White-space concentration exists in AI-driven size standardization tools that reduce return rates for dress and denim categories where fit uncertainty erodes conversion. Target South Africa's installment payment scheme infrastructure as the most penetrable geographic entry point, leveraging National Credit Regulator frameworks to lift average order values in price-sensitive segments. For Investors and Strategic Acquirers: Carve-out targets emerge from brick-and-click retailers with sprawling physical infrastructure but underdeveloped digital channel integration. Landmark Group's hybrid model exemplifies the archetype where regional inventory depth could be unbundled into pure-play marketplace positioning. Long-term viability hinges on data localization mandate compliance and Gulf state server infrastructure investments. The signal to watch is real-time duty calculation API adoption rates across Saudi Arabia's Zakat, Tax and Customs Authority enforcement perimeter.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fulfillment Network Expansion | Noon.com's UAE and Saudi Arabia warehouse automation sustains next-day delivery promises against curated specialists. |
| Ethiopian Industrial Park Sourcing | Hawassa textile zones offer tariff-advantaged manufacturing origin for Gulf-bound apparel inventory. |
| AI-Driven Size Standardization | Machine learning fit algorithms reduce return rates in dress and denim categories with highest fit uncertainty. |
| Social Commerce Platform Integration | TikTok and Instagram Reels discovery layers capture first-touch attribution from Google Shopping in Nigeria. |
| Installment Payment Scheme Licensing | South Africa's National Credit Regulator frameworks enable structured credit products lifting average order values. |
Research Methodology
Initial hypotheses were tested against primary input from e-commerce platform executives, third-party logistics operators, apparel brand regional managers, and mobile payment infrastructure providers and refined through secondary validation. Primary interviews examined fulfillment velocity investments, Zakat and VAT compliance architecture, and social commerce discovery layer engineering. Secondary sources included Saudi Arabia's Zakat, Tax and Customs Authority regulatory filings, UAE Federal Tax Authority customs protocols, South Africa's National Credit Regulator installment scheme disclosures, and trade flow data from Ethiopian Industrial Parks Development Corporation. Bottom-up transaction volume modeling and top-down addressable market sizing were triangulated against operating metrics disclosed by listed marketplace operators.
Demand-supply balance across the projection horizon anchored the analytical framework, with segmentation dimensions spanning product type, customer archetype, distribution channel, and price tier. Modeled variables included activewear technical fabric specifications, mobile application checkout ratios, and luxury versus value tier margin concentration. CAGRs were derived from fitted growth curves against historical trajectory and policy inflection points. Forecast inputs incorporated Saudi female fitness participation rates, Nigerian mobile money interoperability expansion, and Gulf logistics modernization capex cycles.
Stress conditions across customs duty rate volatility, Ethiopian industrial park capacity constraints, and sub-Saharan last-mile network fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around regulatory stability and payment infrastructure penetration that could revise materially with African Union digital trade protocol evolution or Gulf data localization mandate enforcement shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
E-Commerce Logistics Market
E-Commerce Solutions
Japan Cross Border E Commerce Market
E-Commerce Solutions
Hong Kong E-Commerce Market
E-Commerce Solutions
Netherlands E-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
Latin America E-Commerce Logistics Market