
 Australia Data Center Rack Market | 2026-2036
Australia Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Data Center Rack Market Insights
Multi-source procurement of data center rack infrastructure is broadening across Australian facility operators. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale projects. Rittal GMBH & Co.KG competes through precision-engineered enclosure systems suited to tropical climate zones. Vertiv Group sustains its position via thermal management bundled with rack solutions.
A data center rack is a standardized metal frame designed to house servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310-D specifications for equipment mounting width. Its primary purpose is to optimize spatial density, cable management, and airflow containment within climate-controlled facilities. Enclosed racks command premium positioning where dust filtration and physical security drive specification decisions, while open frame variants dominate cost-sensitive colocation builds. Among end users, telecommunications operators represent the most mature procurement segment, whereas government deployments are expanding fastest under digital sovereignty mandates.
TGA infrastructure guidelines intersect with AS/NZS 3000 electrical standards to shape rack-level power distribution and safety certification requirements for Australian facilities. The Critical Infrastructure Protection Act administered by the Department of Home Affairs imposes physical security obligations that directly influence enclosed rack and access control specifications. Stakeholders must monitor how evolving energy efficiency benchmarks from the Climate Change Authority reshape cooling-integrated rack designs.
Market Dynamics
Hyperscale cloud expansions across Sydney and Melbourne are compressing deployment timelines and forcing rack suppliers to synchronize manufacturing with construction schedules. The Critical Infrastructure Protection Act is mandating physical security upgrades that favor enclosed rack architectures over open-frame alternatives.
Growth Catalysts
- Critical Infrastructure Protection Act compliance mandates:Physical security obligations under the Department of Home Affairs directive are accelerating enclosed rack specifications across government and telecommunications facilities.
- Hyperscale construction clusters:New South Wales and Victoria are attracting concentrated cloud provider investment, creating synchronized demand spikes for high-density rack infrastructure.
- TGA infrastructure guidelines:Healthcare data center specifications are expanding rack procurement from pharmaceutical and medical device sectors requiring climate-controlled storage.
Market Restraints
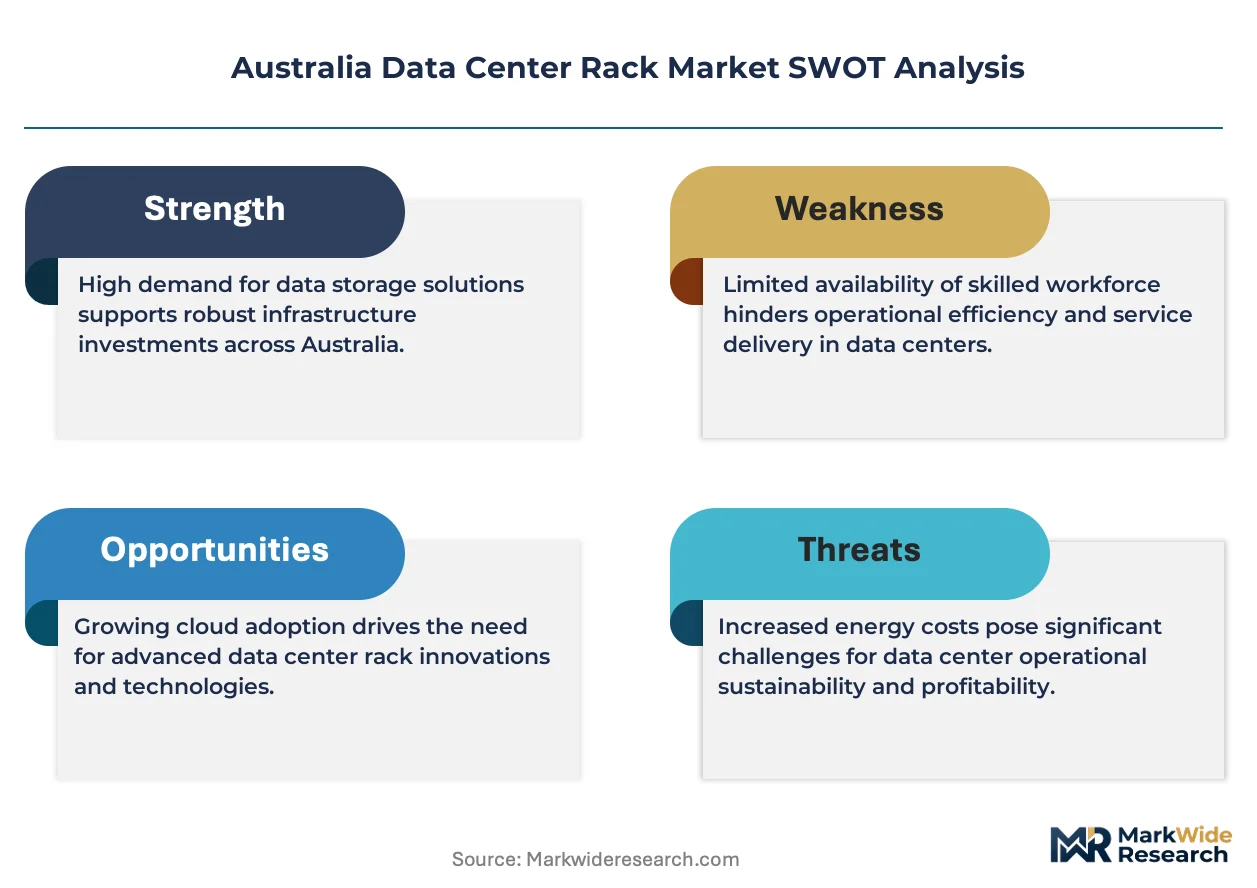
- Steel and aluminum input volatility:Raw material price fluctuations for rack enclosure metals are compressing manufacturer margins and complicating long-term contract pricing.
- Electrical certification bottlenecks:AS/NZS 3000 compliance testing delays are extending delivery timelines for integrated power distribution rack systems.
- Modular containerized substitutes:Prefabricated modular data centers are displacing traditional rack-at-a-time deployments in remote and edge locations.
Strategic Opportunities
- Queensland and Western Australia underpenetration:Secondary state markets lack hyperscale presence, creating first-mover advantages for regional colocation operators seeking rack infrastructure.
- Liquid cooling convergence with rack design:Direct-to-chip cooling integration is opening specification windows for vendors with thermal engineering capabilities.
- Climate Change Authority efficiency benchmarks:Evolving energy performance standards are creating pull for cooling-integrated rack systems that reduce facility-level power usage.
Industry Challenges
- Specialized installation technician scarcity:Certified technicians for high-density rack deployment and cable management are concentrated in Sydney and Melbourne, constraining national rollout velocity.
- Legacy facility retrofit complexity:Older data centers in Australian capital cities require structural reinforcement to support modern rack weight loads, complicating upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Data Center Rack Market |
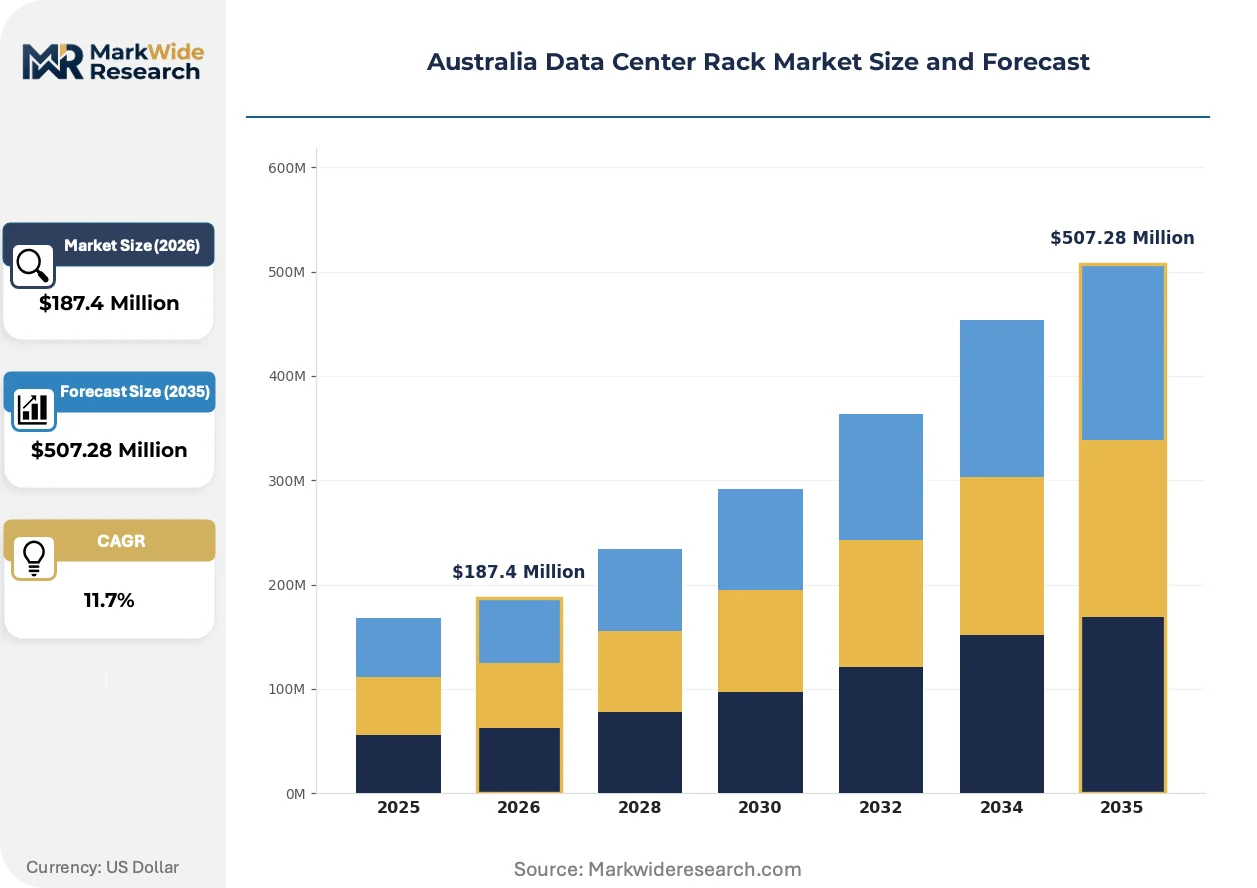
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Racks, Enclosed Racks, Wall-Mounted Racks, Specialized Racks End User: Telecommunications, BFSI, Healthcare, Government Size: 1U, 2U, 3U, 42U Power Rating: Single Phase, Three Phase, High Power, Low Power |
| Companies Covered | Schneider Electric SE, Rittal GMBH & Co.KG, Vertiv Group, Dell Inc., Hewlett Packard Enterprise, Legrand SA, Cisco Systems, Inc., Eaton, Panduit Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Data Center Rack Market Trends and Innovations
Intelligent rack infrastructure is displacing passive metal framing as the default specification. Sensor integration, power monitoring, and automated airflow management are becoming baseline requirements rather than premium upgrades.
AI-enabled predictive thermal management is rewriting how facility operators approach cooling redundancy. Machine learning algorithms analyze real-time rack-level temperature patterns to optimize airflow before hotspots develop. Hyperscale operators in Sydney are deploying these systems at scale, compressing the acceptable response time for thermal anomalies from minutes to seconds. This capability is enabling denser server packing without proportional cooling infrastructure expansion.
The Critical Infrastructure Protection Act is tightening physical access control requirements for data facilities nationwide. Biometric rack-level authentication and audit logging are becoming mandatory specifications for government and critical infrastructure operators. Telstra and NBN Co facilities are retrofitting existing enclosures to meet these standards, creating aftermarket demand for security upgrade kits.
Consolidated procurement through master service agreements is displacing transactional rack purchasing. Large colocation providers are negotiating multi-year supply contracts with integrated maintenance and refresh provisions. This model concentrates purchasing power with top-tier facility operators while marginalizing smaller regional data centers that cannot meet volume minimums. The shift is most visible in Melbourne's Docklands precinct, where competing operators have adopted similar contract structures.
Australia Data Center Rack Market Segmentation
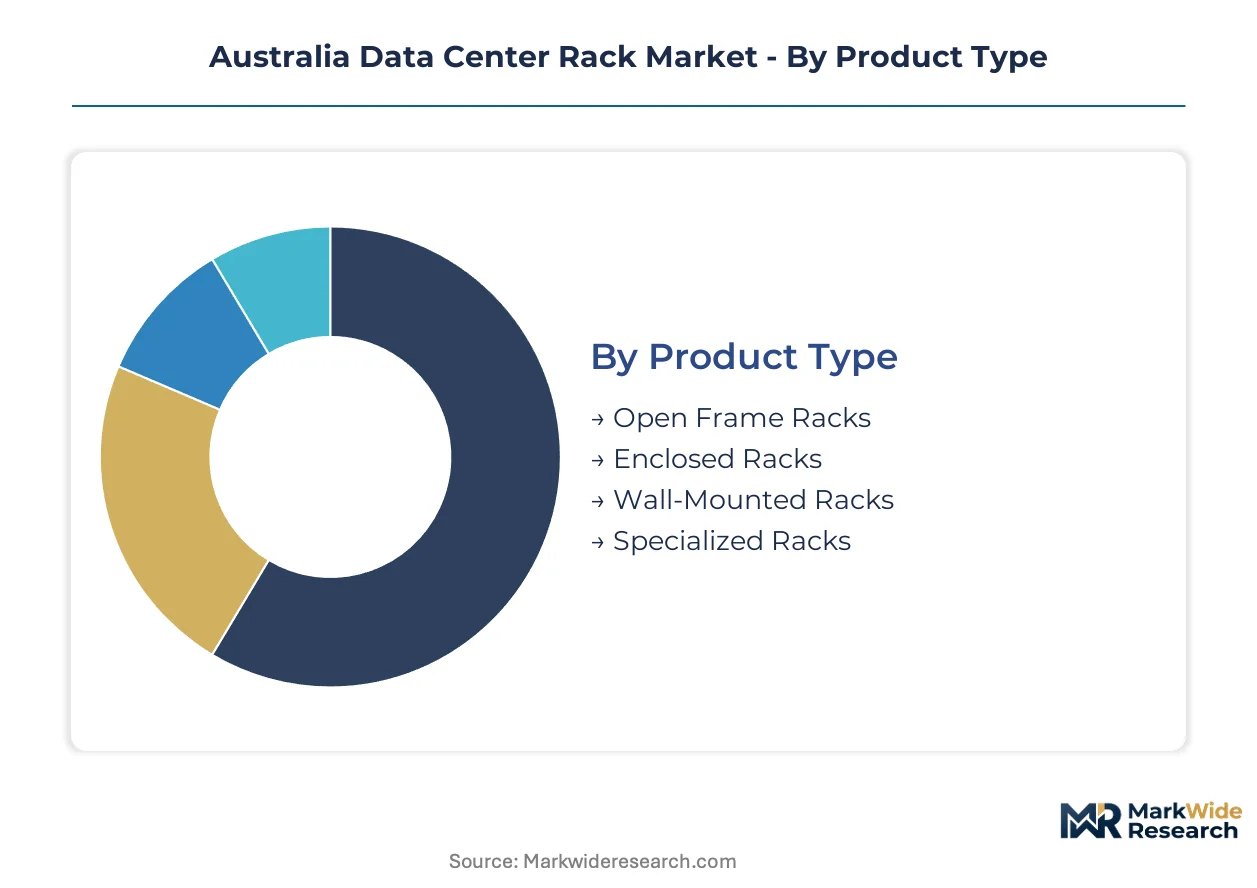
Segmentation reveals how rack specifications diverge across Australian deployment contexts. Product architecture choices reflect security mandates, while end-user procurement patterns map directly to regulatory exposure and infrastructure maturity.
Product Type:
Volume deployments favor open architectures, yet premium specifications are tilting toward sealed enclosures under compliance pressure.
- Open Frame Racks:Metal framing without side panels or doors, optimized for airflow and cable accessibility. Colocation providers across Melbourne's Docklands precinct specify these for cost-sensitive hyperscale halls where rapid equipment swaps outrank physical security concerns.
- Enclosed Racks:Lockable cabinet designs with dust filtration and side panels. Government facilities under the Critical Infrastructure Protection Act mandate these for controlled access, with demand clustering in Canberra and Sydney defense-adjacent sites.
- Wall-Mounted Racks:Compact enclosures for edge and branch deployments. Regional bank branches in Queensland favor these for space-constrained server rooms.
- Specialized Racks:Custom-configured frames for liquid cooling or seismic reinforcement. Niche uptake in Perth's resource-sector data centers handling vibration-sensitive workloads.
Today's leader: Open Frame Racks. Tomorrow's challenger: Enclosed Racks.
End User:
Procurement sophistication varies sharply by sector maturity, with compliance-heavy segments commanding specification premiums.
- Telecommunications:Mature buyers with standardized rack footprints. Telstra and NBN Co facilities drive recurring replacement cycles across Sydney and Melbourne metro networks.
- BFSI:Risk-averse procurement favoring redundant power integration. Major banks in Sydney's CBD specify higher-density 42U configurations for trading floor proximity.
- Healthcare:TGA guidelines dictate climate-controlled storage racks. Hospital data centers in Victoria are expanding capacity for electronic health record digitization.
- Government:Fastest-expanding segment under digital sovereignty mandates. Federal agencies are consolidating into certified facilities with biometric rack access requirements.
Telecommunications dominates current procurement volume. Government deployments are climbing fastest on security-driven refresh cycles.
Size:
Height specifications track density economics, with taller frames capturing share as floor space costs rise.
- 1U:Single-unit height for network appliances and patch panels. Edge computing nodes in Brisbane's commercial districts specify these for shallow-depth equipment.
- 2U:Expanded vertical space for storage arrays and blade chassis. Mid-tier colocation in Adelaide deploys these for mixed workload flexibility.
- 3U:Intermediate height for power distribution and cooling integration. Niche adoption in retrofitted facilities with ceiling height constraints.
- 42U:Full-height standard for hyperscale server deployment. New South Wales hyperscale builds are standardizing on this specification for maximum compute density per square meter.
42U frames anchor greenfield construction. 1U and 2U variants hold ground in distributed edge expansion.
Power Rating:
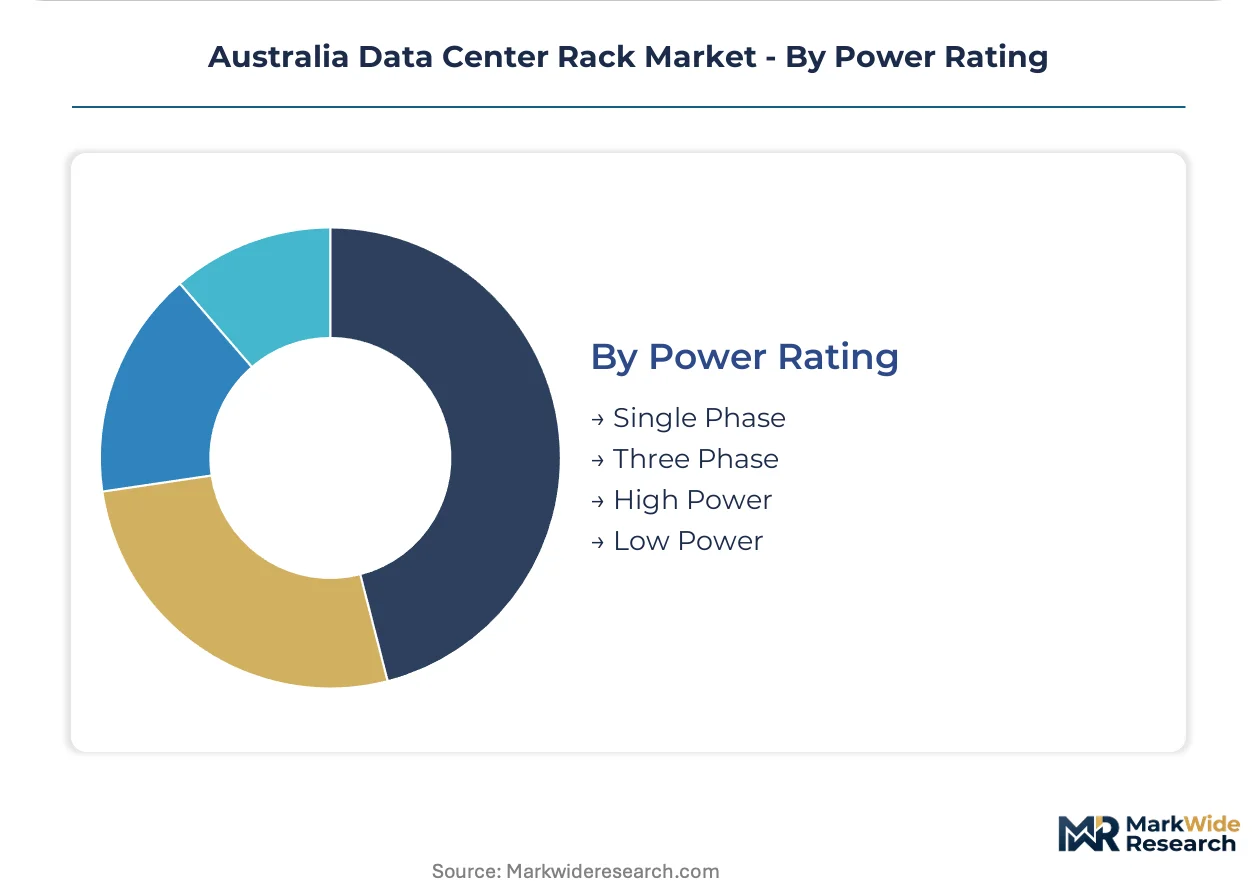
Electrical configuration splits between legacy single-phase branch circuits and three-phase infrastructure for high-density zones.
- Single Phase:Standard 240V residential-derived distribution. Small enterprise data centers in Hobart and Darwin retain this for compatibility with existing electrical infrastructure.
- Three Phase:Industrial-grade 415V power for high-density racks. Melbourne hyperscale facilities mandate this for GPU-intensive AI training clusters exceeding 30kW per rack.
- High Power:Dedicated circuits above 10kW per rack. Emerging specification for liquid-cooled deployments in Sydney's AI-focused data centers.
- Low Power:Sub-3kW configurations for network and storage equipment. Dominates rack edge and telecommunications exchange environments.
Three Phase distribution leads new construction. High Power specifications are gaining traction fastest on AI workload density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne anchor Australian data center rack demand through concentrated hyperscale construction. State-level procurement patterns diverge sharply between established metro clusters and emerging secondary markets.
New South Wales
Hyperscale cloud providers drive rack deployment intensity across Sydney's Western Sydney Aerotropolis and Macquarie Park corridors. The state's Critical Infrastructure Protection Act enforcement by the Department of Home Affairs mandates biometric access control specifications for government-adjacent facilities. Defense and federal agency consolidation into certified Canberra-connected sites is accelerating enclosed rack refresh cycles.
Victoria
Melbourne's Docklands and Fishermans Bend precincts attract competing colocation operators synchronizing rack procurement through master service agreements. AS/NZS 3000 electrical certification requirements extend delivery timelines for three-phase power distribution systems. GPU-intensive AI training clusters exceeding 30kW per rack are standardizing on high-density 42U configurations.
Queensland
Brisbane's commercial districts and regional bank branches sustain demand for compact 1U and wall-mounted edge rack variants. The state's tropical climate conditions favor precision-engineered enclosure systems with enhanced dust filtration. Emerging data center investment in Fortitude Valley is creating first-mover positioning opportunities for regional colocation operators.
Western Australia
Perth's resource-sector data centers handle vibration-sensitive workloads requiring seismic-reinforced specialized rack configurations. Mining and energy company server rooms dominate procurement outside the capital. Underpenetration relative to eastern states creates expansion headroom for facility operators targeting LNG and offshore engineering digital infrastructure.
South Australia
Adelaide's mid-tier colocation market deploys 2U mixed-workload racks for flexibility across enterprise customer segments. The state's smaller scale constrains volume purchasing power compared to New South Wales and Victoria. Emerging space industry data requirements from the Australian Space Agency are stimulating niche demand for climate-controlled storage specifications.
Australia Data Center Rack Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cooling-integrated and intelligent rack architectures. The market exhibits moderate concentration with integrated infrastructure specialists competing against pure-play enclosure fabricators. Three archetypes dominate: full-stack power-cooling-rack integrators, precision enclosure specialists, and IT equipment vendors bundling rack infrastructure. Competitive maneuvering centers on multi-year supply contract consolidation and thermal engineering capability acquisition.
Among European-integrated infrastructure groups, Schneider Electric SE and Rittal GMBH & Co.KG exemplify contrasting strategic positions. Vertiv Group occupies a position bridging thermal management and rack solutions. These three anchors represent the dominant competitive formation, with IT hardware incumbents and electrical component suppliers contesting adjacent specification decisions.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Rittal GMBH & Co.KG |
| Vertiv Group |
| Dell Inc. |
| Hewlett Packard Enterprise |
| Legrand SA |
| Cisco Systems, Inc. |
| Eaton |
| Panduit Corp. |
| Others |
Pricing and Supply Chain Analysis
Certified installation technicians concentrated in Sydney and Melbourne create labor-cost differentials that widen pricing-tier spreads between premium enclosed-rack specifications and economy open-frame alternatives across Australian data center builds.
Pricing Analysis
Input-cost pass-through from steel and aluminum volatility is compressing margins for rack enclosure fabricators serving the Australian market. Three-tier pricing structure across premium, standard, and economy levels separates biometric-integrated enclosed cabinets from basic open-frame configurations, with certification grade under the Critical Infrastructure Protection Act driving premium tier separation. Price erosion runs through standard-tier open-frame racks as colocation providers consolidate procurement through master service agreements. Government and defense-adjacent facilities show least price sensitivity, while regional bank branches in Queensland demonstrate highest sensitivity to per-unit rack costs.
Supply Chain Analysis
Single-source vulnerability sits with Chinese steel and aluminum suppliers feeding Australian rack fabrication. Raw material dependencies center on cold-rolled steel for structural framing, aluminum extrusions for side panels, and copper busbars for power distribution systems. Supply chain risk from tariff exposure on imported metals is amplifying cost uncertainty for domestic integrators. Distribution runs through direct OEM relationships with hyperscale facility operators and master service agreements with colocation providers, bypassing traditional electrical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia data center rack market reads as a late-cycle quality story where the Critical Infrastructure Protection Act is redirecting procurement toward premium enclosed specifications with integrated access control.
For Market Incumbents: Extend thermal engineering capabilities into liquid-cooled rack integration to defend against modular containerized substitutes displacing traditional deployments. Deepen backward integration into power distribution manufacturing to capture AS/NZS 3000 certification bottlenecks as a margin lever. Consolidate master service agreement coverage across Melbourne's Docklands precinct before regional operators achieve volume scale. For New Entrants and Emerging Players: The Critical Infrastructure Protection Act in Australia opens a window for biometric rack access retrofit kits targeting Telstra and NBN Co legacy facility upgrades. Queensland and Western Australia present the most penetrable geographies given underpenetration relative to hyperscale construction clusters in New South Wales and Victoria. Lead with climate-engineered enclosure systems featuring enhanced dust filtration for tropical edge deployments in Brisbane commercial districts. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play enclosure fabricators lacking integrated power-cooling portfolios. Long-term viability hinges on thermal engineering capability ownership as AI workload density drives liquid cooling convergence. Target acquisition candidates with established AS/NZS 3000 certification pathways and existing relationships with Department of Home Affairs compliance officers. Monitor Climate Change Authority efficiency benchmark announcements as the inflection signal for cooling-integrated rack demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Integration | Direct-to-chip thermal engineering captures GPU-intensive AI training cluster specifications exceeding 30kW per rack in Sydney. |
| Biometric Access Retrofit | Rack-level authentication systems address Critical Infrastructure Protection Act mandates across Canberra-connected defense facilities. |
| Master Service Agreement Consolidation | Multi-year supply contracts with maintenance provisions concentrate purchasing power with Melbourne Docklands colocation operators. |
| Regional Geographic Expansion | First-mover positioning in Queensland and Western Australia exploits underpenetration relative to eastern hyperscale clusters. |
| Thermal Engineering Acquisition | Predictive AI-enabled temperature management capabilities compress thermal anomaly response times from minutes to seconds. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct the Australia data center rack market analysis. Primary fieldwork engaged data center facility operators, electrical contractors specializing in AS/NZS 3000 compliance, rack system procurement managers at hyperscale cloud providers, and Department of Home Affairs critical infrastructure security advisors. Secondary validation drew from Australian Bureau of Statistics construction activity data, Climate Change Authority energy efficiency publications, Department of Home Affairs regulatory guidance documents, and customs records for steel and aluminum import flows. Bottom-up rack deployment tallies by state were cross-checked against top-down facility construction pipeline estimates.
Segment-weighting approaches distributed total addressable market value across product architecture types, end-user verticals, height specifications, and power distribution configurations. The analytical framework modeled rack procurement intensity against hyperscale construction timelines, Critical Infrastructure Protection Act compliance deadlines, and TGA healthcare infrastructure guidelines. CAGRs were derived from slope analysis of annual deployment trajectories adjusted for raw material cost pass-through effects and master service agreement pricing compression. Forecast inputs incorporated electrical certification bottleneck durations and liquid cooling adoption curves for AI training workloads.
Revisions become necessary when Critical Infrastructure Protection Act enforcement intensity shifts, Climate Change Authority benchmarks accelerate, or raw material tariff structures materially alter import economics for steel and aluminum feedstocks. Forecasts reflect documented assumptions regarding hyperscale construction completion rates and government facility consolidation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Norway Data Center Rack Market