
 North America Eye Tracking Solutions Market | 2026-2036
North America Eye Tracking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
North America Eye Tracking Solutions Market Insights
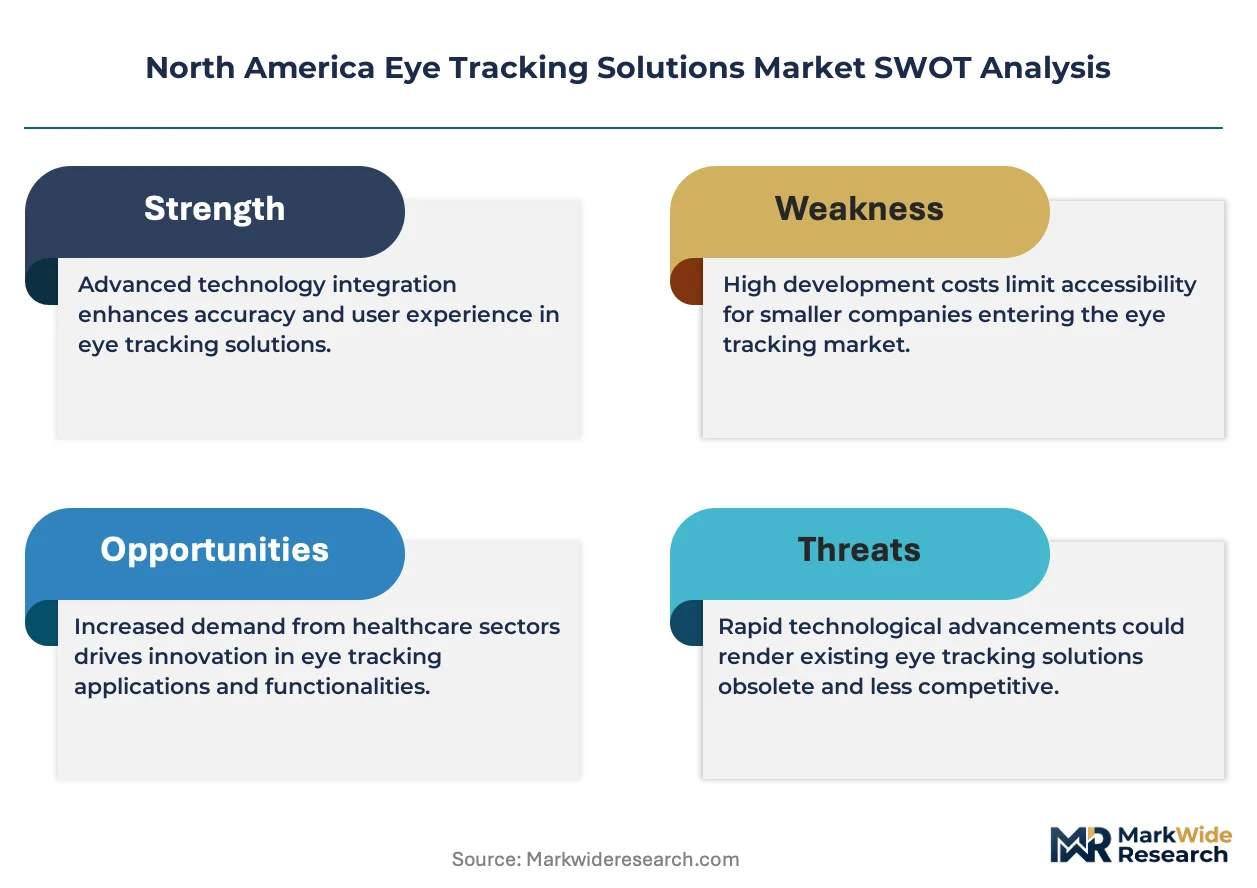
Subscription-based leasing and pay-per-study asset-light models is fragmenting capital barriers for mid-tier research institutions and regional healthcare networks. Tobii Technology leverages its hardware-software bundling to sustain recurring revenue streams across academic and clinical buyers. SR Research Ltd. anchors its position through specialized high-frequency sampling systems for neuroscience laboratories. Smart Eye Group competes by extending automotive-grade gaze algorithms into adjacent medical and consumer verticals.
Eye tracking solutions measure ocular movement, fixation duration, and pupillary response using infrared illumination coupled with high-resolution cameras sampling at 60 Hz to over 2000 Hz, serving applications from cognitive load assessment to driver drowsiness detection. Software Solutions and Integrated Systems dominate current deployment as healthcare providers and retailers seek turnkey platforms with embedded analytics rather than component-level hardware procurement. Mobile Solutions represent the fastest-expanding category, driven by smartphone-integrated gaze interfaces for accessibility and remote research protocols.
FDA software-as-a-medical-device frameworks and HIPAA privacy safeguards shape product architecture and data governance requirements for vendors serving U.S. healthcare end users. Health Canada and provincial privacy commissioners in Ontario and Quebec impose parallel certification and consent protocols that influence cross-border product standardization. Stakeholders must monitor evolving reimbursement codes for gaze-based diagnostic procedures and accessibility mandates from the U.S. Department of Veterans Affairs and provincial health authorities in Canada.
Market Dynamics
Software-as-a-medical-device FDA guidance and HIPAA data governance requirements are forcing vendors to rearchitect cloud-based eye tracking platforms around audit trails and encryption standards, compressing development timelines and elevating compliance costs for healthcare deployments.
Growth Catalysts
- Accessibility Mandates:The U.S. Department of Veterans Affairs procurement directives for gaze-based assistive communication devices are creating guaranteed demand pools for qualified vendors.
- Neuroscience Research Funding:NIH and NSF grants for cognitive load and neurological disorder studies are channeling institutional capital toward high-frequency eye tracking instrumentation.
- Automotive Algorithm Transfer:Driver monitoring systems validated under NHTSA distraction protocols are accelerating clinical adaptation of proven gaze estimation models.
Market Restraints
- Sensor Supply Concentration:Infrared camera modules and specialized CMOS sensors concentrate among East Asian contract manufacturers, exposing vendors to semiconductor allocation volatility.
- Calibration Complexity:Individual physiological variation in corneal curvature and pupil diameter limits universal calibration protocols, constraining plug-and-play deployment scalability.
- Cross-Border Data Friction:Divergent Health Canada and U.S. HIPAA consent frameworks impede seamless multi-site clinical trials requiring gaze data transfer between Ontario hospitals and U.S. research centers.
Strategic Opportunities
- Remote Research Protocols:Smartphone-integrated mobile eye tracking is digitizing accessibility studies and consumer behavior research outside traditional laboratory settings.
- Reimbursement Code Expansion:Emerging CPT codes for gaze-based diagnostic procedures in ophthalmology and neurology are creating billable pathways for clinical adoption.
- AI-Assisted Annotation:Machine learning automation of fixation and saccade classification is reducing per-study analyst labor costs for academic buyers.
Industry Challenges
- Specialized Optics Talent Scarcity:The intersection of ophthalmic physiology, infrared imaging, and real-time signal processing commands premium compensation, constraining vendor hiring pipelines.
- Legacy EHR Integration:Hospital IT departments face protracted API development cycles to embed gaze-derived biomarkers into Epic and Cerner workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Eye Tracking Solutions Market |
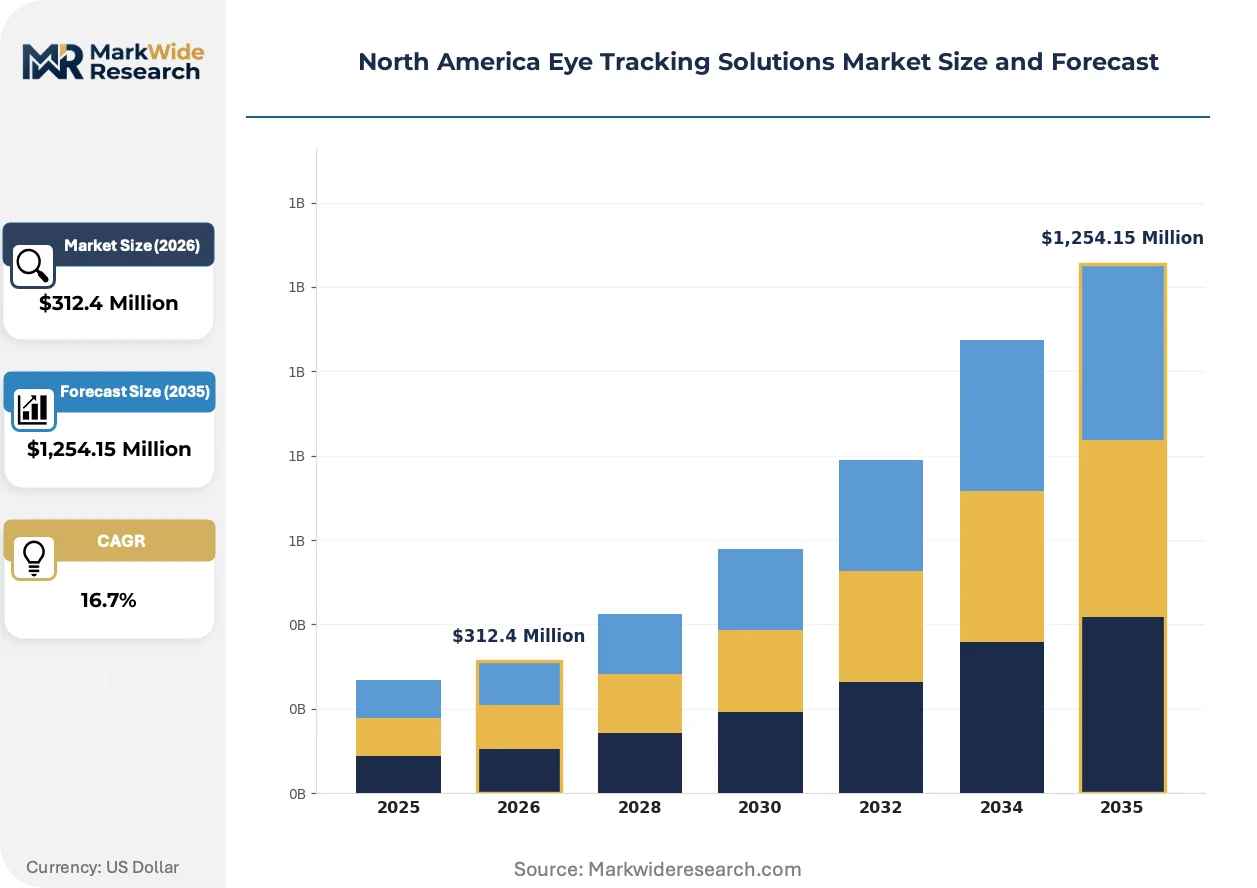
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,254.15 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Devices, Integrated Systems, Software Solutions, Mobile Solutions Application: Market Research, Healthcare, Gaming, Advertising End User: Retailers, Researchers, Healthcare Providers, Academics Technology: Cameras, Sensors, IR Tracking, Display Technologies |
| Companies Covered | Tobii Technology, SR Research Ltd., Seeing Machines, Smart Eye Group, EyeTech Digital Systems, Gazepoint Research, iMotions A/S, Mirametrix, Eyegaze, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Eye Tracking Solutions Market Trends and Innovations
Edge computing architectures and on-device inference are redistributing processing loads away from cloud dependencies, aligning eye tracking systems with stringent clinical data residency requirements while enabling real-time feedback loops.
Event-based vision sensors are digitizing ocular tracking by sampling only pixel-level changes rather than full frames, slashing bandwidth and power requirements for wearable and mobile deployments. Academic research hospitals in California's digital health cluster are piloting these neuromorphic cameras for continuous ambulatory monitoring. The technology is compressing hardware form factors to eyeglass-integrated scales previously unattainable with conventional CMOS arrays.
FDA software-as-a-medical-device premarket guidance is mandating algorithm change control protocols and clinical validation documentation for AI-driven gaze classification tools. Vendors must now maintain locked algorithm versions with traceable performance benchmarks across software updates. Healthcare providers in the Boston-Cambridge corridor are prioritizing suppliers with established 510(k) clearance pathways over experimental platforms.
Subscription-based equipment leasing is displacing capital purchase models among mid-tier research institutions and regional healthcare networks. Asset-light structures transfer obsolescence risk to vendors while preserving buyer operational flexibility. This pattern concentrates in California and Massachusetts markets where research funding cycles favor predictable operational expenditures over depreciable equipment assets.
North America Eye Tracking Solutions Market Segmentation
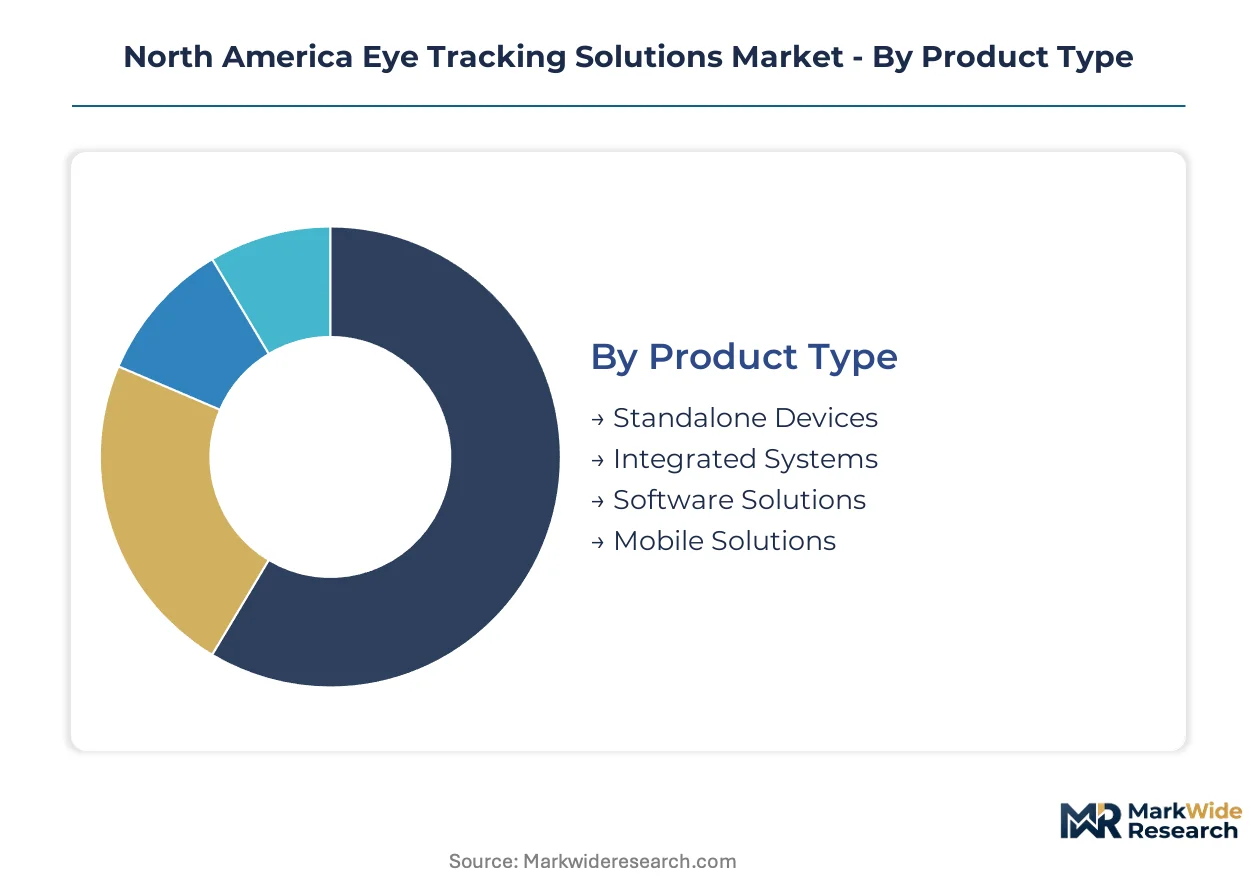
Eye tracking solutions fragment across hardware-software boundaries and use-case specificity, with procurement patterns diverging sharply between capital-intensive institutional buyers and subscription-oriented research networks. Understanding these segment mechanics reveals where pricing power concentrates and which technology trajectories command R&D investment.
Product Type:
Cost tier stratification separates turnkey platforms from component-level procurement, with integration depth determining buyer capital commitment and vendor recurring revenue potential.
- Standalone Devices:Self-contained hardware units with embedded processing deliver 60-500 Hz sampling for dedicated laboratory installations. Healthcare providers in the Boston-Cambridge corridor favor these for clinical diagnostic workflows requiring HIPAA-compliant local data residency.
- Integrated Systems:Bundled sensor-display combinations with pre-calibrated optics reduce deployment complexity for multi-site research programs. NIH-funded neuroscience laboratories concentrate demand here, prioritizing vendor-managed calibration protocols over in-house technical staffing.
- Software Solutions:Platform licenses for gaze analytics and visualization running on buyer-provisioned hardware. Mid-tier research institutions adopt these to preserve equipment flexibility while accessing algorithm updates.
- Mobile Solutions:Smartphone-integrated gaze interfaces leveraging front-facing cameras and edge inference. California's digital health cluster pilots these for remote accessibility studies outside traditional laboratory settings.
Integrated Systems command the established base. The steepest expansion runs through Mobile Solutions.
Application:
End-use specialization drives divergent performance specifications, with medical-grade validation requirements creating certification moats around clinical deployments.
- Healthcare:Diagnostic gaze assessment for neurological disorders and assistive communication for motor-impaired patients. FDA software-as-a-medical-device frameworks mandate locked algorithm versions with traceable performance benchmarks for U.S. hospital deployments.
- Market Research:Consumer attention mapping for packaging and shelf-layout optimization. Retailers concentrate procurement in California and Massachusetts where research funding cycles favor predictable operational expenditures.
- Gaming:Foveated rendering and gaze-contingent content adaptation for immersive experiences. Performance demands here emphasize low-latency estimation over medical-grade precision.
- Advertising:Attention measurement for digital and out-of-home media effectiveness. Privacy constraints under evolving U.S. state consumer protection laws constrain cross-platform data fusion.
Healthcare commands the established base. The steepest expansion runs through Market Research.
End User:
Customer type determines procurement modality, with institutional buyers favoring capital purchases and distributed research networks migrating toward subscription structures.
- Healthcare Providers:Hospital systems and specialty clinics deploying gaze diagnostics under emerging CPT reimbursement codes. The U.S. Department of Veterans Affairs procurement directives create guaranteed demand pools for qualified assistive communication vendors.
- Researchers:Academic laboratories and contract research organizations conducting cognitive load and neurological studies. NIH and NSF grants channel institutional capital toward high-frequency instrumentation with open data export capabilities.
- Retailers:Consumer brands and retail chains purchasing attention analytics for merchandising decisions. These buyers prioritize turnkey reporting dashboards over raw gaze data access.
- Academics:University departments with intermittent funding cycles favoring equipment leasing to transfer obsolescence risk. Subscription structures concentrate in California and Massachusetts markets.
Healthcare Providers command the established base. The steepest expansion runs through Researchers.
Technology:
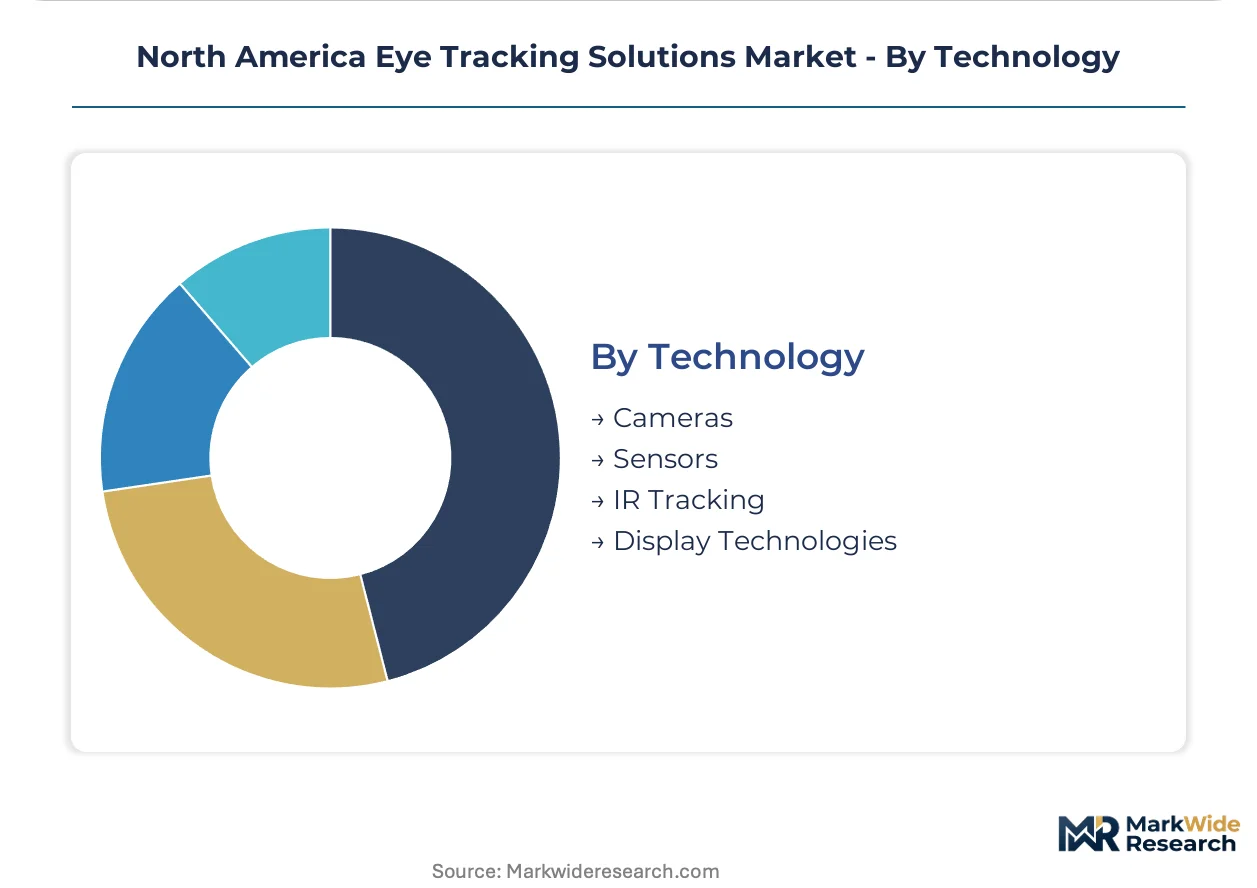
Hardware component selection determines sampling fidelity, power budget, and form factor constraints, with sensor architecture choices propagating through system cost and calibration requirements.
- IR Tracking:Infrared illumination paired with corneal reflection detection delivers sub-degree angular precision for clinical and research applications. FDA guidance on optical radiation exposure limits shapes emitter specification for U.S. medical devices.
- Cameras:High-resolution CMOS and emerging event-based vision sensors capturing ocular dynamics at 60-2000+ Hz. Academic research hospitals in California pilot neuromorphic cameras for continuous ambulatory monitoring.
- Sensors:Specialized photodetectors and microelectromechanical components for pupil tracking and head pose estimation. Supply concentrates among East Asian contract manufacturers, exposing vendors to semiconductor allocation volatility.
- Display Technologies:Gaze-contingent refresh modulation and foveated rendering pipelines for bandwidth-efficient visual output. Gaming and virtual reality applications drive development here.
IR Tracking commands the established base. The steepest expansion runs through Cameras.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American eye tracking solutions flow predominantly through U.S. import channels, with Canadian research institutions and Mexican automotive assembly plants serving as secondary demand nodes. The regional trade balance tilts toward hardware component imports from East Asian sensor foundries, offset by software and analytics service exports from U.S. technology clusters.
United States
FDA software-as-a-medical-device premarket pathways and HIPAA encryption mandates are compressing vendor development cycles for healthcare deployments. NIH neuroscience grant funding channels institutional capital toward high-frequency instrumentation for cognitive load studies. California's digital health cluster and the Boston-Cambridge biotech corridor concentrate pilot programs for gaze-based diagnostic workflows.
Canada
Health Canada and provincial privacy commissioners in Ontario and Quebec impose parallel certification requirements that influence cross-border product standardization for multi-site clinical trials. Federal research councils fund accessibility technology development for motor-impaired populations. Toronto-Waterloo corridor institutions pilot smartphone-integrated gaze interfaces for remote research protocols outside laboratory settings.
Mexico
Automotive assembly plants serving U.S. OEMs are adopting driver monitoring systems validated under NHTSA distraction protocols for export-bound vehicle production. Federal economic development programs in Nuevo León and Baja California attract component testing facilities for North American supply chain integration. Guadalajara's electronics manufacturing cluster hosts calibration and quality assurance operations for infrared sensor modules.
North America Eye Tracking Solutions Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying specialized optics and inference engines. The vendor base stratifies between turnkey healthcare platform providers and modular research instrumentation suppliers. Three archetypes dominate: hardware-software bundlers sustaining recurring revenue through subscription leasing, high-frequency sampling specialists serving neuroscience laboratories, and automotive algorithm developers extending gaze estimation into adjacent medical verticals. Competitive positioning hinges on FDA 510(k) clearance pathways and strategic partnerships with academic medical centers for clinical validation.
Within the hardware-software bundler tier, Tobii Technology exemplifies platform integration across academic and clinical buyer segments. SR Research Ltd. occupies a specialized position through high-frequency instrumentation for neuroscience applications. Smart Eye Group represents automotive algorithm transfer strategies, extending driver monitoring gaze estimation into healthcare and consumer verticals.
| Leading Market Players |
|---|
| Tobii Technology |
| SR Research Ltd. |
| Seeing Machines |
| Smart Eye Group |
| EyeTech Digital Systems |
| Gazepoint Research |
| iMotions A/S |
| Mirametrix |
| Eyegaze |
| Others |
Pricing and Supply Chain Analysis
Semiconductor allocation volatility among East Asian contract manufacturers compresses both tiered pricing spreads and supply chain redundancy, forcing vendors to absorb component cost spikes or sacrifice margin on mid-market integrated systems.
Pricing Analysis
Healthcare providers anchor subscription-based pricing structures across the North American market. Three-tier pricing stratifies across FDA-cleared medical devices, research-grade instrumentation, and consumer-accessible mobile solutions. Price differentiation hinges on certification tier and sampling frequency specifications. Cost compression in research-grade tiers intensifies because NIH funding cycles favor predictable operational expenditures over capital purchases. Academic laboratories exhibit the highest price sensitivity; hospital systems with emerging CPT reimbursement codes demonstrate the lowest.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Foxconn, Quanta Computer, and specialized EMS providers in Taiwan and mainland China. Infrared camera modules, specialized CMOS sensors, and neuromorphic vision chips draw from these concentrated production hubs. Single-source vulnerability runs through East Asian sensor foundries exposed to geopolitical trade friction. Distribution runs through direct vendor sales for healthcare deployments and academic distributors for research instrumentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of ophthalmic physiology, infrared imaging, and real-time signal processing commands premium compensation that constrains vendor hiring pipelines, creating persistent capability bottlenecks across hardware and algorithm development teams.
For Market Incumbents: Pre-empt margin erosion in research-grade instrumentation by securing multi-year NIH grant-funded procurement contracts before subscription-based competitors consolidate mid-tier accounts. Deepen backward integration into specialized infrared emitter manufacturing to reduce exposure to East Asian semiconductor allocation volatility. FDA 510(k) clearance maintenance represents the priority defensive lever against automotive-algorithm entrants lacking clinical validation pathways. For New Entrants and Emerging Players: Mid-market regional healthcare networks in the U.S. Southeast and Canadian Prairie provinces represent the most penetrable entry point, as these buyers face capital constraints that subscription leasing addresses directly. Smartphone-integrated mobile eye tracking for remote accessibility studies offers secondary white-space expansion outside laboratory settings. Go-to-market execution should prioritize partnerships with Veterans Affairs procurement channels to access guaranteed demand pools. For Investors and Strategic Acquirers: FDA software-as-a-medical-device premarket guidance expansion reshapes the acquisition landscape by elevating regulatory compliance capabilities above pure algorithm performance. Long-term viability favors platforms with established 510(k) clearance pathways and hospital EHR integration contracts over experimental hardware. Acquisition target archetypes include neuromorphic camera specialists and clinical annotation automation providers. The signal to watch is emerging CPT code finalization for gaze-based diagnostic procedures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Locked algorithm versions with traceable benchmarks satisfy premarket requirements for clinical deployments. |
| Hospital System Partnership | Epic and Cerner workflow integration embeds gaze-derived biomarkers into established diagnostic protocols. |
| Neuromorphic Camera Integration | Event-based vision sensors slash power requirements for wearable continuous monitoring applications. |
| Reimbursement Strategy Development | CPT code advocacy creates billable pathways for ophthalmology and neurology diagnostic procedures. |
| Academic Medical Center Collaboration | California and Massachusetts research clusters provide clinical validation credibility for regulatory submissions. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and neuroscience laboratory directors and refined through secondary validation against FDA 510(k) filings, Health Canada device licenses, NIH RePORTER grant databases, and hospital procurement records. Bottom-up instrumentation demand estimates triangulated against top-down healthcare IT expenditure forecasts.
Demand-supply balance across the analysis window incorporated modeled segmentation across product type, application, end user, and technology dimensions with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to validated baseline estimates. Forecast inputs included NIH neuroscience funding trajectories and NHTSA driver monitoring system adoption curves.
Practitioners should monitor FDA guidance updates on software-as-a-medical-device algorithm change control and Health Canada provincial privacy commissioner rulings for early signals of regulatory friction. Forecasts reflect assumptions about reimbursement code expansion and semiconductor allocation normalization. Quarterly review of CPT code proposal statuses and East Asian foundry utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Real Time Location System Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Automated Weather Observation System Market
Sensors
Asia Pacific Container Monitoring Market
Sensors
Lidar in Mapping Market
Sensors
Eye Tracking Solutions Market
Sensors
Digital Direction Finder Market
Sensors
Alcohol Sensor Market
Sensors
Digital Olfaction Products Market
Sensors
RFID Smart Cabinet Market
Sensors
Vision Positioning System Market
Sensors
Underground Service Locator Market
Sensors
Transport Monitoring System Market
Sensors
Conveyor Monitoring Market
Sensors
Residential Water Leak Detection System Market