
 Micro Location Technology Market | 2026-2036
Micro Location Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Location Technology Market Intelligence
A widening capability gap between infrastructure-heavy and software-centric vendors is unwinding competitive stability in micro location technology. Cisco Systems Inc leverages its installed networking base to bundle beacon management with enterprise Wi-Fi refresh cycles. Zebra Technologies anchors its position through ruggedized hardware purpose-built for warehouse and manufacturing floor conditions. Estimote competes as a design-forward specialist targeting mid-market retail deployments with lower IT overhead.
Micro location technology encompasses short-range positioning systems that compute spatial coordinates through time-of-flight measurements, received signal strength indicators, or angle-of-arrival algorithms, typically achieving sub-meter accuracy in indoor environments where GPS signals cannot penetrate. Ultra-Wideband pulses at 500 MHz bandwidth enable centimeter-level precision for asset tracking in high-density storage facilities. Bluetooth Beacon deployments dominate retail analytics and location-based marketing due to minimal infrastructure cost and decade-long battery life in broadcast-only configurations. Wi-Fi RTT is gaining structural momentum in smart buildings where facility managers can repurpose existing access point footprints without dedicated beacon hardware.
The FCC governs Ultra-Wideband power spectral density limits under Part 15 rules, directly constraining transmission range and dictating antenna design trade-offs for US market access. CE marking requirements under the EU Radio Equipment Directive mandate interoperability testing that shapes vendor certification roadmaps for European smart building and hospital deployments. Stakeholders must weigh spectrum allocation divergence between jurisdictions when selecting radio technologies, as backward compatibility commitments will lock in architecture choices across multi-year deployment horizons.
Market Dynamics
Ultra-Wideband chip miniaturization from semiconductor process advances is collapsing hardware cost barriers and redistributing competitive advantage toward software-layer vendors. This technological inflection is compressing deployment timelines for indoor positioning systems while forcing infrastructure-heavy incumbents to defend installed-base relationships against leaner entrants.
Growth Catalysts
- Industrial automation clusters:German automotive manufacturers are deploying Ultra-Wideband for centimeter-level asset tracking across high-density production lines. Real-time positioning enables dynamic workflow reconfiguration without physical infrastructure changes.
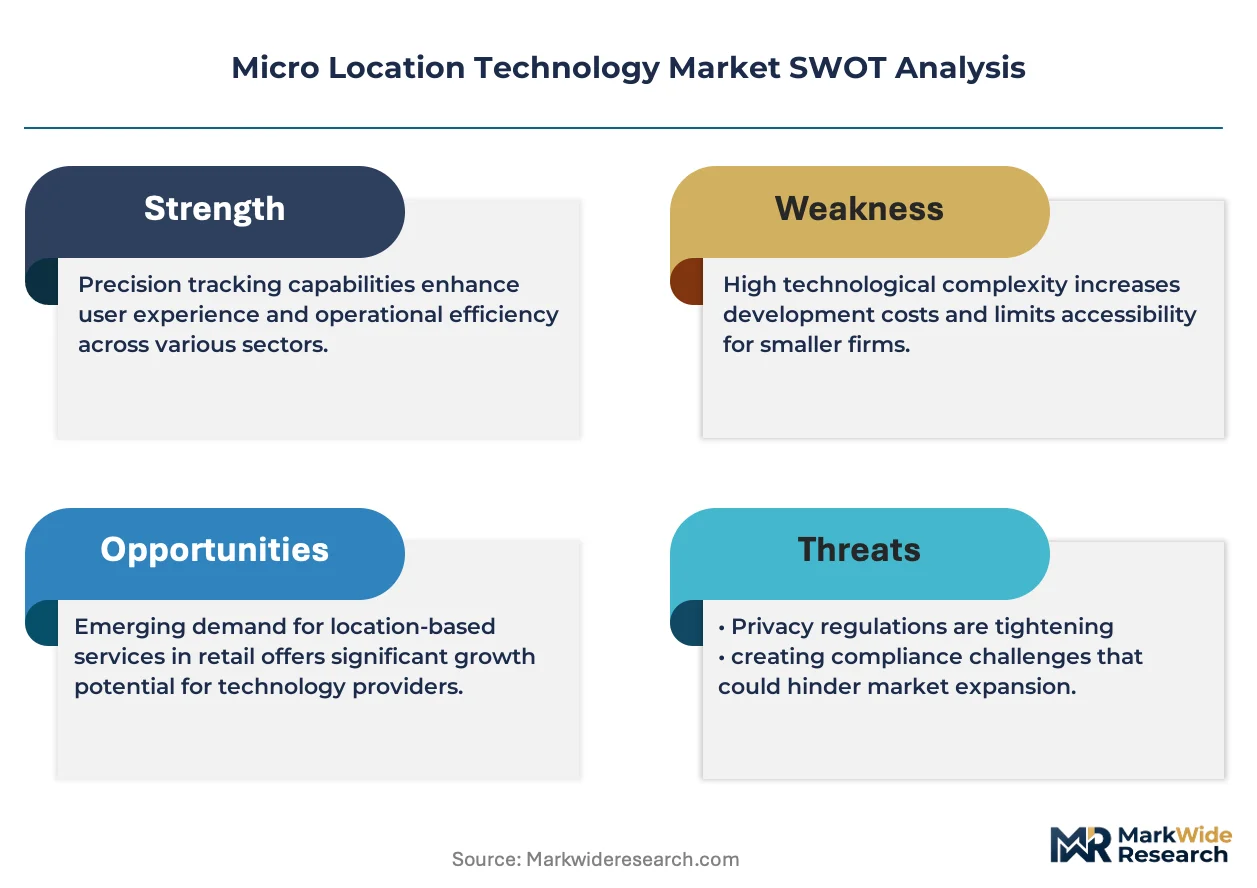
- FCC Part 15 rules:US power spectral density limits for Ultra-Wideband transmissions have stabilized, giving hardware vendors regulatory certainty for antenna design roadmaps. Predictable compliance frameworks accelerate product development cycles.
- Warehouse inventory positioning:Third-party logistics operators are mandating sub-meter location accuracy for automated retrieval systems. Bluetooth Beacon networks provide decade-long battery life for broadcast-only tracking configurations.
Market Restraints
- Silicon supply concentration:Advanced node semiconductor fabrication for Ultra-Wideband chipsets concentrates among Taiwan-based foundries. Geographic concentration risk constrains vendor scaling flexibility during demand spikes.
- CE marking complexity:EU Radio Equipment Directive interoperability testing mandates multi-vendor certification roadmaps. Compliance timelines extend market entry delays for specialized hardware entrants.
- Wi-Fi RTT substitution:Existing access point infrastructure in smart buildings enables positioning without dedicated beacon hardware. Facility managers face lower incremental costs for repurposed versus new deployments.
Strategic Opportunities
- Healthcare asset tracking:German hospital networks are piloting Ultra-Wideband for mobile medical equipment location. Regulatory pressure on patient flow efficiency creates procurement urgency for real-time systems.
- Retail analytics convergence:Bluetooth Beacon deployments are integrating with computer vision for unified customer journey mapping. Technology convergence opens new service revenue streams for analytics vendors.
- EU Green Deal procurement:Public building renovation mandates in member states are incorporating smart building positioning as efficiency enablers. Regulatory tailwind accelerates specification inclusion in tender documents.
Industry Challenges
- RF engineering talent scarcity:Ultra-Wideband antenna design requires specialized expertise in time-of-flight calibration. Vendors compete for limited pools of experienced hardware architects.
- Legacy system integration:Warehouse management software from established providers uses proprietary protocols. API fragmentation forces custom middleware development for unified positioning data streams.
- Multi-jurisdiction certification:Spectrum allocation divergence between FCC, CE marking, and Japanese radio law requires parallel testing tracks. Compliance resource demands strain mid-cap vendor budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Location Technology Market |
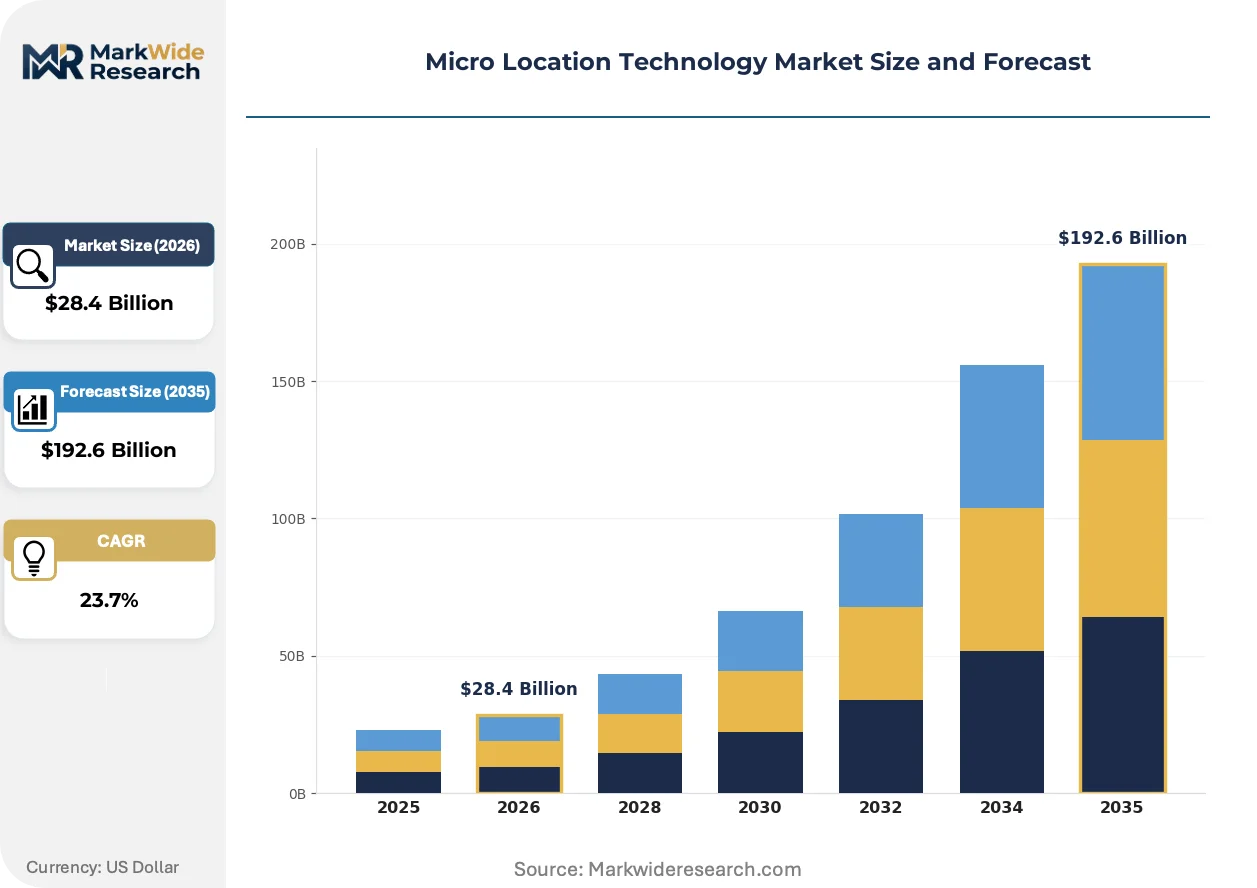
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $192.6 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth Beacon, NFC, Wi-Fi RTT, Ultra-Wideband Application: Retail Analytics, Asset Tracking, Indoor Navigation, Location-Based Marketing End User: Retail Stores, Warehouses, Hospitals, Smart Buildings Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Aruba Networks, Centrak, Cisco Systems Inc, Situm Technologies SL, Ubisense Group, Siemens AG, Estimote, Proximi.io, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Location Technology Market Strategic Shifts & Innovations
Positioning technology architectures are bifurcating between infrastructure-heavy precision systems and software-centric overlay approaches. This divergence is reshaping vendor business models and buyer procurement criteria across industrial and commercial deployments.
Ultra-Wideband pulse transmission is supplanting Bluetooth Beacon received signal strength indicators in high-density warehouse environments. German automotive suppliers are adopting centimeter-level systems for automated guided vehicle coordination. The technology is supplanting legacy barcode-based location verification, compressing implementation timelines from months to weeks.
CE marking requirements under the EU Radio Equipment Directive are mandating interoperability testing for multi-vendor deployments. European smart building integrators must certify cross-manufacturer beacon compatibility before project handover. Hospital networks in Germany are responding by consolidating vendor lists to reduce certification complexity.
Facility managers are unbundling hardware procurement from analytics software subscriptions. Smart building operators in the US are demanding API-first positioning layers that integrate with existing enterprise systems. This purchasing pattern shift is most visible in commercial real estate portfolios where IT standardization reduces vendor lock-in risk.
Micro Location Technology Market Segmentation
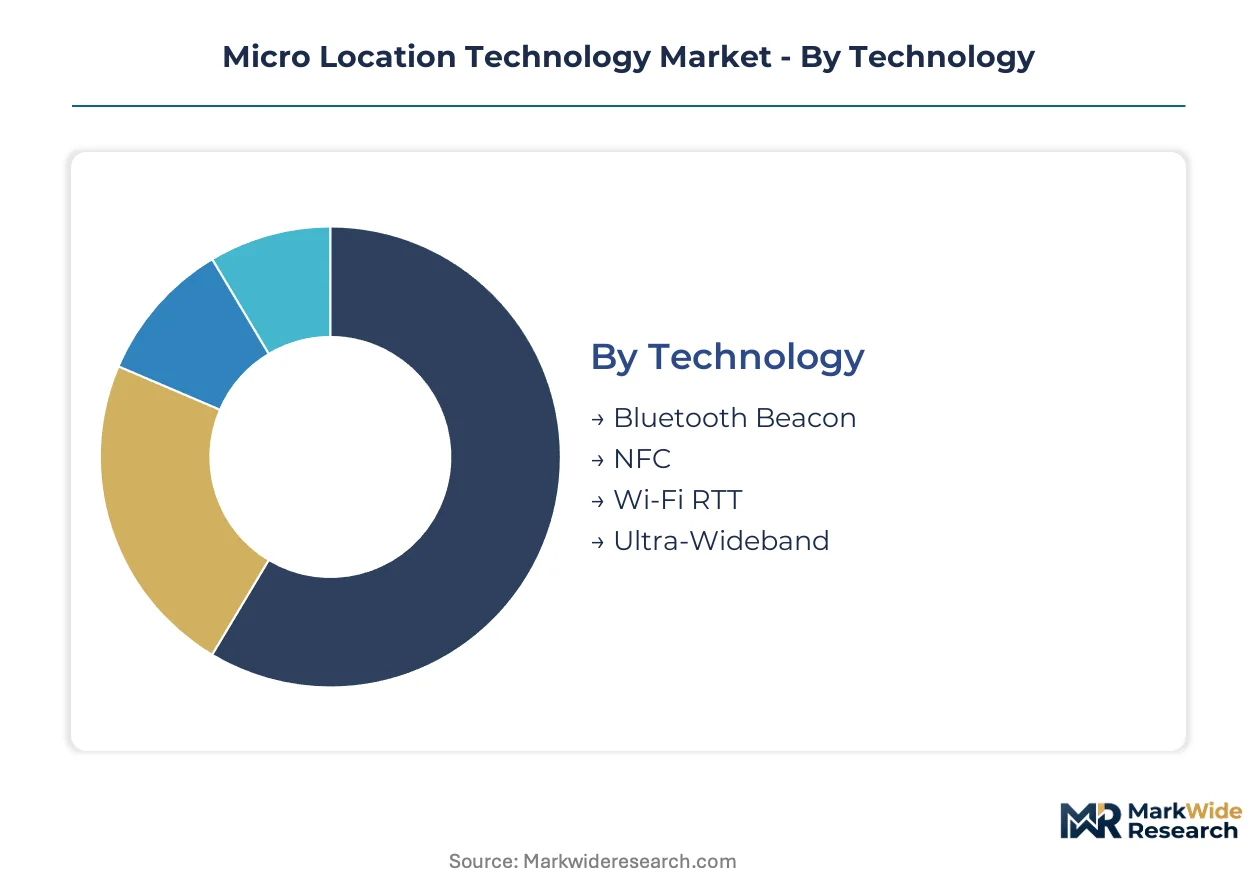
Segmentation in micro location technology reveals how deployment complexity, accuracy requirements, and infrastructure maturity vary sharply across use cases. Buyers select technology stacks based on whether they need centimeter-level precision or room-level granularity, with cost and regulatory constraints further narrowing options.
Technology:
Ultra-Wideband and Bluetooth Beacon deployments concentrate in Germany's automotive and industrial clusters, while Wi-Fi RTT spreads through US smart building retrofits. NFC remains domestically concentrated in payment and access control applications with limited export traction.
- Ultra-Wideband:Pulse transmission at 500 MHz bandwidth achieves centimeter-level precision through time-of-flight measurements. German automotive manufacturers deploy this for automated guided vehicle coordination in high-density production lines where collision avoidance demands sub-10cm accuracy.
- Bluetooth Beacon:Broadcast-only configurations using received signal strength indicators deliver room-level positioning with decade-long battery life. US third-party logistics operators mandate these networks for warehouse inventory positioning where infrastructure cost minimization outweighs precision requirements.
- NFC:Near-field communication enables tap-to-confirm interactions across payment terminals and access control readers. Deployment concentrates in retail point-of-sale and corporate badge systems with limited indoor positioning functionality.
- Wi-Fi RTT:Round-trip time measurements repurpose existing access point infrastructure for meter-level positioning. Facility managers in US commercial real estate favor this for smart building deployments where dedicated beacon hardware would duplicate capital investment.
Bluetooth Beacon holds the largest share; momentum sits with Ultra-Wideband.
Application:
Cost tiering separates applications by infrastructure intensity, with asset tracking commanding premium hardware spending while location-based marketing minimizes upfront deployment.
- Asset Tracking:Real-time location systems monitor mobile equipment through continuous coordinate updates. German hospital networks pilot Ultra-Wideband for medical device location under regulatory pressure to improve patient flow efficiency.
- Indoor Navigation:Wayfinding applications guide users through complex built environments using proximity-triggered directions. Airport and shopping mall operators in France deploy these systems to reduce congestion and improve visitor throughput metrics.
- Retail Analytics:Footfall pattern analysis correlates customer dwell time with purchase conversion. Mid-market retailers favor Bluetooth Beacon deployments for lower IT overhead compared to infrastructure-heavy alternatives.
- Location-Based Marketing:Proximity-triggered promotions deliver targeted content when shoppers enter defined geofences. Broadcast-only beacon configurations minimize infrastructure cost while enabling decade-long operational lifespans.
Asset Tracking commands premium pricing; Retail Analytics is expanding most quickly through mid-market penetration.
End User:
Customer type differentiation separates buyers by procurement sophistication, with warehouses demanding API-first integration while retail stores prioritize turnkey deployment.
- Warehouses:Third-party logistics operators mandate sub-meter accuracy for automated retrieval systems. Real-time inventory positioning enables dynamic workflow reconfiguration without physical infrastructure changes across German distribution hubs.
- Smart Buildings:Facility managers unbundle hardware procurement from analytics software subscriptions. US commercial real estate portfolios demand API-first positioning layers that integrate with existing enterprise systems.
- Hospitals:German hospital networks pilot Ultra-Wideband for mobile medical equipment location. Regulatory pressure on patient flow efficiency creates procurement urgency for real-time systems that reduce equipment search time.
- Retail Stores:Mid-market deployments favor design-forward beacon solutions with minimal IT overhead. Bluetooth Beacon networks provide footfall analytics without dedicated technical staff for infrastructure maintenance.
Warehouses dominate volume; Smart Buildings show the steepest expansion trajectory through retrofit demand.
Deployment:
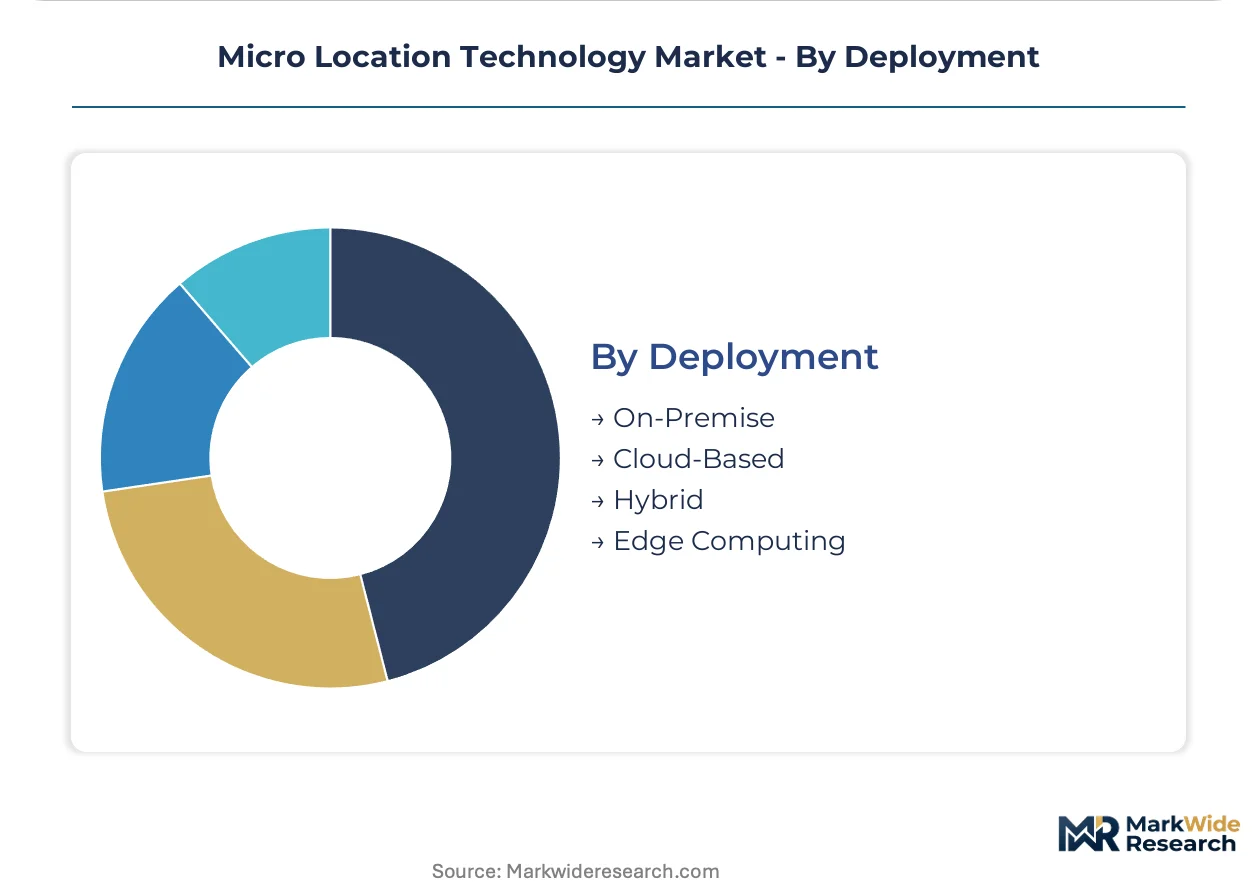
Volume concentration favors cloud-based architectures for multi-site management, while edge computing addresses latency-sensitive industrial applications.
- Cloud-Based:Centralized data processing enables unified management across distributed beacon networks. Retail chains with hundreds of locations favor this model for consistent analytics dashboards and remote configuration updates.
- Edge Computing:Local processing reduces latency for time-critical positioning decisions. German automotive production lines deploy edge architectures to coordinate automated guided vehicles without cloud dependency.
- Hybrid:Split architectures process time-sensitive decisions locally while aggregating analytics centrally. Smart building operators use this to balance real-time responsiveness with enterprise-wide reporting requirements.
- On-Premise:Fully localized deployments satisfy data residency requirements in sensitive environments. Hospital networks in Germany select this model to maintain patient data within facility-controlled infrastructure.
Cloud-Based captures the largest installed base; Edge Computing is gaining share fastest through industrial automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany absorb premium pricing for centimeter-level precision, while US facility managers prioritize infrastructure reuse over hardware spend. Warehouse operators in emerging markets remain price-sensitive, delaying Ultra-Wideband adoption until silicon costs decline further.
United States
Smart building retrofits drive Wi-Fi RTT adoption across commercial real estate portfolios. FCC Part 15 rules provide regulatory certainty for Ultra-Wideband hardware roadmaps. Facility managers in Chicago and Dallas unbundle hardware procurement from software subscriptions to reduce vendor lock-in.
Germany
Automotive manufacturers deploy Ultra-Wideband for automated guided vehicle coordination in high-density production lines. CE marking requirements under the EU Radio Equipment Directive mandate interoperability testing. Industrial clusters in Stuttgart and Munich pilot real-time positioning for dynamic workflow reconfiguration.
China
MIIT spectrum allocations shape vendor certification priorities for indoor positioning hardware. Semiconductor foundries concentrate advanced node fabrication for Ultra-Wideband chipsets. Manufacturing hubs in Shenzhen and Shanghai integrate micro location systems for warehouse automation at scale.
Japan
METI industrial digitization programs subsidize precision positioning deployments in smart factories. JIS standards govern interoperability testing for multi-vendor beacon networks. Automotive suppliers in Nagoya adopt centimeter-level systems for collision avoidance in dense production environments.
United Kingdom
Commercial real estate operators mandate API-first positioning layers for enterprise system integration. GDPR compliance requirements influence data residency decisions in healthcare deployments. London facility managers repurpose existing Wi-Fi infrastructure to minimize incremental capital expenditure.
Micro Location Technology Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive dynamics across the micro location technology landscape. Infrastructure-heavy incumbents defend installed-base relationships through bundled networking hardware, while software-centric entrants compress deployment timelines with leaner overlay approaches. Three strategic archetypes dominate: networking equipment conglomerates, ruggedized hardware specialists, and design-forward beacon vendors. Dominant competitive moves include strategic partnerships for interoperability certification and geographic expansion into German industrial automation clusters.
Within the networking infrastructure tier, Cisco Systems Inc and Aruba Networks exemplify players leveraging enterprise Wi-Fi refresh cycles for beacon management bundling. Zebra Technologies anchors the ruggedized hardware segment with purpose-built devices for warehouse floor conditions. Estimote occupies a position among design-forward specialists targeting mid-market retail with minimal IT overhead requirements.
| Leading Market Players |
|---|
| Aruba Networks |
| Centrak |
| Cisco Systems Inc |
| Situm Technologies SL |
| Ubisense Group |
| Siemens AG |
| Estimote |
| Proximi.io |
| Zebra Technologies |
| Others |
Cost & Logistics Intelligence
Twenty-six-week lead times for FCC-certified Ultra-Wideband modules concentrate pricing power with Taiwan-based foundry partners, while German automotive buyers absorb premiums for CE-marked interoperability. Inventory buffers at distribution hubs in Stuttgart and Dallas shape working capital requirements across tiered procurement contracts.
Pricing Analysis
Software subscription tiers and multi-year service contracts drive lifetime value beyond initial hardware margins. Three-tier pricing structure across precision-grade Ultra-Wideband, standard Bluetooth Beacon, and economy Wi-Fi RTT configurations reflects accuracy certification levels and antenna complexity. Cost compression in entry-level beacon hardware intensifies as semiconductor process advances reduce chip footprints. Third-party logistics operators exhibit highest price sensitivity, while German hospital networks prioritize interoperability certification over unit cost.
Supply Chain Analysis
Strategic stockpiling of certified radio modules dominates procurement patterns ahead of CE marking renewal cycles. Advanced node fabrication concentrates in Taiwan, South Korea, and China, with assembly and test operations spreading across Malaysia and Vietnam. Raw material dependencies span gallium arsenide substrates, ceramic antenna substrates, and lithium primary cells for decade-long beacon deployments. Single-source vulnerability in Taiwan-based foundry capacity threatens scaling flexibility during demand spikes. Distribution runs through authorized component distributors serving system integrators in Stuttgart, Chicago, and Shenzhen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized RF engineering talent pools constrain vendor scaling velocity, with antenna calibration expertise concentrated among a narrow cohort of hardware architects. This scarcity gap separates infrastructure-heavy incumbents from software-centric entrants competing on deployment speed.
For Market Incumbents: Consolidate certification roadmaps to reduce multi-jurisdiction testing overhead, leveraging existing FCC and CE marking investments as competitive moats against leaner entrants. Acquire specialized antenna design teams in Germany or Japan to close RF engineering gaps before talent scarcity intensifies pricing for hardware architecture resources. For New Entrants and Emerging Players: API-first integration services represent an underserved layer where Cisco and Zebra bundle hardware with proprietary analytics, creating openings for independent software vendors. Target US commercial real estate portfolios with unbundled positioning layers that integrate with existing enterprise Wi-Fi infrastructure. Pursue channel partnerships with smart building integrators in Chicago and Dallas to bypass direct hardware competition. For Investors and Strategic Acquirers: Carve-out targets emerge from networking conglomerates divesting non-core indoor positioning divisions amid portfolio rationalization. Long-term viability hinges on software-layer recurring revenue rather than hardware transaction margins. Monitor CE marking interoperability test completion rates as inflection indicators for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | CE marking compliance under EU Radio Equipment Directive accelerates hospital procurement cycles in Germany. |
| RF Engineering Talent Acquisition | Specialized antenna design teams in Stuttgart and Nagoya command premium valuations amid scarcity. |
| API-First Platform Development | Unbundled software layers integrate with Cisco Wi-Fi infrastructure to reduce vendor lock-in risk. |
| Geographic Expansion into German Industrial Clusters | Automotive manufacturers in Munich pilot centimeter-level systems for automated guided vehicle coordination. |
| Strategic Partnership with Taiwan Foundries | Advanced node capacity commitments secure Ultra-Wideband chipset supply amid silicon concentration risk. |
Research Approach
A standing panel of RF engineering directors, smart building facility managers, hospital biomedical engineers, and third-party logistics procurement leads provided ongoing calibration against secondary validation from FCC equipment authorization databases, ETSI harmonized standards filings, and semiconductor foundry capex disclosures. Primary interviews with system integrators in Stuttgart, Chicago, and Shenzhen combined with trade data from customs records and enterprise Wi-Fi deployment metrics. Bottom-up unit economics triangulated against top-down addressable market sizing across technology and application segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated technology type, application intensity, end-user procurement sophistication, and deployment architecture complexity. CAGRs derived from fitted growth curves applied to base-year observations, with sensitivity analysis around Ultra-Wideband chip cost decline trajectories and Wi-Fi RTT infrastructure refresh cycles.
Forecasts assume regulatory continuity in FCC Part 15 and EU Radio Equipment Directive regimes; material policy shifts would require re-modeling transmission power limits or interoperability testing mandates. Revision becomes warranted when Taiwan foundry utilization rates or CE marking backlog durations cross thresholds that compress hardware availability timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
APAC Wireless Sensors Market
Sensors
Consumer 3D Sensing Products Market
Sensors
IO Link Market
Sensors
Asia Pacific RFID Market
Sensors
Wireless Occupancy Sensors Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Smart Barcode Readers Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Wireless Synchronized Clocks Market
Sensors
2D Barcode Reader Market
Sensors
Global Equipment Monitoring Market
Sensors
India Asset Tracking Market
Sensors
IO-Link Technology Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Ultrasonic Technologies Market
Sensors
Europe RFID Market