
 Consumer 3D Sensing Products Market | 2026-2036
Consumer 3D Sensing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer 3D Sensing Products Market Outlook
Modular sensor bundling is expanding across premium smartphone tiers, letting OEMs mix time-of-flight chips with structured light modules based on price positioning. Apple Inc. leverages captive semiconductor design to control depth-camera architecture. Samsung Electronics anchors supply through in-house sensor fabrication and display integration. Sony Corporation dominates image sensor supply for competing Android flagships.
Consumer 3D sensing products comprise compact optical systems that measure depth through time-of-flight, structured light, or stereo vision principles, typically operating at sub-millimeter accuracy for facial geometry capture and spatial mapping. These systems serve biometric authentication, immersive AR rendering, and autonomous navigation in compact consumer devices. Depth cameras lead product-type revenue due to smartphone integration scale, while lidar sensors represent the fastest-growing category as drone and AR headset adoption broadens. Facial recognition anchors application demand, though gesture control is gaining share in gaming console and smart TV interfaces.
The EU AI Act classifies biometric identification as high-risk AI, forcing design changes for CE-marked devices sold in Europe. The FDA oversees clinical-grade facial recognition in health-adjacent consumer devices, while China's SAMR enforces GB standards for data security in domestic 3D sensing hardware. Stakeholders must monitor divergence between EU, US, and Chinese biometric governance frameworks when planning sensor architecture roadmaps.
Market Dynamics
Smartphone OEMs are consolidating depth-sensor procurement around modular reference designs that slash integration costs while forcing component suppliers to absorb certification burdens for biometric compliance.
Growth Catalysts
- EU AI Act high-risk classification:CE-marked devices must embed privacy-by-design for facial recognition, accelerating demand for on-chip processing solutions that keep biometric data local.
- Drone navigation autonomy:Consumer UAV manufacturers in Shenzhen and Los Angeles are embedding solid-state lidar for obstacle avoidance at sub-$500 price tiers.
- Time-of-flight miniaturization:Sub-millimeter accuracy now fits within 3mm z-height constraints, enabling under-display sensor placement in foldable handsets.
Market Restraints
- Image sensor supply concentration:Sony Corporation controls CMOS supply for Android flagships, creating single-source vulnerability for competing OEMs.
- VCSEL array cost volatility:III-V semiconductor foundry capacity constraints in Taiwan and South Korea inflate structured light module BOMs.
- Structured light outdoor performance:Infrared interference from sunlight degrades facial recognition reliability below 10,000 lux, limiting automotive and outdoor robotics adoption.
Strategic Opportunities
- India PLI scheme for electronics:Smartphone assembly incentives are pulling 3D sensing module packaging to Noida and Chennai, creating localized supply for domestic brands.
- AR headset prescription integration:Depth sensors enabling pupillary distance measurement and lens fitting are penetrating eyewear retail channels.
- GDPR Article 35 Data Protection Impact Assessments:Mandatory DPIA documentation for biometric systems creates recurring service revenue for compliance consultancies and embedded software vendors.
Industry Challenges
- Multi-sensor fusion algorithm talent scarcity:The intersection of computer vision, signal processing, and embedded systems engineering commands premium compensation in Shenzhen and Seoul.
- ISO/IEC 30107-3 Presentation Attack Detection certification:Spoof-resistance testing for facial recognition adds 8-14 month timeline extensions to product launches.
- Legacy 2D camera subsystem integration:Depth sensor pipelines must coexist with established ISP architectures, forcing complex driver stack maintenance across Android fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer 3D Sensing Products Market |
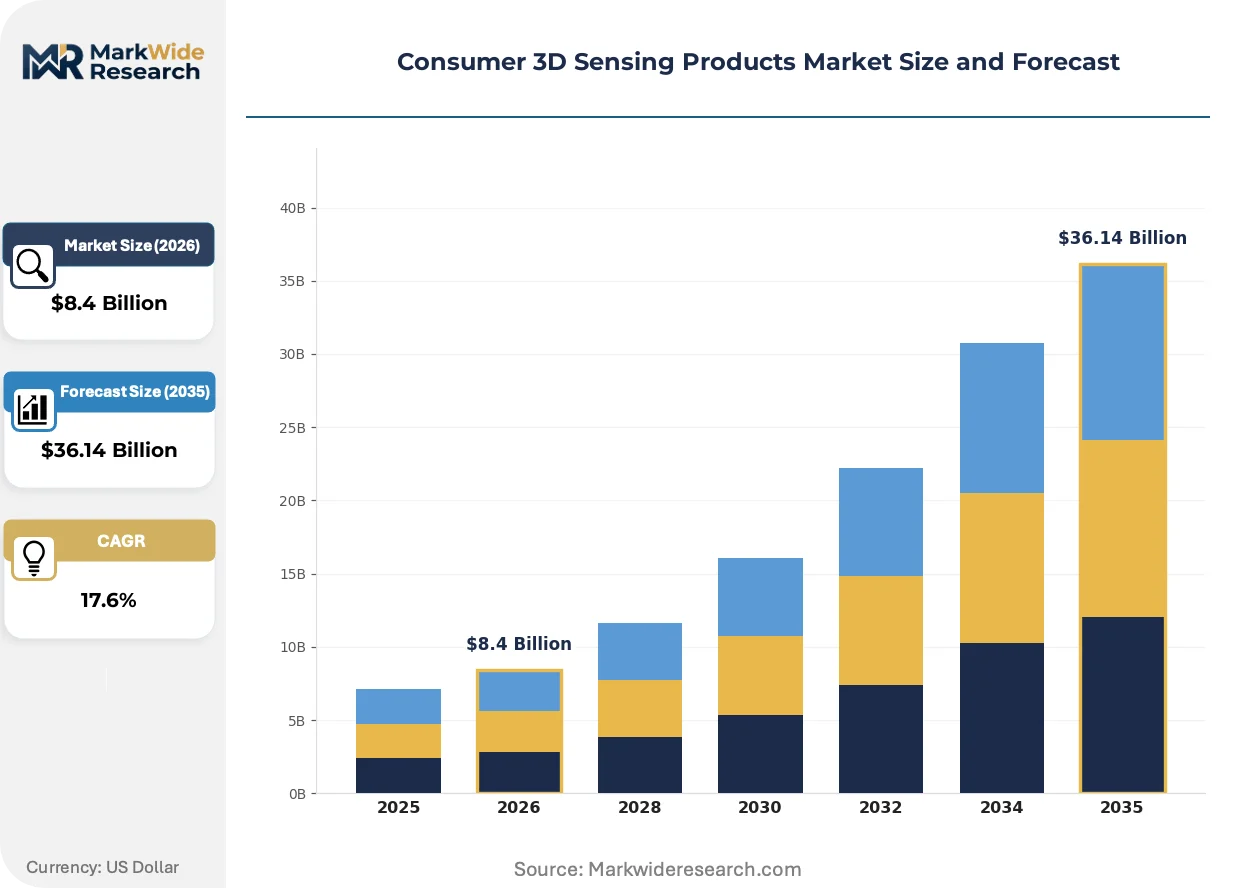
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
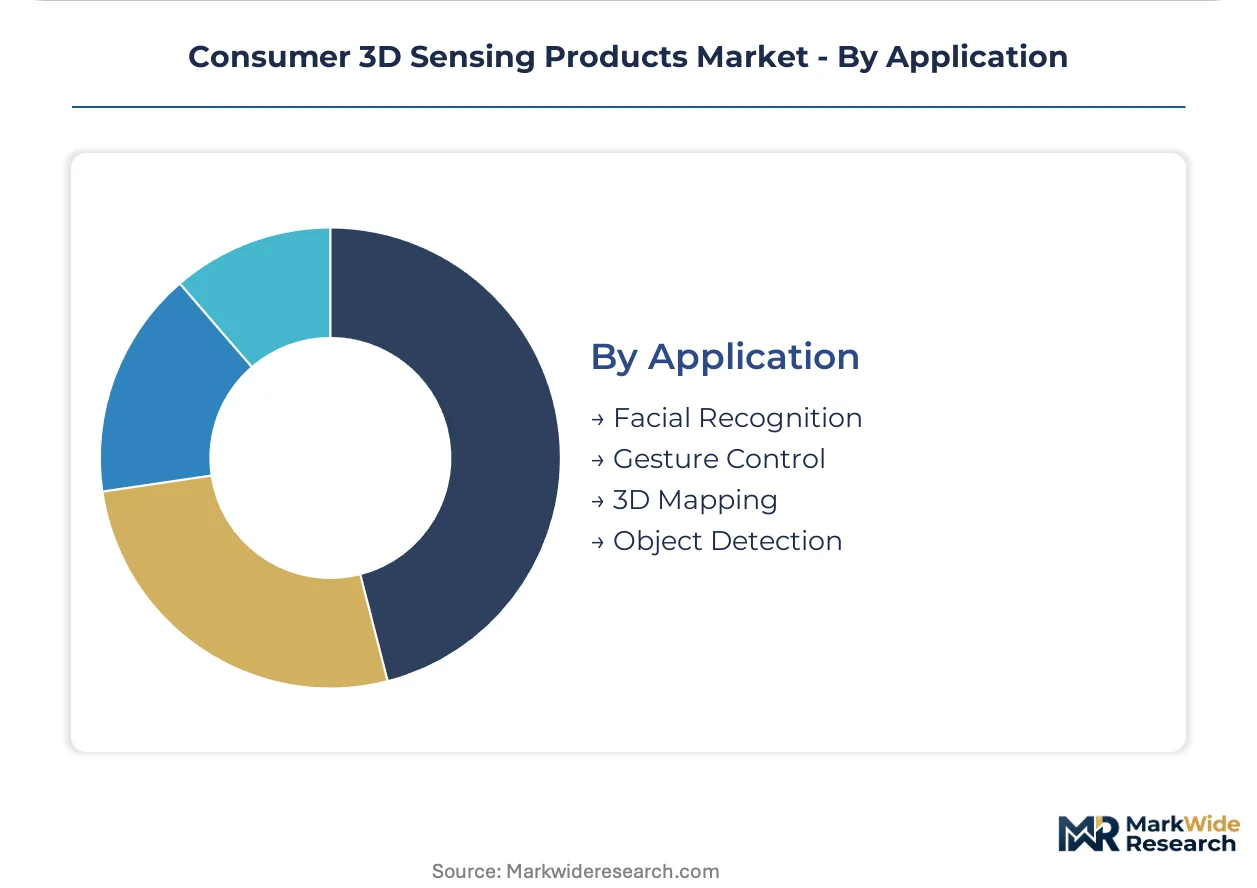
| Segmentation | Product Type: Depth Cameras, Lidar Sensors, 3D Scanners, Structured Light Sensors End User: Smartphones, Drones, AR Devices, Gaming Consoles Technology: Time of Flight, Stereo Vision, Laser Triangulation, Structured Light Application: Facial Recognition, Gesture Control, 3D Mapping, Object Detection |
| Companies Covered | Sony Corporation, Samsung Electronics, Infineon Technologies AG, Microchip Technology Inc., Qualcomm Technologies Inc., Apple Inc., OmniVision Technologies, Keyence Corporation, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer 3D Sensing Products Market Strategic Shifts
Sensor fusion architectures are collapsing discrete depth, RGB, and infrared pipelines into unified computational imaging stacks that reduce power draw and PCB footprint simultaneously.
Direct time-of-flight (dToF) SPAD arrays are unifying depth sensing and ambient light rejection in single photon avalanche diode configurations. Automotive-qualified dToF modules are migrating into consumer drones and AR glasses at accelerated refresh cycles. This unification is compressing the addressable market for discrete ambient light sensors and forcing legacy suppliers into module packaging partnerships.
The EU AI Act's high-risk system obligations are mandating algorithmic transparency documentation and human oversight interfaces for biometric identification functions. Hardware vendors must now ship with pre-completed conformity assessments and technical file packages. Premium smartphone OEMs targeting European distribution are absorbing these compliance costs into flagship pricing while mid-tier brands delay CE-marked launches.
Enterprise procurement of 3D sensing-enabled devices is consolidating around security-cleared distribution channels that bundle hardware with managed compliance services. Government and healthcare buyers in Germany and France are rejecting standard retail SKUs in favor of vendor-managed encryption key escrow and audit trail guarantees. This channel bifurcation is most visible in public sector tablet and access control terminal deployments.
Consumer 3D Sensing Products Market Segmentation
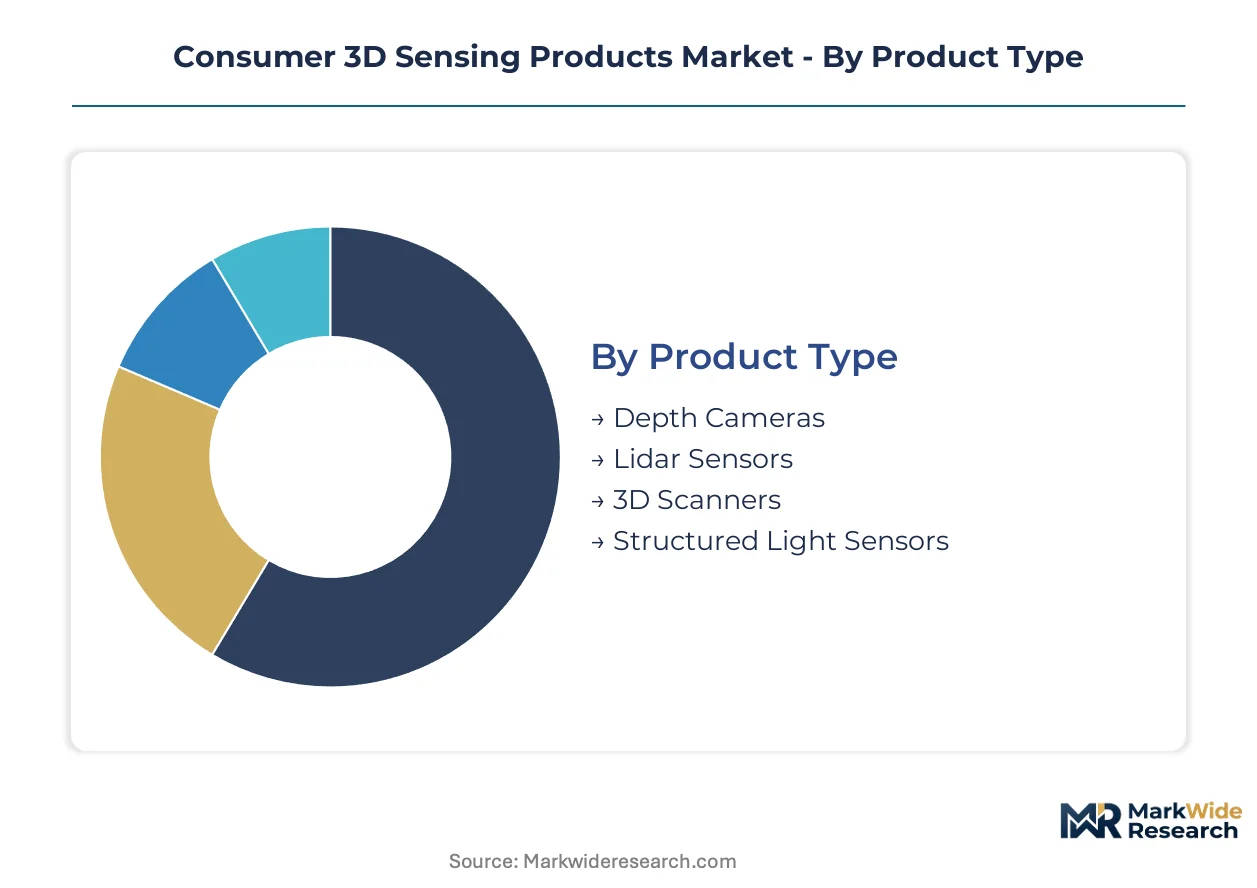
Consumer 3D sensing products fragment across four distinct category axes. Each segmentation layer reveals divergent margin profiles, certification burdens, and supply chain configurations that shape vendor positioning strategies.
Product Type:
Volume concentration sits with depth cameras in smartphone integration programs. Premium positioning belongs to lidar sensors in emerging AR and drone autonomy stacks.
- Depth Cameras:Compact optical systems combining RGB and infrared imagers with dedicated depth processing ASICs. Apple and Samsung anchor procurement in Cupertino and Suwon for facial authentication modules.
- Lidar Sensors:Solid-state and mechanical scanning variants emitting pulsed laser arrays for centimeter-precision spatial mapping. Shenzhen drone manufacturers and Los Angeles AR startups are driving adoption at sub-$500 consumer price tiers.
- 3D Scanners:Handheld and desktop units capturing full-body or object geometry for content creation and e-commerce visualization.
- Structured Light Sensors:Pattern projection systems using VCSEL arrays and diffractive optical elements for sub-millimeter facial geometry capture.
Mature deployment sits with depth cameras. Newer deployment is concentrated in lidar sensors.
End User:
Smartphone OEMs command the largest procurement volumes. AR device manufacturers represent the steepest expansion trajectory for component vendors.
- Smartphones:Facial recognition and portrait mode depth effects dominate BOM allocation. Chinese, South Korean, and US flagship programs consume the majority of time-of-flight and structured light module output.
- Drones:Obstacle avoidance and precision landing systems embed solid-state lidar for sub-$500 consumer UAV tiers. DJI and Skydio procurement patterns are reshaping sensor miniaturization roadmaps.
- AR Devices:Head-mounted displays require simultaneous localization and mapping capabilities. Meta and Apple headset programs are pulling automotive-qualified dToF modules into consumer refresh cycles.
- Gaming Consoles:Gesture control interfaces in living room environments leverage depth cameras for controller-free interaction.
Established integration sits with smartphones. Accelerated qualification cycles are concentrated in AR devices.
Technology:
Time of flight dominates current smartphone design wins. Structured light retains premium positioning in high-security facial authentication systems.
- Time of Flight:Direct and indirect measurement variants using modulated infrared illumination. Sony SPAD arrays and Samsung ISOCELL depth sensors anchor Android flagship supply.
- Stereo Vision:Dual-camera disparity calculation without active illumination. Lower BOM cost suits mid-tier smartphone and entry drone segments.
- Laser Triangulation:Line laser and camera offset geometry for industrial-grade precision in desktop 3D scanning applications.
- Structured Light:Dot pattern projection analyzed through deformable surface algorithms. Apple's captive VCSEL design maintains architectural control for Face ID systems.
Commoditization pressure sits with stereo vision. Performance differentiation is concentrated in structured light.
Application:
Facial recognition absorbs the majority of hardware volume. Gesture control is gaining share in gaming and smart TV interface programs.
- Facial Recognition:Biometric authentication and device unlock functions. EU AI Act high-risk classification is mandating on-chip processing and local data retention for CE-marked devices.
- Gesture Control:Hand tracking and mid-air interaction for controller-free gaming. Microsoft Kinect legacy and emerging smart TV integrations are expanding addressable hardware.
- 3D Mapping:Environmental reconstruction for AR persistence and drone navigation. Indoor scanning and outdoor topographic capture split between consumer and prosumer tiers.
- Object Detection:Real-time obstacle identification for autonomous movement in robotics and UAV platforms.
Regulatory scrutiny sits with facial recognition. Interface innovation is concentrated in gesture control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian electronics clusters while consumption splits between premium device markets in North America, Europe, and affluent Asian metros. Component fabrication dominates in China and South Korea, with final assembly gravitating toward India under production-linked incentive schemes.
China
Domestic smartphone brands and drone manufacturers anchor sensor procurement from Shenzhen and Dongguan module packagers. SAMR enforces GB standards for biometric data security in locally sold 3D sensing hardware. Yangtze River Delta fabs in Shanghai and Suzhou supply VCSEL arrays and diffractive optical elements to both domestic and export programs.
South Korea
Samsung Electronics and component suppliers drive captive demand for time-of-flight and structured light modules in flagship smartphone launches. MFDS oversight extends to health-adjacent facial recognition in wellness devices. Seoul Capital Area cleanrooms in Hwaseong and Pyeongtaek fabricate ISOCELL depth sensors for Android OEMs worldwide.
United States
Apple Inc. and Meta Platforms pull automotive-qualified lidar modules into consumer AR headset roadmaps, while drone autonomy startups in Los Angeles embed solid-state sensors. FDA regulates clinical-grade facial recognition in health-monitoring peripherals. Bay Area engineering offices in Cupertino and Menlo Park control depth-camera architecture and sensor fusion algorithm development.
Germany
Automotive lidar specialists pivot toward consumer drone and industrial 3D scanning applications as domestic OEMs diversify revenue streams. EU AI Act high-risk classification mandates privacy-by-design documentation for biometric devices sold across the single market. Bavarian optics clusters around Munich supply precision lens assemblies for structured light projection systems.
India
PLI scheme incentives for smartphone assembly are pulling 3D sensing module packaging to Noida and Chennai contract manufacturers. Domestic brands Lava and Micromax qualify locally assembled depth cameras for mid-tier facial authentication. Karnataka's Electronics City hosts testing facilities for BIS certification of imported sensor subassemblies.
Consumer 3D Sensing Products Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Captive semiconductor design arms at vertically integrated smartphone OEMs control premium facial recognition architectures, while merchant sensor vendors serve fragmented Android flagship programs. Three archetypes dominate: integrated device manufacturers with captive sensing divisions, merchant component suppliers with broad foundry partnerships, and specialized optical system houses. Competitive moves center on backward integration into VCSEL and SPAD fabrication, plus geographic relocation of module packaging to India under PLI incentives.
Within the integrated device manufacturer tier, Apple Inc. and Samsung Electronics exemplify divergent approaches to architectural control—Cupertino through captive semiconductor design, Suwon through in-house sensor fabrication and display integration. Sony Corporation anchors the merchant supplier archetype as a Japan-based Co., Ltd., dominating CMOS image sensor supply for competing Android flagships. STMicroelectronics represents the European diversified semiconductor model, shipping time-of-flight ASICs across consumer and automotive qualification grades.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics |
| Infineon Technologies AG |
| Microchip Technology Inc. |
| Qualcomm Technologies Inc. |
| Apple Inc. |
| OmniVision Technologies |
| Keyence Corporation |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
Direct time-of-flight SPAD array miniaturization is collapsing discrete component stacks into unified imaging pipelines, simultaneously compressing bill-of-materials costs and concentrating procurement leverage among vertically integrated smartphone OEMs with captive semiconductor design arms.
Pricing Analysis
Cost-down pressure on structured light modules accelerates because VCSEL array foundry capacity constraints in Taiwan and South Korea inflate III-V semiconductor input costs. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified dToF modules from consumer-grade time-of-flight chips from entry stereo vision implementations. Price differentiation hinges on ISO/IEC 30107-3 Presentation Attack Detection certification grade and volume procurement scale. Mid-tier Android OEMs exhibit acute price sensitivity, while Apple and Samsung absorb compliance premiums into flagship pricing.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Suwon, and Noida orchestrate hub-and-spoke patterns for module packagers serving smartphone assembly lines. Component fabrication concentrates in China, South Korea, and Japan, with Yangtze River Delta fabs supplying VCSEL arrays and Seoul Capital Area cleanrooms producing ISOCELL depth sensors. Raw material dependencies span indium phosphide wafers, diffractive optical elements, and specialized CMOS substrates. Single-source vulnerability around Sony Corporation's CMOS image sensor monopoly constitutes the dominant structural risk. Distribution runs through contract manufacturer consignment models with just-in-time delivery to final assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct time-of-flight SPAD architectures are displacing legacy structured light and stereo vision implementations across smartphone and AR headset programs, compressing the addressable market for discrete ambient light sensors and forcing module vendors into unified computational imaging partnerships.
For Market Incumbents: Acquire SPAD array fabrication capabilities to secure supply of direct time-of-flight chips as Android flagship programs consolidate procurement around Sony and Samsung captive designs. Invest in ISO/IEC 30107-3 certification infrastructure to accelerate facial recognition module launches before EU AI Act enforcement hardens. Defend against emerging pure-play lidar specialists by locking long-term VCSEL foundry offtake agreements with Taiwan and South Korea III-V semiconductor houses. For New Entrants and Emerging Players: Capture India PLI scheme incentives for 3D sensing module packaging in Noida and Chennai, supplying domestic smartphone brands Lava and Micromax with cost-optimized depth cameras for mid-tier facial authentication programs. Target AR headset prescription integration channels where pupillary distance measurement sensors penetrate eyewear retail with minimal incumbent saturation. Pursue compliance-as-a-service bundling for GDPR Article 35 Data Protection Impact Assessment documentation to differentiate from hardware-only competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified semiconductor conglomerates seeking depth-sensing module capabilities for automotive-to-consumer crossover applications. Long-term viability favors merchant sensor vendors with broad foundry partnerships and automotive qualification grades that insulate against smartphone demand cyclicality. Watch for inflection when automotive-qualified dToF module refresh cycles accelerate into consumer AR headset production ramps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCSEL Fabrication | Cupertino and Suwon OEMs secure III-V semiconductor supply against Taiwan foundry capacity constraints. |
| ISO/IEC 30107-3 Certification Investment | Module vendors reduce 8-14 month timeline extensions for facial recognition product launches. |
| India PLI Scheme Module Packaging | Contract manufacturers in Noida and Chennai capture localized supply for domestic smartphone brands. |
| Automotive-to-Consumer dToF Migration | Bavarian lidar specialists pivot precision optics toward sub-$500 drone and AR headset tiers. |
| Compliance-as-a-Service Bundling | Embedded software vendors monetize GDPR Article 35 DPIA documentation for biometric system deployments. |
Study Parameters
Document review covered SEC 10-K filings, SAMR GB standard publications, EU AI Act implementation guidance, and VCSEL foundry capacity disclosures, complemented by interviews with smartphone OEM platform engineers, depth-sensor module procurement leads, AR device optical system architects, and biometric compliance consultants. Primary fieldwork with Shenzhen and Dongguan module packagers, Seoul Capital Area cleanroom operations managers, and Bavarian precision lens assembly houses validated secondary intelligence. Bottom-up bill-of-materials analysis across time-of-flight, structured light, and lidar product categories triangulated against top-down smartphone and AR headset shipment projections.
Segment-level outputs across the analysis window reflect modeled trajectories for depth cameras, lidar sensors, 3D scanners, and structured light modules by technology principle, end-user vertical, and application function. The analytical framework incorporated time-of-flight miniaturization roadmaps, EU AI Act high-risk system compliance timelines, and India PLI scheme incentive disbursement patterns as industry-specific forecast inputs. CAGRs derived from logistic diffusion curves fitted to historical smartphone facial recognition adoption rates and projected AR headset penetration scenarios.
The model holds under stable VCSEL foundry capacity expansion and gradual EU AI Act enforcement; deviation in Taiwan semiconductor export restrictions or accelerated GDPR biometric litigation would shift module pricing and certification timelines. Forecasts reflect documented assumptions regarding smartphone OEM consolidation patterns and AR headset manufacturer qualification cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Data Buoy Market
Sensors
Yield Monitoring Systems Market
Sensors
Transport Monitoring System Market
Sensors
Global Position Tracking System Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Asia Pacific Container Monitoring Market
Sensors
Transportation Sensors Market
Sensors
IO Link Market
Sensors
Automated Weather Observation System Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
2D Barcode Reader Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Digital Direction Finder Market
Sensors
Machine Health Monitoring Market
Sensors
North America Eye Tracking Solutions Market