
 Smart Pest Monitoring Management System Market | 2026-2036
Smart Pest Monitoring Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pest Monitoring Management System Market Outlook
IP65-rated outdoor sensor enclosures is reorganizing procurement standards across the smart pest monitoring sector. Bayer AG leverages its crop science division to anchor integrated pest management platforms in large-scale agricultural zones. Ecolab Inc. specializes in hospitality and food safety applications, sustaining channel dominance through service bundling with monitoring hardware. SemiosBio Technologies dominates orchard-specific deployments, extending its reach through climate-pest correlation algorithms.
A smart pest monitoring management system comprises networked traps, environmental sensors, and cloud-connected analytics platforms that detect, identify, and track pest populations across agricultural and commercial environments. These systems typically operate on sub-gigahertz wireless protocols with battery lifespans exceeding three years to enable uninterrupted field deployment in remote growing regions. Cloud-based deployment architectures now capture the fastest-growing margin pool as recurring software revenue displaces one-time hardware sales. Agriculture end users lead volume absorption, though hospitality segments generate premium pricing through compliance-driven replacement cycles.
The EPA registers all pesticide-adjacent monitoring devices under FIFRA guidelines, while the EU Green Deal mandates integrated pest management adoption that directly stimulates sensor-based surveillance procurement. Brazil's national agricultural regulator enforces traceability standards that embed digital pest logs into export certification workflows. Stakeholders must weigh hardware durability specifications against cloud analytics depth when configuring solutions for tropical versus temperate growing zones.
Market Dynamics
The EU Green Deal's pesticide reduction mandates are forcing agricultural operators to replace chemical surveillance with networked sensor arrays, compressing procurement timelines for integrated pest management infrastructure.
Growth Catalysts
- Integrated pest management mandates:The EU Green Deal requires member states to cut chemical pesticide use by half, compelling French and German grain cooperatives to install pheromone trap networks with cloud analytics.
- Brazil:ANVISA traceability protocols now embed digital pest logs into soybean export certifications, mandating sensor deployment across Mato Grosso and Paraná production zones.
- Sub-gigahertz wireless protocols:Battery-efficient LoRaWAN and Sigfox connectivity enable three-year uninterrupted field operation in remote agricultural regions lacking cellular infrastructure.
Market Restraints
- Lithium battery supply concentration:Cell production concentrates in East Asian manufacturing hubs, exposing Brazilian and Australian agricultural deployers to raw material volatility and extended lead times.
- IP65 enclosure cost structure:Precision-machined aluminum housings with gasket sealing represent 23-31% of hardware bill-of-materials, compressing margin pools for temperate-zone equipment vendors.
- FIFRA registration friction:EPA device classification under pesticide-adjacent rules imposes 18-24 month approval timelines for novel trap designs, delaying US market entry for European sensor manufacturers.
Strategic Opportunities
- Hospitality compliance cycles:FDA Food Code revisions and HACCP audit intensification drive replacement demand for automated rodent monitoring in US hotel and food processing chains.
- AI-vision convergence:Edge-deployed image recognition processors combined with pheromone sensors enable species-level identification without cloud latency, opening premium orchard and vineyard segments.
- India:FSSAI mandatory traceability for spice exports creates first-mover advantage for integrated pest surveillance platforms in Gujarat and Rajasthan processing clusters.
Industry Challenges
- Entomological data science talent scarcity:Interpretation of pest population dynamics requires hybrid agronomy-machine learning expertise that agricultural technology vendors struggle to recruit.
- Legacy farm management system integration:John Deere Operations Center and Climate FieldView APIs lack standardized pest data schemas, forcing costly middleware development for sensor platform vendors.
- Multi-jurisdiction certification timelines:simultaneous EPA FIFRA, CE marking, and ANVISA approvals extend product launch cycles by 14-20 months for global equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pest Monitoring Management System Market |
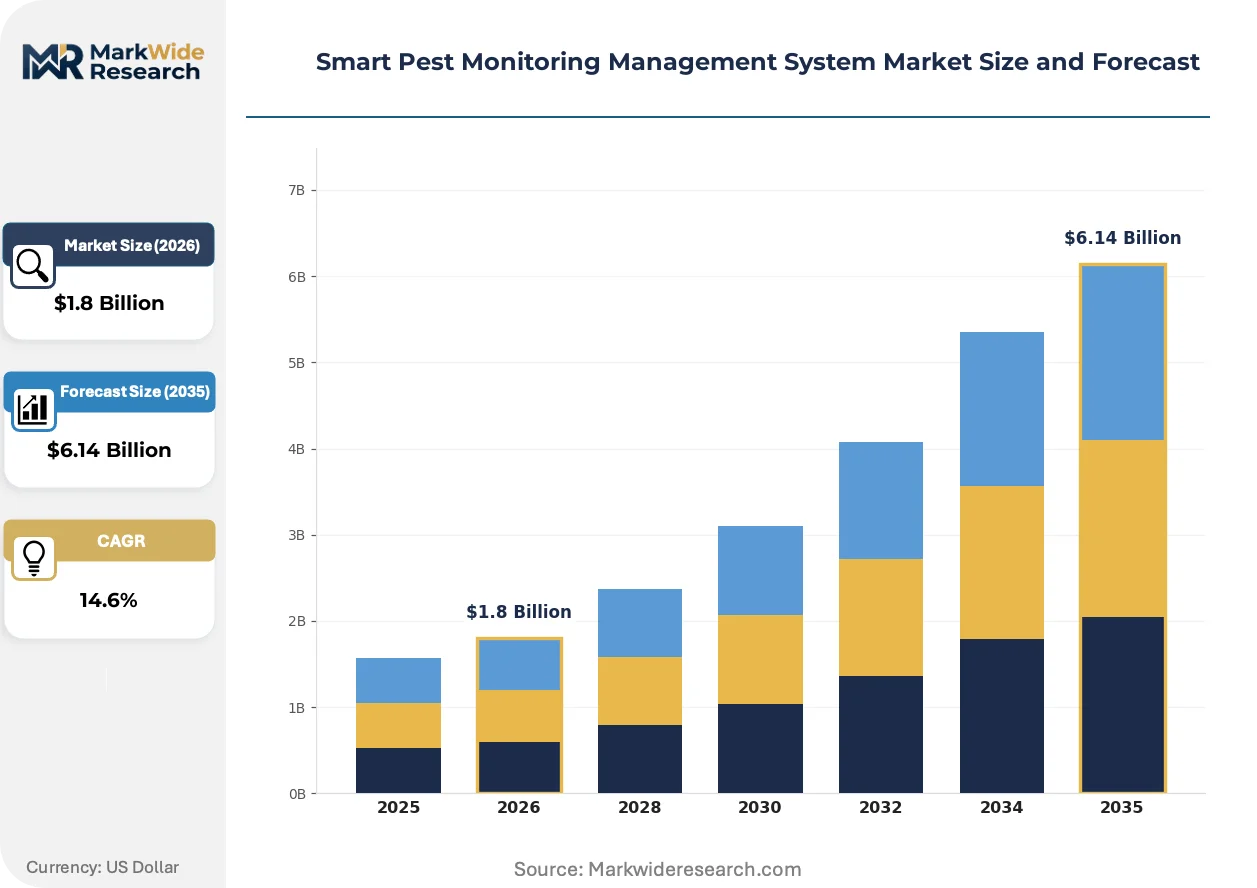
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traps, Sensors, Technology Platforms, Software Solutions End User: Agriculture, Hospitality, Residential, Commercial Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solution: Monitoring, Prevention, Data Analytics, Reporting |
| Companies Covered | Bayer AG, Anticimex, Corteva Agriscience, BASF, Ecolab Inc., Syngenta AG, Trapview, SemiosBio Technologies, DunavNET, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pest Monitoring Management System Market Strategic Shifts
Sensor miniaturization and edge AI deployment are collapsing the cost-performance frontier for automated pest detection, enabling subscription-based analytics to capture recurring revenue streams previously locked in hardware sales.
Computer vision modules with onboard neural inference engines are displacing manual trap inspection protocols in large-scale grain operations. US precision agriculture cooperatives in Iowa and Illinois are deploying camera-equipped pheromone traps at 400-unit densities per 1,000 hectares. This hardware architecture is displacing seasonal labor contracts and compressing detection latency from seven days to four hours.
REACH substance restrictions on persistent organic pollutants are accelerating biopesticide adjuvant development in European orchard systems. EFSA residue monitoring protocols now require documented non-chemical intervention attempts before synthetic pesticide authorization. German and Spanish stone fruit growers are responding with sensor-network investments that satisfy audit requirements for integrated pest management compliance.
Equipment-as-a-service contracting is restructuring buyer-vendor relationships in Brazilian soybean production. Local agricultural credit cooperatives in Mato Grosso are bundling sensor subscriptions with crop insurance products, transferring hardware ownership risk from growers to technology platforms. This financial innovation is most visible in regions where BNDES rural credit lines explicitly cover digital agriculture infrastructure amortization.
Smart Pest Monitoring Management System Market Segmentation
Pest monitoring procurement splits sharply between capital-intensive hardware buyers and recurring-software subscribers. Regulatory mandates in agriculture and hospitality create divergent specification requirements across each segment cluster.
Product Type:
EPA FIFRA registration requirements differentiate pesticide-adjacent hardware from pure analytics software, compressing approval timelines for European trap manufacturers entering US markets.
- Traps:Pheromone-baited enclosures with IP65-rated aluminum housings dominate Brazilian soybean certification workflows. French grain cooperatives deploy these at 400-unit densities per 1,000 hectares to satisfy EU Green Deal pesticide reduction audits.
- Sensors:Environmental monitoring nodes operating on LoRaWAN protocols achieve three-year battery life in remote Mato Grosso growing regions. Sub-gigahertz connectivity eliminates cellular infrastructure dependency for Australian wheat belt operators.
- Technology Platforms:Integrated hardware-software bundles bundle sensor networks with cloud dashboards for Iowa precision agriculture cooperatives.
- Software Solutions:Subscription analytics layers capture recurring revenue from hospitality compliance cycles in US hotel chains.
Established volume favors traps; emerging adoption favors software solutions.
End User:
Cost tier differentiation separates high-volume agricultural deployments from premium-priced compliance-driven hospitality installations.
- Agriculture:Grain cooperatives in Illinois and Iowa absorb hardware at scale, replacing seasonal labor contracts with automated detection. ANVISA traceability mandates embed digital pest logs into Brazilian soybean export certifications.
- Hospitality:FDA Food Code revisions and HACCP audit intensification drive replacement cycles for automated rodent monitoring in US hotel and food processing chains. Premium pricing reflects liability exposure rather than hardware cost.
- Residential:Smart home integration lags commercial adoption due to price sensitivity and limited regulatory pressure.
- Commercial:Warehouse and logistics facilities deploy perimeter monitoring for insurance premium reductions.
Volume concentration sits with agriculture; margin expansion sits with hospitality.
Deployment:
Application architecture determines latency sensitivity for species-level identification workflows.
- Cloud-Based:Centralized analytics platforms capture the steepest expansion trajectory as recurring software revenue displaces one-time hardware sales. German stone fruit growers rely on cloud correlation engines to satisfy EFSA residue monitoring protocols.
- On-Premises:Air-gapped installations serve data sovereignty requirements in Indian spice processing clusters under FSSAI traceability mandates.
- Hybrid:Edge-cloud split processing balances detection latency against storage cost for large-scale grain operations.
- Mobile:Field technician companion apps support trap inspection workflows in remote temperate zones lacking continuous connectivity.
Legacy infrastructure favors on-premises; AI-vision convergence favors cloud-based.
Solution:
Customer type stratification separates preventive specification buyers from reactive monitoring purchasers.
- Monitoring:Real-time population tracking with automated alert thresholds dominates Brazilian integrated pest management programs. Sensor networks in Paraná production zones transmit trap counts every four hours versus seven-day manual inspection cycles.
- Data Analytics:Climate-pest correlation algorithms enable predictive intervention timing for Spanish vineyard operators facing REACH substance restrictions on persistent organic pollutants.
- Prevention:Early warning systems reduce synthetic pesticide authorization requirements under EFSA documented-intervention protocols.
- Reporting:Audit-ready documentation packages satisfy export certification workflows for Gujarat spice processors.
Compliance pressure favors reporting; operational efficiency favors data analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor manufacturing clusters concentrate in East Asian industrial zones, yet deployment demand distributes across agricultural belts in the Americas, Europe, and Asia-Pacific. Procurement patterns diverge sharply between regulatory-driven European grain cooperatives and export-certification-dependent Brazilian soybean operations.
United States
Precision agriculture cooperatives in Iowa and Illinois deploy camera-equipped pheromone traps at 400-unit densities per 1,000 hectares. EPA FIFRA registration requirements impose 18-24 month approval timelines for novel trap designs, compressing market entry for European sensor manufacturers. The Corn Belt's automated detection networks displace seasonal labor contracts and reduce detection latency from seven days to four hours.
Brazil
ANVISA traceability protocols embed digital pest logs into soybean export certifications, mandating sensor deployment across Mato Grosso and Paraná production zones. Local agricultural credit cooperatives bundle sensor subscriptions with crop insurance products, transferring hardware ownership risk from growers to technology platforms. BNDES rural credit lines explicitly cover digital agriculture infrastructure amortization in these regions.
Germany
Stone fruit growers in Baden-Württemberg and Bavaria invest in sensor networks to satisfy EFSA residue monitoring protocols under REACH substance restrictions. The EU Green Deal's pesticide reduction mandates require documented non-chemical intervention attempts before synthetic pesticide authorization. German grain cooperatives install pheromone trap networks with cloud analytics to comply with member state targets to cut chemical pesticide use by half.
India
FSSAI mandatory traceability for spice exports creates first-mover advantage for integrated pest surveillance platforms in Gujarat and Rajasthan processing clusters. Air-gapped on-premises installations serve data sovereignty requirements in these regions. Indian spice processors deploy audit-ready documentation packages to satisfy export certification workflows.
Australia
Wheat belt operators rely on sub-gigahertz LoRaWAN connectivity to eliminate cellular infrastructure dependency in remote growing regions. Three-year battery life specifications prove critical for uninterrupted field operation where maintenance access is limited. Australian agricultural deployers face exposure to lithium battery supply volatility from East Asian manufacturing concentration.
Smart Pest Monitoring Management System Market Competitive Environment
Concentration sits with diversified agrochemical conglomerates that leverage crop science divisions to anchor integrated pest management platforms. The vendor base stratifies across three tiers: global life science majors with bundled hardware-software offerings, specialized sensor platform vendors with orchard-specific climate-pest algorithms, and regional service integrators with hospitality-focused compliance bundling. Dominant competitive moves include backward integration into sensor hardware manufacturing and geographic expansion through agricultural credit cooperative partnerships.
Within the diversified agrochemical tier, Bayer AG and BASF exemplify conglomerate-scale positioning that spans crop protection and digital surveillance infrastructure. Corteva Agriscience and Syngenta AG occupy parallel positions with integrated seed-to-sensor portfolios. Ecolab Inc. represents the service-bundling archetype in hospitality and food safety applications, while SemiosBio Technologies anchors the orchard-specialist vector with climate-pest correlation capabilities. Trapview and DunavNET exemplify the sensor-platform-native archetype with cloud-first deployment architectures.
| Leading Market Players |
|---|
| Bayer AG |
| Anticimex |
| Corteva Agriscience |
| BASF |
| Ecolab Inc. |
| Syngenta AG |
| Trapview |
| SemiosBio Technologies |
| DunavNET |
| Others |
Value Chain & Pricing Dynamics
Equipment-as-a-service contracting locks in multi-year subscription revenue for Brazilian soybean operators while insulating Mato Grosso growers from lithium battery price volatility through bundled crop insurance products. This financial structure transfers hardware ownership risk to technology platforms and creates price visibility across the analysis window.
Pricing Analysis
EPA FIFRA registration dictates the pricing tier structure for pesticide-adjacent hardware entering US markets, with 18-24 month approval timelines compressing European sensor manufacturers into premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates IP65-rated aluminum enclosures from polycarbonate alternatives. Cost compression in temperate-zone equipment stems from precision-machined housing expenses representing 23-31% of hardware bill-of-materials. Agricultural grain cooperatives exhibit highest price sensitivity due to volume procurement scales, while hospitality chains absorb premium pricing driven by HACCP audit liability exposure.
Supply Chain Analysis
Port congestion along East Asian trade lanes elevates inbound logistics costs for Brazilian and Australian agricultural deployers sourcing lithium cells. Cell production concentrates in China, South Korea, and Japan, creating single-source vulnerability for battery-dependent sensor platforms. Hardware feeds from precision-machined aluminum suppliers, LoRaWAN chipset fabricators, and cloud infrastructure providers. Distribution runs through agricultural credit cooperatives in Mato Grosso and precision agriculture dealer networks in Iowa and Illinois.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's pesticide reduction mandates constitute a regulatory inflection accelerating displacement of chemical surveillance with networked sensor arrays. This policy disruption creates asymmetric growth windows for technology platforms versus incumbent agrochemical suppliers.
For Market Incumbents: Shield integrated pest management platform margins by accelerating backward integration into sensor hardware manufacturing. Consolidate channel control through exclusive partnerships with John Deere Operations Center and Climate FieldView API standardization efforts. Counter emerging entrant pressure from orchard-specialist climate-pest algorithm vendors by acquiring edge AI vision capabilities.
For New Entrants and Emerging Players: ANVISA fast-track certification for Brazilian soybean export workflows opens immediate white-space access in Paraná and Mato Grosso production zones. Target hospitality compliance cycles in US hotel chains where FDA Food Code revisions drive replacement demand with premium pricing tolerance. Deploy service-bundled go-to-market models mirroring Ecolab's food safety application architecture.
For Investors and Strategic Acquirers: Orchard-specific sensor platform vendors with climate-pest correlation algorithms represent the most attractive acquisition target archetype for agrochemical conglomerates seeking digital surveillance capabilities. Long-term viability hinges on recurring software revenue displacement of one-time hardware sales across the projection horizon. Monitor EPA FIFRA registration approval velocity as inflection indicator for US market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | Bayer AG and BASF reduce supply chain exposure to East Asian lithium cell concentration. |
| Equipment-as-a-Service Contracting | Brazilian credit cooperatives bundle sensor subscriptions with BNDES-covered crop insurance products. |
| Edge AI Vision Deployment | SemiosBio Technologies and Trapview enable species-level identification without cloud latency in orchard segments. |
| API Standardization Investment | Platform vendors reduce middleware development costs for John Deere and Climate FieldView integration. |
| Multi-Jurisdiction Certification Parallelization | Global suppliers compress 14-20 month EPA FIFRA, CE marking, and ANVISA approval cycles. |
Study Parameters
Initial hypotheses were tested against primary input from precision agriculture cooperative managers, hospitality compliance officers, agricultural credit underwriters, and entomological data scientists and refined through secondary validation. Primary fieldwork encompassed stakeholder interviews across Brazilian soybean production zones, German stone fruit growing regions, and US Corn Belt precision agriculture operations. Secondary sources included EPA FIFRA registration databases, ANVISA traceability protocol documentation, EU Green Deal implementation reports, and BNDES rural credit line disclosures. Bottom-up sensor deployment counts triangulated against top-down agricultural technology spending estimates.
Variance decomposition across product type, end user, deployment architecture, and solution function shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled dimensions included hardware-software revenue split, regulatory mandate compliance timelines, and battery technology substitution curves. Industry-specific forecast inputs incorporated LoRaWAN network deployment trajectories and cloud analytics subscription renewal rates.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable lithium supply chain configurations; material deviation would warrant model refresh. Specific risk factors include REACH substance restriction acceleration, FSSAI traceability mandate expansion, and East Asian battery manufacturing concentration shocks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Asia-Pacific Remote Sensing Technology Market
Sensors
Smart Barcode Readers Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
2D Barcode Reader Market
Sensors
Global Equipment Monitoring Market
Sensors
Cloud Camera Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Eye Tracking Market
Sensors
Weigh-In-Motion System Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Traffic Sensor Market
Sensors
Asset Tags Market
Sensors
Beacon Technology Market
Sensors
Europe RFID Market
Sensors
Industrial Automation Sensors Market
Sensors
Underground Service Locator Market