
 Terrestrial Laser Scanning System Market | 2026-2036
Terrestrial Laser Scanning System Market Size, Share, and Industry Trends Forecast 2026-2036
Terrestrial Laser Scanning System Market Analysis
Multi-source component procurement is shifting toward captive sensor manufacturing among leading vendors. RIEGL Laser Measurement Systems GmbH leverages in-house diode laser production to control beam quality and delivery timelines. Trimble Inc. anchors its position through tightly integrated GNSS-LS hardware-software bundles. FARO Technologies, Inc. competes on service density, maintaining calibration and support centers across major metropolitan zones.
A terrestrial laser scanning system emits pulsed or continuous-wave laser beams to capture dense three-dimensional point clouds with sub-centimeter accuracy, typically operating at wavelengths between 600 and 1,550 nanometers for eye-safe terrestrial deployment. These systems serve primarily to document as-built conditions, monitor structural deformation, and generate spatially precise digital twins for engineering and facility management. Phase-based scanners currently lead unit shipments in indoor metrology and heritage documentation due to superior speed at short range, while time-of-flight systems dominate outdoor surveying and mining applications where maximum range exceeds one kilometer. Hybrid architectures that switch between modalities are capturing margin pools in construction, where a single instrument must perform across diverse site conditions without crew changes.
FDA laser product regulations in the United States classify scanner emission levels and mandate safety interlocks, directly influencing optical engine design choices for vendors seeking North American market access. EASA and national aviation authorities across Europe impose flight-permission frameworks for drone-mounted scanners, shaping how mobile scanning technology segments develop alongside traditional tripod-based systems. ISO 19130 and ASTM E57 standards govern point-cloud interoperability, creating compliance barriers that favor established players with dedicated certification engineering. Stakeholders must weigh captive versus outsourced photodetector supply as geopolitical trade policies disrupt semiconductor availability.
Market Dynamics
Construction digitization mandates and BIM integration requirements are compressing hardware replacement cycles while elevating software-embedded service expectations across surveying equipment procurement.
Growth Catalysts
- China's MIIT dual carbon policy:Precision surveying requirements for renewable energy infrastructure and smart city development accelerate phase-based scanner deployment in utility-scale solar and wind projects.
- Phase-based scanning speed:Heritage documentation and indoor metrology applications favor sub-second capture rates that time-of-flight architectures cannot match at short range.
- German industrial corridor demand:Automotive OEMs and infrastructure consortia in Bavaria and Baden-Württemberg require millimeter-accurate as-built documentation for factory retrofits and tunnel monitoring.
Market Restraints
- Photodetector supply concentration:Geopolitical trade policies disrupt semiconductor availability from East Asian foundries, forcing vendors to absorb lead time volatility or redesign optical engines.
- FDA laser classification compliance:Eye-safety interlock requirements for Class 3R and 4 products add engineering cost and certification timeline friction for North American market entry.
- Photogrammetry substitution:Drone-mounted camera arrays with AI-enhanced point cloud generation compete for outdoor surveying applications where absolute range precision is secondary.
Strategic Opportunities
- India infrastructure buildout:National highway and railway corridor projects under the Ministry of Road Transport and Highways create first-time demand for mobile mapping systems in tier-2 and tier-3 urban zones.
- SLAM-LS convergence:Simultaneous localization and mapping algorithms paired with lightweight laser sensors enable handheld scanning formats that displace tripod-based workflows in confined industrial environments.
- EU Green Deal building renovation mandates:Member state requirements for energy performance documentation of existing structures drive recurring survey contracts for facility management service providers.
Industry Challenges
- Point cloud processing talent scarcity:Surveying firms compete with gaming and autonomous vehicle sectors for computational geometry specialists capable of managing billion-point datasets.
- ISO 19130 interoperability certification:Multi-format data exchange compliance creates engineering backlog for vendors seeking public-sector procurement eligibility in European markets.
- Legacy CAD integration complexity:Engineering consultancies face workflow friction when translating dense laser scan outputs into parametric models compatible with decade-old design software installations.
Report Scope
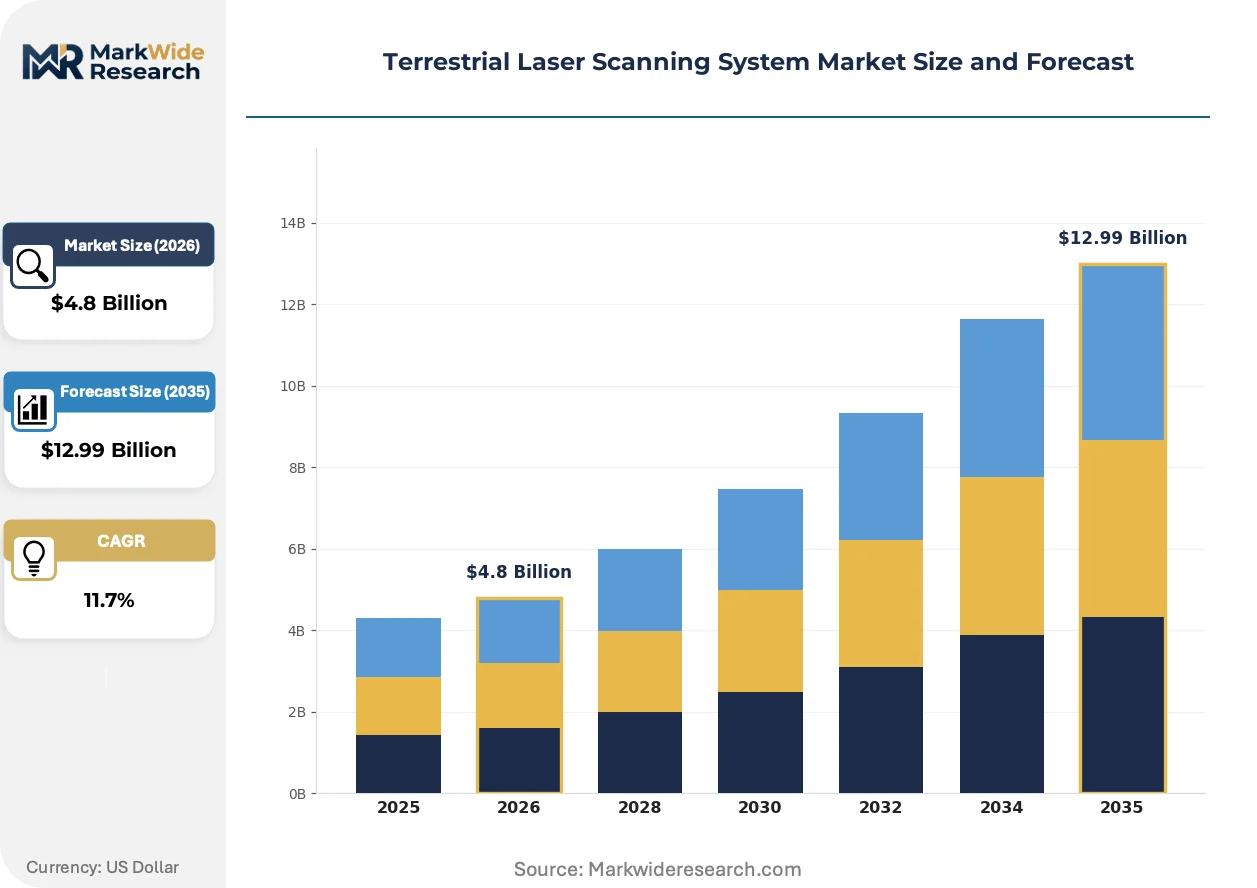
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terrestrial Laser Scanning System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phase-Based, Time-of-Flight, Hybrid, Ultra-High Definition End User: Construction, Surveying, Mining, Research Institutions Technology: GPS Integration, 3D Imaging, Mobile Scanning, Cloud Processing Application: Building Information Modeling, Cultural Heritage Documentation, Land Surveying, Asset Management |
| Companies Covered | RIEGL Laser Measurement Systems GmbH, Topcon Corporation, Hexagon AB, Zoller + Fröhlich GmbH, Teledyne Technologies, Inc., Trimble Inc., Leica Geosystems AG, NavVis GmbH, FARO Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terrestrial Laser Scanning System Market Emerging Trajectories
Hardware-software bundling and cloud-native processing architectures are compressing the traditional separation between field data capture and office-based deliverable production.
Hybrid phase-time-of-flight architectures are unifying indoor and outdoor scanning capabilities within single instrument platforms. Construction contractors operating across diverse site conditions adopt these dual-modality systems to eliminate crew changes and equipment swaps. This unification is compressing vendor product line complexity while expanding addressable use cases per unit sale.
REACH restrictions on hazardous substance content in electronics are forcing optical engine redesigns for European market compliance. Manufacturers substitute lead-free solder formulations and revise thermal management schemes to maintain beam stability. Scanner product lines destined for EU distribution now carry separate bill-of-materials configurations from identical models shipping to other regions.
Subscription-based software licensing is displacing perpetual ownership models among mid-sized surveying firms. Trimble and FARO now bundle cloud processing credits with hardware leases, capturing recurring revenue from customers previously purchasing standalone perpetual seats. This shift is most visible in North American AEC markets where operational expenditure treatment of software costs aligns with project-based accounting practices.
Terrestrial Laser Scanning System Market Segmentation
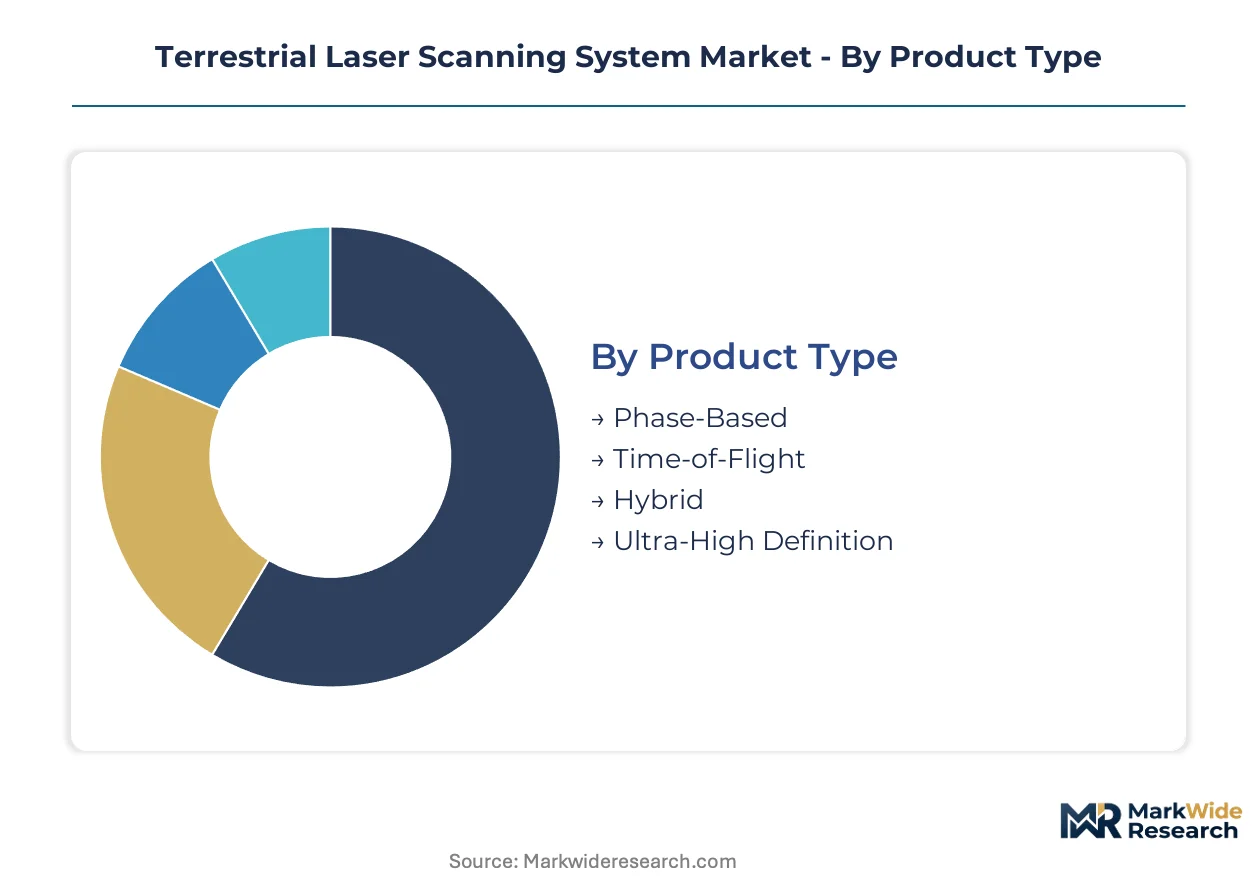
Scanner architecture determines deployment flexibility and price positioning across construction, mining, and heritage documentation verticals. End-user workflows diverge sharply between precision-driven metrology and speed-driven mobile mapping. Technology integration and application specificity further fragment procurement criteria among engineering consultancies and government survey departments.
Product Type:
Range precision and capture speed trade-offs dominate equipment selection for mixed indoor-outdoor operations.
- Phase-Based:These scanners modulate continuous-wave laser signals to achieve sub-millimeter accuracy at ranges under 80 meters. Heritage conservation teams in Italy and France deploy phase-based units for cathedral documentation where detail density outweighs range requirements.
- Time-of-Flight:Pulsed laser emission enables kilometer-scale range capture with centimeter-level precision. Mining operators in Western Australia and Chile favor time-of-flight architectures for pit wall stability monitoring where single-setup coverage reduces survey crew exposure hours.
- Hybrid:Switchable phase-time-of-flight engines adapt to construction sites demanding both interior as-built verification and exterior earthwork volume calculations without instrument swaps.
- Ultra-High Definition:Dense point spacing below 1 millimeter serves industrial metrology and forensic reconstruction applications requiring surface texture capture.
Time-of-Flight leads on scale; Hybrid leads on momentum.
End User:
Procurement authority and software integration requirements vary dramatically across buyer categories.
- Construction:General contractors and specialty trades drive the largest equipment volumes, integrating scanner outputs directly into Autodesk and Bentley BIM workflows for clash detection and progress verification.
- Surveying:Licensed geomatics firms prioritize ISO 19130 compliance and multi-instrument calibration chains to maintain legal survey traceability for cadastral and boundary determinations.
- Mining:Pit optimization and stockpile volume calculations demand ruggedized housings and dust-sealed optics for continuous operation in abrasive environments.
- Research Institutions:Universities and archaeological institutes acquire specialized units through grant funding, often prioritizing open data formats and long-term manufacturer support commitments over acquisition cost.
Construction dominates absolute procurement volume; Research Institutions show the steepest expansion trajectory as digital humanities funding accelerates.
Technology:
Field-to-office data pipeline efficiency increasingly determines vendor selection over raw hardware specifications.
- GPS Integration:Tightly coupled GNSS receivers enable georeferenced point clouds without separate control point establishment, accelerating topographic survey workflows in open terrain.
- 3D Imaging:Panoramic camera co-registration with laser data produces photorealistic deliverables for stakeholder visualization and texture-mapped mesh generation.
- Mobile Scanning:Vehicle-mounted SLAM-LS systems capture corridor infrastructure at highway speeds, displacing static scanning for linear asset inventory projects.
- Cloud Processing:Subscription-based point cloud hosting and automated feature extraction reduce on-premise computational infrastructure requirements for mid-sized surveying firms.
Cloud Processing is gaining share fastest; GPS Integration retains the largest installed base.
Application:
Deliverable format specifications and contractual liability exposure shape application-level demand patterns.
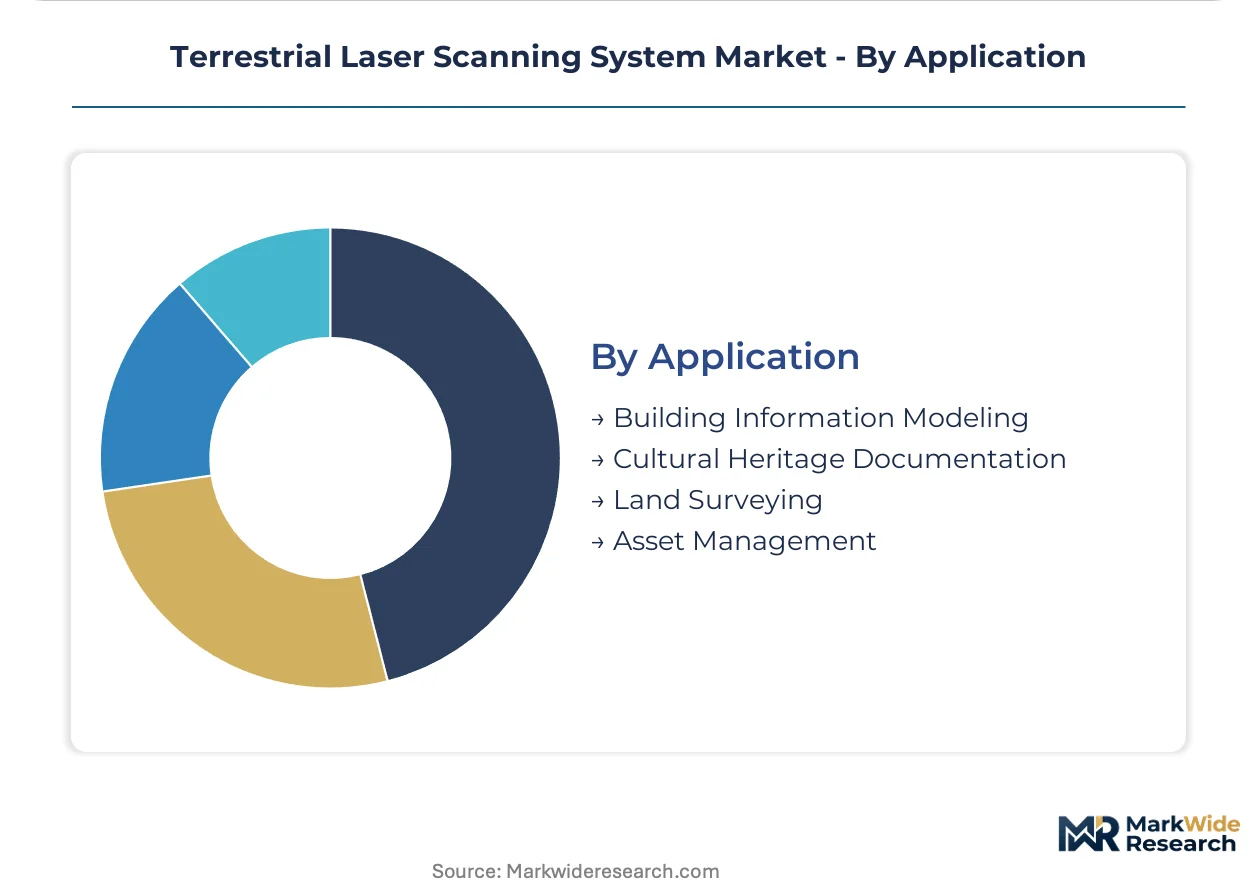
- Building Information Modeling:As-built documentation for facility handover requires scan-to-BIM conversion services that bundle hardware with specialized modeling labor.
- Cultural Heritage Documentation:UNESCO World Heritage site monitoring and disaster recovery planning drive recurring survey contracts with stringent archival metadata requirements.
- Land Surveying:Cadastral boundary determination and topographic base mapping remain regulated professions with instrument certification mandates varying by jurisdiction.
- Asset Management:Industrial facility digital twins for predictive maintenance integrate scanner outputs with IoT sensor networks and enterprise asset management platforms.
Building Information Modeling anchors current revenue; Asset Management exhibits the strongest forward momentum as owner-operators extend digital twin investments beyond initial construction phases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor concentrates the highest density of precision surveying demand. Automotive OEMs and infrastructure consortia in Bavaria and Baden-Württemberg drive millimeter-accurate as-built documentation requirements. China's MIIT dual carbon policy accelerates renewable energy infrastructure surveying across utility-scale solar and wind projects.
United States
Construction digitization mandates compress hardware replacement cycles while elevating software-embedded service expectations. FDA laser product regulations classify scanner emission levels and mandate safety interlocks, directly influencing optical engine design choices for North American market access. Major metropolitan zones host calibration and support centers serving AEC firms integrating scanning into Autodesk and Bentley BIM workflows.
Germany
Automotive OEMs and infrastructure consortia in Bavaria and Baden-Württemberg require millimeter-accurate as-built documentation for factory retrofits and tunnel monitoring. REACH restrictions on hazardous substance content force optical engine redesigns with lead-free solder formulations and revised thermal management. The industrial corridor concentrates demand for phase-based scanners in heritage documentation and indoor metrology applications.
China
MIIT dual carbon goals accelerate precision surveying adoption for renewable energy infrastructure and smart city development. National standards under GB classification govern laser product safety and measurement accuracy for domestic market access. Utility-scale solar installations in western provinces and offshore wind projects along the eastern coast deploy phase-based scanners for foundation verification and blade alignment.
India
National highway and railway corridor projects under the Ministry of Road Transport and Highways create first-time demand for mobile mapping systems. BIS certification requirements for surveying equipment shape procurement criteria among emerging engineering consultancies. Tier-2 and tier-3 urban zones in Maharashtra, Gujarat, and Karnataka witness initial scanner deployment for corridor infrastructure inventory and urban planning documentation.
Australia
Mining operators in Western Australia favor time-of-flight architectures for pit wall stability monitoring where single-setup coverage reduces survey crew exposure hours. The country's national measurement institute maintains traceability standards for geospatial instrumentation used in resource extraction. Remote mine sites drive demand for ruggedized housings and dust-sealed optics enabling continuous operation in abrasive environments.
Terrestrial Laser Scanning System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue SLAM-LS convergence and handheld scanning formats. The vendor base stratifies across three maturity tiers: heritage European metrology houses with captive optical component production, North American platform integrators bundling hardware-software-cloud stacks, and Asian precision manufacturers scaling through component cost discipline. Dominant competitive moves include backward integration into diode laser and photodetector supply, plus geographic expansion through calibration center density.
Within the heritage European tier, RIEGL Laser Measurement Systems GmbH and Zoller + Fröhlich GmbH exemplify in-house optical engine production. Among North American platform integrators, Trimble Inc. and FARO Technologies, Inc. occupy positions emphasizing tightly integrated hardware-software bundles and service density respectively. Hexagon AB and Leica Geosystems AG sit within the metrology-specialist archetype, representing precision surveying heritage extending into terrestrial laser scanning applications.
| Leading Market Players |
|---|
| RIEGL Laser Measurement Systems GmbH |
| Topcon Corporation |
| Hexagon AB |
| Zoller + Fröhlich GmbH |
| Teledyne Technologies, Inc. |
| Trimble Inc. |
| Leica Geosystems AG |
| NavVis GmbH |
| FARO Technologies, Inc. |
| Others |
Supply Flow & Price Mechanics
Computational geometry specialists concentrated in Germany's industrial corridor command wage premiums that compress margins on premium-tier phase-based scanners while widening spreads to economy-tier time-of-flight units sourced from Asian manufacturing hubs. This labor-cost differential between European metrology engineering and East Asian component assembly feeds directly into three-tier pricing stratification across the vendor base.
Pricing Analysis
Input-cost pass-through from photodetector supply volatility anchors pricing dynamics across all tiers. Three-tier pricing structure across premium, standard, and economy levels separates RIEGL and Leica Geosystems certification-grade instruments from Trimble's bundled hardware-software mid-tier offerings and emerging Asian OEM economy units. Price differentiation hinges on ISO 19130 compliance certification and after-sales calibration network density. Cost compression in the economy tier is intensifying because photogrammetry substitution erodes entry-level scanner demand. Research institutions and grant-funded archaeology programs exhibit highest price sensitivity; mining operators with pit-safety compliance mandates show least.
Supply Chain Analysis
Freight cost escalation from East Asian foundries to European assembly plants compresses landed margins on photodetector-dependent optical engines. Supply concentrates in China for diode laser substrates, Germany for precision optomechanical housings, and Japan for avalanche photodiode arrays. Raw material dependencies span rare-earth-doped laser crystals, high-purity aluminum for thermal management, and specialty epoxy formulations for vacuum-sealed optics. Single-source vulnerability in East Asian semiconductor foundries poses structural risk as geopolitical trade policies disrupt availability. Distribution runs through manufacturer-direct calibration centers for premium tiers and regional equipment distributors for standard and economy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage returns for vendors relocating final assembly to India to exploit BIS certification proximity and lower labor costs versus German production, while maintaining optical engine sourcing from established European suppliers to preserve precision specifications.
For Market Incumbents: Deploy captive photodetector supply as the primary defensive lever. Backward integration into diode laser production at RIEGL and Zoller + Fröhlich insulates beam quality control from East Asian foundry disruptions. Channel control through dedicated calibration center expansion in China's tier-2 cities counters emerging domestic OEM price pressure. SLAM-LS handheld convergence from NavVis and indoor mobile mapping entrants threatens tripod-based scanner volumes in confined industrial environments; incumbents must accelerate hybrid architecture R&D to neutralize format substitution. For New Entrants and Emerging Players: Surveying software resellers represent the most accessible channel partner type for market penetration. India's tier-2 and tier-3 urban zones under the Ministry of Road Transport and Highways corridor buildout offer the most penetrable white-space for first-time mobile mapping system deployment. Heritage documentation applications in Italy and France present secondary entry points through grant-funded institutional procurement with lower incumbent switching costs. A go-to-market angle emphasizing cloud-native processing subscriptions displaces perpetual-license incumbents among mid-sized surveying firms seeking operational expenditure treatment. For Investors and Strategic Acquirers: Valuations sit cheapest among Asian precision manufacturers scaling through component cost discipline rather than brand premium capture. Long-term viability over the projection horizon favors vendors with demonstrated ISO 19130 certification engineering and established public-sector procurement eligibility in European markets. Acquisition targets should display captive optical component production or SLAM algorithm IP portfolios. The signal to watch as inflection indicator is BIS certification completion rates among Indian engineering consultancies, signaling addressable market expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diode Laser Production | RIEGL's in-house beam quality control insulates delivery timelines from East Asian foundry disruptions. |
| Hybrid Phase-Time-of-Flight Architecture Launch | Construction contractors eliminate crew changes across diverse indoor-outdoor site conditions. |
| Cloud-Native Processing Platform Integration | Trimble and FARO capture recurring revenue through subscription displacement of perpetual licenses. |
| Calibration Center Geographic Expansion | Service density in China's tier-2 cities counters domestic OEM price competition. |
| SLAM-LS Convergence Product Development | Handheld scanning formats displace tripod-based workflows in confined industrial environments. |
Methodological Framework
Bottom-up construction and mining end-use modeling reconciled against top-down optical component supply tracking forms the analytical core of this study. Primary interviews with surveying firm principals, BIM integration specialists, mining pit engineers, heritage conservation officers, and geomatics procurement managers combined with secondary validation from SEC filings, customs trade databases, EASA drone-permission registries, and ISO certification body records. Triangulation between field equipment deployment data and vendor shipment disclosures ensures volume estimates align with observed installation patterns across German automotive corridors and Chinese renewable energy sites.
Historical trendline analysis of phase-based versus time-of-flight unit shipments establishes baseline growth trajectories across the projection horizon. The analytical framework models segmentation across scanner architecture, end-user vertical, technology integration tier, and application deliverable format. CAGRs derive from fitted growth curves adjusted for technology substitution effects and regulatory compliance timeline friction. Industry-specific forecast inputs include MIIT dual carbon policy implementation velocity and EU Green Deal building renovation mandate adoption rates among member states.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to photodetector supply chain restructuring and SLAM-LS convergence adoption curves. Forecasts reflect documented assumptions regarding BIM mandate expansion, semiconductor trade policy stability, and cloud processing subscription conversion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Facial Tracking Solution Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Vision Positioning System Market
Sensors
Lidar in Mapping Market
Sensors
Safety Motion Control System Market
Sensors
Indoor Location Market
Sensors
Traffic Sensor Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
2D Barcode Reader Market
Sensors
Real Time Location System Market
Sensors
Industrial Barcode Scanners Market
Sensors
Europe Lidar Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Beacon Technology Market
Sensors
Underground Utility Mapping Market