
 Convertible Roof Control Unit Market | 2026-2036
Convertible Roof Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Convertible Roof Control Unit Market Outlook
Buyer concentration among premium European and North American OEMs is rebalancing as Chinese electric vehicle manufacturers enter the convertible segment with localized supply chains. Webasto Group leverages its integrated roof systems portfolio to sustain engineering partnerships across German luxury brands. Magna International Inc. anchors North American production capacity through dedicated comfort electronics facilities in Michigan and Ontario. Continental AG competes on sensor fusion capabilities that merge roof position data with advanced driver assistance systems.
A convertible roof control unit governs the electromechanical deployment, stowage, and sealing of retractable automotive roof assemblies through hydraulic actuators, electric motors, or hybrid drive configurations, typically operating at 12V or 48V vehicle electrical architectures with cycle counts exceeding 50,000 operations. The unit manages position feedback through Hall-effect or inductive sensors while coordinating latch sequencing, tonneau cover alignment, and wind deflector deployment to ensure occupant safety and weather sealing integrity. Electrical controls and sensor integration segments command premium positioning due to their direct linkage with vehicle network architectures and diagnostic requirements. Hybrid systems represent the fastest-expanding technology dimension as manufacturers blend hydraulic force density with electric precision to accommodate heavier glass and composite roof panels in electric vehicle architectures.
NHTSA Federal Motor Vehicle Safety Standard 216a mandates roof crush resistance thresholds that directly influence control unit load monitoring algorithms and emergency deployment logic. ECE R94 and ECE R95 frameworks govern European occupant protection during rollover events, compelling calibration of roof position sensors with seatbelt pretensioner and curtain airbag trigger systems. EU REACH restrictions on hexavalent chromium and specific hydraulic fluids are forcing material substitutions in seal coatings and actuator lubricants. Stakeholders must monitor the divergence between 48V mild-hybrid electrical standards and full battery electric vehicle architectures to ensure control unit compatibility across emerging powertrain platforms.
Market Dynamics
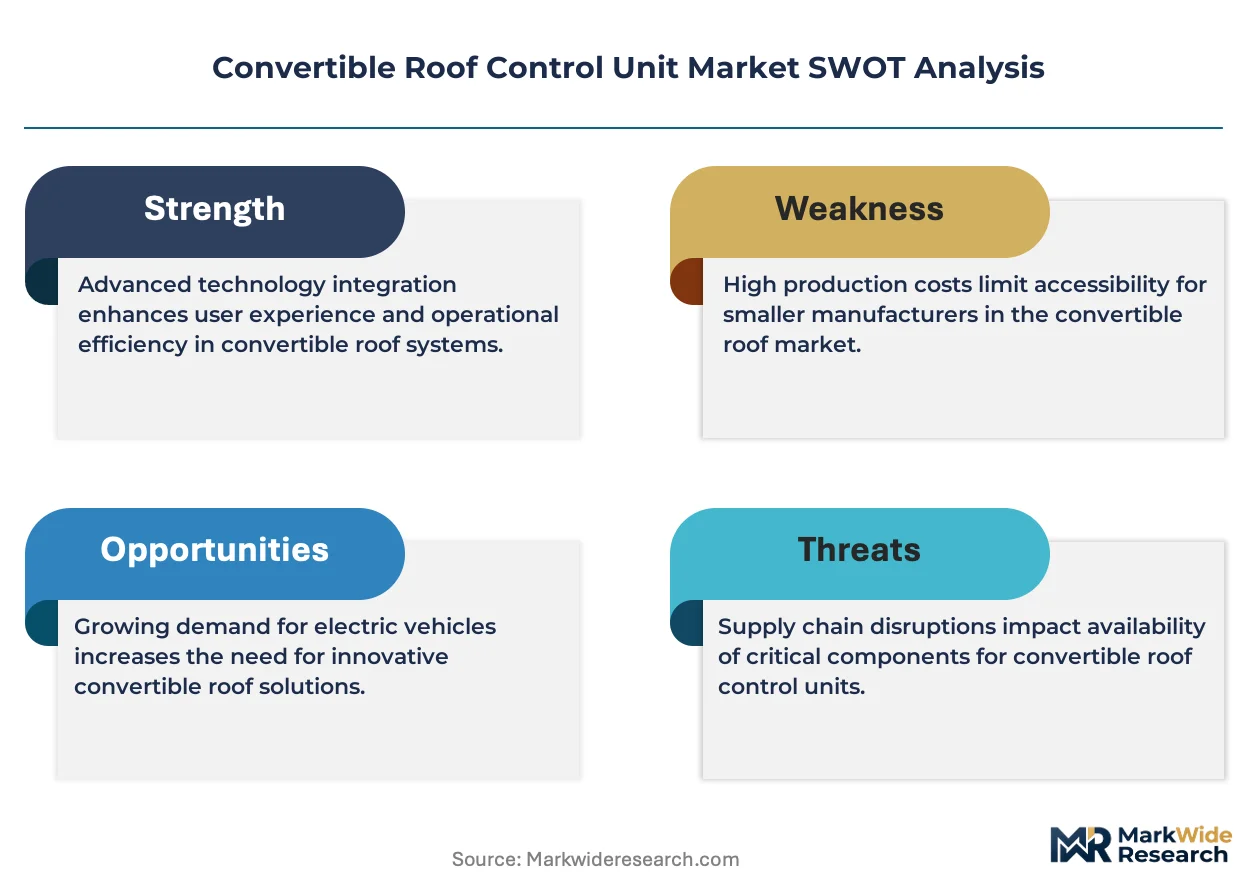
The transition from 12V to 48V electrical architectures in premium electric vehicles is compressing control unit design cycles and forcing simultaneous compatibility across hybrid and full-electric platforms.
Growth Catalysts
- EU pedestrian protection mandates:ECE R127 regulations require active hood and roof edge systems that integrate with convertible roof position sensors, expanding sensor fusion requirements in European luxury platforms.
- Glass panel proliferation:Heavier transparent polycarbonate and electrochromic roof modules in electric convertibles demand hybrid hydraulic-electric actuation with precise load monitoring.
- Japan's luxury EV segment:Domestic OEMs are developing dedicated convertible variants for battery-electric sports cars, creating localized demand for 48V-compatible control architectures.
Market Restraints
- Copper and rare-earth magnet costs:Neodymium price volatility directly impacts electric motor actuator margins, compressing tier-two supplier profitability.
- German supplier concentration:Hydraulic pump and seal manufacturing clusters in Baden-Württemberg create single-source vulnerability for just-in-time assembly lines.
- REACH substance restrictions:Hexavalent chromium bans in seal coatings force qualification of alternative corrosion inhibitors with unproven long-term durability.
Strategic Opportunities
- United States aftermarket channel:Independent service networks for legacy soft-top convertibles lack diagnostic tool access, creating white space for retrofit control module suppliers.
- ADAS convergence:Roof position data integration with lane-keeping and automatic emergency braking systems enables new safety-critical software revenue streams.
- India's emerging luxury segment:Import tariff reductions on completely knocked-down kits under the PLI scheme position the country for convertible assembly localization.
Industry Challenges
- Embedded software certification:ISO 26262 ASIL-D compliance for safety-critical roof deployment algorithms extends development timelines by 14-18 months.
- Legacy platform integration:Retrofitting 48V control units into existing 12V vehicle architectures requires costly voltage converter modules and harness redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Convertible Roof Control Unit Market |
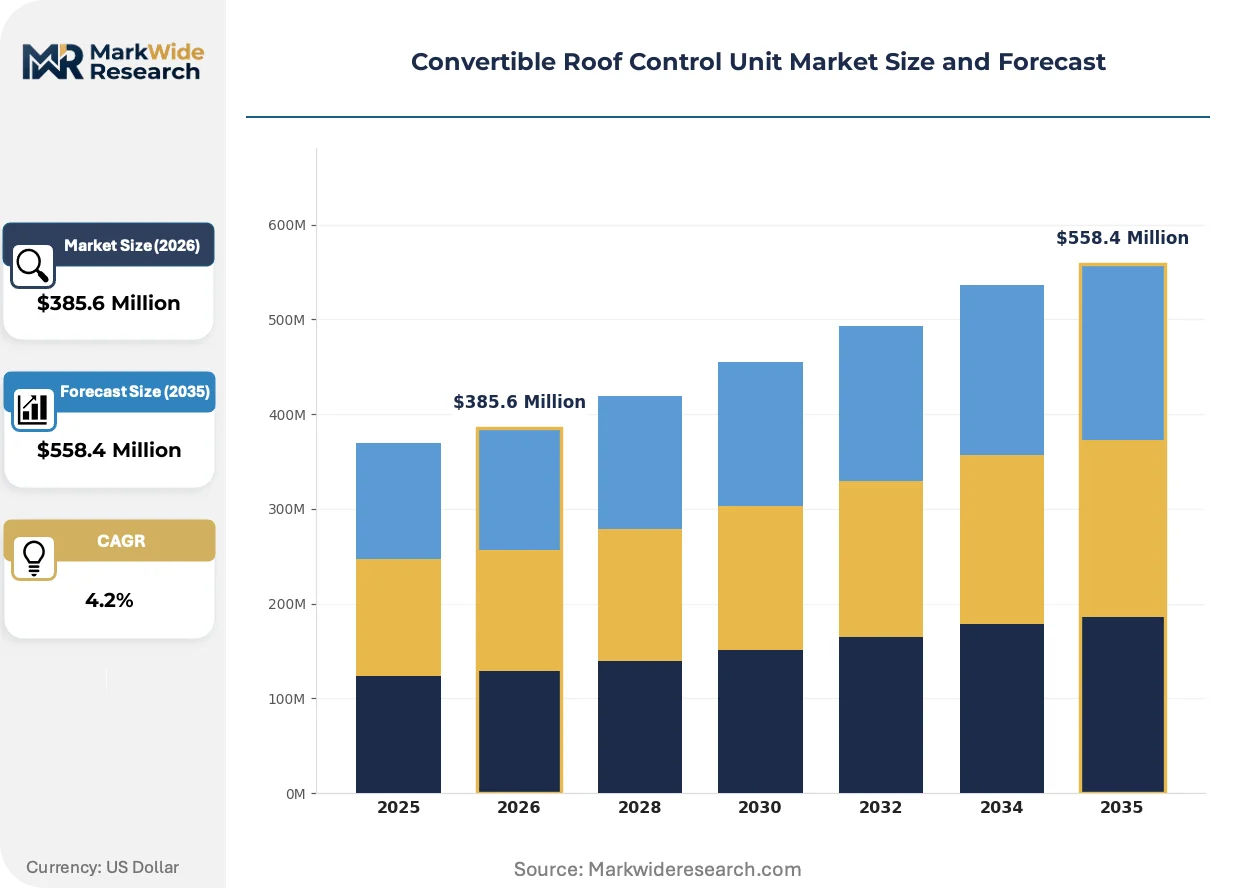
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $558.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Systems, Electrical Controls, Pneumatic Systems, Hybrid Systems Technology: Microcontroller-Based, Wireless Communication, Sensor Integration, Drive Mechanism End User: OEMs, Aftermarket Providers, Automotive Manufacturers, Vehicle Assemblers Application: Luxury Vehicles, Sports Cars, Convertibles, Electric Vehicles |
| Companies Covered | Haartz Corporation, Valmet Automotive Inc., Webasto Group, Aisin Seiki Co. Ltd., Hoerbiger Automotive Komfortsysteme GmbH, Magna International Inc., U-Shin Ltd, GAHH LLC., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Convertible Roof Control Unit Market Strategic Shifts
Control unit engineering is pivoting from discrete mechanical systems to software-defined architectures that coordinate roof mechanics with vehicle-wide safety networks.
Electrohydraulic hybrid actuation is electrifying convertible roof mechanisms by blending hydraulic force density with electric precision for heavy glass panels. German luxury OEMs are adopting these systems across new electric roadster platforms. The technology is electrifying competitive positioning by enabling tier-one suppliers to capture sensor integration value previously held by separate electronics vendors.
NHTSA Federal Motor Vehicle Safety Standard 216a mandates roof crush resistance thresholds that exceed 3.5 times vehicle weight. The regulation forces recalibration of load monitoring algorithms and emergency deployment logic in all US-market convertibles. Premium electric vehicle platforms in California and Michigan are responding with redundant position sensor architectures and faster hydraulic pump ramp rates.
Buyer concentration among consolidated luxury OEMs has compressed component sourcing cycles from 48 to 24 months. Tier-one suppliers are displacing traditional two-step distribution through direct engineering partnerships with vehicle program offices. This pattern is most visible in Germany, where Webasto and Continental maintain co-located engineering teams at BMW and Mercedes-Benz development centers.
Convertible Roof Control Unit Market Segmentation
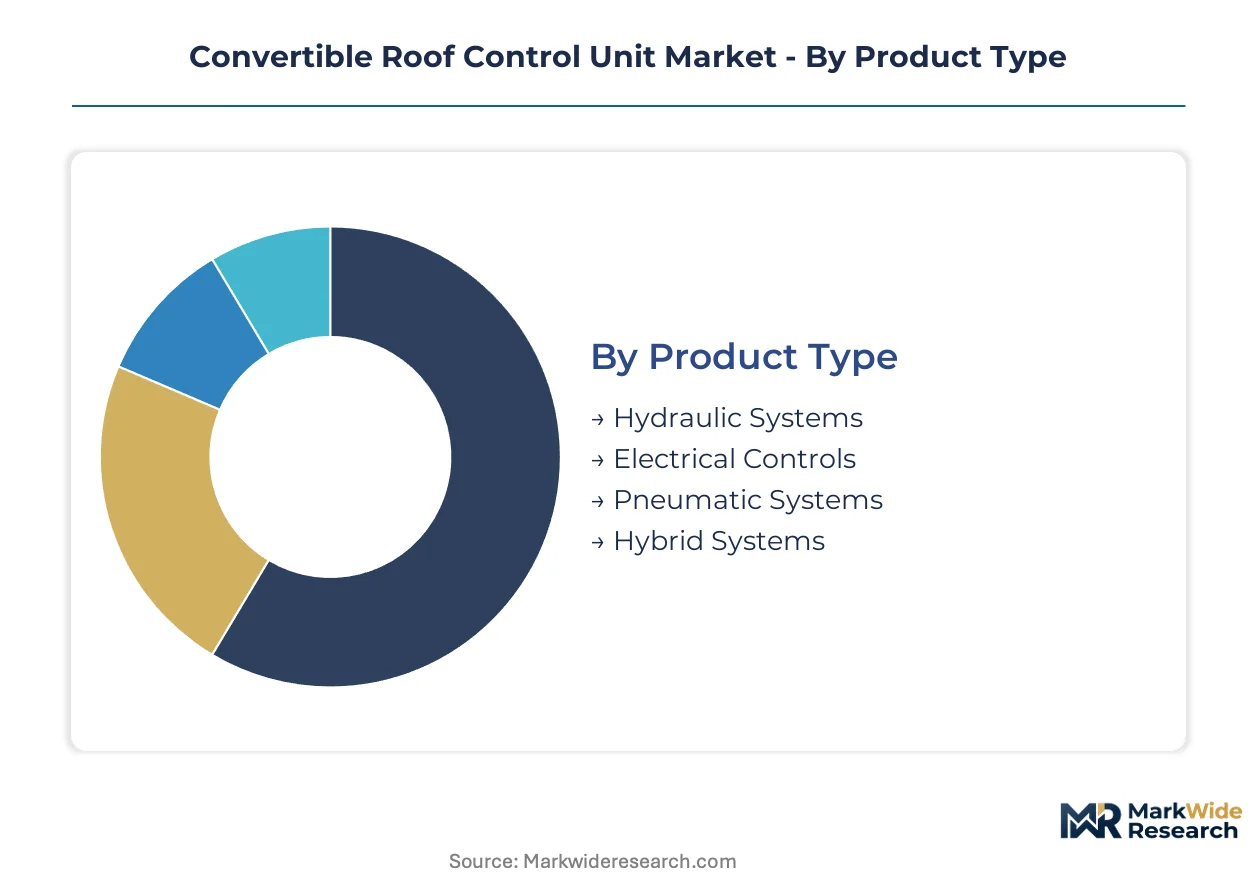
Convertible roof control unit procurement decisions hinge on electrical architecture compatibility, actuation force requirements, and integration complexity with vehicle safety networks. Buyers evaluate segments based on powertrain voltage standards, panel weight trajectories, and software certification burdens.
Product Type:
Cost tier determines supplier selection, with premium electric vehicle platforms demanding precision actuation while mass-market convertibles prioritize acquisition economics.
- Hydraulic Systems:These units deploy pressurized fluid circuits to generate high-force actuation for heavy folding metal roofs and multi-layer soft tops. German luxury OEMs in Stuttgart and Munich specify hydraulic systems for their electric roadster programs where glass panel weights exceed 45 kilograms. NHTSA roof crush resistance mandates are compressing design cycles for hydraulic pump calibration algorithms.
- Hybrid Systems:Blending hydraulic force density with electric motor precision, these architectures manage electrochromic and transparent polycarbonate panels in battery-electric convertibles. Japanese OEMs in Toyota City and German manufacturers in Ingolstadt are expanding adoption as 48V electrical architectures proliferate across premium platforms. These configurations are gaining share fastest as glass roof module weights climb in electric vehicle architectures.
- Electrical Controls:Pure electric actuation using rare-earth magnet motors and position feedback sensors serves lightweight soft-top applications in entry-luxury segments.
- Pneumatic Systems:Compressed air mechanisms retain niche positioning in specialty vehicle conversions and aftermarket retrofits where electrical harness modification is prohibitive.
Hydraulic systems lead on scale; hybrid systems lead on momentum.
Technology:
Application specificity shapes technology adoption, with safety-critical roof deployment demanding certified software architectures while convenience features enable wireless connectivity.
- Sensor Integration:Hall-effect and inductive position sensors coordinate latch sequencing, tonneau alignment, and wind deflector deployment through real-time feedback loops. California-based electric vehicle manufacturers and Bavarian luxury OEMs require redundant sensor architectures to satisfy NHTSA rollover protection mandates. ISO 26262 ASIL-D compliance timelines extend development cycles by 14-18 months for this segment.
- Microcontroller-Based:Dedicated ECUs executing roof deployment algorithms through deterministic real-time operating systems anchor mainstream production volumes. Michigan-based automotive manufacturers and Ontario assembly facilities specify these units for 12V legacy platforms and 48V mild-hybrid architectures. The segment concentrates procurement among German and North American semiconductor suppliers.
- Wireless Communication:Bluetooth and ultra-wideband-enabled diagnostic interfaces support aftermarket service tooling and remote roof status monitoring.
- Drive Mechanism:Motor and gearbox assemblies providing rotational-to-linear motion conversion serve as replaceable subcomponents in modular control unit architectures.
Microcontroller-based architectures dominate current volumes; sensor integration commands the steepest expansion trajectory.
End User:
Customer type dictates contracting structures, with vehicle assemblers negotiating system-level procurement while aftermarket channels fragment across independent service networks.
- OEMs:Original equipment manufacturers specifying complete roof systems integrate control units through tier-one engineering partnerships with dedicated program offices. German luxury brands in Baden-Württemberg and premium electric vehicle manufacturers in California compress sourcing cycles from 48 to 24 months through direct supplier co-location. These buyers demand synchronized development with vehicle network architectures and ADAS integration.
- Automotive Manufacturers:Volume producers operating assembly lines across multiple geographies standardize control unit specifications across convertible and fixed-roof variants to maximize component scale. Japanese OEMs in Hiroshima and American manufacturers in Detroit leverage common electrical architectures across sports car and mainstream passenger vehicle programs. Procurement concentrates among suppliers with dual 12V and 48V platform compatibility.
- Aftermarket Providers:Independent distributors and service networks supply replacement modules for legacy soft-top convertibles outside warranty periods.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders purchasing knocked-down kits for localized assembly.
OEMs anchor premium segment value capture; automotive manufacturers dominate unit volumes.
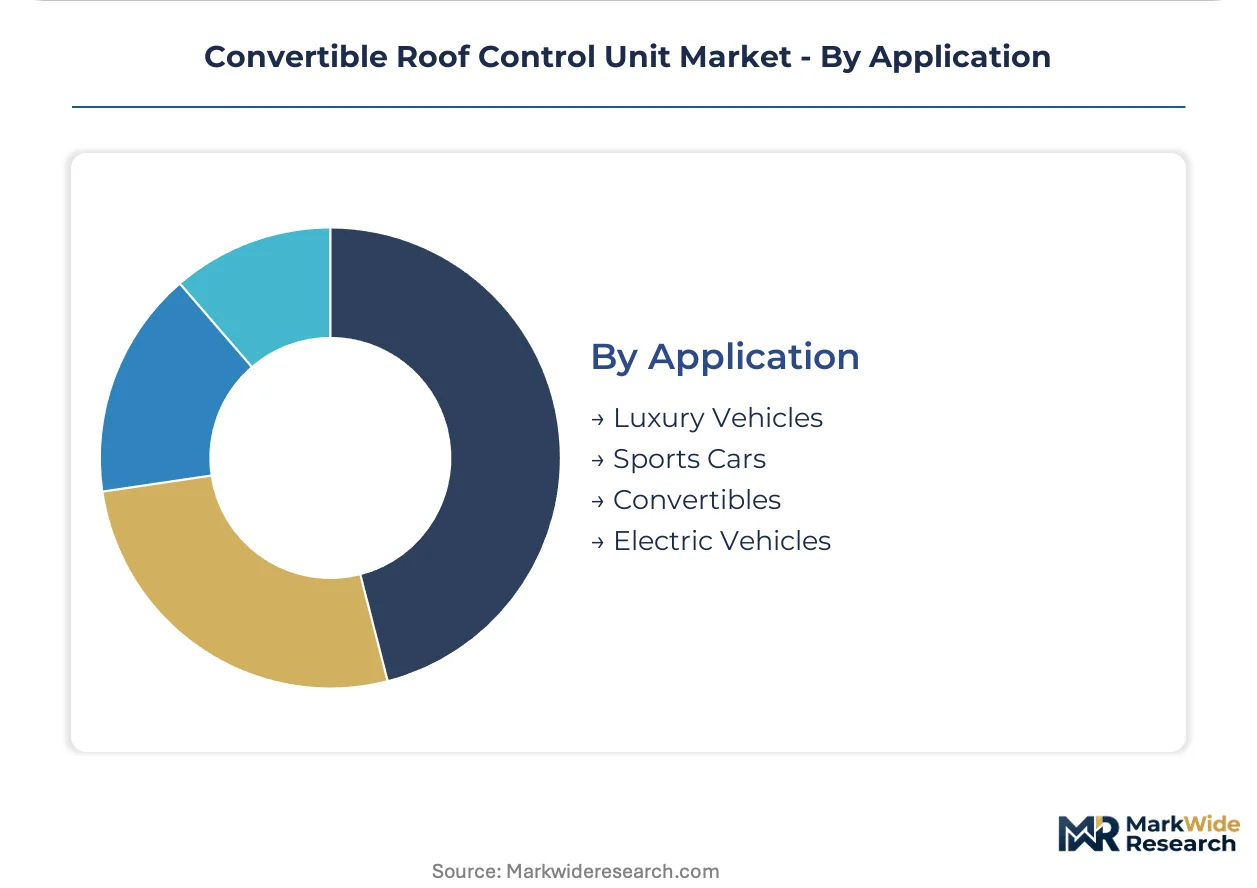
Application:
Volume concentration varies sharply by vehicle category, with electric vehicle platforms redefining material specifications while sports cars retain specialized lightweight requirements.
- Electric Vehicles:Battery-electric convertibles demand 48V-compatible control architectures managing heavier transparent and electrochromic roof modules. German manufacturers in Zuffenhausen and Japanese OEMs in Nagoya are developing dedicated electric roadster platforms with hybrid actuation systems. ECE R127 pedestrian protection mandates in Europe are expanding sensor fusion requirements for active hood and roof edge integration.
- Luxury Vehicles:Premium sedans and grand tourers with retractable roof options prioritize acoustic sealing and deployment refinement over cycle speed. British manufacturers in Gaydon and Italian OEMs in Modena specify multi-layer soft tops with precision latch sequencing. These applications sustain hydraulic system demand despite electrification pressures elsewhere.
- Sports Cars:Performance-oriented convertibles emphasize weight minimization and rapid deployment cycles.
- Convertibles:Dedicated open-top vehicle architectures spanning mass-market to ultra-premium positioning.
Luxury vehicles sustain incumbent technology revenues; electric vehicles are restructuring supplier competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters outpace Japanese production scale in convertible roof control unit deployment, while United States regulatory pressure reshapes design priorities faster than European standard-setting.
United States
NHTSA Federal Motor Vehicle Safety Standard 216a mandates roof crush resistance thresholds exceeding 3.5 times vehicle weight. California-based electric vehicle manufacturers and Michigan assembly facilities demand redundant position sensor architectures. Detroit-area automotive manufacturers compress sourcing cycles through direct tier-one engineering partnerships.
Germany
Baden-Württemberg hydraulic pump clusters face single-source vulnerability amid just-in-time assembly line dependencies. EU REACH restrictions on hexavalent chromium force material substitutions in seal coatings. Stuttgart and Munich luxury OEMs specify hybrid electrohydraulic systems for electric roadster programs.
Japan
Domestic OEMs in Toyota City and Nagoya develop dedicated convertible variants for battery-electric sports cars. METI industrial policy supports 48V-compatible control architecture localization. Japanese luxury EV segment expansion creates concentrated demand for precision actuation systems.
China
Premium electric vehicle manufacturers enter the convertible segment with localized supply chains, rebalancing buyer concentration. MIIT standards for new energy vehicles influence electrical architecture specifications. Yangtze River Delta assembly hubs integrate control units with domestic battery-electric platforms.
India
Import tariff reductions on completely knocked-down kits under the PLI scheme position the country for convertible assembly localization. Maharashtra and Gujarat automotive corridors attract component supplier investment. BIS certification requirements shape control unit qualification timelines for luxury vehicle programs.
Convertible Roof Control Unit Market Competitive Environment
German producers anchor the integrated systems tier; North American specialists hold comfort electronics and sensor fusion positions. The vendor base concentrates among tier-one automotive suppliers with dedicated program offices at major OEM development centers. Two strategic archetypes dominate: full-system integrators managing complete roof mechanisms, and electronics-focused suppliers capturing sensor and control module value. Competitive moves center on co-located engineering partnerships and 48V platform compatibility investments.
Within the full-system integrator tier, Webasto Group and Magna International Inc. represent engineering partnership models with direct OEM program office integration. Continental AG occupies a position bridging electronics and sensor fusion capabilities. Hoerbiger Automotive Komfortsysteme GmbH exemplifies the specialized comfort systems archetype with German GmbH structure. These three anchors illustrate the geographic split between European integrated system leadership and North American electronics specialization.
| Leading Market Players |
|---|
| Haartz Corporation |
| Valmet Automotive Inc. |
| Webasto Group |
| Aisin Seiki Co. Ltd. |
| Hoerbiger Automotive Komfortsysteme GmbH |
| Magna International Inc. |
| U-Shin Ltd |
| GAHH LLC. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Captive hydraulic pump production in Baden-Württemberg anchors supplier pricing power for German luxury OEMs while compressing tier-two margins through just-in-time dependency. This upstream control over seal coatings and actuator calibration creates asymmetric leverage between integrated system houses and component specialists serving North American electric vehicle platforms.
Pricing Analysis
Capacity additions in Michigan and Ontario are reshaping price floors for 48V-compatible control architectures as Magna International expands comfort electronics facilities. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified sensor fusion modules from microcontroller-based legacy units and aftermarket retrofit kits. Cost compression in entry-luxury electric actuation intensifies because neodymium magnet volatility feeds directly into electric motor bill-of-materials. Automotive manufacturers operating dual 12V and 48V platforms exhibit highest price sensitivity; German luxury OEMs with co-located engineering partnerships show lowest sensitivity due to lifecycle value capture.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through tier-one engineering partnerships at BMW and Mercedes-Benz development centers. Manufacturing concentrates in Germany, Japan, and the United States, with Baden-Württemberg hydraulic clusters and Michigan electronics facilities anchoring regional supply. The supply chain draws from rare-earth magnet processors, semiconductor foundries, and specialized seal coating formulators. Single-source vulnerability in German hydraulic pump manufacturing creates systemic risk for just-in-time assembly lines serving European luxury platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Convertible roof control unit procurement functions as a geographic-arbitrage play between EU REACH compliance costs and United States NHTSA certification burdens, with the regulatory differential favoring North American aftermarket channel investment.
For Market Incumbents: Hedge against Chinese electric vehicle manufacturer entry by securing backward integration into rare-earth magnet supply through offtake agreements with processors outside single-source jurisdictions. Reinforce engineering partnership stickiness through co-located 48V platform development teams at OEM program offices. Defensive priority rests on sensor fusion IP that merges roof position data with ADAS architectures. For New Entrants and Emerging Players: Wireless diagnostic interfaces for legacy soft-top convertibles represent the most penetrable white-space target, as independent United States service networks lack OEM tooling access. Retrofit control modules for 12V architectures offer secondary entry point given legacy platform installed base. Go-to-market angle should emphasize subscription-enabled remote monitoring capabilities that bypass dealership channel capture. For Investors and Strategic Acquirers: Consolidation pressure builds where tier-two suppliers face simultaneous REACH substance restriction compliance and neodymium cost volatility without scale to absorb shocks. Long-term viability favors electronics-focused specialists with sensor fusion capabilities over pure mechanical system houses. Signal to watch: OEM announcements of dedicated electric roadster platforms requiring hybrid electrohydraulic architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Dual 12V and 48V compatibility maximizes component reuse across hybrid and battery-electric vehicle programs. |
| Software-Defined Vehicle Investment | ISO 26262 ASIL-D certification for roof deployment algorithms opens safety-critical software revenue streams. |
| Geographic Manufacturing Footprint | Michigan and Ontario facilities anchor North American production capacity for NHTSA-compliant architectures. |
| Battery Supply Agreement | 48V electrical architecture alignment with electric vehicle platform roadmaps ensures powertrain compatibility. |
| Charging Infrastructure Partnership | Integration with premium electric vehicle ecosystems in California and Germany sustains convertible segment relevance. |
Study Parameters
Multiple input streams — OEM platform engineering directors, tier-one supplier procurement leads, aftermarket distributor operations heads, and semiconductor component specialists — were reconciled through structured primary interviews and secondary validation. Regulatory filings from NHTSA and ECHA, vehicle production databases, and customs trade records anchored quantitative triangulation. Bottom-up segmentation modeling and top-down market sizing approaches were cross-referenced for convergence.
Historical shipment patterns were cross-referenced against expert panel inputs regarding 48V architecture transition timing and glass panel weight trajectories. Segmentation dimensions spanned actuation technology, sensor integration level, electrical architecture voltage, and regional production cluster. CAGRs were derived from slope analysis of technology adoption curves and OEM platform launch schedules, with electric vehicle content-per-vehicle assumptions stress-tested against battery-electric roadster program announcements.
The model holds under stable rare-earth magnet pricing and sustained NHTSA rollover standard enforcement; deviation in REACH substance restriction scope or Chinese electric vehicle export tariff regimes would shift supplier competitive positioning. Forecasts reflect documented assumptions regarding hybrid system penetration rates and ADAS convergence timelines. Periodic stress-testing of base assumptions is recommended given regulatory divergence between 48V mild-hybrid and full battery electric architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
United States Car Bumper Guard Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Car Canopies Market