
 Automotive Cabin Insulation Market | 2026-2036
Automotive Cabin Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cabin Insulation Market Analytics
Buyer concentration among premium electric vehicle OEMs is shifting procurement power toward platforms requiring multi-layer acoustic and thermal packages. Autoneum Holding AG leverages vertical integration from fiber processing to module assembly, sustaining cost advantages across European and Chinese supply chains. BASF SE anchors its position through polyurethane foam chemistry leadership, while Saint-Gobain competes via glass wool innovations for high-temperature firewall applications.
Automotive cabin insulation comprises engineered barrier, absorption, and damping materials—typically fiberglass, polyurethane foam, or polyester blends—installed at interior surfaces to attenuate airborne and structure-borne noise while managing thermal transfer. These materials must satisfy flammability, fogging, and volatile organic compound thresholds specified under OEM material standards and regional safety codes. Foam-based solutions lead in value contribution due to their weight advantages in electric vehicle architectures, while spray application methods represent the fastest-growing installation category as OEMs pursue automation and labor reduction in assembly plants. Pre-assembled module formats retain margin concentration where tier suppliers integrate insulation with carpet and trim subsystems.
The US NHTSA and EPA jointly shape material selection through crash safety and fuel economy regulations that penalize weight addition without acoustic benefit. Europe's ECHA REACH framework restricts certain flame retardants and isocyanate formulations, compelling reformulation investments across the supply base. China's MIIT enforces GB standards for interior air quality that limit volatile emissions from insulation substrates. Stakeholders must monitor regulatory divergence between these jurisdictions when configuring global product platforms and qualification strategies.
Market Dynamics
Premium electric vehicle platforms are consolidating procurement power around multi-layer acoustic-thermal packages, compressing supplier margins while elevating technical qualification barriers for cabin insulation materials.
Growth Catalysts
- China's dual carbon goals:MIIT emissions mandates accelerate lightweight foam adoption across domestic EV production lines, creating pull-through for acoustic substrate suppliers.
- Spray application automation:Assembly plant robotics integration reduces labor content and enables precision material deposition at firewall and floorpan interfaces.
- Stuttgart-Wolfsburg corridor:Germany's manufacturing concentration sustains demand for glass wool and polyurethane modules serving premium OEM final assembly.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs fluctuate with crude oil indices, compressing foam producer margins without pass-through mechanisms.
- REACH chemical restrictions:ECHA flame retardant limitations force reformulation cycles that extend qualification timelines by 18-24 months.
- Recycled cotton fiber substitution:Nonwoven natural fiber alternatives displace synthetic absorption materials in entry-segment vehicle programs.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for domestic EV manufacturing create greenfield demand for localized insulation module assembly.
- GB standards air quality enforcement:China's interior VOC limits favor low-emission foam chemistries from qualified suppliers.
- Recyclable mono-material designs:Single-substrate acoustic packages simplify end-of-life recovery and align with EU Green Deal circularity requirements.
Industry Challenges
- Acoustic simulation talent scarcity:CAE modeling for multi-physics noise-vibration-harshness prediction requires specialized engineers concentrated at OEM technical centers.
- Flammability certification bottlenecks:FMVSS 302 and ECE R118 testing queue delays compress program launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cabin Insulation Market |
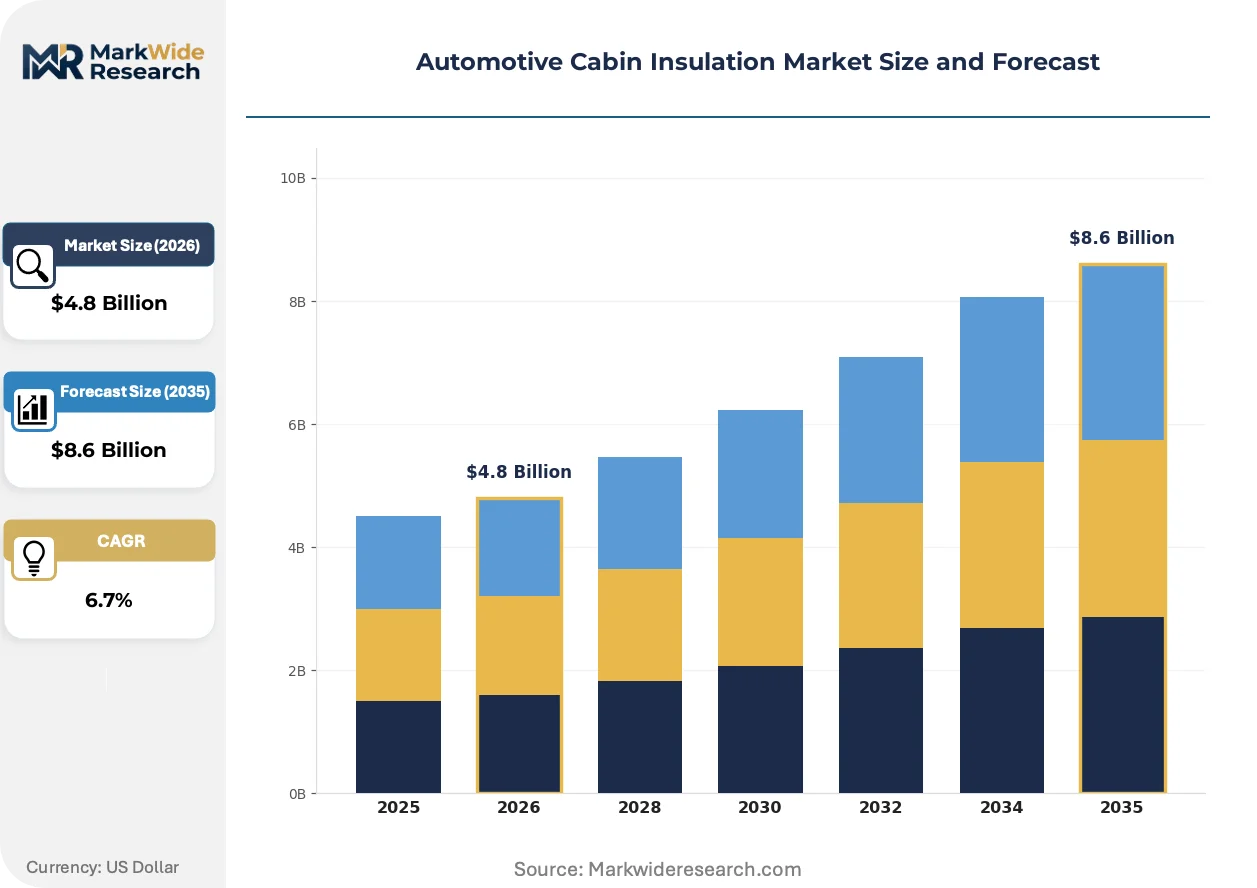
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
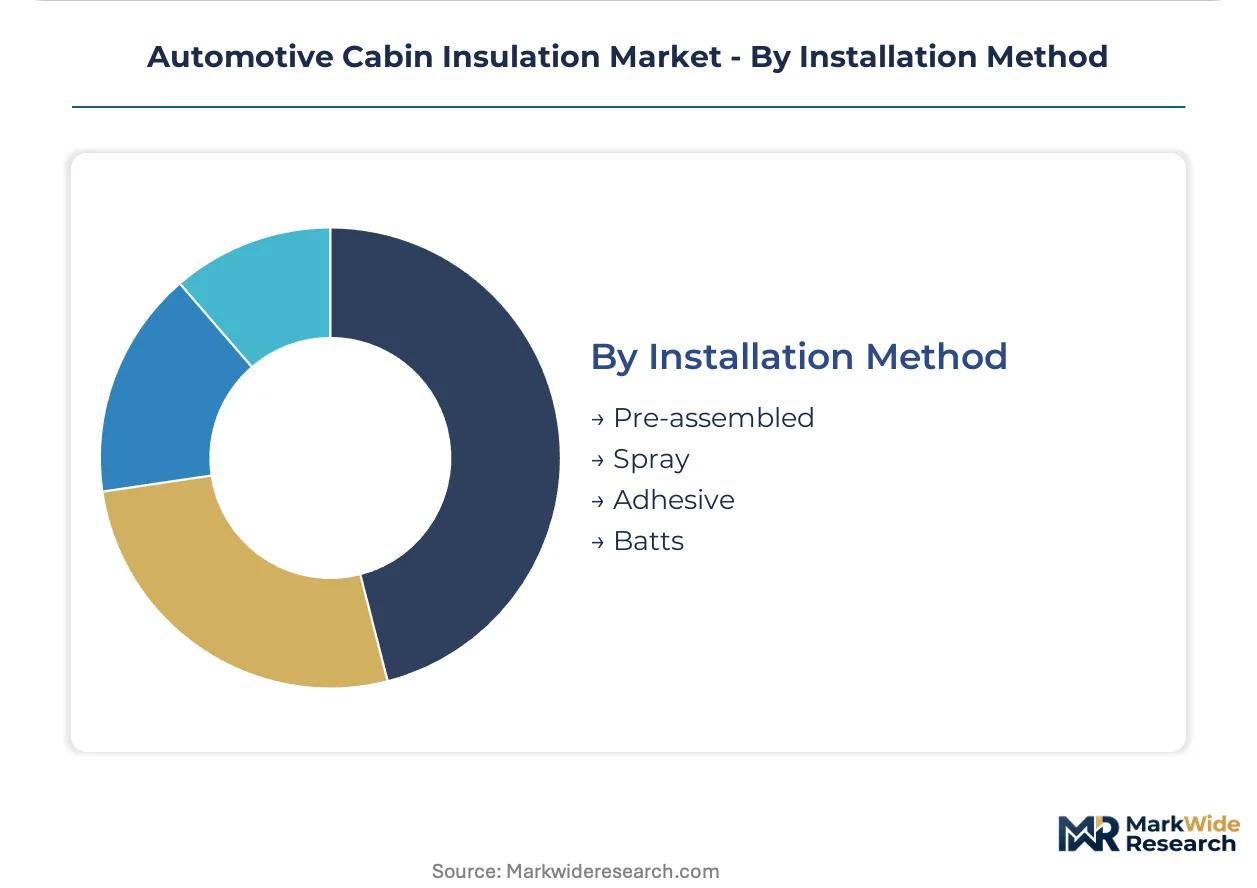
| Segmentation | Material Type: Fiberglass, Foam, Cotton, Polyester Application Area: Floor, Roof, Door, Firewall Vehicle Type: Passenger Cars, SUVs, Trucks, Vans Installation Method: Pre-assembled, Spray, Adhesive, Batts |
| Companies Covered | Autoneum Holding AG, 3M Company, BASF SE, Covestro AG, DuPont, Huntsman Corporation, Toray Industries, Saint-Gobain, Adient plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cabin Insulation Market Evolving Landscape
Material science convergence with automated manufacturing is reconfiguring how acoustic and thermal performance get engineered into vehicle architectures, shifting value capture toward process-integrated suppliers.
Active noise cancellation hardware is integrating with traditional passive insulation layers, creating hybrid acoustic systems that reduce material mass while maintaining cabin quietness targets. Premium EV platforms from European and Chinese OEMs are adopting these configurations fastest. This convergence is integrating electronics suppliers into insulation procurement decisions, fragmenting historical tier relationships.
REACH chemical restrictions are compelling polyurethane foam reformulations that eliminate halogenated flame retardants without compromising fire safety ratings. BASF and competing chemical suppliers have invested in phosphorus-based alternatives that meet ECHA compliance windows. European firewall applications face the tightest substitution timelines, with qualification cycles compressing supplier R&D budgets.
Modular pre-assembly contracts are displacing in-plant insulation installation at premium OEMs, concentrating procurement decisions at tier-one integrators rather than individual material suppliers. Autoneum and similar subsystem specialists now specify substrate chemistry and application method. This pattern is most pronounced in German and Chinese manufacturing corridors where final assembly automation investments are deepest.
Automotive Cabin Insulation Market Segmentation
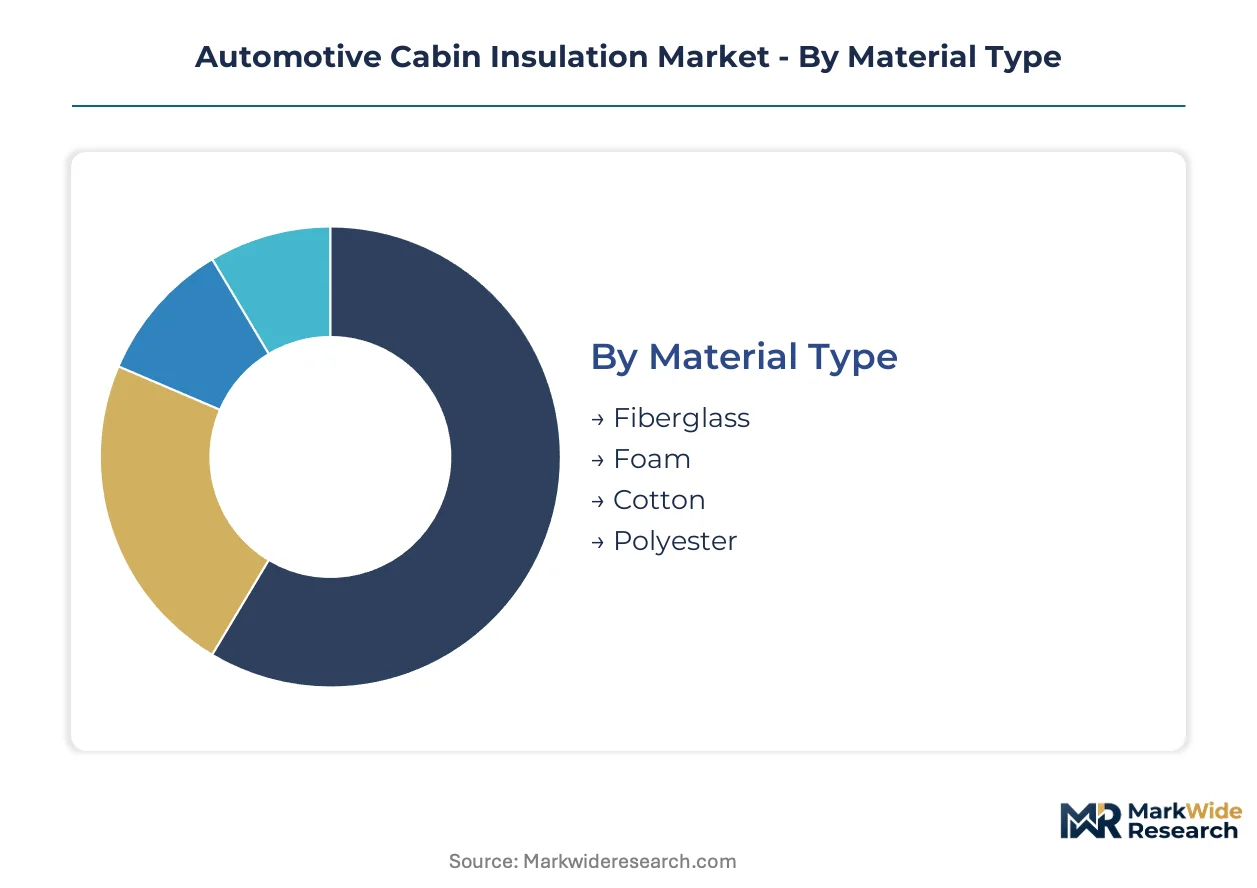
Automotive cabin insulation procurement patterns diver sharply across material chemistry, vehicle architecture, and assembly integration depth. OEM platform strategies and regulatory compliance timelines reshape which segment combinations capture investment and margin.
Material Type:
Foam commands premium electric vehicle programs seeking mass reduction without acoustic compromise; fiberglass retains firewall dominance where thermal resistance thresholds are non-negotiable.
- Foam:Polyurethane and melamine formulations deliver the lowest weight-per-decibel attenuation. MIIT lightweighting mandates across China's EV production corridors accelerate specification shifts from fiberglass to foam at floorpan and roof interfaces.
- Fiberglass:Glass wool substrates withstand sustained temperatures exceeding 400°C at engine-adjacent surfaces. Stuttgart-Wolfsburg manufacturing clusters sustain demand for E-glass formulations meeting ECE R118 flammability protocols.
- Cotton:Recycled denim and natural fiber nonwovens serve entry-segment vehicle programs in India and Southeast Asia where cost floors dominate material selection.
- Polyester:PET fiber absorption layers integrate with carpet backings through thermal bonding processes, concentrating supply among textile processors with automotive qualification histories.
Volume sits with fiberglass legacy installations; growth tilts toward foam substitution in battery-electric architectures.
Application Area:
Firewall and floorpan specifications absorb the most engineering hours due to multi-physics performance requirements spanning acoustics, thermal management, and crash safety.
- Firewall:Multi-layer barriers combining dense mass-loaded vinyl with fibrous absorption face the tightest REACH flame retardant reformulation timelines. ECHA phosphorus-based alternative qualifications are compressing European supplier R&D calendars.
- Floor:Spray polyurethane foam application methods are gaining share fastest at automated assembly plants, reducing labor content while enabling precision deposition around structural cavities and wiring harnesses.
- Roof:Headliner-integrated absorption packages prioritize low-fogging polyester substrates meeting OEM interior air quality standards, particularly stringent under China's GB/T 27630 enforcement.
- Door:Water-shedding barrier films laminated to fibrous layers must pass FMVSS 302 horizontal burn tests, creating certification bottlenecks that extend US launch timelines.
Firewall commands the highest per-vehicle material value; floor applications are climbing the fastest on automation adoption curves.
Vehicle Type:
Platform electrification intensity determines acoustic package sophistication more than traditional segment boundaries between passenger and commercial vehicles.
- Passenger Cars:Sedan and hatchback architectures in European premium segments specify active noise cancellation integration with passive foam layers, elevating electronics supplier influence over material selection.
- SUVs:Larger cabin volumes and panoramic roof openings demand enhanced roof absorption and side-window damping, concentrating procurement at tier-one integrators with CAE modeling capabilities.
- Trucks:Commercial vehicle programs prioritize thermal retention for sleeper cab applications, sustaining demand for thick fiberglass batts with foil-facing vapor barriers.
- Vans:Last-mile delivery electrification in urban European markets is creating specialized low-weight acoustic specifications for compact commercial platforms.
SUVs absorb the greatest insulation surface area per unit; passenger cars are expanding most quickly on EV platform proliferation.
Installation Method:
Assembly plant automation depth and labor cost structures determine whether insulation arrives as pre-engineered modules or in-process applied materials.
- Pre-assembled:Carpet and trim subsystem integrators specify substrate chemistry and attachment methods, consolidating procurement decisions at tier suppliers with module assembly capabilities concentrated in Germany and China.
- Spray:Robotic polyurethane deposition at firewall and floorpan interfaces eliminates cutting and fitting labor while improving acoustic consistency across vehicle variants.
- Adhesive:Pressure-sensitive and heat-activated bonding systems for barrier films require surface preparation protocols that complicate rework and repair scenarios.
- Batts:Cut-to-dimension fiberglass and cotton rolls retain share in lower-volume vehicle programs and aftermarket replacement channels where capital investment in automation is uneconomical.
Batts retain volume leadership in aftermarket and legacy platforms; spray application is gaining share fastest on OEM automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium electric vehicle OEM procurement concentrates in manufacturing corridors where acoustic-thermal package engineering intersects with final assembly automation. Germany, China, the United States, Japan, and India each anchor distinct demand patterns shaped by local regulatory frameworks and industrial clustering.
Germany
Stuttgart and Wolfsburg manufacturing clusters sustain demand for glass wool and polyurethane modules serving premium OEM final assembly. ECHA REACH restrictions on halogenated flame retardants force 18-24 month reformulation cycles among local foam suppliers. Bavaria and Baden-Württemberg house the densest concentrations of tier-one integrators with CAE modeling capabilities.
China
MIIT dual carbon mandates accelerate lightweight foam adoption across domestic EV production lines in the Yangtze River Delta. GB/T 27630 interior air quality standards favor low-emission foam chemistries from qualified suppliers. Shanghai and Guangdong manufacturing corridors concentrate spray application automation investments.
United States
NHTSA fuel economy regulations penalize weight addition without acoustic benefit, pushing OEMs toward foam substitution. FMVSS 302 flammability testing queue delays compress program launch windows for barrier film suppliers. Michigan and Ohio assembly plants retain batt-format insulation for lower-volume vehicle programs.
Japan
METI carbon neutrality targets drive active noise cancellation integration with passive insulation layers in premium EV architectures. JIS standards govern interior material emissions, creating qualification barriers for imported substrates. Kanto and Kansai manufacturing belts concentrate electronics-acoustics convergence engineering.
India
PLI scheme production-linked incentives for domestic EV manufacturing create greenfield demand for localized insulation module assembly. BIS certification requirements extend qualification timelines for foreign material suppliers. Maharashtra and Gujarat automotive corridors attract tier-one subsystem integrators.
Automotive Cabin Insulation Market Competitive Landscape
German producers anchor one tier of supply; Chinese specialists hold process-automation advantages at scale. The vendor base clusters around three strategic archetypes: chemical suppliers with foam chemistry leadership, textile processors with automotive qualification histories, and subsystem integrators controlling module assembly decisions. Capacity expansion and backward integration into fiber processing represent the dominant competitive moves as suppliers defend margin position against OEM consolidation.
Among European-based specialists, Autoneum Holding AG exemplifies the integrated subsystem archetype through captive supply of fiber processing to module assembly. BASF SE and Saint-Gobain occupy positions on the materials chemistry vector, with the former representing polyurethane formulation leadership and the latter anchoring high-temperature substrate applications. These three entities illustrate how competitive positioning fragments across material supply, chemical formulation, and subsystem integration tiers.
| Leading Market Players |
|---|
| Autoneum Holding AG |
| 3M Company |
| BASF SE |
| Covestro AG |
| DuPont |
| Huntsman Corporation |
| Toray Industries |
| Saint-Gobain |
| Adient plc |
| Others |
Value Network & Pricing Analysis
Backward integration from fiber processing through module assembly anchors supply position and pricing power for tier-one integrators serving Stuttgart-Wolfsburg and Yangtze River Delta manufacturing corridors. Captive control over polyurethane foam chemistry and glass wool substrate production insulates margin structures against petrochemical feedstock volatility while compressing qualification timelines for ECHA REACH-compliant formulations.
Pricing Analysis
Volume leadership resides with fiberglass batt formats in legacy platforms and aftermarket channels, while foam-based solutions command margin premiums in battery-electric architectures. Three-tier pricing structure across premium, standard, and economy levels separates active noise cancellation-integrated packages from passive multi-layer configurations and basic absorption materials. Cost compression in entry-segment programs is intensifying because recycled cotton fiber substitutes displace synthetic substrates. Fleet procurement teams at domestic Chinese OEMs exhibit the highest price sensitivity; premium European EV platforms prioritize acoustic performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from premium OEMs mandate multi-supplier qualification for polyurethane polyols and isocyanates, fragmenting procurement across BASF, Covestro, and Huntsman production networks. Manufacturing concentration centers on Germany, China, and the United States, with raw material dependencies on crude oil derivatives, recycled PET feedstocks, and E-glass fiber rovings. Single-source vulnerability persists in specialized phosphorus-based flame retardant additives qualified under ECHA timelines. Distribution runs through tier-one subsystem integrators controlling module assembly decisions rather than direct material supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where ECHA REACH flame retardant restrictions create 18-24 month qualification moats that favor incumbents with existing certification portfolios and reformulation R&D budgets.
For Market Incumbents: Deploy CAE modeling capabilities as a defensive lever against emerging simulation-as-a-service entrants. Deepen captive supply of low-VOC foam chemistries to meet GB/T 27630 enforcement windows in China. Reinforce firewall application dominance through accelerated phosphorus-based alternative qualifications ahead of ECHA substitution deadlines.
For New Entrants and Emerging Players: Spray application robotics integration offers a technology-first wedge into floorpan specification at automated assembly plants in Shanghai and Guangdong corridors. Target India's PLI scheme greenfield capacity as the most penetrable geography, where BIS certification barriers are surmountable through joint venture structures with established textile processors.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to chemical conglomerates seeking foam chemistry verticality. Long-term viability favors subsystem integrators with backward fiber processing control and active-passive acoustic convergence engineering. Watch MIIT enforcement intensity on dual carbon mandates as the signal for foam substitution acceleration versus fiberglass retention.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Investment | Phosphorus-based flame retardant qualifications secure ECHA-compliant supply positions for European firewall programs. |
| Spray Application Automation Deployment | Robotic polyurethane deposition at MIIT-mandated lightweighting lines reduces labor content and acoustic variance. |
| India PLI Localization Partnership | Greenfield module assembly capacity in Maharashtra-Gujarat corridors captures domestic EV procurement preferences. |
| Active Noise Cancellation Integration | Electronics-acoustics convergence engineering elevates tier-one integrator influence over substrate specification. |
| Recyclable Mono-Material Design Development | Single-substrate acoustic packages align with EU Green Deal circularity requirements and simplify end-of-life recovery. |
Research Methodology
Regulatory filings from ECHA, MIIT, and NHTSA, trade customs databases tracking polyol and isocyanate flows, and OEM material specification sheets formed the secondary backbone of this analysis. Primary interviews with tier-one supplier procurement directors, OEM platform engineers, acoustic CAE specialists, and aftermarket distribution heads combined with bottom-up and top-down triangulation to validate segment sizing and growth trajectory assumptions.
Bottom-up modeling of vehicle production volumes by propulsion architecture, content-per-vehicle estimates by application area, and regional pricing differentials anchored the analytical lens. Segmentation across material chemistry, installation method, vehicle class, and regional manufacturing cluster fed into CAGR derivation through trend extrapolation and elasticity analysis. Forecast inputs included MIIT dual carbon mandate enforcement schedules, ECHA REACH substitution timelines, and spray application automation adoption curves at premium OEM assembly plants.
Several conditions sit outside the modeled scope, including abrupt petrochemical price shocks, unilateral tariff impositions on cross-border foam substrate trade, and breakthrough solid-state battery thermal management architectures that eliminate firewall insulation requirements. Deviation in ECHA enforcement intensity or phosphorus-based additive supply constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Weatherstrip Market