
 Indonesia Automotive Lubricants Market | 2026-2036
Indonesia Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Automotive Lubricants Market Foresight
Fleet operator consolidation across Java is restructuring downstream procurement patterns for automotive lubricants. PT Pertamina anchors national supply through its extensive fuel-station network and captive blending capacity. Shell plc competes via premium synthetic positioning among motorcycle owners in urban centers. Exxon Mobil Corporation leverages technical partnerships with OEM service channels to sustain volume commitments.
Indonesia automotive lubricants comprise refined base oils combined with additive packages engineered to reduce friction, dissipate heat, and prevent wear across internal combustion powertrains. Typical passenger car engine oils operate within SAE viscosity grades 5W-30 or 10W-40, formulated with detergents, dispersants, and anti-wear agents to meet OEM drain-interval specifications. Engine oil occupies the dominant value share given high motorcycle and passenger car parc density, while synthetic formulations command expanding shelf space as OEMs specify extended drain intervals. The aftermarket channel generates the bulk of transaction volume, though fleet operators are consolidating purchases through direct supply agreements that bypass traditional retail.
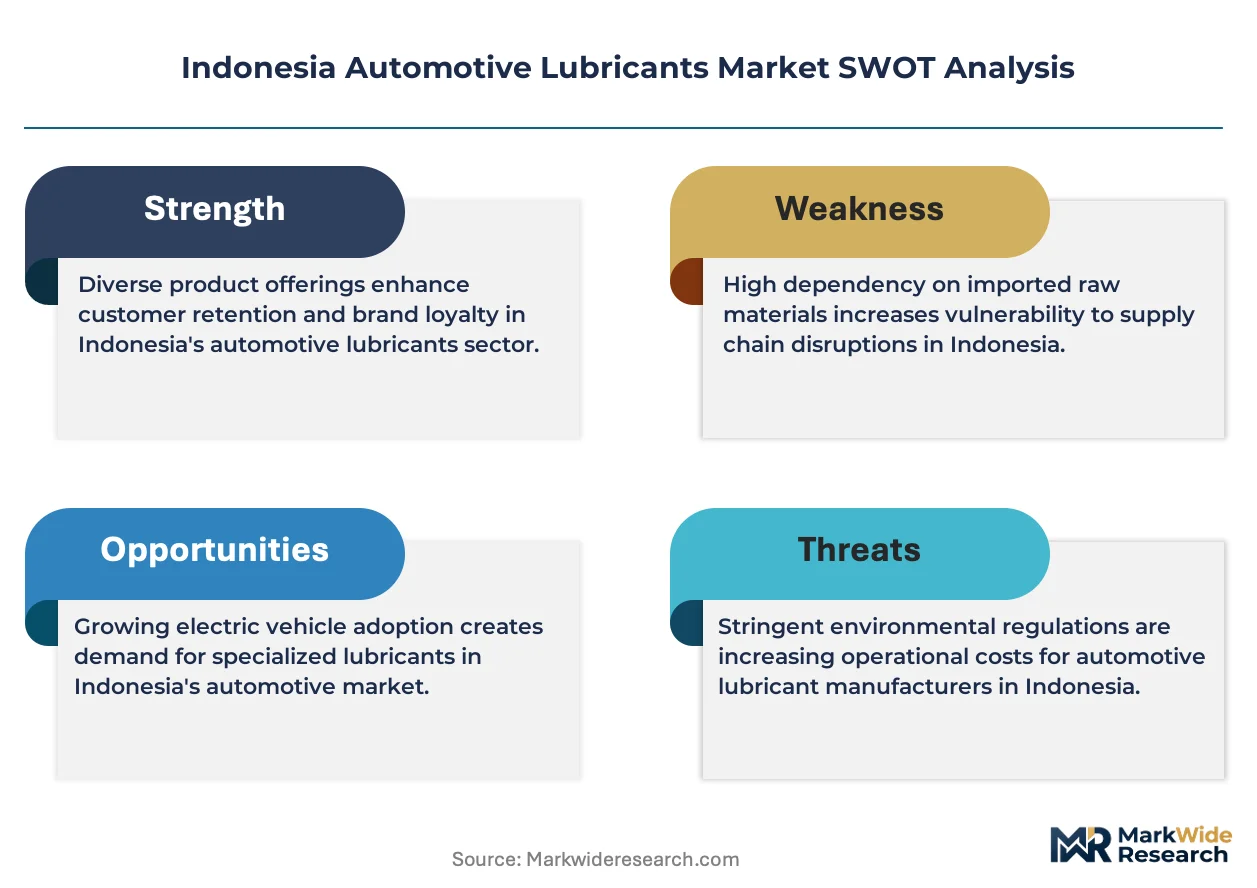
Indonesia's Ministry of Industry and national standards body enforce product quality benchmarks for lubricant labeling and performance claims, while environmental regulations from the Ministry of Environment and Forestry tighten waste-oil handling and recycling obligations. These frameworks elevate compliance costs for smaller blenders while creating certification barriers that favor established players with in-house testing laboratories. Stakeholders must monitor how electrification timelines for two-wheelers and buses reshape lubricant demand profiles across the archipelago's fragmented vehicle parc.
Market Dynamics
Fleet consolidation across Java and Sumatra is concentrating purchasing power among commercial vehicle operators, compressing margins for blenders while elevating volume commitments for national suppliers with captive distribution networks.
Growth Catalysts
- Commercial vehicle parc expansion:Rising logistics demand through Surabaya's port corridor and Jakarta's industrial belt is expanding lubricant consumption among heavy-duty fleets operating on extended drain intervals.
- BIS-equivalent standards enforcement:Indonesia's national quality benchmarks for lubricant labeling are elevating product differentiation and pushing smaller blenders toward certification investments that favor established testing capabilities.
- Fuel-economy regulations:Evolving mandates from the Ministry of Industry are accelerating specification shifts toward lower-viscosity grades among OEM service channels and aftermarket distributors.
Market Restraints
- Base oil supply concentration:Indonesia remains dependent on Group I and II base oil imports from regional refiners, exposing blenders to freight cost volatility and currency fluctuation risks.
- Electrification timeline uncertainty:Accelerating electric two-wheeler and bus adoption in Jakarta and Bali threatens long-term lubricant demand volumes without clear replacement revenue streams.
- Waste-oil handling compliance:Ministry of Environment and Forestry regulations tightening recycling obligations impose capital requirements on collection infrastructure that disadvantage non-integrated operators.
Strategic Opportunities
- Eastern Indonesia penetration:Kalimantan and Sulawesi remain underserved by premium synthetic distribution, creating first-mover advantages for blenders establishing direct fleet relationships outside Java.
- Extended-drain synthetic formulations:OEM specification convergence toward 10,000-kilometer-plus intervals opens margin expansion for formulators with API SP and ILSAC GF-6 certification capabilities.
- Direct fleet supply agreements:Consolidating transport operators in Sumatra are bypassing traditional retail channels, rewarding lubricant suppliers with dedicated logistics and technical service teams.
Industry Challenges
- Additive package formulation expertise:Scarcity of tribology specialists familiar with tropical humidity conditions and stop-start traffic patterns limits indigenous product development capabilities.
- Used-oil reverse logistics:Fragmented collection networks across Indonesia's archipelago geography complicate compliance with extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Automotive Lubricants Market |
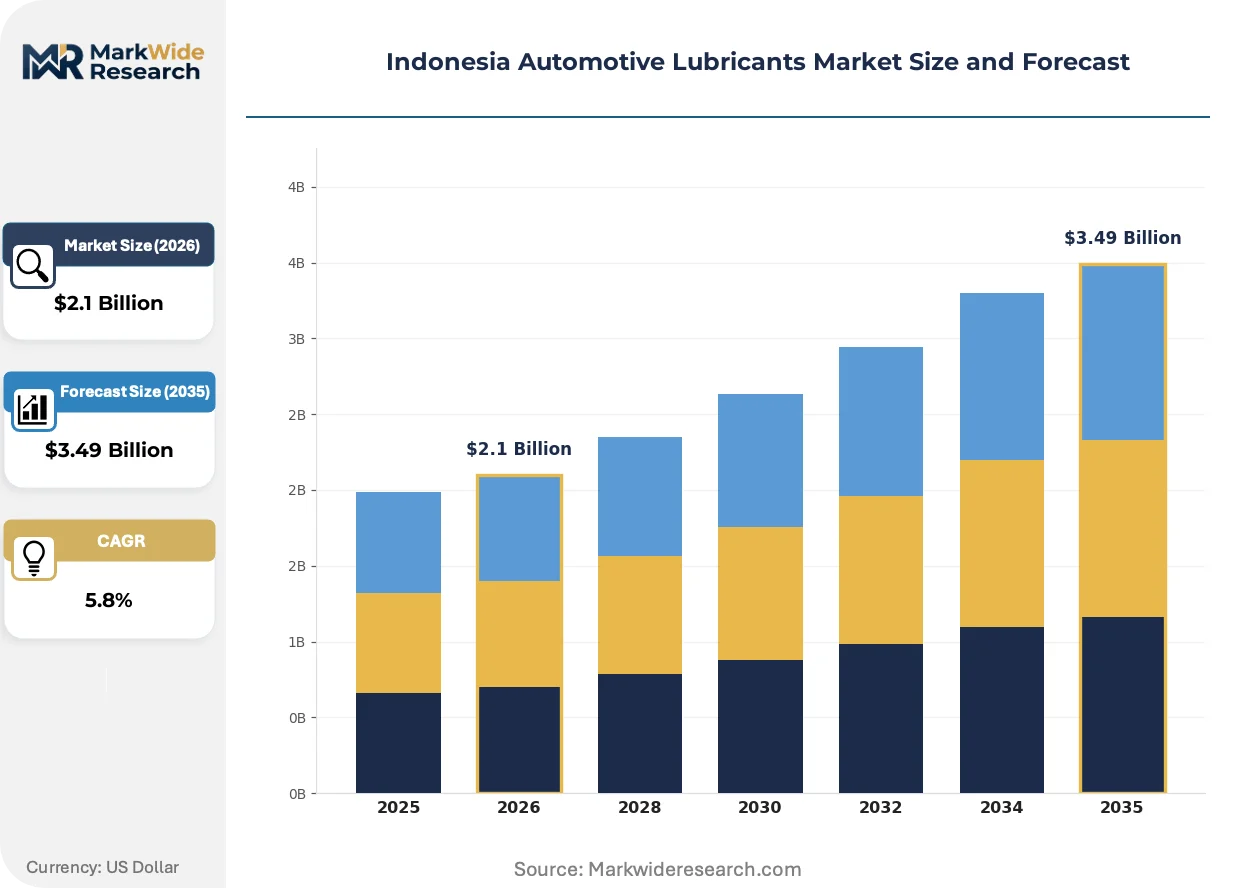
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Grease Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Formulation: Synthetic, Semi-Synthetic, Mineral, Bio-Based End User: OEMs, Aftermarket, Fleet Operators, Service Stations |
| Companies Covered | Exxon Mobil Corporation, PT Wiraswasta Gemilang Indonesia (Evalube), PT Pertamina, Idemitsu Kosan Co. Ltd., TotalEnergies, Shell plc, BP p.l.c., Fuchs Petrolub SE, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Automotive Lubricants Market Shifts & Advancements
Digitalization of fleet maintenance scheduling is reshaping how lubricant demand is forecasted and fulfilled, compressing traditional distributor layers while elevating predictive analytics capabilities among integrated suppliers.
Automated oil analysis systems are automating condition monitoring for commercial vehicle fleets operating across Java's toll-road networks. Transport operators with 500-plus unit parcs are deploying these sensors at 15,000-kilometer intervals. The technology is automating drain interval optimization and displacing fixed-schedule maintenance contracts that previously anchored volume predictability for lubricant distributors.
Indonesia's Ministry of Industry is tightening enforcement of SNI labeling requirements for lubricant performance claims and viscosity grade accuracy. The regulations are elevating compliance costs for importers lacking in-house testing laboratories. Smaller blenders in Surabaya and Medan are responding by outsourcing certification to third-party laboratories or exiting premium synthetic segments entirely.
Fleet procurement teams are consolidating lubricant purchasing through centralized tender processes that bypass traditional workshop and retail channels. Large logistics operators in Jakarta's industrial corridor are awarding multi-year supply contracts to single-source providers with integrated technical service capabilities. This concentration is most visible among e-commerce delivery fleets where vehicle utilization rates exceed 250,000 kilometers annually.
Indonesia Automotive Lubricants Market Segmentation
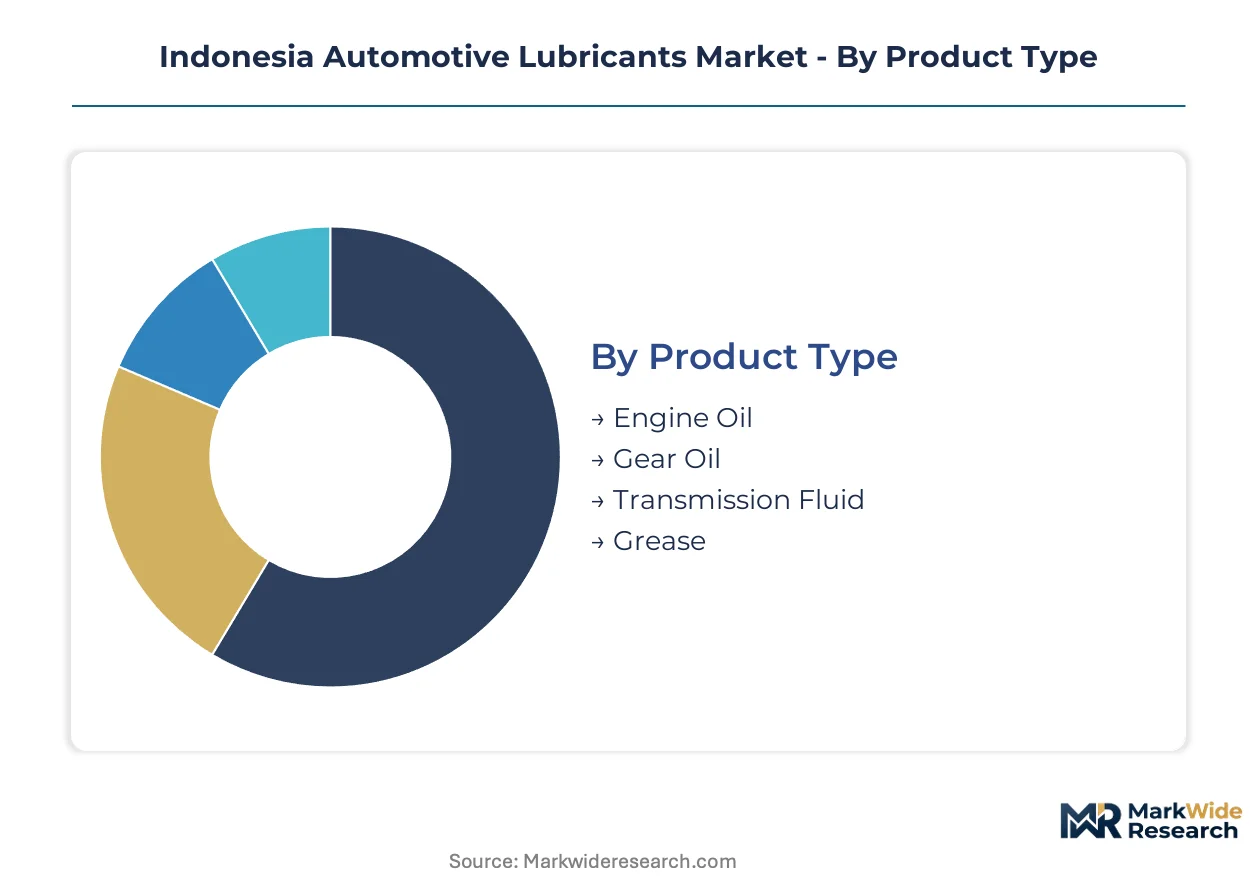
Segmentation in Indonesia's automotive lubricants market reveals how procurement power, vehicle parc composition, and regulatory pressure reshape competitive positioning across distinct buyer clusters. Understanding these divides exposes where margin concentrates and where volume growth accelerates.
Product Type:
Buyers differentiate by drain interval requirements, equipment protection needs, and total cost of ownership calculations across powertrain configurations.
- Engine Oil:Formulated with detergent-dispersant packages meeting API SP and ILSAC GF-6 specifications for friction reduction and deposit control. Demand concentrates among motorcycle owners in Jakarta and Surabaya where stop-start traffic patterns accelerate oil degradation and shorten replacement cycles. Fleet operators in Java's industrial corridor are consolidating procurement around extended-drain synthetics that reduce downtime.
- Gear Oil:Extreme-pressure additives protect hypoid gears in commercial vehicle axles operating under high-torque, high-temperature conditions. Heavy-duty fleets traversing Sumatra's mountainous terrain specify SAE 80W-90 or 85W-140 grades with enhanced thermal stability for differential and transmission applications.
- Transmission Fluid:ATF and CVT formulations serve automatic and continuously variable transmissions with friction modifiers ensuring smooth shift quality.
- Grease:Lithium-complex and calcium-sulfonate thickeners protect chassis components, wheel bearings, and universal joints from water washout in tropical humidity.
Volume sits with Engine Oil given motorcycle and passenger car density; growth tilts toward synthetic Gear Oil formulations as heavy-duty fleet specifications tighten.
Vehicle Type:
Segment boundaries reflect utilization intensity, maintenance infrastructure access, and lubricant consumption rates per kilometer traveled.
- Passenger Cars:SAE 5W-30 and 0W-20 grades dominate as Japanese and Korean OEM service channels push low-viscosity specifications for fuel economy compliance. Urban owners in Jakarta's satellite cities favor semi-synthetic formulations balancing cost with 10,000-kilometer drain intervals.
- Commercial Vehicles:Medium-duty trucks and buses operating intercity routes consume high-volume diesel engine oils with TBN retention for soot handling. Logistics operators in Surabaya's port zone specify CI-4/CK-4 grades for engines exceeding 500,000 kilometers before overhaul.
- Motorcycles:Four-stroke scooter and underbone engines represent the largest lubricant consumption base by unit volume across Indonesia's 120-million-plus two-wheeler parc.
- Heavy-Duty Trucks:Mining and construction equipment in Kalimantan and Papua demand specialized hydraulic fluids and engine oils with extended service life in severe-duty cycles.
Volume concentrates with Motorcycles due to parc scale; expansion tilts toward Heavy-Duty Trucks as mining logistics intensify in Eastern Indonesia.
Formulation:
Cost-performance tradeoffs and OEM warranty compliance requirements segment buyers across base oil quality tiers.
- Synthetic:Group III and PAO base stocks deliver oxidative stability for 15,000-kilometer-plus drain intervals. Premium positioning among Jakarta's upper-middle vehicle owners and express delivery fleets seeking maximum uptime justifies price premiums over mineral alternatives.
- Semi-Synthetic:Blended formulations combining Group II base oils with synthetic content occupy the value-conscious middle market. Workshop channels in Surabaya and Bandung promote these grades as OEM-specification compliant at moderate price points.
- Mineral:Group I base oils serve price-sensitive motorcycle owners and older vehicle parcs in rural Java where 3,000-kilometer drain intervals remain standard practice.
- Bio-Based:Estolide and vegetable-derived formulations address sustainability commitments among state-owned fleet operators and mining companies with environmental compliance obligations.
Volume rests with Mineral formulations in the aftermarket; value expansion tilts toward Synthetic grades as OEM specifications harden and fleet consolidation favors total-cost optimization.
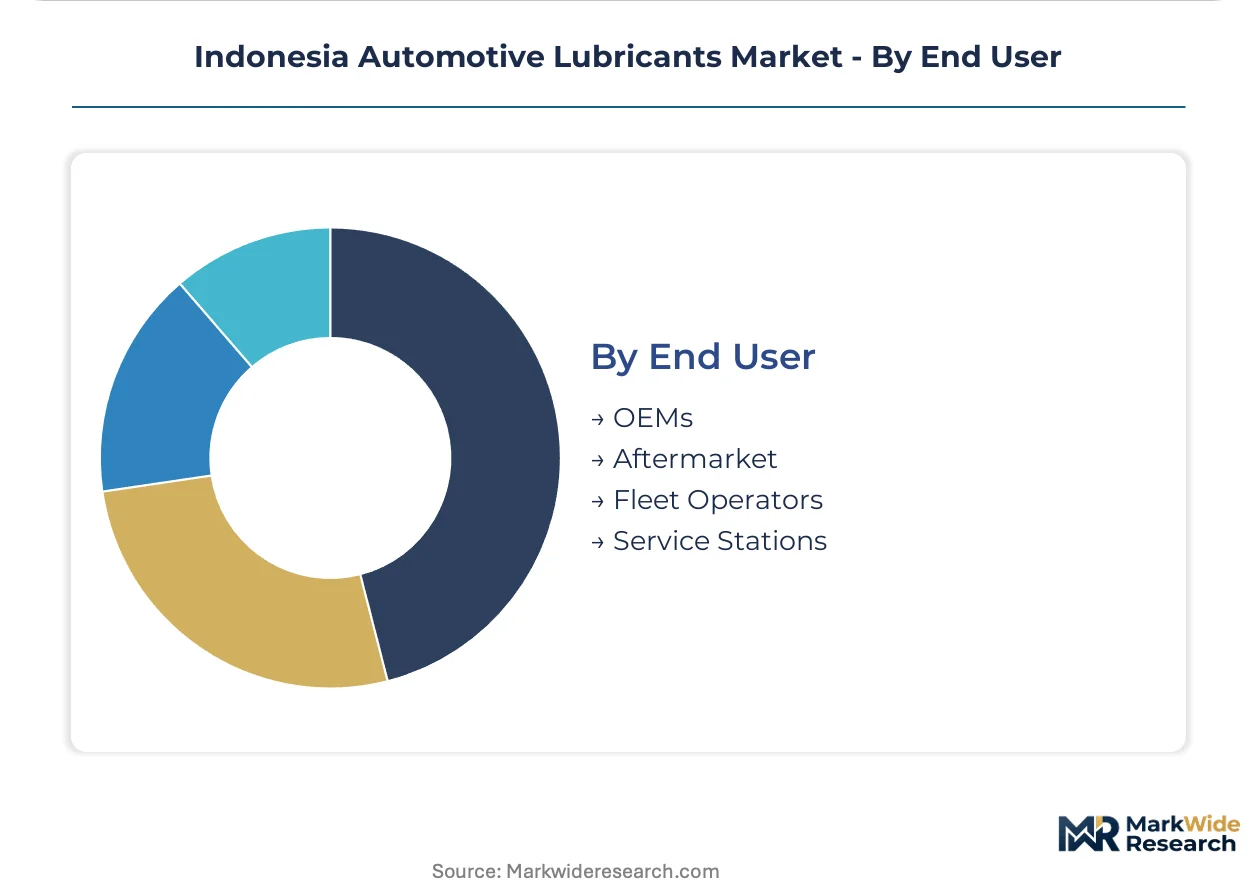
End User:
Channel control and technical service integration determine how lubricant suppliers capture margin and secure volume commitments.
- OEMs:Factory-fill specifications and authorized service networks lock in supplier relationships through technical partnerships and co-development agreements. Japanese automotive assemblers in Indonesia's manufacturing zones specify proprietary lubricant grades that anchor aftermarket loyalty.
- Aftermarket:Independent workshops, retail auto parts stores, and traditional markets distribute bulk of transaction volume through fragmented reseller networks. Price competition intensifies in this channel as unbranded and counterfeit products erode margins for certified suppliers.
- Fleet Operators:Consolidated transport and logistics companies with 500-plus unit parcs negotiate direct supply agreements bypassing distributor layers. E-commerce delivery fleets in Jakarta's industrial corridor award multi-year contracts to single-source providers with integrated oil analysis services.
- Service Stations:Fuel retail networks leverage convenience positioning for top-up sales and quick-lube services targeting time-constrained urban vehicle owners.
Volume flows through Aftermarket channels; value capture tilts toward Fleet Operators as procurement centralization compresses distributor margins and rewards technical service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's automotive lubricant consumption clusters in Java's industrial belt and Surabaya's port logistics zone, with fleet operators driving procurement consolidation across the archipelago's most densely motorized regions.
Java
Jakarta's industrial corridor anchors national lubricant demand through e-commerce delivery fleets and intercity bus operators specifying extended-drain synthetics. Indonesia's Ministry of Industry enforces SNI labeling requirements that elevate compliance costs for smaller blenders. Bandung and Surabaya workshop channels distribute semi-synthetic formulations to motorcycle owners facing stop-start traffic degradation.
Sumatra
Medan's logistics operators and palm-oil transport fleets consume high-volume diesel engine oils for heavy-duty trucks traversing mountainous terrain. The Ministry of Environment and Forestry tightens waste-oil recycling obligations that disadvantage non-integrated collectors. Batam's free-trade zone attracts premium synthetic distribution targeting cross-border commercial vehicle traffic.
Kalimantan
Mining equipment in East Kalimantan's coal belt demands specialized hydraulic fluids and severe-duty engine oils with extended service life. Regional infrastructure gaps limit premium synthetic penetration, creating first-mover opportunities for suppliers establishing direct fleet relationships. Samarinda's mining logistics operators consolidate procurement around technical service-integrated providers.
Sulawesi
Nickel-processing logistics in Central Sulawesi's Morowali Industrial Park drives commercial vehicle lubricant consumption for ore transport fleets. Underdeveloped distribution networks leave the region underserved by synthetic formulations relative to Java. Makassar's port zone emerging as a consolidation point for Eastern Indonesia supply chain expansion.
Bali
Tourism transport fleets and urban delivery vehicles in Denpasar consume passenger car and motorcycle lubricants amid accelerating electric two-wheeler adoption. Local regulations targeting emissions reduction reshape long-term lubricant demand profiles without clear replacement revenue streams. The island's concentrated vehicle parc supports centralized fleet procurement models bypassing traditional retail.
Indonesia Automotive Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty synthetic positioning and direct fleet supply relationships. National oil companies leverage captive fuel-station networks and blending capacity to defend volume positions. Multinational energy majors compete through OEM technical partnerships and premium branding among urban vehicle owners. Strategic moves concentrate on certification investments for API SP and ILSAC GF-6 compliance, plus logistics integration for bypassing fragmented distributor layers.
Within the national champion tier, PT Pertamina anchors supply through extensive retail infrastructure and domestic blending assets. Shell plc and Exxon Mobil Corporation exemplify multinational positioning strategies—Shell via premium synthetic recognition among motorcycle owners in Jakarta and Surabaya, Exxon Mobil through OEM service channel technical partnerships that secure factory-fill specifications and aftermarket loyalty.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| PT Wiraswasta Gemilang Indonesia (Evalube) |
| PT Pertamina |
| Idemitsu Kosan Co. Ltd. |
| TotalEnergies |
| Shell plc |
| BP p.l.c. |
| Fuchs Petrolub SE |
| Chevron Corporation |
| Others |
Supply & Pricing Matrix
Ministry of Environment and Forestry waste-oil recycling mandates gate qualified supply access and premium-tier pricing power, as compliance capital requirements filter non-integrated blenders from synthetic formulation markets while elevating certification costs that concentrate margin among laboratory-equipped incumbents.
Pricing Analysis
Volume concentrates in mineral-grade motorcycle oils where 3,000-kilometer drain intervals anchor transactional per-unit pricing; margin concentrates in synthetic formulations where API SP certification and extended-drain specifications command premiums. Price differentiation hinges on SNI labeling compliance and technical service bundling for fleet operators. Pricing pressure stems from fleet procurement centralization compressing distributor markups. Price-sensitive rural motorcycle owners in Java favor unbranded mineral grades; least-sensitive express delivery fleets prioritize uptime over unit cost.
Supply Chain Analysis
SNI certification and API SP qualification requirements gate supply access, favoring blenders with in-house testing laboratories in Jakarta and Surabaya. Base oil supply draws from Singapore, South Korea, and Thailand refineries producing Group I and II stocks. Additive packages hinge on imports from specialty chemical producers in Japan and the United States. Single-source vulnerability runs through regional base oil import channels exposed to freight cost volatility. Distribution runs through Pertamina's captive fuel-station network and fragmented independent workshop channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Base oil import dependency and limited domestic Group III production capacity prop pricing power for qualified suppliers, constraining volume expansion for non-integrated blenders lacking backward integration into regional refining.
For Market Incumbents: Anticipate electrification timeline acceleration in Jakarta and Bali by deepening technical service integration with heavy-duty fleet operators in Kalimantan and Sulawesi where mining logistics demand remains insulated from two-wheeler substitution. Fortify API SP certification capabilities to capture extended-drain synthetic volume as OEM specifications tighten. Secure direct supply agreements with consolidating e-commerce delivery fleets before procurement centralization locks in competitor relationships. For New Entrants and Emerging Players: Fleet operators in Eastern Indonesia represent the most penetrable channel archetype, as Samarinda mining logistics and Morowali nickel transport fleets remain underserved by premium synthetic distribution relative to Java. Establish direct technical service relationships bypassing fragmented distributor layers. Target bio-based formulation positioning for state-owned mining companies with environmental compliance obligations as a differentiated entry wedge. For Investors and Strategic Acquirers: Consolidation of Pertamina's retail dominance with independent blender technical capabilities is the leading indicator that margin capture will shift toward integrated supply-service models. Five-to-ten-year viability favors blenders with captive laboratory certification and direct fleet relationships over pure distribution plays. Acquisition target archetype: mid-cap regional blenders with SNI compliance infrastructure and established Sumatra or Kalimantan fleet accounts. Watch for Ministry of Industry enforcement actions accelerating smaller player exits as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive access to Group II/III stocks from Singapore and Thai refiners reduces currency exposure and secures formulation consistency. |
| Extended-Drain Synthetic Certification | API SP and ILSAC GF-6 compliance opens OEM service channel access and fleet procurement tenders in Jakarta's industrial corridor. |
| Direct Fleet Supply Agreement | Multi-year contracts with 500-plus unit logistics operators bypass distributor margin compression and anchor volume predictability. |
| Eastern Indonesia Distribution Buildout | First-mover positioning in Kalimantan and Sulawesi mining logistics captures underserved premium synthetic demand outside Java. |
| Used-Oil Reverse Logistics Investment | Ministry of Environment and Forestry compliance infrastructure creates competitive moat against non-integrated blenders. |
Research Methodology
Multi-period observation of fleet procurement patterns, SNI certification enforcement actions, and base oil import volumes anchored the trend analysis, supplemented by interviews with lubricant formulation chemists, fleet maintenance directors at mining and logistics operators, aftermarket workshop owners in Surabaya and Medan, and procurement leads at national oil companies. Secondary validation drew from Ministry of Industry regulatory filings, Ministry of Environment and Forestry waste-handling compliance records, customs trade data on base oil imports, and API/ILSAC specification documentation. Bottom-up volume estimates from vehicle parc and drain interval assumptions triangulated against top-down value projections from channel margin structures.
Input-output matrix modeling connected base oil cost structures, additive package pricing, and channel margin compression to synthetic and mineral formulation value pools across the projection horizon. Segmentation dimensions included product type, vehicle category, formulation grade, and end-user channel control. CAGRs derived from elasticity-adjusted demand curves incorporating electrification scenario weighting. Industry-specific inputs encompassed OEM drain interval specification convergence and fleet operator consolidation velocity.
Caveats apply where Ministry of Industry regulatory enforcement intensity, electric two-wheeler adoption acceleration, or base oil supply disruption could materially shift the outlook. A model refresh is warranted upon material change in fleet electrification policy or regional refining capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Struts System Market
Automotive Parts
Rammer Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Automotive Axle and Propeller Shaft Market