
 Automotive Interior Materials Market | 2026-2036
Automotive Interior Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Interior Materials Market Analysis
ISO 14001 environmental management certification is bifurcating the supplier base into qualified tier-1 partners and excluded smaller producers. Faurecia leverages its European manufacturing footprint to sustain delivery contracts with premium German OEMs. Lear Corporation anchors its position through vertical integration into foam-in-place seating operations across North American assembly corridors. Yanfeng competes aggressively on cost-engineered dashboard modules for volume Chinese brands.
Automotive interior materials encompass engineered textiles, polymer composites, leather hides, and thermoplastic olefins formulated for cabin surfaces, with specifications spanning abrasion resistance above 100,000 Martindale cycles and fogging values below 3 mg per DIN 75201. These materials serve to reduce vehicle mass, manage acoustic profiles, and satisfy tactile quality benchmarks for passenger compartments. Upholstery and dashboard segments command the deepest margin pools where OEMs specify multi-layer constructions with integrated heating elements and capacitive touch channels. Composites and vinyl formulations within the material dimension are gaining specification share as weight reduction targets tighten across electric vehicle architectures.
REACH in Europe, EPA VOC guidelines in the United States, and GB standards administered by SAMR in China collectively restrict phthalate plasticizers and formaldehyde off-gassing from cabin components. These frameworks force reformulation of polyurethane foams and adhesive systems, raising compliance costs for suppliers without certified laboratories. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant testing regimes.
Market Dynamics
Electric vehicle platform architectures are compressing development cycles for cabin components, forcing material suppliers to synchronize roadmaps with battery-pack thermal management systems and reduced-mass structural targets.
Growth Catalysts
- REACH chemical restrictions:European VOC emission limits are accelerating reformulation of polyurethane foams toward water-based adhesive systems, creating first-mover advantages for certified laboratories.
- EV thermal management:Battery-electric architectures require interior materials with enhanced heat resistance near power electronics, pulling specification upgrades across seating and dashboard segments.
- China SAMR GB standards:Domestic formaldehyde off-gassing mandates are consolidating procurement toward tier-1 suppliers with in-house emissions testing capabilities.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and TPU resin prices swing with crude oil benchmarks, compressing margin predictability for synthetic leather producers.
- Concentrated hide supply:Premium automotive leather sourcing clusters in Italian and Brazilian tanning corridors, exposing OEMs to single-region disruption risk.
- Recycling infrastructure gaps:Multi-layer composite seat constructions lack scaled chemical depolymerization pathways, constraining circular economy claims.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced automotive components are attracting dashboard module investments from multinational tier-1s seeking cost-engineered export hubs.
- Bio-based polyurethane:Castor oil-derived polyols are penetrating luxury EV segments where carbon footprint disclosure carries brand weight.
- Direct OEM contracting:Bypassing traditional tier-2 distributors through digital specification platforms is opening margin capture for specialized textile weavers.
Industry Challenges
- Cross-functional talent scarcity:Material scientists fluent in both polymer chemistry and capacitive touch integration command premium compensation, constraining R&D team scaling.
- ISO 14001 certification timelines:Environmental management audits require 12-18 month implementation cycles, delaying qualification for urgent EV platform awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Interior Materials Market |
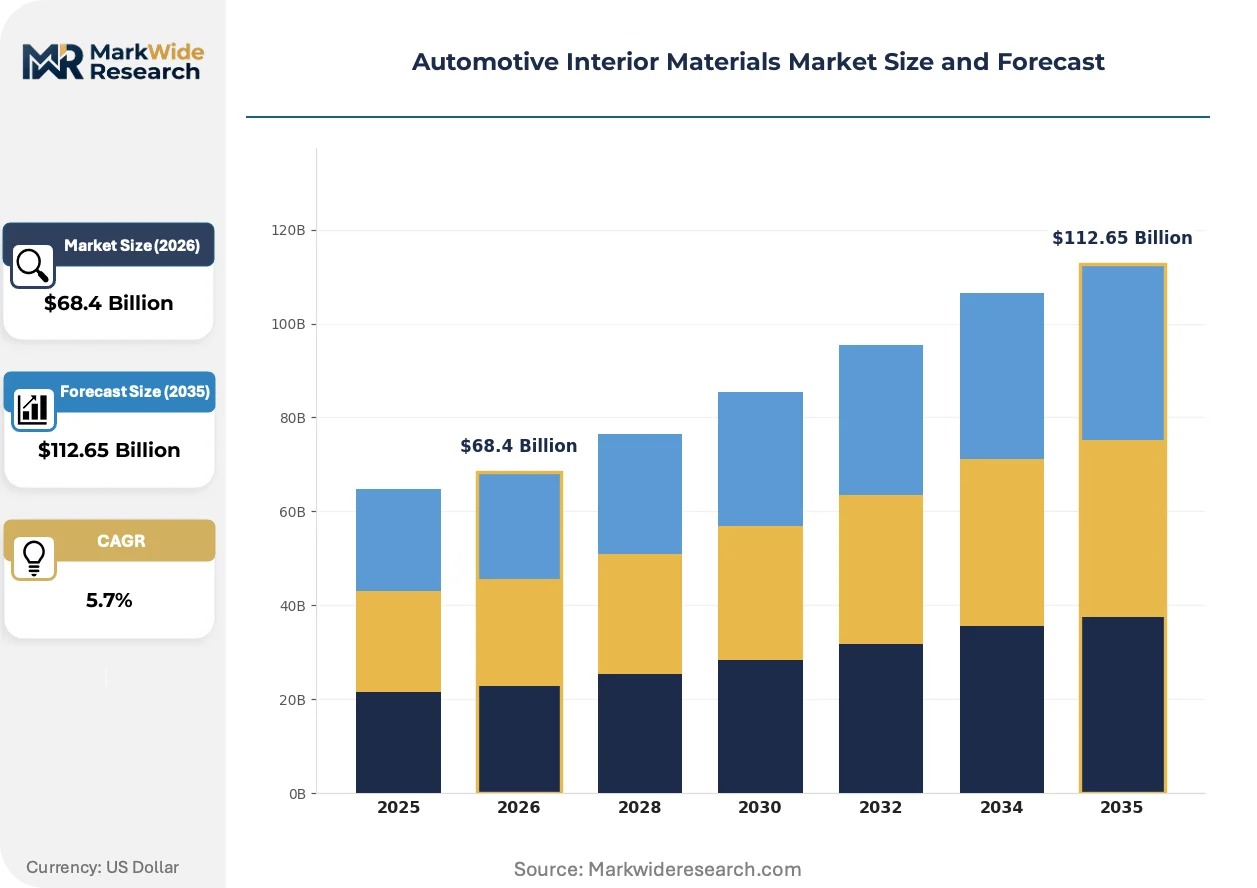
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upholstery, Dashboard, Trims, Headliners Material: Leather, Fabric, Vinyl, Composites Feature: Eco-Friendly, Durable, Lightweight, Noise Reduction End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships |
| Companies Covered | Faurecia, Grupo Antolin, Lear Corporation, Toyoda Gosei Co., Ltd., DRÄXLMAIER, Toyota Boshoku Corporation, BASF SE, Yanfeng, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Interior Materials Market Emerging Trajectories
Material science advances are collapsing the boundary between decorative surfaces and functional electronics, embedding sensors and heating elements directly into substrate layers rather than attaching them as discrete components.
Thermoplastic olefin formulations with integrated graphene dispersions are fragmenting the traditional separation between structural and aesthetic cabin layers. Tier-1 seating suppliers in Germany and Michigan are specifying these composites for load-bearing seat pans that simultaneously deliver haptic feedback channels. The convergence is compressing part counts and assembly labor content while raising tooling complexity for mold-flow simulation.
REACH authorization requirements for phthalate plasticizers are forcing adhesive system reformulations across European supply chains. Polyurethane foam producers are migrating to citrate-based alternatives, with validation cycles extending qualification timelines by four to six months. Upholstery segment margins face the steepest compression where multi-layer constructions require recertification of entire material stacks.
Fleet operators and mobility service providers are consolidating interior specifications around durability-first material selections rather than retail-consumer tactile preferences. Rental vehicle procurement desks in California and Singapore are prioritizing abrasion-resistant vinyl over genuine leather, shifting volume toward engineered textile suppliers with 150,000-plus Martindale cycle certifications. This rotation is decoupling premium pricing from traditional luxury signifiers.
Automotive Interior Materials Market Segmentation
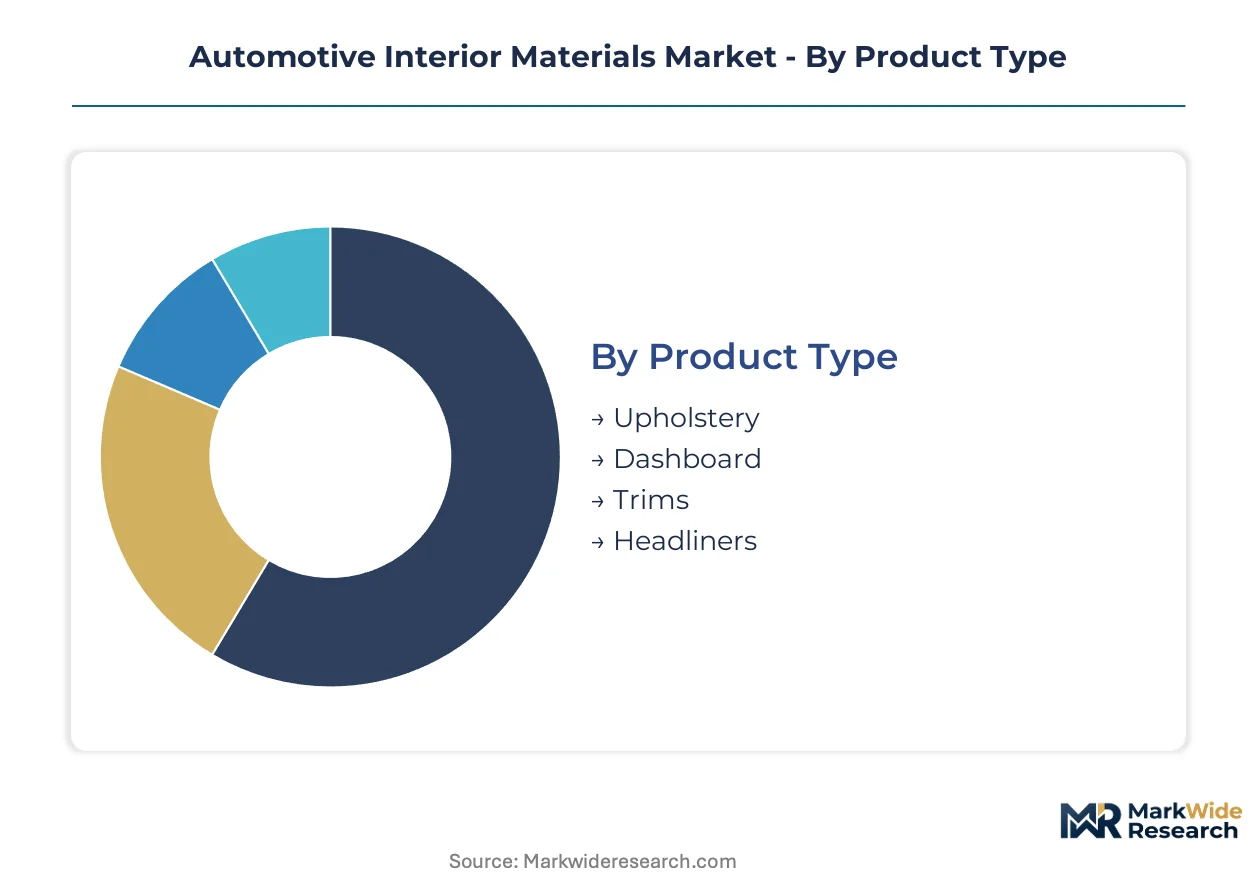
Automotive interior materials segment along four intersecting dimensions that determine specification requirements, compliance pathways, and margin architecture. Product type and material composition dictate regulatory exposure, while feature prioritization and end-user channel shape pricing power and contract duration.
Product Type:
REACH chemical restrictions and EPA VOC guidelines apply differential stringency across cabin zones based on passenger proximity and surface area exposure.
- Upholstery:Multi-layer constructions combining substrate foam, adhesive bonding, and topcoat finish must satisfy abrasion resistance above 100,000 Martindale cycles and fogging values below 3 mg per DIN 75201. Seating procurement in Germany and the United States concentrates specification authority with OEM direct contracts, compressing tier-2 margin capture. Established volume favors upholstery; emerging adoption favors dashboard.
- Dashboard:Thermoplastic olefin and polymer composite formulations integrate capacitive touch channels, heating elements, and structural load-bearing functions into single-module assemblies. Chinese EV manufacturers in Shenzhen and Ningbo are compressing development cycles to synchronize with battery-pack thermal management roadmaps.
- Trims:Decorative surface applications spanning door panels, center consoles, and pillar coverings prioritize tactile quality benchmarks and color-fastness under UV exposure.
- Headliners:Acoustic management substrates combining fiberglass matting, foam backing, and fabric facing address cabin noise reduction targets with reduced mass profiles.
Seating and dashboard modules absorb the bulk of R&D investment; trim and headliner specifications follow derivative from these anchor platforms.
Material:
Feedstock volatility and hide supply concentration create divergent risk profiles across synthetic and natural material streams.
- Leather:Premium automotive hide sourcing clusters in Italian and Brazilian tanning corridors, exposing OEMs to single-region disruption risk from environmental compliance actions or logistics constraints. Full-grain selections command specification in German luxury EV platforms where tactile quality carries brand weight.
- Fabric:Engineered textiles with 150,000-plus Martindale cycle certifications are displacing genuine leather in California and Singapore fleet procurement, where durability-first selection criteria override retail-consumer tactile preferences.
- Vinyl:Polyvinyl chloride formulations with phthalate-free plasticizers address REACH authorization requirements while maintaining cost positions for volume vehicle segments.
- Composites:Graphene-dispersed thermoplastic olefins collapse the boundary between structural and aesthetic cabin layers, enabling load-bearing seat pans with integrated haptic feedback channels.
Natural materials concentrate margin in premium tiers; synthetic formulations are climbing the fastest as weight reduction targets tighten across electric vehicle architectures.
Feature:
OEM specification priorities are rotating from tactile luxury signifiers toward functional performance attributes validated by certified testing protocols.
- Eco-Friendly:Castor oil-derived polyols and bio-based polyurethane systems penetrate luxury EV segments where carbon footprint disclosure carries regulatory and brand weight. ISO 14001 certification bifurcates qualified tier-1 partners from excluded smaller producers.
- Durable:Abrasion-resistant vinyl and engineered textiles with extended cycle certifications address fleet operator procurement desks prioritizing total cost of ownership over initial acquisition expense.
- Lightweight:Mass reduction targets in battery-electric architectures pull specification upgrades toward aluminum-reinforced composites and density-optimized foam substrates.
- Noise Reduction:Multi-layer acoustic constructions combining dense mass barriers with absorptive open-cell foams manage cabin sound profiles in luxury and mass-market segments alike.
Sustainability and durability features are expanding specification share; lightweight and acoustic attributes follow platform-specific engineering requirements.
End User:
Contracting authority and technical integration responsibility vary sharply across the value chain, determining supplier qualification timelines and margin retention.
- OEMs:Volkswagen, BMW, and Ford retain direct specification authority for seating and dashboard modules, issuing platform-specific material roadmaps that synchronize with vehicle development cycles.
- Aftermarket Providers:Independent distributors and installation networks address replacement upholstery and trim demand outside warranty coverage, with sourcing flexibility constrained by fit-for-purpose validation requirements.
- Tier-1 Suppliers:Faurecia, Lear Corporation, and Yanfeng consolidate procurement of sub-assembled modules, managing tier-2 material qualification and compliance documentation on behalf of OEM customers.
- Dealerships:Authorized retail channels execute accessory upgrades and warranty replacements, drawing from OEM-approved supplier catalogs with limited independent sourcing discretion.
Direct OEM and tier-1 supplier channels concentrate procurement volume; aftermarket and dealership pathways follow derivative demand patterns with compressed margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives and emissions regulations are redrawing procurement geography across major automotive manufacturing corridors. OEMs now route orders toward jurisdictions with certified laboratory infrastructure and aligned chemical compliance frameworks.
Germany
REACH authorization timelines for phthalate alternatives compress supplier qualification windows. ECHA mandates force polyurethane foam reformulations toward citrate-based plasticizers. Stuttgart and Munich anchor premium EV seating development for BMW and Mercedes-Benz platforms.
China
Domestic EV manufacturers in Shenzhen and Ningbo compress dashboard module development cycles to match battery thermal management roadmaps. SAMR-administered GB standards on formaldehyde off-gassing consolidate procurement toward tier-1 suppliers with in-house emissions testing. Yangtze River Delta clusters concentrate specification authority for next-generation cabin platforms.
United States
Fleet operators in California prioritize durability-first material selections with 150,000-plus Martindale cycle certifications over retail-consumer tactile preferences. EPA VOC guidelines restrict adhesive system formulations across seating and trim applications. Michigan-based seating suppliers manage foam-in-place operations across North American assembly corridors.
India
PLI scheme incentives for advanced automotive components attract dashboard module investments from multinational tier-1s seeking cost-engineered export hubs. BIS standards govern material specifications for domestic OEM procurement. Tamil Nadu and Maharashtra concentrate assembly plant investments from volume passenger vehicle manufacturers.
Brazil
Premium automotive hide sourcing clusters in domestic tanning corridors, exposing supply chains to single-region disruption risk from environmental compliance actions. ANVISA regulations govern material safety for imported cabin components. São Paulo state anchors leather finishing operations for export to European luxury EV platforms.
Automotive Interior Materials Market Vendor Landscape
Player mix skews toward integrated tier-1 module suppliers and specialized material compounders. Market structure concentrates procurement authority with firms possessing ISO 14001 certification and captive emissions testing laboratories. Three archetypes dominate: European premium seating specialists, Asian cost-engineered dashboard fabricators, and diversified chemical conglomerates with polymer formulation depth. Competitive dynamics center on backward integration into foam substrates and strategic partnerships with EV platform architects.
Within the European premium tier, Faurecia and DRÄXLMAIER occupy positions defined by proximity to German OEM specification authority. Lear Corporation exemplifies the North American integrated model with in-house production of seating systems. Yanfeng represents the Asia-Pacific cost-engineering archetype, competing aggressively on dashboard module pricing for volume Chinese brands. These three anchors illustrate how geographic manufacturing footprint and certification status determine contract access across diverging regulatory environments.
| Leading Market Players |
|---|
| Faurecia |
| Grupo Antolin |
| Lear Corporation |
| Toyoda Gosei Co., Ltd. |
| DRÄXLMAIER |
| Toyota Boshoku Corporation |
| BASF SE |
| Yanfeng |
| Asahi Kasei Corporation |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-week qualification timelines for ISO 14001 certification concentrate procurement authority with tier-1 suppliers holding captive laboratory infrastructure, compressing margin capture for uncertified competitors while elevating pricing power for qualified partners across German and Chinese OEM contracts.
Pricing Analysis
Certification level creates the primary spread between qualified tier-1 partners and excluded producers, with ISO 14001 and REACH-compliant laboratories commanding premium positioning against uncertified competitors. Three-tier pricing structure across premium leather, certified synthetics, and economy vinyl segments reflects material grade and compliance investment. Pricing pressure stems from petrochemical feedstock volatility swinging polypropylene and TPU resin costs. Fleet operators in California exhibit highest price sensitivity, prioritizing durability-first engineered textiles over tactile luxury signifiers.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Italian and Brazilian tanning corridors supplying premium automotive hide. Raw material sourcing draws from German polymer compounders, Chinese TPU resin producers, and Brazilian hide finishing operations. Single-region concentration in Italian tanning corridors exposes supply chains to environmental compliance disruption. Distribution runs through tier-1 module suppliers consolidating tier-2 qualification and OEM direct contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from bio-based polyurethane systems penetrating luxury EV segments where carbon footprint disclosure carries brand weight.
For Market Incumbents: Compound backward integration into foam substrate production to defend margin positions against citrate-based adhesive reformulation costs. Accelerate captive emissions testing laboratory investments to compress qualification timelines for urgent EV platform awards. Lock in long-term supply agreements with Italian and Brazilian tanning corridors to mitigate single-region disruption exposure.
For New Entrants and Emerging Players: Lead with bio-based polyurethane formulations targeting luxury EV OEMs in Germany where REACH authorization timelines create qualification gaps. Penetrate India PLI scheme corridors for cost-engineered dashboard module exports. Deploy digital specification platforms to bypass traditional tier-2 distribution and capture direct OEM contracting margin.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ISO 14001 certification requirements are bifurcating qualified tier-1 partners from excluded smaller producers. Target mid-cap seating specialists with in-house foam-in-place operations and established German OEM relationships. Monitor fleet operator procurement desk shifts toward durability-first material selections as inflection signal for premium leather demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Substrates | Captures margin compression from citrate-based adhesive reformulation costs across European supply chains. |
| Captive Emissions Testing Laboratory Investment | Compresses ISO 14001 qualification timelines to match compressed EV platform development cycles. |
| Bio-Based Polyurethane Formulation Launch | Penetrates luxury EV segments where REACH authorization and carbon disclosure carry brand weight. |
| Digital Specification Platform Deployment | Bypasses tier-2 distributors to open direct OEM contracting for specialized textile weavers. |
| India PLI Corridor Manufacturing Footprint | Positions cost-engineered dashboard module production for export to volume Chinese EV brands. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from listed automotive component manufacturers. Bottom-up volume modeling triangulated against top-down market sizing from industry association aggregates.
Across the analysis window, forecasts segmented by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from historical trajectory analysis adjusted for platform-specific thermal management and weight reduction roadmaps. Model inputs incorporated REACH authorization timelines, SAMR GB standard implementation phases, and EV battery-pack thermal management specifications.
The analysis sits within stated boundaries; outcomes outside sustained EV adoption rates, stable petrochemical feedstock pricing, or aligned regulatory enforcement across jurisdictions would require recalibration. Forecasts reflect documented assumptions around qualification timeline compression and tier-1 supplier consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market