
 Automotive Load Floors Market | 2026-2036
Automotive Load Floors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Load Floors Market Analytics
Modular load floor configurations is expanding across OEM sourcing strategies as buyers seek configurable cargo systems that adapt to hybrid, electric, and internal combustion platforms. Toyota Boshoku Corporation leverages its interior systems integration expertise to anchor multi-material floor assemblies for Japanese and North American automakers. Magna International Inc. competes through manufacturing scale across its North American and European plant network, sustaining cost positions in aluminum-intensive designs.
Automotive load floors are structural panels installed in vehicle cargo compartments, typically engineered from honeycomb cores, reinforced thermoplastics, or metal-skinned composites with specified load-bearing capacities ranging from 100 to 500 kilograms, designed to protect underlying components while enabling flexible storage configurations. Plastic and aluminum product types lead volume due to weight-reduction mandates, while wood-composite variants occupy niche positions in premium acoustic applications. Passenger vehicles and SUVs dominate application demand, though electric vehicle platforms represent the fastest-growing structural segment as battery placement below the floor plane redefines packaging constraints and load distribution requirements.
The EPA's fuel economy standards and NHTSA's crashworthiness regulations in the United States compel manufacturers to validate load floor performance under dynamic collision scenarios, while Europe's REACH framework restricts certain flame-retardant chemistries in interior substrates. China's GB standards for automotive interior materials and MIIT's new energy vehicle technical guidelines further fragment compliance requirements across supply chains. Stakeholders must monitor how divergent regional material restrictions and recyclability mandates reshape supplier qualification criteria and raw material sourcing flexibility.
Market Dynamics
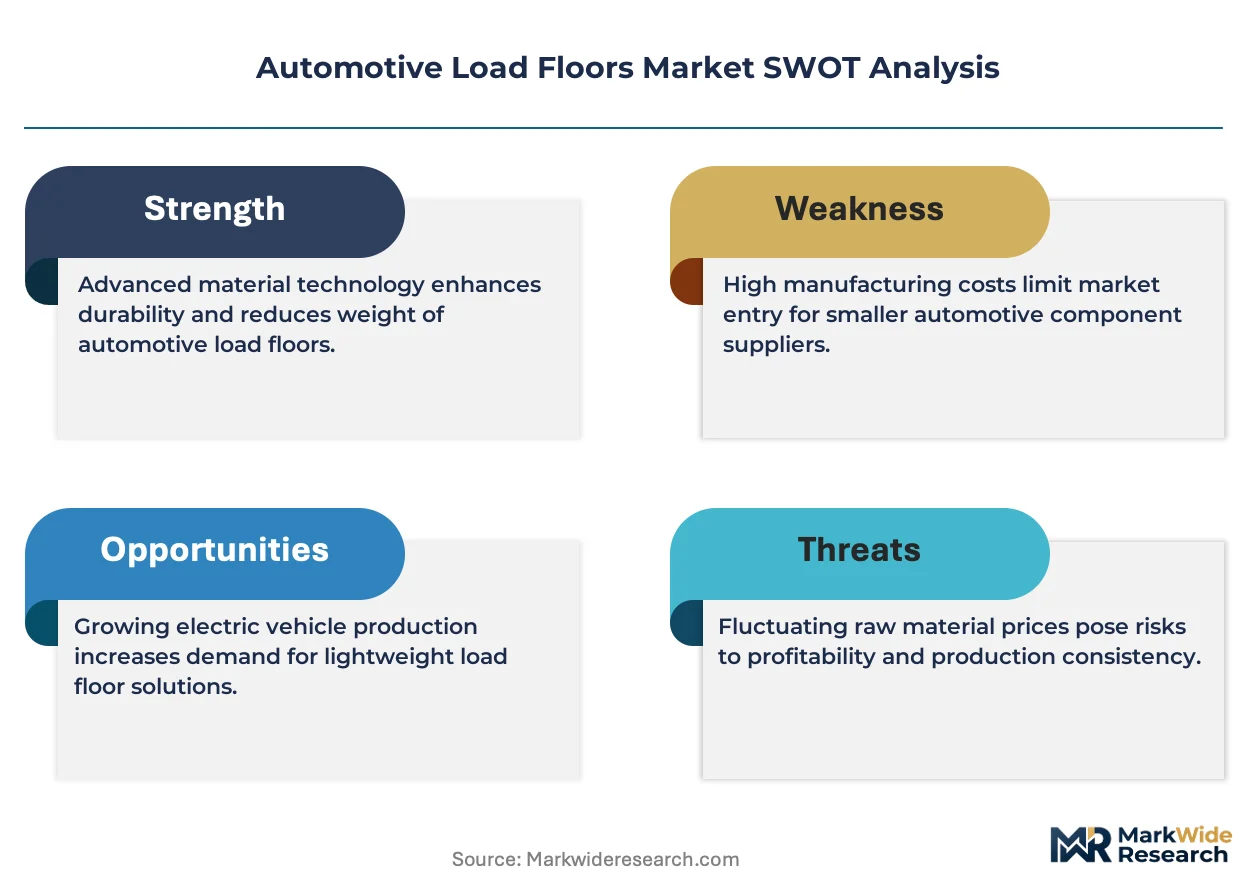
Electric vehicle platform architecture is compressing traditional load floor specifications as battery pack integration beneath cargo compartments forces redesigns of structural panels, load distribution pathways, and thermal management interfaces.
Growth Catalysts
- Lightweighting mandates:EPA fuel economy standards in the United States compel OEMs to adopt honeycomb-core composites and aluminum-intensive designs that reduce vehicle mass without sacrificing structural integrity.
- Europe's ECE R14 regulation:Seat anchorage and load retention requirements in the European Union drive demand for reinforced thermoplastic assemblies that withstand dynamic collision forces.
- EV platform proliferation:Battery placement below floor planes in electric SUVs and crossovers creates specialized demand for load-bearing panels with integrated thermal barriers and electromagnetic shielding properties.
Market Restraints
- Aluminum price volatility:Primary aluminum input costs fluctuate with energy-intensive smelting economics, compressing margin predictability for metal-skinned composite manufacturers.
- REACH chemical restrictions:Europe's framework on flame-retardant chemistries limits substrate formulation flexibility, forcing reformulation cycles that extend supplier qualification timelines.
- Glass fiber supply concentration:Reinforcement material production clusters in China create geographic dependency risks for composite core manufacturers serving Western OEMs.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive materials attract capacity expansion for thermoplastic honeycomb manufacturing serving domestic EV programs.
- Recyclability mandates:The EU Green Deal's circular economy requirements favor mono-material floor designs that simplify end-of-life disassembly and material recovery.
- Autonomous vehicle cargo modules:Self-driving shuttle and robotaxi platforms require reconfigurable interior panels with embedded sensor mounting points and modular seating attachment systems.
Industry Challenges
- Multi-material bonding expertise:Assembly of aluminum skins to thermoplastic cores demands specialized adhesive process control and thermal expansion management that outpaces current workforce training pipelines.
- Crash certification timelines:NHTSA dynamic testing protocols for interior structural components require 18-24 month validation cycles that delay platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Load Floors Market |
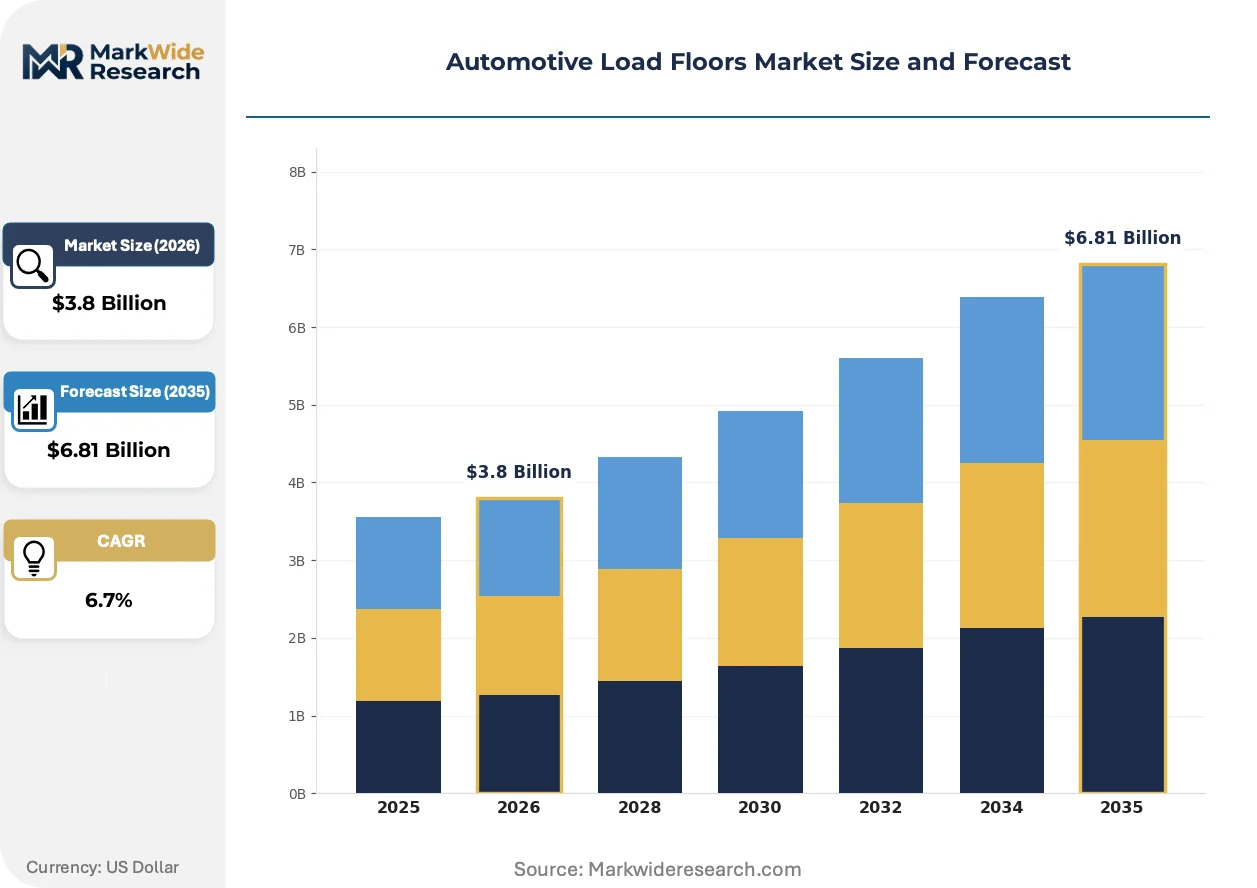
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Wood, Aluminum, Steel Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, SUVs End User: Manufacturers, Aftermarket Suppliers, Retailers, Tier-1 Suppliers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Daikyo Nishikawa Corporation, Magna International Inc., IAC Group, Lear Corporation, Faurecia, Toyota Boshoku Corporation, Grupo Antolin, Motus Integrated Technologies, Trèves Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Load Floors Market Evolving Landscape
Material science convergence with digital manufacturing is compressing development cycles for load-bearing interior panels while regulatory pressure on recyclability forces substrate redesign.
Continuous fiber-reinforced thermoplastic (CFRTP) composites are expanding into structural load floor applications as BMW and Mercedes-Benz integrate these materials into premium SUV platforms. The technology enables snap-fit assembly without mechanical fasteners, reducing manufacturing complexity. CFRTP is expanding into mid-volume production lines previously dominated by stamped aluminum, creating cost parity at lower production scales.
REACH restrictions on halogenated flame retardants are forcing substrate suppliers toward phosphorus-based and mineral-fill alternatives that meet ECE R14 fire safety standards. The regulatory shift elevates material costs by 8-15 percent but opens qualification pathways for European suppliers with advanced compounding capabilities. German OEMs are responding with design-for-recycling specifications that specify separable material layers.
Fleet operators and mobility service providers now specify modular cargo systems with standardized attachment interfaces across vehicle generations. This procurement pattern displaces custom-tooled floor designs in favor of platform-agnostic subassemblies that reduce spare parts complexity. The shift concentrates most visibly in North American commercial van segments where upfitters demand interchangeable load management accessories.
Automotive Load Floors Market Segmentation
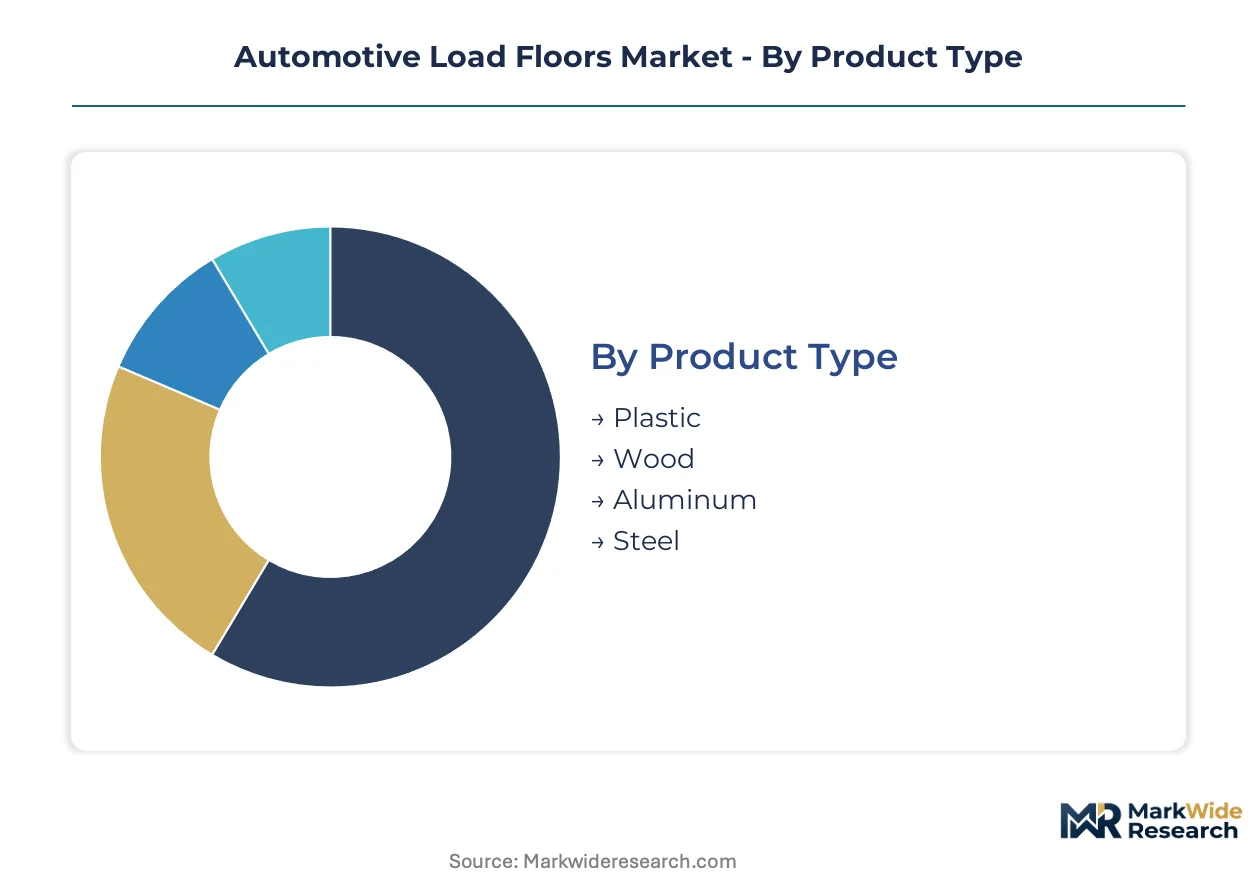
Automotive load floor procurement patterns diverge sharply across material specifications, vehicle architectures, and supply chain tiers. OEMs structure sourcing strategies around platform-specific weight targets and regional regulatory compliance, creating distinct demand pockets that reshape supplier qualification criteria.
Product Type:
Cost tier differentiation separates commodity substrates from engineered composites with specialized thermal or acoustic properties.
- Plastic:Honeycomb-core thermoplastic assemblies dominate mid-volume production through snap-fit manufacturing compatibility and corrosion resistance. Demand clusters in North American crossover platforms where Toyota and Honda specify polypropylene-based cores to meet CAFE efficiency targets without secondary surface treatments.
- Aluminum:Metal-skinned honeycomb panels deliver maximum stiffness-to-weight ratios for premium SUV load ratings exceeding 300 kilograms. German OEMs in Stuttgart and Munich anchor procurement volumes, though smelting energy costs in Norway and Iceland influence annual contract pricing volatility.
- Wood:Veneered composite substrates serve acoustic dampening requirements in luxury wagon segments with heritage cabin aesthetics.
- Steel:Stamped metal floors retain position in commercial van upfitting where repairability and impact tolerance outweigh mass penalties.
Volume sits with plastic; growth tilts toward aluminum.
Application:
Vehicle architecture complexity determines whether load floors must integrate thermal barriers, electromagnetic shielding, or modular attachment systems.
- Electric Vehicles:Battery placement beneath cargo compartments forces structural redesigns with integrated thermal management interfaces and electromagnetic interference shielding. Tesla's Austin and Berlin facilities specify CFRTP composites with embedded cooling channel compatibility, compressing traditional aluminum honeycomb adoption timelines.
- SUVs:Raised ride heights and flexible seating configurations demand higher dynamic load ratings with collapsible storage modularity. BMW's Spartanburg assembly plant sources multi-material assemblies combining aluminum reinforcement with thermoplastic acoustic layers for X-series platforms.
- Passenger Vehicles:Sedan and hatchback applications prioritize shallow-profile designs with minimal mass addition for compact cargo volumes.
- Commercial Vehicles:Fleet operators in last-mile delivery segments specify standardized floor interfaces across van generations to reduce upfitter tooling costs.
Volume sits with SUVs; growth tilts toward electric vehicles.
End User:
Supply chain position dictates whether buyers specify raw material grades, finished assemblies, or branded aftermarket accessories.
- Tier-1 Suppliers:Magna and Toyota Boshoku purchase substrate materials in master roll formats for in-house lamination and edge-finishing operations serving multiple OEM programs simultaneously.
- Manufacturers:OEM engineering teams source complete floor modules with integrated attachment hardware and surface finishing for direct assembly line sequencing.
- Aftermarket Suppliers:Independent distributors procure universal-fit panels with trim-to-install capability for collision repair and vehicle modification shops.
- Retailers:Consumer-facing channels stock cargo liners and protective mats with vehicle-specific fitment databases.
Volume sits with manufacturers; growth tilts toward Tier-1 suppliers.
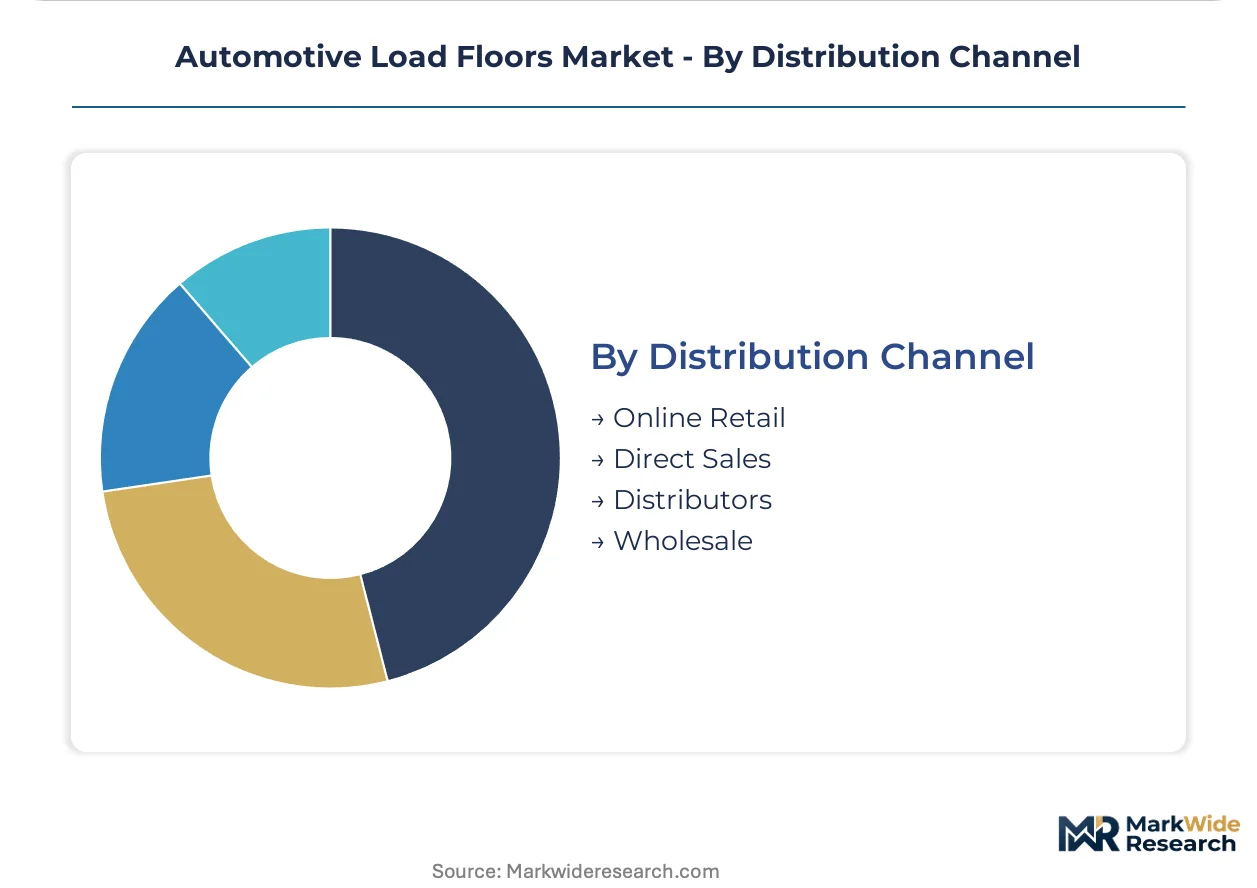
Distribution Channel:
Order scale and technical specification complexity determine whether transactions flow through intermediaries or direct procurement relationships.
- Direct Sales:High-volume OEM programs execute annual framework agreements with dedicated account engineering support and joint development protocols for platform-specific designs.
- Distributors:Regional logistics networks serve mid-tier suppliers with consolidated material sourcing and just-in-time delivery scheduling for variable production volumes.
- Online Retail:Digital catalog platforms capture aftermarket demand with VIN-based compatibility verification and drop-ship fulfillment for low-mix, high-SKU accessory lines.
- Wholesale:Bulk purchasing cooperatives aggregate demand from independent repair facilities and small fleet operators seeking volume pricing without direct mill relationships.
Volume sits with direct sales; growth tilts toward online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and Japan while consumption spreads across multiple vehicle manufacturing hubs. The United States and China absorb significant volumes through domestic assembly operations. Regulatory divergence across major markets forces suppliers to maintain parallel certification pathways.
Germany
Premium SUV manufacturing in Stuttgart and Munich drives demand for aluminum-intensive load floor assemblies with 300+ kilogram ratings. ECE R14 seat anchorage regulations enforce rigorous dynamic collision testing for all cargo compartment panels. The Baden-Württemberg cluster hosts specialized honeycomb core lamination facilities serving BMW and Mercedes-Benz platforms.
United States
EPA fuel economy standards compel adoption of lightweight thermoplastic designs across crossover and pickup truck segments. NHTSA crashworthiness protocols mandate 18-24 month validation cycles for interior structural components. Toyota's Georgetown assembly plant in Kentucky sources polypropylene-based floor systems for Highlander and Sienna production lines.
China
MIIT new energy vehicle technical guidelines reshape load floor specifications as battery placement beneath cargo compartments forces thermal management integration. GB standards for automotive interior materials establish flammability and emissions thresholds. The Yangtze River Delta manufacturing corridor around Shanghai hosts composite core production serving Tesla's Gigafactory and domestic EV brands.
Japan
Kei car and compact vehicle segments prioritize shallow-profile floor designs with minimal mass addition. METI carbon neutrality roadmaps accelerate material substitution toward recyclable mono-material substrates. Toyota Boshoku's headquarters region in Aichi Prefecture anchors development of multi-material bonding processes for hybrid platform compatibility.
India
PLI scheme production-linked incentives attract thermoplastic honeycomb manufacturing capacity for domestic EV programs. BIS automotive component standards establish quality benchmarks for local sourcing requirements. The Tamil Nadu automotive belt around Chennai hosts emerging Tier-1 suppliers targeting Maruti Suzuki and Hyundai Motor India assembly operations.
Automotive Load Floors Market Competitive Landscape
The competitive structure tilts toward diversified automotive suppliers with interior systems integration capabilities. Tier-1 conglomerates dominate high-volume OEM contracts through manufacturing scale across multi-continent plant networks. Three archetypes populate the vendor landscape: full-service interior integrators, specialized composite fabricators, and regional metal-forming specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players position for EV platform sourcing.
Within the full-service interior integrator tier, Magna International Inc. and Toyota Boshoku Corporation exemplify scale-driven positions spanning material sourcing through finished assembly. Daikyo Nishikawa Corporation occupies a specialist niche focused on acoustic and structural composite solutions. These three anchors represent divergent geographic footprints—Canadian, Japanese, and Japanese respectively—reflecting the industry's distributed production logic.
| Leading Market Players |
|---|
| Daikyo Nishikawa Corporation |
| Magna International Inc. |
| IAC Group |
| Lear Corporation |
| Faurecia |
| Toyota Boshoku Corporation |
| Grupo Antolin |
| Motus Integrated Technologies |
| Trèves Group |
| Others |
Value Network & Pricing Analysis
Tier 1 interior integrators command contract-based long-term offtake pricing that compresses margin visibility for raw material suppliers. Three-tier pricing structure across premium aluminum-honeycomb, standard thermoplastic-core, and economy steel-stamped configurations stratifies procurement volumes across OEM platform tiers.
Pricing Analysis
Margin tightening in aluminum-intensive assemblies reflects energy-intensive smelting economics and Norwegian power contract volatility. Cost-down pressure on polypropylene honeycomb suppliers accelerates because Toyota and Honda consolidate crossover platform sourcing under master supply agreements. Price differentiation traces to ECE R14 certification grade and volume scale, with aftermarket channels exhibiting highest price sensitivity versus captive OEM supply chains.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit anchor hub-and-spoke patterns serving just-in-sequence assembly plants. Geographic supply concentration centers on Germany for aluminum honeycomb lamination, China for glass fiber reinforcement, and Japan for multi-material bonding adhesives. Raw material dependencies rest on primary aluminum ingots, polypropylene resin, and continuous glass fiber rovings. Single-source vulnerability in Chinese glass fiber production creates geographic concentration risk. Distribution runs through direct mill relationships for Tier 1 suppliers and consolidated distributors for mid-tier fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Load Floors Market functions as a cost-of-compliance story where REACH chemical restrictions and ECE R14 dynamic testing protocols erect qualification barriers that favor incumbent suppliers with established certification pathways.
For Market Incumbents: Lock in multi-year platform contracts with BMW and Mercedes-Benz before CFRTP composites achieve cost parity at scale. Deepen backward integration into honeycomb core manufacturing to defend margin position against aluminum price volatility. Prioritize mono-material thermoplastic designs that align with EU Green Deal recyclability mandates.
For New Entrants and Emerging Players: Begin with India's PLI scheme production-linked incentive corridors serving Maruti Suzuki and Hyundai Motor India EV programs. Target thermoplastic honeycomb capacity for domestic sourcing requirements where ECE R14 certification timelines have deterred European competitors. Pursue joint development agreements with emerging EV platforms lacking established interior supply relationships.
For Investors and Strategic Acquirers: The window for entry favors specialized composite fabricators with ECE R14 validated testing protocols and multi-material bonding process expertise. Long-term viability hinges on qualification timelines that extend 18-24 months under NHTSA protocols, creating sticky supplier relationships. Monitor CFRTP adoption curves at Tesla's Austin and Berlin facilities as inflection signals for aluminum displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Magna and Toyota Boshoku reduce tooling costs across hybrid, electric, and ICE architectures. |
| Battery Supply Agreement | CFRTP suppliers secure thermal management interface specifications with Tesla and BYD platforms. |
| Geographic Manufacturing Footprint | Tamil Nadu belt expansion captures PLI incentives for domestic EV component sourcing. |
| Software-Defined Vehicle Investment | Embedded sensor mounting points in autonomous shuttle cargo modules create new content opportunities. |
| Charging Infrastructure Partnership | Load floor thermal barrier integration aligns with battery fast-charging heat dissipation requirements. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, and aftermarket distributor operations underwrites the qualitative findings. Primary fieldwork engaged vehicle interior systems executives, composite material R&D directors, and automotive regulatory compliance officers. Secondary validation drew from EPA fuel economy filings, ECE R14 test protocol documentation, MIIT new energy vehicle technical guidelines, and IHS Markit vehicle production databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand indicators.
Rate-of-change decomposition across vehicle class, propulsion architecture, and material specification dimensions enabled volume and value projections. The analytical framework modeled content per vehicle shifts as battery placement beneath cargo compartments redefined load floor structural requirements. CAGRs were derived from platform launch schedules and regional regulatory compliance timelines. Industry-specific forecast inputs included aluminum smelting energy cost trajectories and CFRTP manufacturing scale-up curves.
Underlying measurement precision varies by segment; electric vehicle and aluminum product type projections carry tighter precision than wood-composite niche applications. Forecasts reflect documented assumptions regarding platform standardization rates and regulatory harmonization timelines. Supply chain disruption risks, raw material price volatility, and certification protocol revisions could materially revise trajectory outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Low-Noise Anti-Squeak Additives for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market