
 Heavy-Duty Truck Fleet Control Unit Architectures Market | 2026-2036
Heavy-Duty Truck Fleet Control Unit Architectures Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Truck Fleet Control Unit Architectures Market Insights
The EU Green Deal's transport decarbonization targets is broadening the addressable market for advanced control architectures across European heavy-duty fleets. Daimler Truck leverages its integrated powertrain expertise to develop proprietary centralized control platforms for Mercedes-Benz Actros models. Volvo Group anchors its competitive position through sustained investment in hierarchical architectures that unify propulsion, braking, and telematics subsystems.
Heavy-duty truck fleet control unit architectures comprise embedded electronic systems that coordinate powertrain, chassis, and body electronics through deterministic real-time communication buses operating at data rates from 125 kbps to 100 Mbps. These architectures execute load balancing, predictive maintenance algorithms, and regulatory compliance logging across heterogeneous vehicle subsystems. Distributed control configurations currently dominate installed bases due to legacy compatibility and fault isolation advantages, while Ethernet-based centralized architectures represent the fastest-growing segment as fleet operators demand unified data pipelines for over-the-air updates and AI-driven route optimization. Modular control frameworks are capturing margin pools in retrofit applications where logistics providers seek incremental upgrades without full platform replacement.
The EPA's Phase 3 standards and California Air Resources Board mandates are forcing North American OEMs to embed emissions monitoring and reporting capabilities directly into control unit firmware. EMA's MDR traceability requirements and ISO 26262 functional safety classifications shape product development roadmaps and supplier qualification criteria across European markets. Stakeholders must monitor regulatory divergence between jurisdictional safety and emissions frameworks when architecting control platforms intended for cross-border fleet deployment.
Market Dynamics
The central structural force reshaping heavy-duty truck fleet control unit architectures is the mandatory transition from distributed to centralized electronic architectures, driven by EPA Phase 3 greenhouse gas standards and the EU Green Deal's transport decarbonization mandates requiring unified powertrain coordination.
Growth Catalysts
- EPA Phase 3 Standards:North American OEMs must embed emissions monitoring and reporting capabilities directly into control unit firmware, forcing wholesale architecture upgrades across heavy-duty fleets.
- Ethernet Backbone Adoption:Fleet operators demand deterministic 100 Mbps data pipelines for over-the-air updates and AI-driven route optimization, accelerating migration from legacy CAN bus systems.
- German R&D Concentration:Daimler Truck and TRATON Group anchor major development investments in Stuttgart and Munich, creating supplier ecosystems for advanced centralized platforms.
Market Restraints
- Semiconductor Supply Concentration:Advanced SoCs for automotive Ethernet switches concentrate in Taiwanese foundries, exposing OEMs to single-source vulnerability and allocation constraints.
- ISO 26262 Certification Burden:ASIL-D functional safety classifications for braking and steering control units extend development cycles and lock out non-specialist suppliers.
- Legacy Fleet Inertia:Distributed architectures retain installed base dominance due to fault isolation advantages and mechanic familiarity, slowing centralized platform penetration in retrofit markets.
Strategic Opportunities
- Modular Retrofit Frameworks:Logistics providers seek incremental control unit upgrades without full platform replacement, creating margin pools for backward-compatible gateway modules.
- AI-Edge Convergence:Onboard inference engines merging with real-time deterministic buses enable predictive maintenance algorithms that reduce unplanned downtime for long-haul operators.
- EMA MDR Traceability:European medical-equipment-grade documentation requirements for safety-critical systems create qualification barriers that favor incumbent control unit suppliers with established audit trails.
Industry Challenges
- Embedded Cybersecurity Skill Scarcity:ISO/SAE 21434 compliance for automotive cybersecurity engineering outpaces available talent pools in Detroit, Stuttgart, and Nagoya.
- Heterogeneous Integration Complexity:Centralized architectures must coordinate legacy powertrain controllers with new battery management systems across incompatible communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Truck Fleet Control Unit Architectures Market |
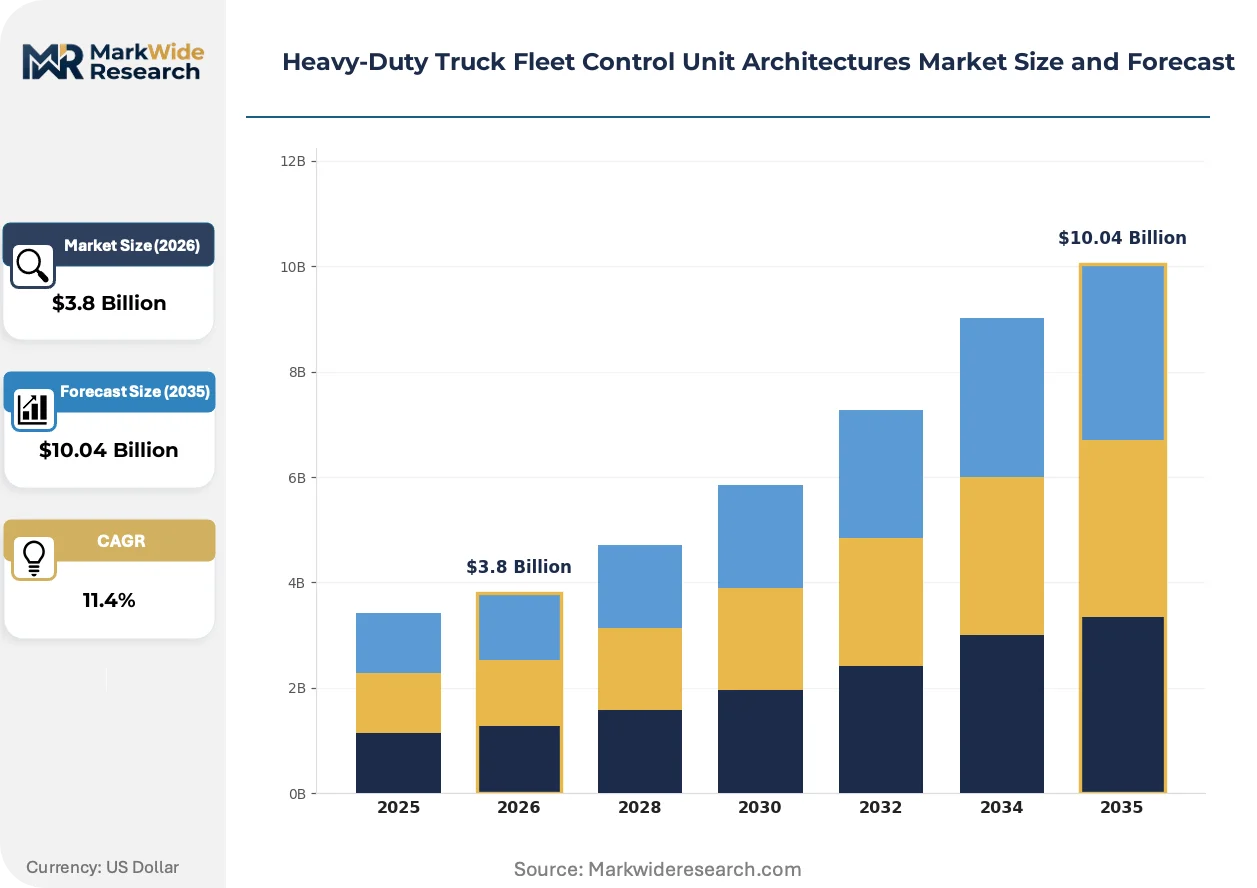
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Architecture Type: Distributed Control, Centralized Control, Hierarchical Control, Modular Control Communication Protocol: CAN Bus, LIN Bus, Ethernet, FlexRay, MOST End User: Long-Haul Operators, Logistics Providers, Freight Forwarders, Parcel Delivery Services Application: Fleet Management, Route Optimization, Fuel Efficiency Monitoring, Safety Compliance |
| Companies Covered | Daimler Truck, Volvo Group, PACCAR, TRATON Group, Scania, Robert Bosch, Continental, FAW Group, Ashok Leyland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Truck Fleet Control Unit Architectures Market Trends and Innovations
Deterministic Ethernet is displacing legacy fieldbus networks as the backbone for heavy-duty vehicle electronics, while regulatory mandates compress development timelines and fleet procurement models pivot toward lifecycle service contracts.
Time-Sensitive Networking over Ethernet is automating microsecond-precision coordination between powertrain, braking, and ADAS subsystems. Long-haul fleet operators in Germany and the United States are adopting TSN-enabled gateways at accelerating rates. This convergence is automating the elimination of redundant sensor networks and consolidating ECU counts from dozens to single-domain controllers.
EU Green Deal transport decarbonization targets are mandating embedded carbon accounting and energy consumption logging in control unit firmware. OEMs must now architect unified data pipelines that stream real-time emissions data to fleet management platforms. Heavy-duty segments operating across German-Dutch-Belgian corridors face the steepest compliance gradients and are prioritizing centralized architectures with over-the-air update capabilities.
Fleet procurement departments are consolidating vendor relationships around full-lifecycle service agreements that unbundle hardware from predictive maintenance subscriptions. Third-party telematics providers are losing ground to OEM-integrated control platforms. This consolidation is most visible among North American refrigerated transport operators demanding single-source accountability for uptime guarantees.
Heavy-Duty Truck Fleet Control Unit Architectures Market Segmentation
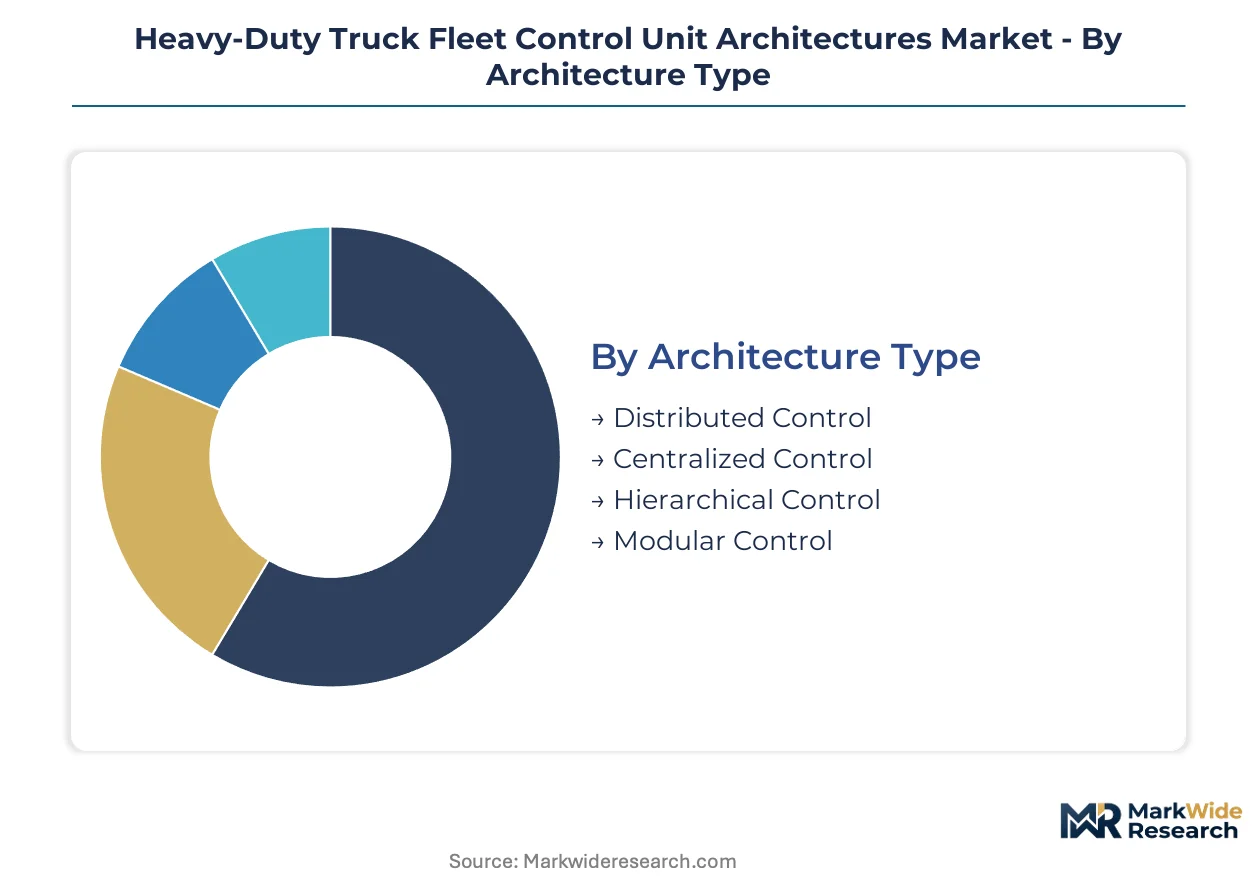
Control unit architectures fragment across four distinct configuration paradigms, each demanding specific supplier capabilities and integration approaches. Fleet procurement teams select architectures based on legacy fleet composition, regulatory jurisdiction, and total cost of ownership over vehicle lifecycle.
Architecture Type:
The customization-standardization spectrum runs from rigid proprietary platforms to adaptable modular frameworks, with fault tolerance and upgrade flexibility as opposing poles.
- Centralized Control:Single-domain controllers consolidate powertrain, braking, and telematics functions through Ethernet backbones operating at 100 Mbps. Long-haul operators in Germany prioritize these platforms for unified over-the-air update pipelines and AI-driven route optimization capabilities.
- Distributed Control:Legacy configurations isolate subsystems across dedicated ECUs linked by CAN bus networks at 125 kbps to 1 Mbps. Mechanic familiarity and fault isolation advantages sustain demand among North American refrigerated transport fleets with extended vehicle replacement cycles.
- Hierarchical Control:Tiered architectures segment vehicle functions across domain controllers with deterministic priority arbitration. Volvo Group anchors development investments in Gothenburg for unified propulsion-braking coordination.
- Modular Control:Gateway-based frameworks enable incremental retrofit without full platform replacement. Logistics providers in Dutch-Belgian corridors adopt these for phased compliance with EU Green Deal embedded carbon accounting mandates.
Leading the category by volume: Distributed Control. Growing fastest: Centralized Control.
Communication Protocol:
Data rate requirements and deterministic latency tolerances segment protocol selection across fleet operational profiles.
- Ethernet:Time-Sensitive Networking variants deliver microsecond-precision coordination for consolidated ECU architectures. EPA Phase 3 emissions monitoring mandates accelerate adoption among North American heavy-duty OEMs.
- CAN Bus:Controller Area Network protocols dominate legacy installed bases with proven reliability in electromagnetic-heavy chassis environments. Cost-sensitive retrofit applications in Eastern European markets sustain residual demand.
- FlexRay:Deterministic time-division multiple access supports safety-critical braking and steering subsystems requiring ASIL-D functional safety classifications.
- LIN Bus:Low-cost single-master-multiple-slave topology serves body electronics and door modules with modest bandwidth requirements.
- MOST:Media Oriented Systems Transport persists in premium cab infotainment networks despite Ethernet displacement pressure.
CAN Bus retains installed base dominance. Ethernet climbs the fastest with fleet digitization mandates.
End User:
Procurement sophistication and uptime penalty exposure differentiate customer segments across the value chain.
- Long-Haul Operators:Asset-heavy fleets with 500+ vehicle counts demand predictive maintenance integration and single-source lifecycle accountability. German autobahn corridor operators prioritize centralized architectures with embedded telematics.
- Logistics Providers:Third-party fulfillment networks require backward-compatible gateway modules for heterogeneous fleet consolidation. Modular retrofit frameworks capture margin pools in this segment.
- Freight Forwarders:Intermodal coordination demands drive investment in cross-border regulatory compliance logging capabilities.
- Parcel Delivery Services:Stop-and-go urban duty cycles prioritize regenerative braking optimization and last-mile route efficiency algorithms.
Long-Haul Operators anchor category revenue. Parcel Delivery Services expand most quickly with e-commerce fulfillment growth.
Application:
Functional use cases determine sensor fusion requirements and edge computing deployment intensity.
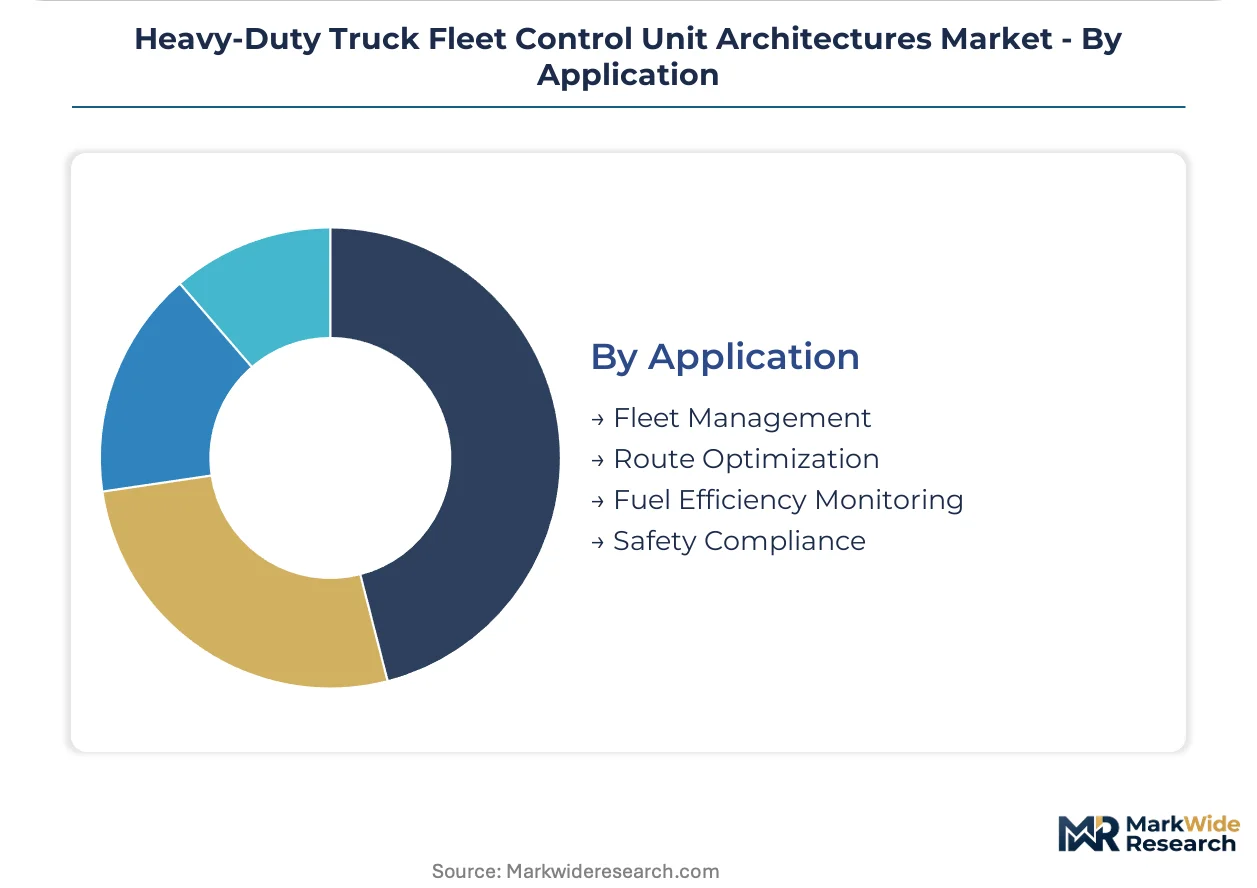
- Fleet Management:Real-time vehicle health monitoring and driver behavior analytics consolidate around OEM-integrated control platforms. Third-party telematics providers lose ground as procurement departments consolidate vendor relationships.
- Fuel Efficiency Monitoring:Embedded carbon accounting and energy consumption logging respond to EU Green Deal transport decarbonization targets. Firmware must stream emissions data to centralized fleet management platforms.
- Route Optimization:AI-edge convergence enables onboard inference engines merging with deterministic buses for dynamic rerouting.
- Safety Compliance:ISO 26262 ASIL-D classifications for braking and steering extend development cycles and lock out non-specialist suppliers.
Fleet Management commands the largest deployment base. Fuel Efficiency Monitoring gains share fastest with regulatory compliance compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Control unit architecture production concentrates in Germany and the United States while fleet consumption spreads across corridors linking industrial ports to inland distribution hubs. Manufacturing clusters align with OEM headquarters and tier-1 supplier ecosystems rather than end-use geographies.
United States
Long-haul operators across the I-80 and I-95 corridors drive demand for centralized platforms with over-the-air update capabilities. EPA Phase 3 standards mandate embedded emissions monitoring firmware, forcing architecture refreshes across Class 8 vehicle populations. Detroit anchors supplier development with concentrated R&D investments from domestic OEMs and tier-1 electronics houses.
Germany
Autobahn freight corridors connecting Rotterdam to Milan prioritize deterministic Ethernet backbones for unified fleet coordination. EU Green Deal transport decarbonization targets require embedded carbon accounting in control unit firmware. Stuttgart and Munich host development clusters where Daimler Truck and TRATON Group anchor proprietary platform investments.
China
Domestic heavy-duty fleet operators accelerate migration from distributed to hierarchical architectures for long-haul coal and container transport. MIIT new energy vehicle mandates push integration of battery management systems with legacy powertrain controllers. Shandong Province and the Yangtze River Delta concentrate manufacturing capacity for commercial vehicle electronics.
Japan
Precision logistics operators demand ASIL-D certified control units for automated braking coordination in dense urban delivery corridors. METI carbon neutrality roadmaps for transport sectors accelerate firmware investments in energy consumption logging. Nagoya and Tokyo metropolitan areas concentrate supplier engineering resources for hierarchical domain controller development.
India
Logistics providers serving Delhi-Mumbai and Chennai-Bengaluru corridors adopt modular retrofit frameworks for phased fleet upgrades. BIS automotive electronics standards and state-level electric mobility policies shape procurement specifications for control unit replacements. Tamil Nadu and Maharashtra host emerging assembly operations for gateway module production.
Heavy-Duty Truck Fleet Control Unit Architectures Market Competitive Landscape
The competitive structure tilts toward integrated OEM-tied suppliers with deep functional safety credentials. Tier-1 electronics houses and captive OEM development divisions split the addressable market, with semiconductor-dependent component specialists occupying narrower retrofit niches. Three archetypes dominate: proprietary platform developers, open-architecture modular suppliers, and safety-certification specialists. Consolidation through strategic technology licensing and backward integration into semiconductor sourcing represent the primary competitive vectors.
Among European-based OEM-integrated developers, Daimler Truck and Volvo Group occupy positions exemplifying proprietary centralized platform strategies, while TRATON Group represents the multi-brand architecture consolidation archetype. These entities anchor competitive dynamics through captive control over firmware development roadmaps and direct fleet service relationships.
| Leading Market Players |
|---|
| Daimler Truck |
| Volvo Group |
| PACCAR |
| TRATON Group |
| Scania |
| Robert Bosch |
| Continental |
| FAW Group |
| Ashok Leyland |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade silicon wafer spot indices cascading from Taiwanese foundries stratify control unit pricing across ASIL-D certified premium tiers and economy-grade legacy replacements. Fleet procurement departments absorb cost compression through volume commitments while retrofit logistics providers face margin erosion from spot-market component volatility.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for long-haul operators demanding predictive maintenance integration. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified domain controllers from modular gateway retrofits and legacy CAN bus replacements. Pricing pressure stems from semiconductor allocation constraints forcing OEMs toward captive silicon sourcing. Refrigerated transport fleets in North America exhibit highest price sensitivity due to extended replacement cycles, while German autobahn operators prioritize certification-grade premiums for unified fleet coordination.
Supply Chain Analysis
ISO 26262 ASIL-D qualification gates concentrate advanced SoC supply in Taiwan, South Korea, and Germany, locking out non-specialist component vendors. Raw material dependencies span automotive-grade silicon wafers, high-reliability capacitors, and Ethernet PHY transceivers. Single-source vulnerability in Taiwanese foundry capacity exposes OEMs to allocation rationing during demand spikes. Distribution runs through captive OEM supply chains and tier-1 electronics houses with direct fleet service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where backward integration into semiconductor sourcing separates viable platform developers from margin-compressed assemblers.
For Market Incumbents: Anchor proprietary firmware roadmaps through captive Ethernet switch development in Stuttgart and Detroit engineering clusters. Deepen ASIL-D certification moats to exclude modular retrofit competitors exploiting ISO 21434 compliance gaps. Defensive consolidation must neutralize emerging AI-edge inference specialists threatening predictive maintenance subscription revenues. For New Entrants and Emerging Players: Cloud-based fleet analytics portals offer the lowest customer-acquisition-cost route into logistics provider procurement committees. Target modular retrofit frameworks for Dutch-Belgian corridor operators facing phased EU Green Deal compliance deadlines. White-space penetration demands backward-compatible gateway modules priced below OEM captive alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor tier-2 electronics houses with dormant ASIL-D certifications in South Korea and Japan. Long-term viability hinges on semiconductor supply security across the projection horizon. Acquisition targets must demonstrate functional safety audit trails and established OEM qualification pathways. Watch for inflection when EPA Phase 3 enforcement accelerates North American architecture refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Sourcing | Taiwanese foundry allocation constraints force OEMs toward in-house wafer supply negotiations. |
| ASIL-D Certification Investment | Extended development cycles lock out non-specialist suppliers from braking and steering domains. |
| Time-Sensitive Networking Deployment | Microsecond-precision Ethernet backbones enable consolidated ECU architectures for German fleets. |
| Predictive Maintenance Platform Launch | AI-edge convergence reduces unplanned downtime through onboard inference engine integration. |
| Modular Retrofit Gateway Development | Backward-compatible frameworks capture logistics provider demand for phased compliance upgrades. |
Research Methodology
Independent corroboration across OEM platform engineering leads, tier-1 electronics procurement directors, and fleet operations managers underwrites the qualitative findings. Primary fieldwork with control unit firmware architects, semiconductor supply planners, and long-haul fleet maintenance heads combined with secondary validation from EPA regulatory filings, EU Green Deal implementation documents, and ISO 26262 certification registries. Bottom-up vehicle production estimates and top-down fleet digitization spending patterns triangulate market sizing across the analysis window.
Rate-of-change decomposition separates baseline fleet replacement cycles from regulatory-forced architecture upgrade waves across the projection horizon. Segmentation dimensions span architecture type, communication protocol, end-user procurement sophistication, and application functional intensity. CAGRs derive from fitted adoption curves for centralized versus distributed platform migration. Industry-specific inputs include EPA Phase 3 compliance timelines and EU embedded carbon accounting mandate rollouts.
The model holds under stable semiconductor allocation and regulatory enforcement schedules; deviation in foundry capacity expansion or jurisdictional safety standard divergence would shift fleet procurement priorities. Forecasts reflect documented assumptions regarding OEM R&D concentration and tier-1 supplier consolidation patterns. A model refresh is warranted upon material change in EPA enforcement intensity or Taiwanese foundry capacity utilization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market