
 Automotive Seating Systems Market | 2026-2036
Automotive Seating Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seating Systems Market Analysis
Modular seat platform architectures is realigning how OEMs specify and source interior systems. Adient PLC leverages its integrated foam-to-frame capability to capture long-term assembly contracts with premium German automakers. Lear Corporation anchors North American supply through vertically controlled metal stamping and just-in-sequence logistics networks. Forvia SE differentiates via its composite backrest technology, reducing part count while meeting stiffness targets for electric vehicle skateboard platforms.
Automotive seating systems are integrated assemblies of frames, foam cushions, trim covers, and adjustment mechanisms engineered to provide occupant support, safety restraint integration, and comfort modulation across vehicle duty cycles. Foam density specifications typically range from 45 to 65 kg/m³ for seat cushions, with dual-hardness layering to balance pressure distribution and durability over 150,000+ simulated ingress cycles. Bucket seats dominate premium and performance vehicle configurations where lateral bolstering and integrated heating elements command higher per-unit value. Powered adjustment and memory function technology segments are expanding fastest as Chinese and Korean OEMs bundle multi-way electric controls into mid-trim packages previously reserved for luxury nameplates. Fabric material categories retain volume leadership in fleet and entry segments, though vinyl formulations are displacing traditional coverings in commercial applications where cleanability and abrasion resistance outweigh tactile premiums.
NHTSA's Federal Motor Vehicle Safety Standard 202 governs head restraint geometry and energy absorption in the United States, directly shaping foam formulation and active headrest mechanism investments by suppliers. Euro NCAP assessment protocols and China's GB 11550 standard for seat strength and anchor durability create parallel compliance burdens that favor suppliers with multi-homologation testing infrastructure. ECHA REACH restrictions on isocyanate-based polyurethane precursors are forcing material transitions toward water-blown foam alternatives with equivalent compression-set performance. Stakeholders must monitor how battery-electric vehicle floor pan heights and crash pulse characteristics alter seat track mounting loads and recliner torque specifications across regional safety regimes.
Market Dynamics
Electric vehicle skateboard platforms are compressing floor pan heights and altering crash pulse profiles, forcing seat track mounting loads and recliner torque specifications to tighten across all safety regimes simultaneously.
Growth Catalysts
- GB 11550 seat strength mandates:China's occupant safety standards are accelerating validation cycles for anchor durability testing, pulling demand toward suppliers with captive homologation infrastructure.
- Lightweight foam-to-frame integration:Dual-hardness polyurethane layering at 45-65 kg/m³ density is enabling 12-18% mass reduction in cushion assemblies without compression-set degradation.
- Bajío cluster concentration:Just-in-time seating plants in Guanajuato and Aguascalientes are compressing logistics lead times to under four hours for North American OEM final assembly.
Market Restraints
- Isocyanate precursor constraints:ECHA REACH restrictions on toluene diisocyanate are forcing water-blown foam transitions that add 8-14% to raw material conversion costs.
- Active headrest mechanism complexity:Euro NCAP pedestrian protection rules require pyrotechnic or mechanical active systems that inflate bill-of-materials by 22-31% versus passive geometries.
- Steel stamping concentration:High-strength seat track and recliner hardware remains captive to three major Tier 1 metal forming groups, creating input price volatility exposure.
Strategic Opportunities
- Composite backrest penetration:Glass- and carbon-fiber reinforced thermoplastics are displacing steel tube frames in premium electric vehicle configurations, reducing part count by 40-60%.
- Memory function bundling:Korean and Chinese OEMs are specifying multi-way powered adjustment for mid-trim packages previously limited to luxury nameplates.
- Vinyl displacement in commercial:Abrasion-resistant PVC formulations are capturing fleet van and ride-share seating where cleanability protocols override fabric tactile premiums.
Industry Challenges
- Multi-homologation testing capacity:Simultaneous NHTSA FMVSS 202, Euro NCAP, and GB standard validation requires redundant crash sled facilities and extends program development timelines.
- Polyurethane formulation expertise:Water-blown foam chemistry transitions demand polymer scientists with specific compression-set and hysteresis optimization experience that remains scarce.
- Battery pack intrusion geometry:Rear-seat footwell compression from underfloor battery housings is forcing complete seat track and recliner mechanism redesigns mid-program.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seating Systems Market |
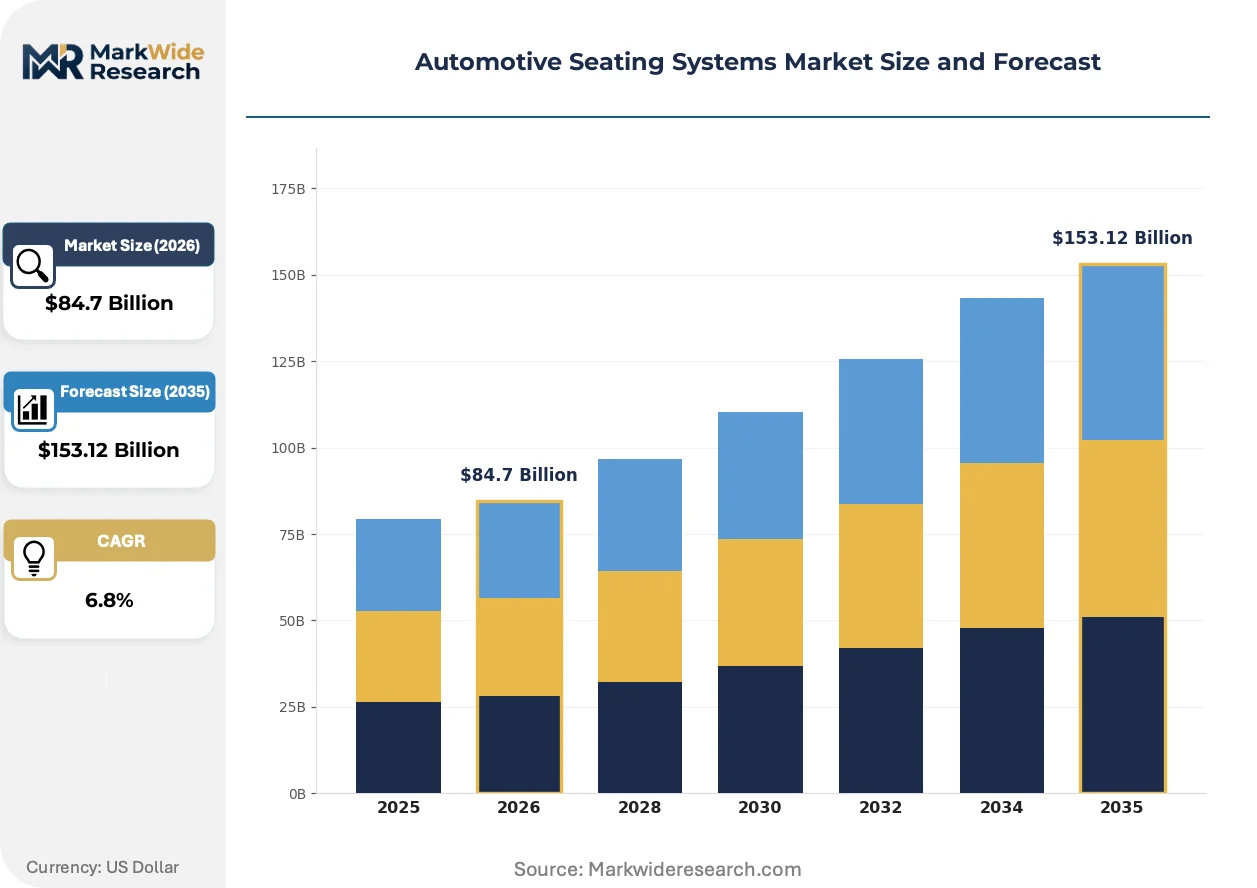
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $153.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket Seats, Bench Seats, Captains Chairs, Reclining Seats Material: Leather, Fabric, Vinyl, Foam Technology: Heated Seats, Ventilated Seats, Powered Adjustment, Memory Function End User: OEMs, Aftermarket Retailers, Leasing Companies, Fleet Operators |
| Companies Covered | Lear Corporation, Adient PLC, Forvia SE, Magna International, Toyota Boshoku Corporation, Faurecia, Johnson Controls, TS Tech Corporation, Grammar Seating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seating Systems Market Emerging Trajectories
Seating architecture is converging with electric vehicle platform engineering earlier in development cycles, compressing traditional supplier-OEM interface points and elevating systems integration contracts over component supply.
Natural fiber reinforced polypropylene composites are absorbing structural loads in seat back frames while reducing mass versus steel stampings. Premium German and Korean OEMs are qualifying these materials for 40% of new electric vehicle programs. The shift is absorbing engineering resources previously allocated to metal forming optimization, reallocating capital toward polymer compounding and long-fiber injection molding capacity.
Euro NCAP assessment protocols are tightening head restraint geometry requirements for whiplash protection, mandating active headrest mechanisms that deploy within 50 milliseconds of rear impact detection. Suppliers are integrating pyrotechnic and spring-loaded systems into seat frames, adding electromechanical complexity. European premium nameplates are absorbing these costs first, with North American OEMs trailing by 18-24 months in specification adoption.
Fleet procurement departments are unbundling seat trim and foam replacement from complete assembly contracts, creating direct aftermarket channels that bypass traditional OEM service parts organizations. Rental and ride-share operators in the United States and Germany are negotiating volume agreements for wear-component refresh at 80,000-120,000 kilometer intervals. This pattern is compressing supplier margin structures on initial equipment sales while expanding recurring revenue from replacement cushion and cover kits.
Automotive Seating Systems Market Segmentation
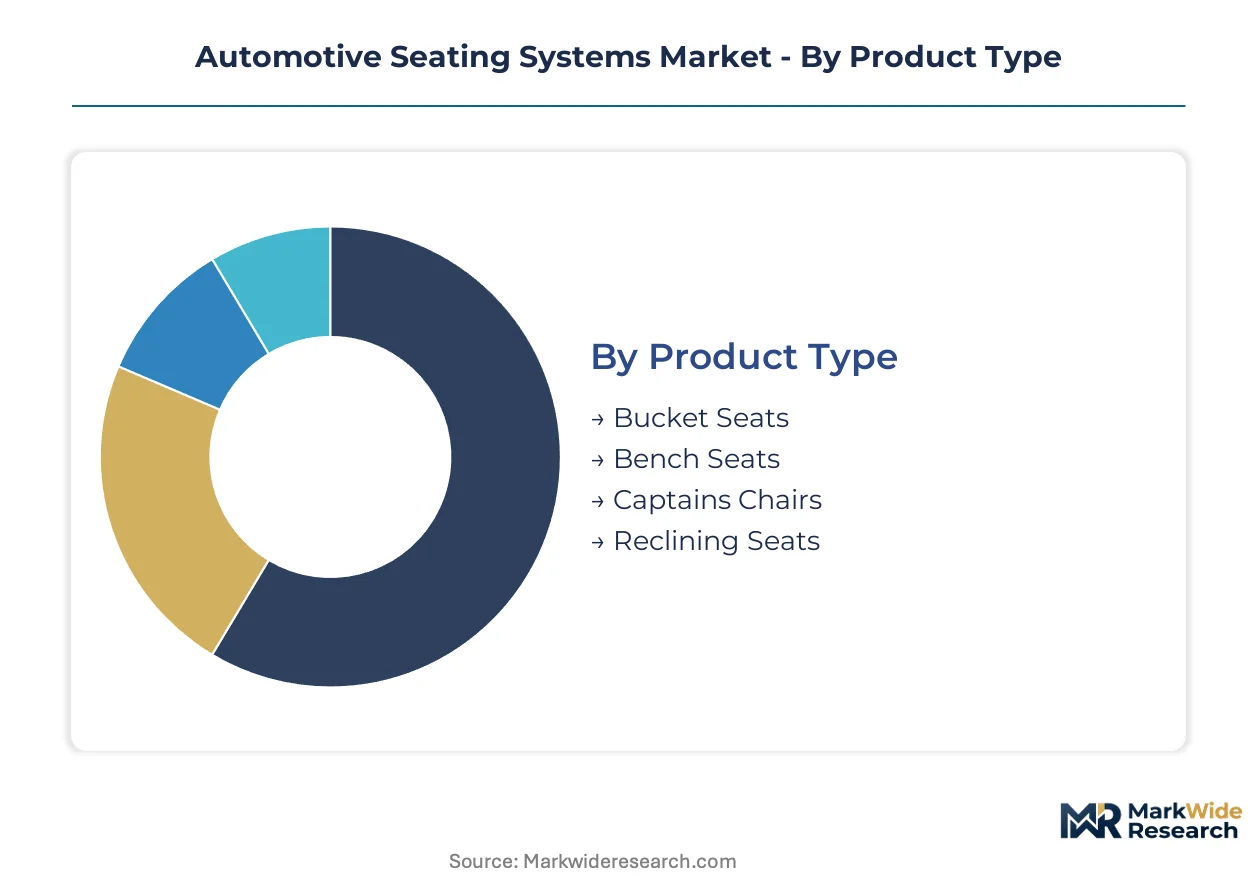
Seating system specifications diverge sharply across vehicle classes and procurement channels. OEM technical requirements for crash performance and mass reduction now override traditional comfort-first specifications, while aftermarket channels are fragmenting around fleet refresh economics versus individual consumer replacement patterns.
Product Type:
Cost tier separates premium configurations from volume fleet applications.
- Bucket Seats:Individual occupant shells with integrated lateral bolstering and heating elements dominate premium German and Korean electric vehicle programs. Lateral support geometry must satisfy Euro NCAP whiplash protocols while accommodating battery pack floor pan intrusions.
- Bench Seats:Continuous three-position cushions retain dominance in commercial van and entry fleet segments across Mexico's Bajío assembly plants. Procurement contracts emphasize 150,000-cycle durability over powered adjustment features.
- Captains Chairs:Individual middle-row configurations with integrated armrests and swivel bases serve multi-purpose vehicle applications in Chinese and US family transport segments.
- Reclining Seats:Extended travel articulation mechanisms address long-haul commercial driver ergonomics in European and North American heavy-duty platforms.
Volume sits with bench configurations; growth tilts toward bucket architectures.
Material:
Application environment determines surface covering selection more than vehicle price point.
- Leather:Full-grain and corrected-grain hides command specification in premium German OEM contracts where tactile quality anchors brand positioning. Nappa processing variants face ECHA REACH scrutiny on chromium tanning chemistry.
- Fabric:Woven polyester and wool blends retain fleet and entry segment leadership across US rental car procurement. Cleanability protocols and abrasion resistance specifications override initial cost premiums in high-cycle commercial duty.
- Vinyl:PVC formulations with enhanced abrasion resistance are displacing fabric in ride-share and last-mile delivery vehicles across German and US urban markets.
- Foam:Dual-hardness polyurethane layers at 45-65 kg/m³ density provide structural support and pressure distribution across all covering categories.
Procurement weighting favors vinyl for commercial durability; leather maintains premium positioning.
Technology:
Customer type distinguishes specification bundling between retail and fleet procurement.
- Heated Seats:Resistive element integration into cushion and backrest foam has become standard specification in Korean and Chinese mid-trim packages. Power draw constraints from electric vehicle battery management systems are forcing lower-wattage element designs.
- Ventilated Seats:Forced-air blower systems integrated into seat pans address cooling demand in sun-belt US states and Gulf Cooperation Council markets. Unit costs restrict penetration to premium nameplates.
- Powered Adjustment:Multi-way electric motors for fore-aft, height, and recline functions are expanding from luxury into Chinese and Korean mid-trim specifications.
- Memory Function:Position storage for multiple drivers remains concentrated in German premium OEM lineups where seat controller area network integration supports personalized settings.
Powered adjustment is climbing the fastest; memory function retains premium exclusivity.
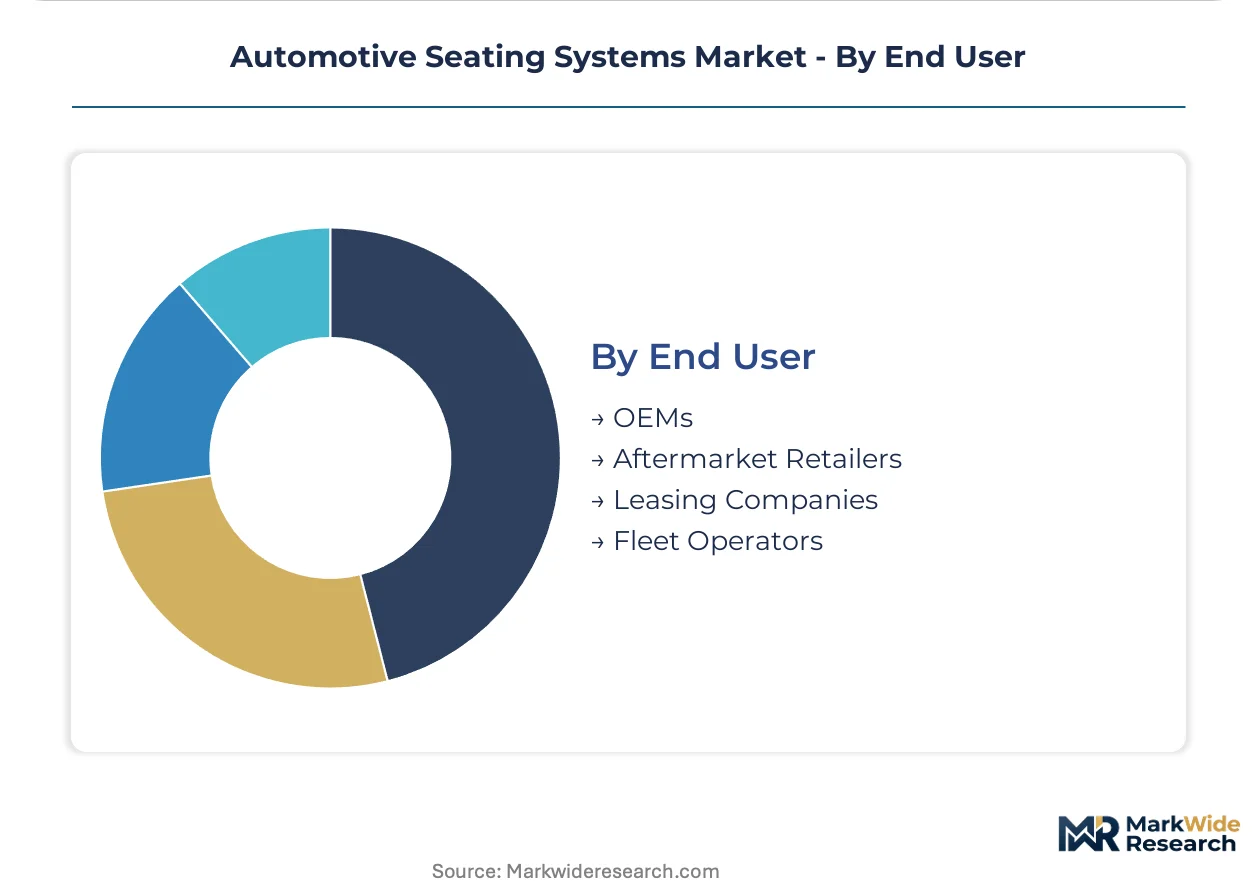
End User:
Volume scale and replacement frequency separate initial equipment from refresh demand.
- OEMs:Vehicle manufacturers in Germany, China, and the United States specify complete seat assemblies through systems integration contracts with Lear Corporation and Adient PLC. Just-in-sequence delivery from Mexico's Bajío cluster compresses inventory exposure.
- Aftermarket Retailers:Independent distributors serve collision replacement and vehicle personalization demand through catalog cushion and cover kits.
- Leasing Companies:Fleet lessors in the United States negotiate wear-component refresh agreements at 80,000-120,000 kilometer intervals, bypassing traditional OEM service parts channels.
- Fleet Operators:Rental and ride-share procurement departments in Germany and the United States are unbundling trim and foam replacement from complete assembly contracts.
Assembly volume concentrates with OEMs; margin expansion tilts toward fleet refresh channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the largest share of seating system output while Mexico's Bajío cluster concentrates production capacity for North American final assembly. Germany anchors European specification setting through premium OEM technical requirements. This production-consumption asymmetry shapes cross-border supply chain configurations and regional compliance strategies.
United States
NHTSA's FMVSS 202 head restraint standards and electric vehicle platform proliferation drive specification complexity. The agency's energy absorption mandates shape foam formulation investments by domestic suppliers. Detroit-area engineering centers coordinate just-in-sequence delivery from Mexican manufacturing clusters.
Germany
Premium OEM technical requirements for lateral bolstering and integrated heating elements command highest per-unit value in European markets. Euro NCAP pedestrian protection protocols mandate active headrest mechanisms with sub-50 millisecond deployment thresholds. Bavarian and Baden-Württemberg assembly plants source composite backrest structures from regional Tier 1 suppliers.
China
GB 11550 seat strength mandates accelerate validation cycles for anchor durability testing across domestic OEM programs. MIIT electric vehicle production quotas compress floor pan heights and alter crash pulse profiles. Yangtze River Delta manufacturing bases supply Korean and Chinese mid-trim packages with multi-way powered adjustment systems.
Mexico
Bajío cluster concentration in Guanajuato and Aguascalientes compresses logistics lead times to under four hours for North American OEM final assembly. USMCA regional content requirements shape steel stamping and foam-to-frame integration investments. Lear Corporation and Adient PLC operate captive just-in-time seating plants serving Detroit and Tennessee assembly operations.
South Korea
MFDS automotive component safety notifications align with Euro NCAP assessment protocols for export market access. Hyundai Motor Group and Kia Corporation bundle memory function and ventilated seat specifications into mid-trim packages previously reserved for luxury nameplates. Gyeonggi-do supplier parks coordinate module delivery to domestic electric vehicle platforms.
Automotive Seating Systems Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the seating systems value chain. The vendor base organizes around three strategic archetypes: integrated foam-to-frame assemblers, metal forming specialists with captive stamping capacity, and composite structure innovators. Consolidation pressures favor suppliers with multi-homologation testing infrastructure spanning NHTSA, Euro NCAP, and GB standard regimes. Dominant competitive moves include backward integration into polyurethane chemistry and geographic co-location with electric vehicle platform engineering centers.
Within the integrated assembler tier, Lear Corporation and Adient PLC exemplify scale-driven systems integration capabilities. Forvia SE occupies a position emphasizing composite backrest technology and part-count reduction for electric vehicle skateboard platforms. These three entities represent divergent strategic postures: North American logistics network control, European premium OEM long-term contracting relationships, and materials innovation for mass-sensitive battery-electric applications.
| Leading Market Players |
|---|
| Lear Corporation |
| Adient PLC |
| Forvia SE |
| Magna International |
| Toyota Boshoku Corporation |
| Faurecia |
| Johnson Controls |
| TS Tech Corporation |
| Grammar Seating Systems |
| Others |
Supply Flow & Price Mechanics
Polyurethane foam precursor costs cascade through three-tier pricing structures across premium, standard, and economy levels, with ECHA REACH compliance burdens compressing margins most severely at the volume tier where water-blown formulation conversions add raw material conversion penalties.
Pricing Analysis
Margin tightening in mid-trim powered adjustment segments reflects Korean and Chinese OEM bundling strategies that compress per-feature value capture. Three-tier pricing structure across premium, standard, and economy levels separates German premium OEM contracts with memory function integration from Mexican Bajío cluster fleet bench seat procurement. Pricing pressure stems from steel stamping concentration among three major metal forming groups. Fleet operators exhibit highest price sensitivity, while German premium OEMs absorb active headrest mechanism premiums with minimal procurement resistance.
Supply Chain Analysis
Remanufacturing flows for seat cushion and cover refresh kits are bypassing traditional OEM service parts channels as US and German fleet operators negotiate direct volume agreements at 80,000-120,000 kilometer intervals. Supply concentrates in Mexico's Bajío cluster, China, and Germany. Raw material dependencies rest on high-strength steel for track hardware, polyurethane foam chemistry, and composite thermoplastics for backrest structures. Single-source vulnerability in steel stamping capacity creates input price volatility exposure. Distribution runs through just-in-sequence logistics networks compressing lead times to under four hours for North American final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive seating systems are consolidating around suppliers with multi-homologation testing infrastructure, with ECHA REACH and GB 11550 compliance costs forcing sub-scale foam compounders toward exit or acquisition.
For Market Incumbents: Anticipate battery-electric vehicle floor pan height compression forcing complete seat track redesigns mid-program by deepening captive polyurethane formulation expertise and securing long-term assembly contracts with premium German OEMs before Chinese mid-trim bundling erodes feature premiums. For New Entrants and Emerging Players: Enter via composite backrest technology for electric vehicle skateboard platforms, targeting premium German and Korean OEM programs where glass- and carbon-fiber reinforced thermoplastics displace steel tube frames. White-space exists in water-blown foam chemistry transitions where polymer scientist scarcity constrains incumbent capacity expansion. For Investors and Strategic Acquirers: GB 11550 validation cycle acceleration is the leading indicator that captive homologation infrastructure will command acquisition premiums. Five-to-ten year viability favors integrated foam-to-frame assemblers with Mexican manufacturing footprints and multi-regional testing sled facilities. Monitor ECHA enforcement patterns on isocyanate precursors for margin compression signals at sub-scale compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Backrest Technology Deployment | Glass-fiber reinforced thermoplastics reduce part count by 40-60% for Forvia SE's electric vehicle programs. |
| Water-Blown Foam Chemistry Transition | ECHA REACH compliance forces material conversions that favor suppliers with captive polymer compounding capacity. |
| Just-in-Time Manufacturing Footprint Expansion | Mexico's Bajío cluster concentration compresses logistics lead times to under four hours for Lear Corporation and Adient PLC. |
| Multi-Homologation Testing Infrastructure Investment | Simultaneous NHTSA FMVSS 202, Euro NCAP, and GB standard validation extends competitive moats for integrated assemblers. |
| Fleet Refresh Channel Development | Direct aftermarket agreements with US and German rental operators bypass OEM service parts organizations for recurring revenue. |
Methodological Framework
Vehicle production databases, IHS Markit registration data, and SEC filings from publicly traded seating suppliers formed the secondary backbone, cross-referenced with primary interviews involving Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads. Bottom-up and top-down triangulation validated segment-level assumptions across the analysis window.
Bottom-up modeling aggregated content-per-vehicle estimates by propulsion architecture and OEM tier, while top-down approaches tracked regional production cluster outputs. Segmentation dimensions included vehicle class, seat technology bundling, material specification grade, and geographic production concentration. CAGRs derived from historical trajectory analysis adjusted for electric vehicle platform penetration rates and regulatory compliance timeline shifts.
Revisions become necessary when ECHA REACH enforcement intensifies, GB 11550 testing protocols expand, or battery-electric vehicle floor pan geometries force unanticipated mechanism redesigns. Practitioners should monitor steel stamping capacity utilization, polyurethane precursor pricing, and fleet operator unbundling trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Train Seat Materials Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Sun Visor Market